
 Middle East and Africa Bath and Shower Products Market | 2026-2036
Middle East and Africa Bath and Shower Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Bath and Shower Products Market Insights
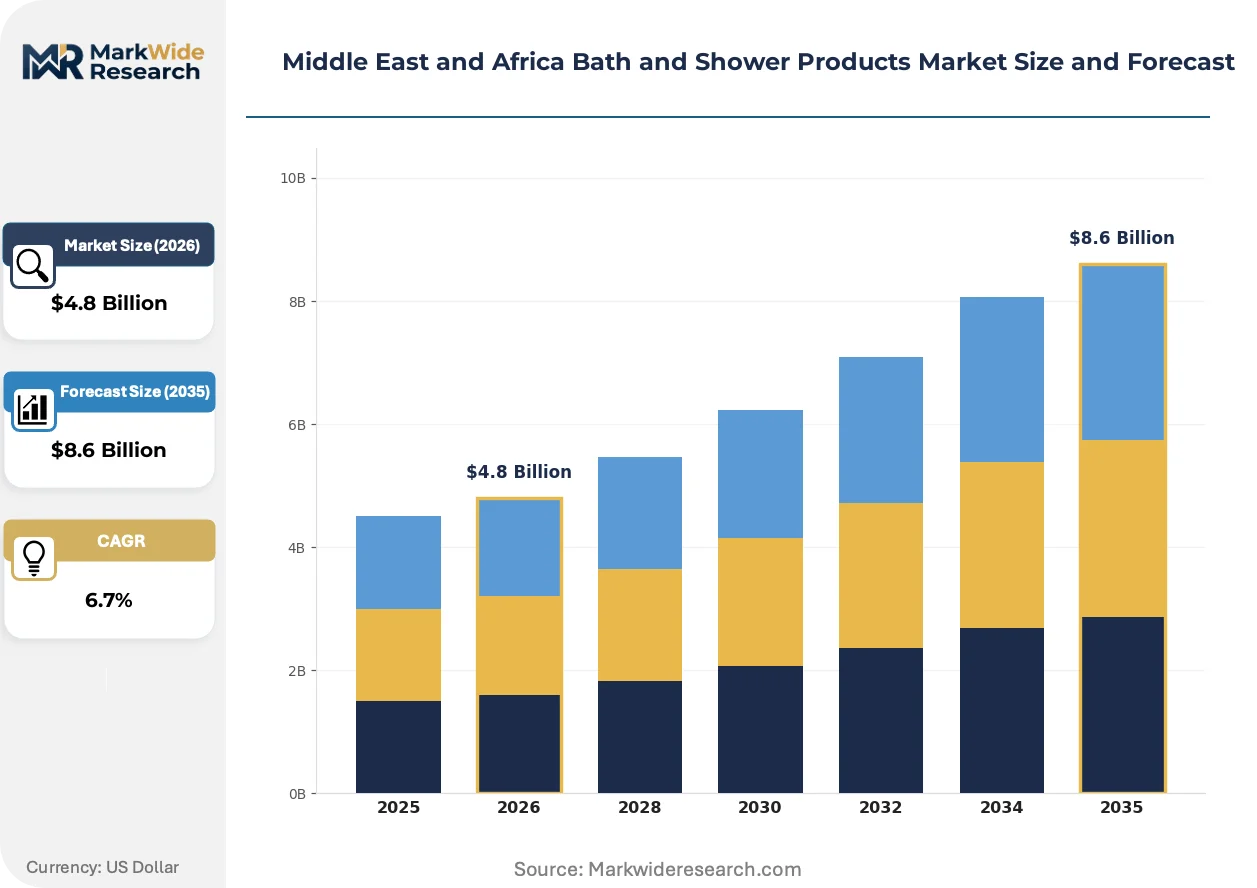
Asset-light distributor financing and third-party manufacturing leases is rewriting competitive entry dynamics across the Middle East and Africa Bath and Shower Products Market. Unilever PLC leverages its extensive regional distribution network to sustain shelf dominance in mass-market supermarkets. Beiersdorf AG anchors its position through specialized skincare formulations that differentiate Nivea-branded body wash in pharmacy channels. L'Oréal S.A. competes by extending premium brand equity from its European base into select Gulf retail environments.
Bath and shower products comprise surfactant-based cleansing formulations—typically containing sodium lauryl sulfate, cocamidopropyl betaine, or milder glucoside alternatives—delivered as liquids, gels, or solid bars for personal hygiene and skin conditioning. Manufacturing involves saponification or cold-process blending, with pH buffering between 5.5 and 7.0 to maintain skin barrier compatibility. Shower gel and body wash categories command the dominant volume share, though organic and herbal formulations within the formulation dimension are pulling fastest growth as ingredient transparency becomes a purchasing filter. Bar soap retains substantial mass-market penetration but occupies a compressing margin pool as consumers trade upward toward moisturizing and antibacterial liquid alternatives.
South Africa's National Regulator for Compulsory Specifications enforces mandatory labeling and safety standards for cosmetic products, while Saudi Arabia's Saudi Food and Drug Authority governs import registration and ingredient disclosure for bath and shower items entering Gulf markets. These frameworks elevate compliance costs for new entrants but simultaneously protect established players with regulatory infrastructure. Stakeholders must monitor formulation pre-approval timelines and evolving halal certification requirements as decisive variables for market access speed across the region.
Market Dynamics
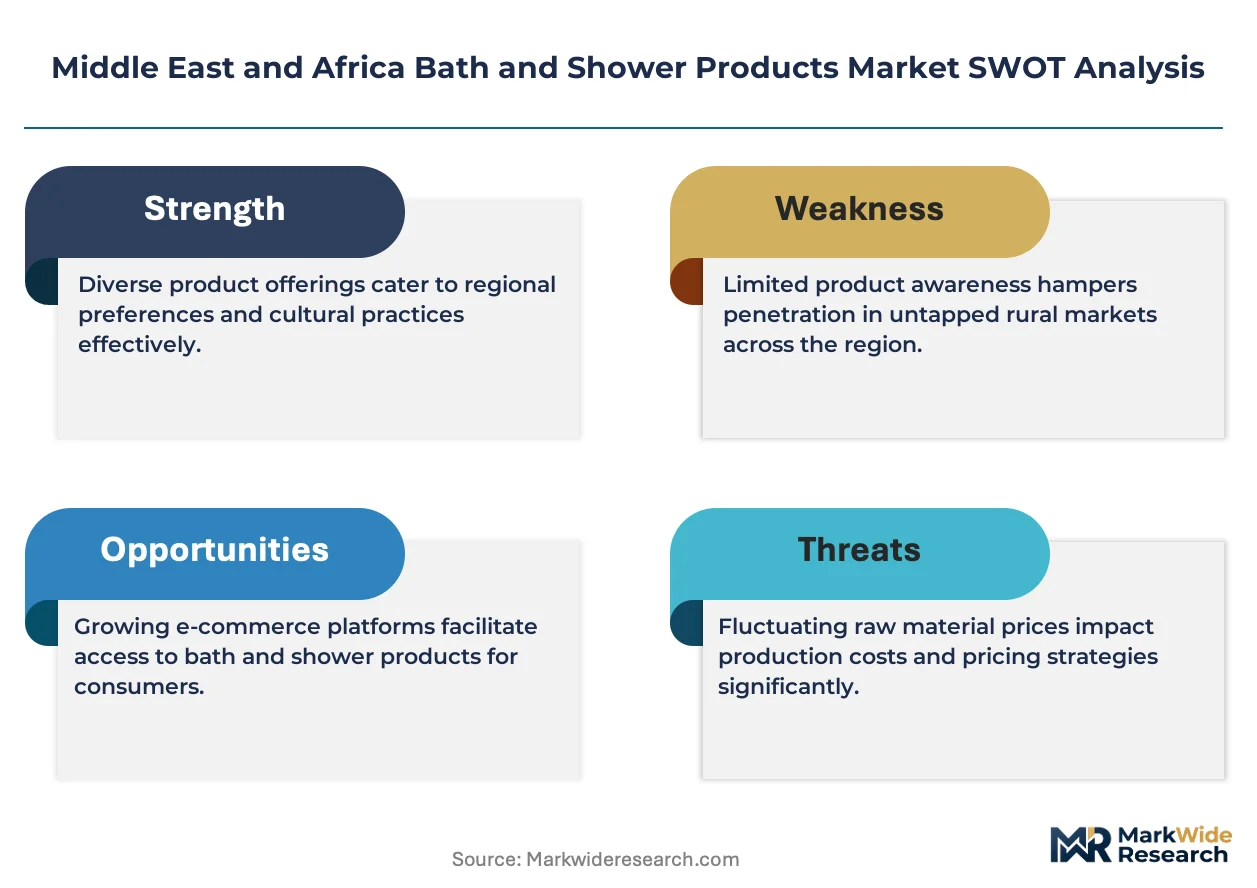
The Middle East and Africa Bath and Shower Products Market is undergoing a structural recalibration as hospitality procurement standards in luxury hotels and resorts accelerate demand for premium amenity formats, while South Africa's National Regulator for Compulsory Specifications enforces reformulation mandates that compress legacy product lifecycles.
Growth Catalysts
- Halal certification expansion:Saudi Arabia's SFDA and UAE's MOHAP are streamlining halal approval pathways for bath and shower imports, accelerating market access for compliant formulations across Gulf retail channels.
- Hospitality amenity upgrading:Luxury hotel chains in Dubai and Riyadh are mandating premium liquid formats over bar soap in guest bathrooms, pulling volume toward branded body wash and shower gel categories.
- Urban retail modernization:Nigeria's Lagos and Abuja corridors are seeing supermarket and convenience store expansion that displaces traditional open-air soap markets with packaged branded alternatives.
Market Restraints
- Palm oil derivative volatility:Sodium lauryl sulfate and cocamidopropyl betaine feedstock costs fluctuate with Malaysian and Indonesian palm kernel oil export pricing, compressing formulation margins for regional manufacturers.
- Import dependency concentration:Gulf markets rely on concentrated European and Asian supply nodes for surfactant intermediates, exposing distributors to Red Sea shipping disruptions and extended lead times.
- Water scarcity formulation limits:Rinse-off product development faces technical constraints in water-stressed regions like the UAE and Saudi Arabia, where low-water cleansing formats remain underdeveloped.
Strategic Opportunities
- Ethiopia's underpenetrated urban corridors:Addis Ababa and secondary cities show minimal branded liquid soap penetration, presenting first-mover advantage for distribution infrastructure investment.
- Clean beauty regulatory tailwinds:South Africa's updated cosmetics labeling standards under NRCS are creating preference shifts toward ingredient-transparent formulations that command shelf positioning in pharmacy channels.
- E-commerce platform convergence:Jumia and Noon marketplace expansion is virtualizing traditional wholesale relationships, enabling direct-to-consumer trial sizes that bypass supermarket slotting fee barriers.
Industry Challenges
- Formulation chemist scarcity:pH buffering expertise for skin-barrier-compatible surfactant systems remains concentrated in South Africa and Egypt, limiting regional manufacturing scale-up.
- NRCS pre-approval timelines:South Africa's mandatory safety assessment procedures for new cosmetic introductions create 12-18 month certification cycles that delay product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Bath and Shower Products Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shower Gel, Body Wash, Bar Soap, Bath Salts End User: Households, Hotels, Spas, Fitness Centers Formulation: Organic, Antibacterial, Moisturizing, Herbal Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Beiersdorf AG, L'Occitane International SA, Procter & Gamble Company, Colgate-Palmolive Company, Henkel AG & Co. KGaA, Unilever PLC, Johnson & Johnson Consumer Health, Reckitt Benckiser Group, L'Oréal S.A., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Bath and Shower Products Market Trends and Innovations
Digital traceability systems and biotechnology-derived surfactants are converging to redefine product differentiation in Middle East and Africa bath and shower categories, while regulatory disclosure mandates accelerate ingredient transparency as a purchasing filter.
Biotechnology-derived alkyl polyglucosides from corn and coconut feedstocks are displacing petroleum-based sodium lauryl sulfate in premium formulations. Gulf hospitality buyers and South African pharmacy chains are adopting these milder surfactants at accelerated procurement cycles. The technology is virtualizing traditional chemical supply relationships, enabling manufacturers to bypass petrochemical distributor networks and contract directly with agricultural processors for feedstock security.
South Africa's National Regulator for Compulsory Specifications now mandates full ingredient disclosure on cosmetic labels including fragrance allergens and preservative concentrations. This regulatory compression forces reformulation of legacy products containing undisclosed formaldehyde-releasing preservatives. Mass-market bar soap and economy liquid soap segments face the steepest compliance costs, while premium body wash lines with pre-existing clean positioning capture displaced shelf space.
Buyer concentration in Nigeria's supermarket sector is consolidating procurement decisions into fewer retail headquarters, compressing supplier negotiation leverage. Traditional open-air market distributors are losing volume to formal retail chains in Lagos and Abuja that demand standardized packaging and batch traceability. This channel shift is most visible in body wash and shower gel categories where branded penetration now exceeds bar soap in urban Nigerian households.
Middle East and Africa Bath and Shower Products Market Segmentation
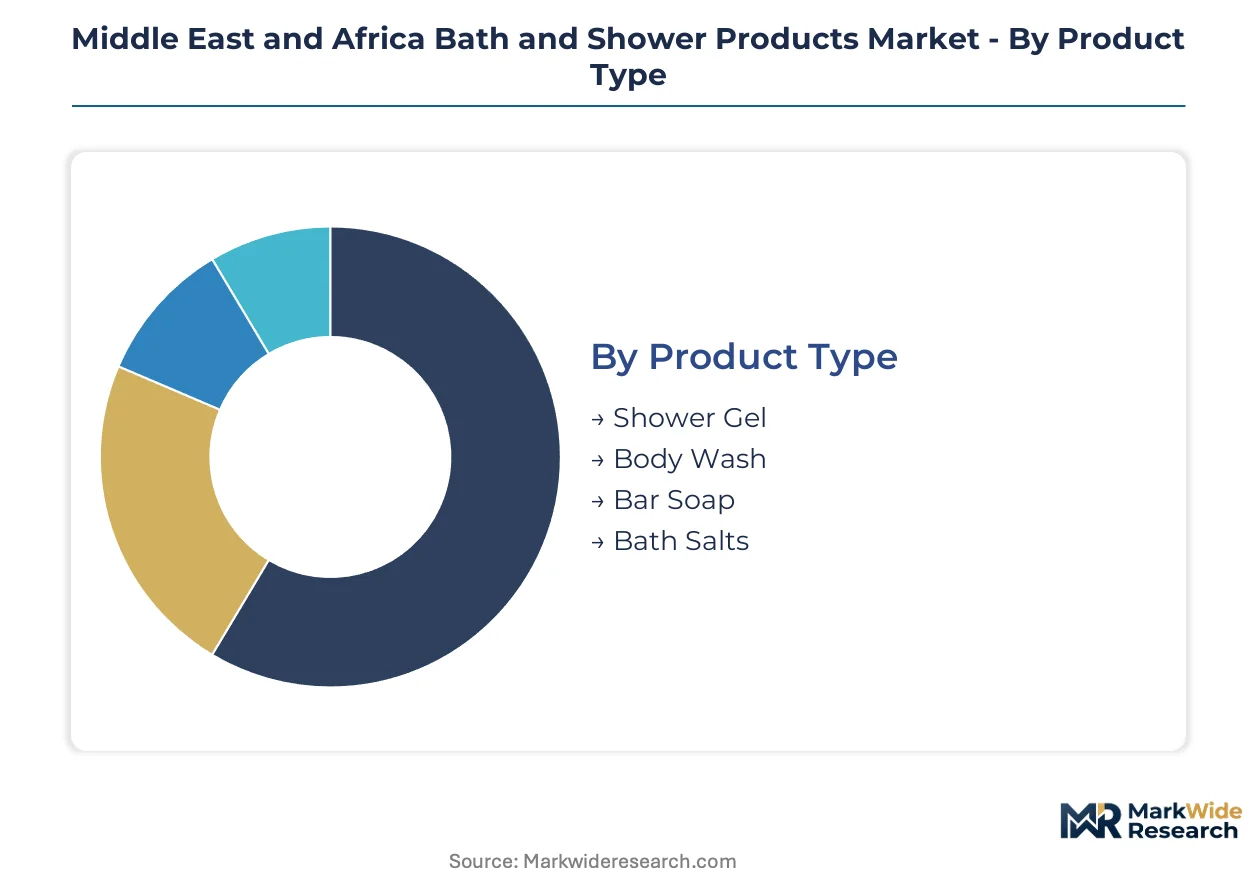
Segmentation in the Middle East and Africa Bath and Shower Products Market reveals how formulation chemistry, procurement channel, and end-use environment reshape competitive positioning. Each dimension carries distinct margin profiles and regulatory exposure that determine where manufacturers invest product development resources.
Product Type:
Volume concentration across liquid versus solid formats exposes divergent supply chain economics and hospitality procurement standards.
- Shower Gel:Viscous surfactant systems with pH-balanced formulations between 5.5 and 6.5 dominate amenity programs in Dubai and Riyadh luxury hotels. Hospitality procurement mandates are displacing bar soap in guest bathrooms, pulling branded gel volume through Gulf distribution networks.
- Body Wash:Thicker emulsion bases incorporating cocamidopropyl betaine and glycerin humectants target South African pharmacy channels. NRCS labeling compliance costs favor established players with reformulation infrastructure.
- Bar Soap:Saponified fatty acid bars retain mass-market penetration in Nigeria's open-air markets but face compressing margins as urban retail modernizes.
- Bath Salts:Mineral and essential oil compositions serve spa and wellness segments with limited scale outside South Africa's hospitality corridor.
Shower Gel commands the established base. The steepest expansion runs through Body Wash.
End User:
Customer environment dictates packaging specification, volume commitment, and certification burden across the value chain.
- Households:Individual consumption units purchasing through retail channels drive baseline demand for standard-format liquids and bar soap. Nigeria's Lagos and Abuja corridors show accelerating branded penetration as supermarket expansion displaces traditional market structures.
- Hotels:Bulk procurement of amenity-size formats with halal certification requirements governs Gulf hospitality supply. Procurement concentration into fewer luxury chain headquarters compresses supplier negotiation leverage.
- Spas:Premium positioning demands therapeutic ingredient claims and specialized packaging, limiting addressable scale.
- Fitness Centers:Post-workout cleansing formulations with antibacterial positioning serve institutional contracts with price-sensitive procurement.
Households anchor volume throughput. Hotels generate the fastest margin expansion.
Formulation:
Ingredient transparency and certification status now determine shelf positioning and pricing power across retail channels.
- Organic:Corn and coconut-derived alkyl polyglucosides replacing petroleum surfactants command premium placement in South African pharmacy chains. Agricultural feedstock contracting bypasses petrochemical distributor networks.
- Antibacterial:Triclosan-free alternatives using benzalkonium chloride or natural extracts face reformulation pressure under NRCS disclosure mandates.
- Moisturizing:Glycerin and shea butter enrichment targets dry-climate consumers in UAE and Saudi Arabia with functional positioning.
- Herbal:Indigenous plant extracts serve local preference segments with limited export scalability.
Moisturizing formulations hold the mass-market core. Organic lines are climbing the fastest.
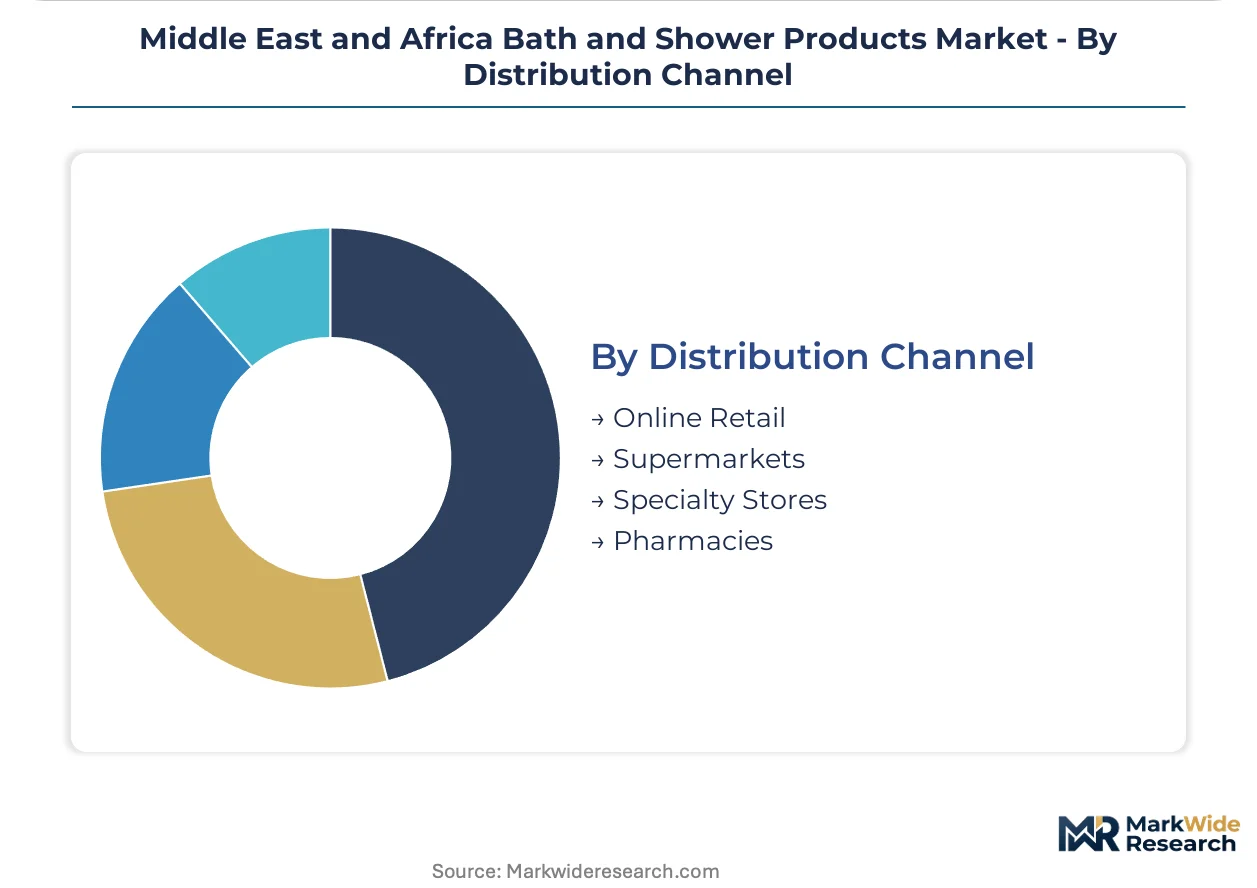
Distribution Channel:
Channel selection determines working capital intensity, traceability requirements, and consumer data access for manufacturers.
- Online Retail:Jumia and Noon marketplace infrastructure enables direct-to-consumer trial formats that bypass supermarket slotting fees. Virtualized wholesale relationships compress traditional distributor margins.
- Supermarkets:Buyer concentration in Nigeria's formal retail sector consolidates procurement decisions into fewer headquarters demanding standardized packaging and batch traceability.
- Specialty Stores:Curated assortments with service differentiation serve premium positioning but limit geographic reach.
- Pharmacies:South Africa's NRCS disclosure requirements concentrate compliant formulations in this channel with professional endorsement value.
Supermarkets maintain volume dominance. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency defines regional trade flows, with Gulf markets sourcing surfactant intermediates from European and Asian supply nodes while South Africa maintains stronger domestic formulation capabilities. Export competitiveness varies sharply across the region's manufacturing bases.
Saudi Arabia
Luxury hospitality procurement in Riyadh and Jeddah drives premium liquid format demand as hotel chains mandate branded amenity programs. The Saudi Food and Drug Authority governs halal certification pathways that accelerate compliant product registration. The Eastern Province's petrochemical infrastructure supplies feedstock for regional surfactant production.
United Arab Emirates
Dubai's retail and hospitality sectors concentrate purchasing power for imported premium formulations. The Ministry of Health and Prevention streamlines import registration for bath and shower items entering Gulf distribution networks. The Jebel Ali industrial zone hosts third-party manufacturing facilities serving regional re-export markets.
South Africa
Pharmacy channel expansion in Johannesburg and Cape Town pulls compliant formulations through professional endorsement networks. The National Regulator for Compulsory Specifications enforces mandatory labeling standards that compress legacy product lifecycles. The Gauteng province anchors domestic manufacturing with pH buffering expertise for skin-barrier-compatible systems.
Nigeria
Urban retail modernization in Lagos and Abuja corridors displaces traditional open-air soap markets with packaged branded alternatives. The country's national standards body oversees cosmetics safety assessments that create compliance barriers for new entrants. The Lekki Free Trade Zone attracts distribution infrastructure investment targeting West African consumer markets.
Egypt
Local manufacturing scale-up in Cairo and Alexandria serves price-sensitive mass-market segments with saponified bar soap production. The Egyptian Drug Authority regulates cosmetic product registration with pre-approval timelines that favor established players. The Suez Canal Economic Zone positions chemical processing facilities for regional export competitiveness.
Middle East and Africa Bath and Shower Products Market Competitive Landscape
On the supply side, the industry is consolidating around multinational consumer goods conglomerates with established regulatory infrastructure and distribution networks. Three strategic archetypes dominate: mass-market volume players leveraging supermarket shelf dominance, premium skincare specialists targeting pharmacy and hospitality channels, and agile private-label manufacturers serving retailer-owned brands. Competitive moves center on reformulation compliance investments and e-commerce platform partnerships that bypass traditional wholesale structures.
Among European-based consumer goods conglomerates, Unilever PLC and Beiersdorf AG exemplify divergent positioning archetypes. L'Oréal S.A. occupies a premium-tier position extending brand equity from its established European base into selective Gulf retail environments. These entities represent the spectrum of competitive approaches: mass-market penetration through distribution scale, specialized skincare formulation differentiation, and cross-regional brand leverage.
| Leading Market Players |
|---|
| Beiersdorf AG |
| L'Occitane International SA |
| Procter & Gamble Company |
| Colgate-Palmolive Company |
| Henkel AG & Co. KGaA |
| Unilever PLC |
| Johnson & Johnson Consumer Health |
| Reckitt Benckiser Group |
| L'Oréal S.A. |
| Others |
Pricing and Supply Chain Analysis
Red Sea shipping disruptions determine both pricing tier spreads and supply chain shape across Middle East and Africa bath and shower markets. Gulf distributors face compressed margins on European surfactant imports while South African manufacturers exploit domestic pH buffering expertise to capture pharmacy channel premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Middle East and Africa bath and shower procurement. Price differentiation separates halal-certified hospitality amenity formats from mass-market supermarket liquids and open-air market bar soap, with certification grade and volume scale as primary drivers. Pricing pressure stems from palm kernel oil feedstock volatility originating in Malaysian and Indonesian export markets. Mass-market bar soap segments exhibit highest price sensitivity, while luxury hotel procurement demonstrates lowest elasticity due to brand positioning requirements.
Supply Chain Analysis
Upstream surfactant intermediates draw from concentrated European and Asian supply nodes, with Germany, China, and India anchoring feedstock production for Gulf and African formulation facilities. Raw material dependencies center on sodium lauryl sulfate, cocamidopropyl betaine, and emerging alkyl polyglucoside alternatives from corn and coconut agricultural processors. Single-source vulnerability concentrates in Red Sea logistics corridors where shipping disruptions extend lead times for UAE and Saudi Arabian distributors. Distribution runs through third-party manufacturing leases and asset-light distributor financing that rewrites competitive entry dynamics across the region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in formulation compliance consulting and halal certification advisory are expanding faster than base product manufacturing across Middle East and Africa bath and shower markets. Recurring revenue from regulatory navigation support now exceeds hardware margins for specialized distributors serving hospitality and pharmacy channels.
For Market Incumbents: Harden regulatory infrastructure investments against South Africa's NRCS pre-approval timeline compression and emerging halal certification complexity in Gulf markets. Prioritize backward integration into agricultural feedstock contracting for alkyl polyglucoside surfactants to bypass petrochemical distributor networks. Consolidate pharmacy channel positioning through NRCS-compliant formulation portfolios that capture shelf space from legacy bar soap manufacturers facing disclosure mandate costs. For New Entrants and Emerging Players: Build out distribution infrastructure in Ethiopia's underpenetrated Addis Ababa and secondary city corridors where branded liquid soap penetration remains minimal. Target Nigeria's urban retail modernization as supermarkets displace traditional open-air markets with packaged alternatives. Pursue direct-to-consumer trial formats through Jumia and Noon marketplace partnerships that bypass supermarket slotting fee barriers and establish brand recognition before physical retail expansion. For Investors and Strategic Acquirers: South Africa's NRCS disclosure mandate reshapes the acquisition landscape by compressing legacy product lifecycles and elevating compliant formulation portfolios. Long-term viability centers on targets with established regulatory infrastructure and pH buffering expertise concentrated in Gauteng province manufacturing bases. Watch for halal certification pathway streamlining by Saudi Arabia's SFDA and UAE's MOHAP as inflection indicators for Gulf market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | SFDA and MOHAP pathway alignment accelerates product registration across Gulf retail channels. |
| Agricultural Feedstock Contracting | Corn and coconut-derived surfactant sourcing bypasses petroleum distributor margin layers. |
| Pharmacy Channel Expansion | NRCS-compliant formulations capture professional endorsement value in Johannesburg and Cape Town. |
| E-commerce Platform Integration | Jumia and Noon marketplace partnerships enable trial-size distribution without slotting fees. |
| Reformulation Infrastructure Buildout | pH buffering expertise investment defends against NRCS disclosure mandate compliance costs. |
Research Methodology
A standing panel of brand managers, category buyers at retailers, channel sales heads, and supply planners provided ongoing calibration across primary interview cycles. Secondary validation drew from customs and trade data, Nielsen retail audit records, SEC filings of listed consumer goods conglomerates, and hospitality procurement databases. Bottom-up volume modeling triangulated against top-down market sizing across product type, formulation chemistry, distribution channel, and end-user environment dimensions.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning liquid versus solid formats, organic versus conventional surfactant systems, and hospitality versus household procurement channels. CAGRs were derived from trend extrapolation of ingredient transparency preference shifts and urban retail modernization trajectories. Forecast inputs incorporated halal certification adoption curves and NRCS compliance cost trajectories specific to South African pharmacy channel dynamics.
Stress conditions across palm kernel oil price volatility, Red Sea logistics disruption duration, and NRCS pre-approval timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway streamlining and supermarket expansion velocity in Nigerian urban corridors. Cross-checking against hospitality procurement database benchmarks and customs import records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Hair Removal Wax Market
Beauty & Personal Care
Luxury Beauty Devices Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Spas and Beauty Salons Market
Beauty & Personal Care
South America E-Commerce Skin Care Products Market
Beauty & Personal Care
Hair Color Spray Market
Beauty & Personal Care
Cosmetic Palettes Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Delivery Systems in Personal Care Market
Beauty & Personal Care
Luxury Hair Care Market
Beauty & Personal Care
Colombia Hair Care Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
Beauty and Wellness Products Market