
 Makeup Egg Market | 2026-2036
Makeup Egg Market Size, Share, and Industry Trends Forecast 2026-2036
Makeup Egg Market Insights
The EU Green Deal is recalibrating material sourcing priorities across cosmetic applicator supply chains. Beautyblender leverages its Los Angeles manufacturing base to sustain premium positioning in domestic distribution. Real Techniques competes through Boots and Ulta channel control across the United Kingdom and North America. e.l.f. Cosmetics anchors volume-tier demand via mass retail partnerships and aggressive digital pricing.
Makeup eggs are porous or non-porous applicator tools, typically 2-4 centimeters in dimension, designed to deposit and blend cosmetic formulations across facial contours through controlled absorption and release. Blending sponge variants dominate unit economics due to recurring replacement cycles and consumer familiarity, while silicone sponge formats occupy a faster-growing niche driven by non-porous hygiene claims and reduced product waste. Foam materials lead production volumes though latex-free alternatives gain share amid dermatological sensitivity concerns.
The US FDA oversees cosmetic safety labeling while California's Proposition 65 imposes additional substance disclosure burdens on imported applicator materials. The EU REACH framework and ECHA substance restrictions directly govern chemical composition in foam and silicone inputs entering European retail channels. Stakeholders must monitor evolving state-level chemical bans and retailer-specific clean-beauty certification programs to preserve market access across priority geographies.
Market Dynamics
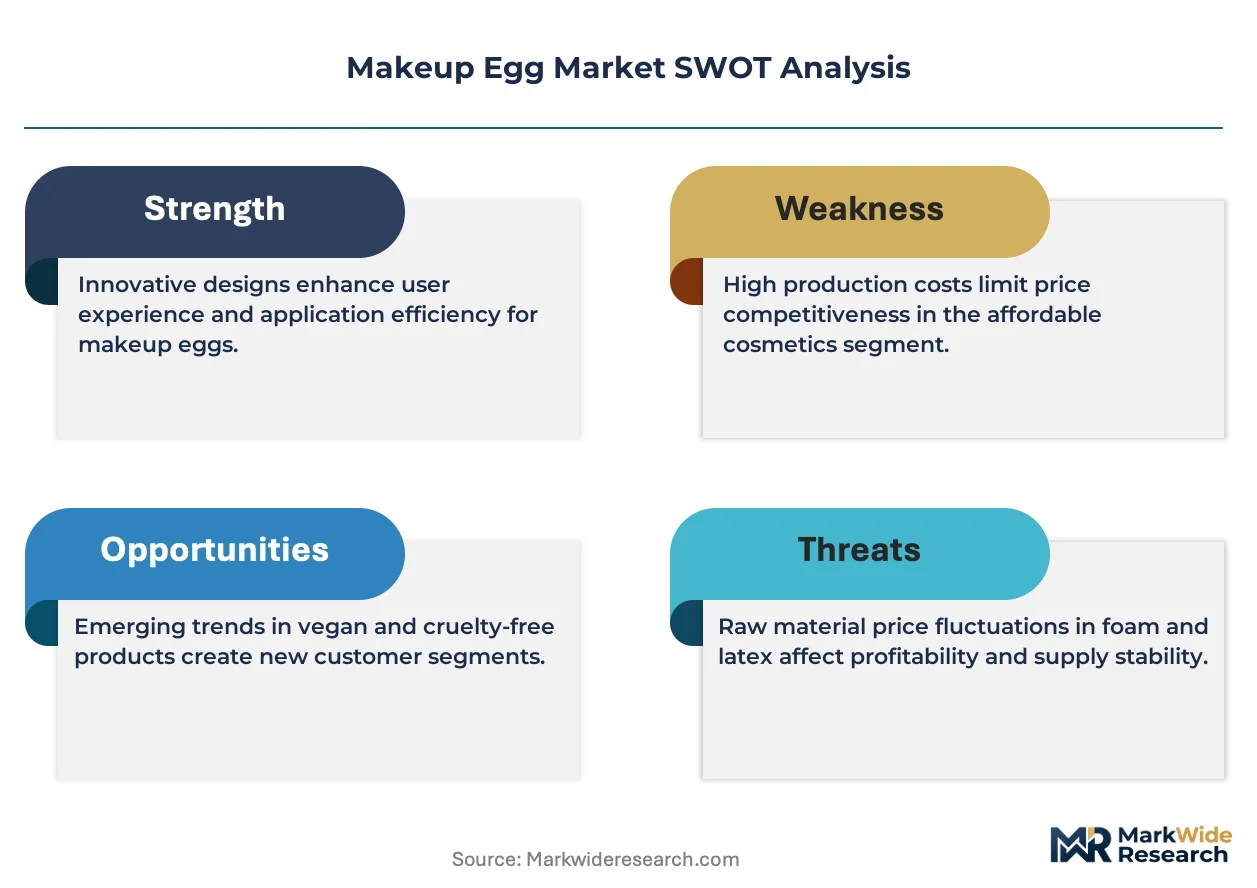
The EU Green Deal is recalibrating material sourcing priorities across cosmetic applicator supply chains, forcing manufacturers to abandon petroleum-derived foams and accelerate bio-based polymer adoption.
Growth Catalysts
- REACH chemical restrictions:The EU's substance authorization requirements are accelerating latex-free foam migration as manufacturers reformulate to preserve European retail access.
- Professional salon channel:Beauty service providers in the United States are standardizing disposable sponge protocols to reduce cross-contamination liability.
- Silicone surface engineering:Non-porous applicator formats are capturing hygiene-conscious consumers through reduced bacterial retention claims and extended replacement cycles.
Market Restraints
- Petrochemical input volatility:Polyurethane foam production remains exposed to crude oil derivative price swings that compress contract manufacturing margins.
- Chinese molding equipment concentration:Precision sponge cutting and thermal bonding machinery supply concentrates in Guangdong province, creating single-source vulnerability.
- California Proposition 65 friction:The state's chemical disclosure mandates impose labeling burdens on imported silicone formulations that delay product launches.
Strategic Opportunities
- Indian professional beauty sector:Underdeveloped salon infrastructure in tier-two cities creates first-mover positioning for applicator distributors establishing direct supply relationships.
- Biodegradable polymer convergence:PLA-cellulose composite development is opening compostable sponge categories that align with retailer clean-beauty certification programs.
- Subscription channel innovation:Direct-to-consumer replacement cycles are anchoring recurring revenue models that bypass traditional retail slotting fees.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in open-cell foam density calibration and skin-contact biocompatibility testing remains concentrated among legacy European compounders.
- ISO 10993 certification timelines:Extended biological evaluation protocols for new polymer introductions stretch product development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Makeup Egg Market |
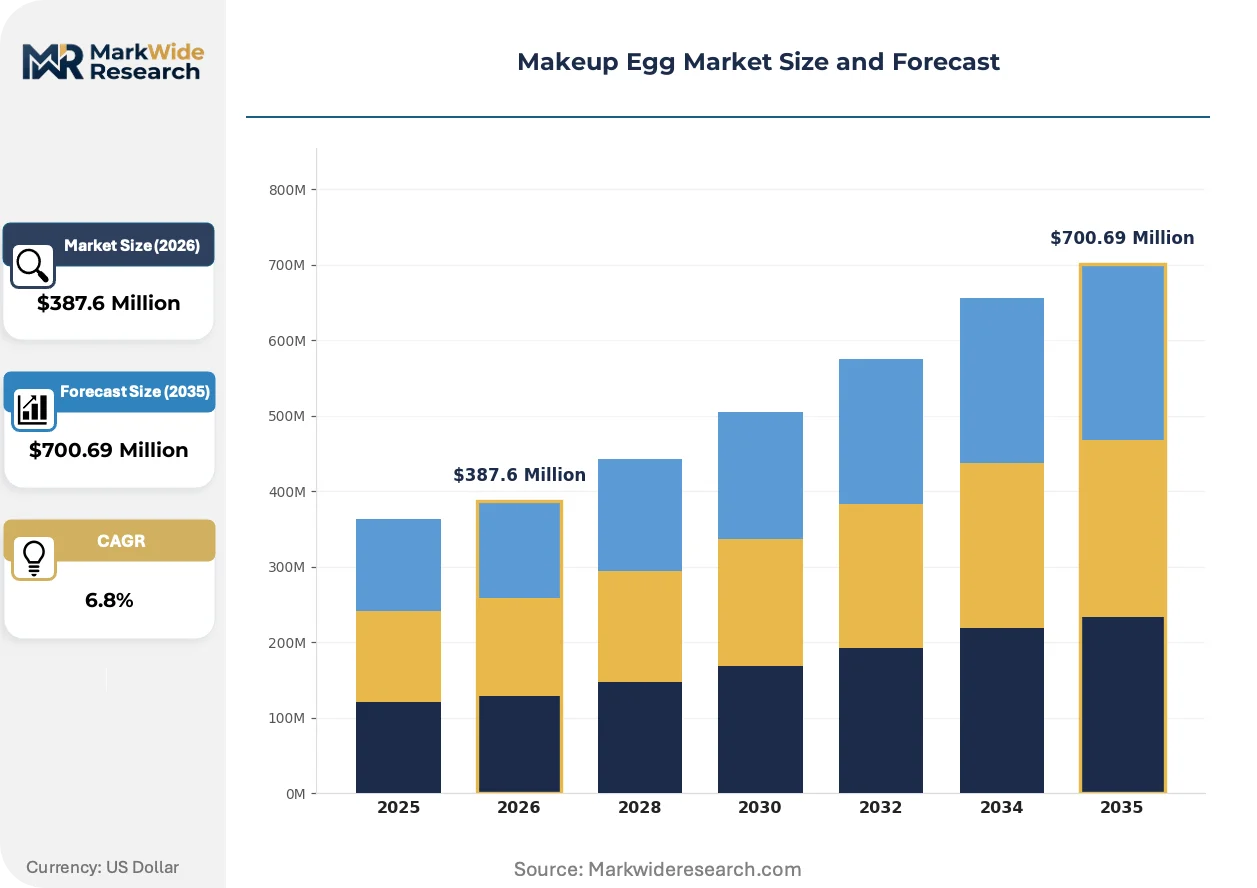
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blending Sponge, Silicone Sponge, Powder Puff, Applicator Brush Material: Foam, Silicone, Velvet, Latex Shape: Teardrop, Oval, Flat, Round Application: Foundation, Concealer, Blush, Baking |
| Companies Covered | Beautyblender, Real Techniques, e.l.f. Cosmetics, Revolution Beauty, NYX Professional Makeup, Sigma Beauty, Anastasia Beverly Hills, Tarte Cosmetics, IT Cosmetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Makeup Egg Market Trends and Innovations
Material science breakthroughs and regulatory chemistry restrictions are converging to transform applicator composition, manufacturing location, and end-of-life disposal pathways.
Plant-derived polyurethane alternatives are absorbing significant research investment from compounders seeking to decouple from fossil feedstocks. Major beauty retailers in Germany and France are mandating bio-based content thresholds for shelf placement. This material transition is absorbing capital that previously flowed into conventional foam capacity expansion.
REACH substance restrictions are tightening allowable residual monomer levels in cosmetic-grade polymers. The European Chemicals Agency's updated guidance is forcing reformulation of traditional latex alternatives. Small-batch manufacturers in Spain and Italy are responding by localizing blending operations to reduce cross-border compliance complexity.
Professional makeup artists are consolidating purchasing through specialized distributor cooperatives that aggregate volume and standardize quality specifications. These buying collectives are displacing fragmented direct-to-brand procurement across the United Kingdom and Netherlands. Channel concentration is most pronounced in metropolitan salon clusters where hygiene liability concerns drive preference for certified single-use formats.
Makeup Egg Market Segmentation
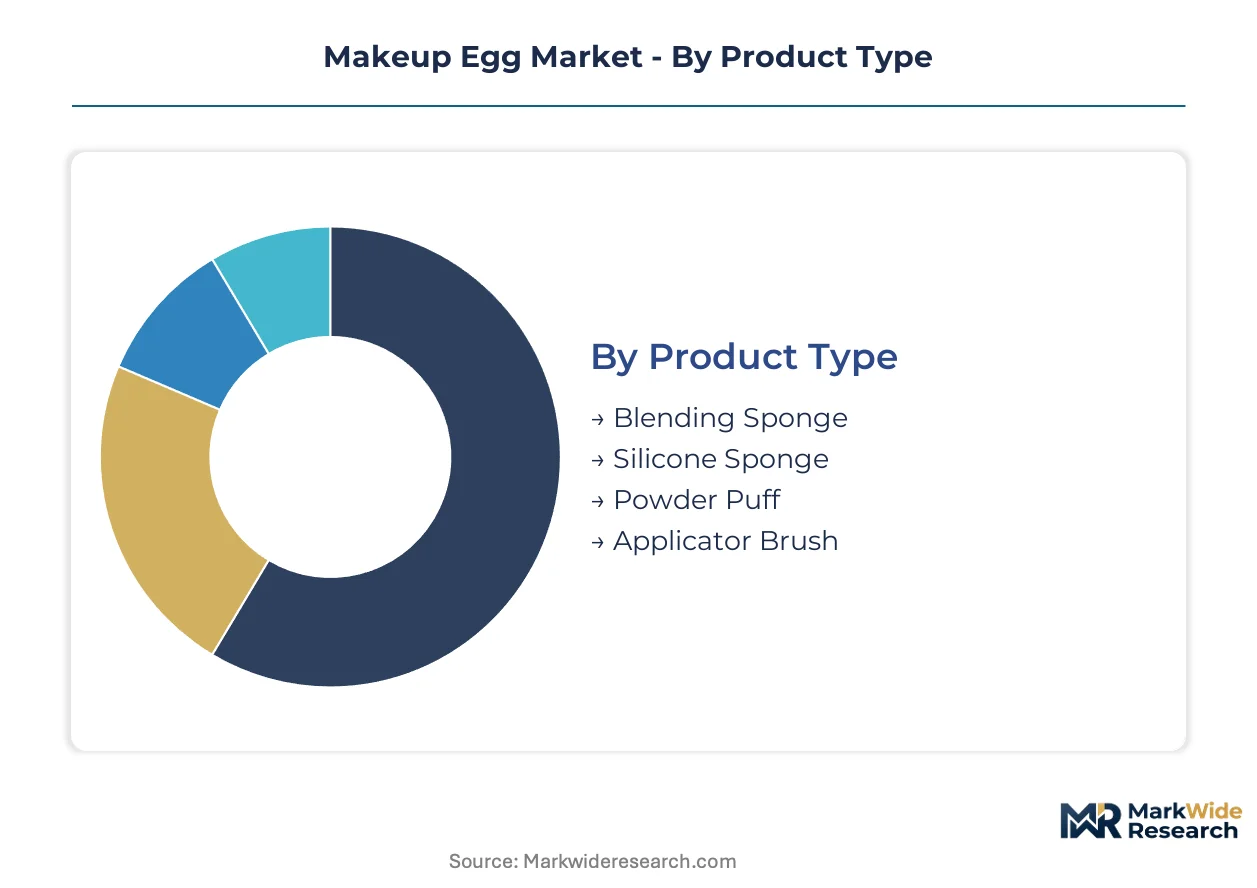
Segmentation in the makeup egg market reveals how material science, application technique, and professional workflow requirements fragment demand across distinct purchasing behaviors. Manufacturers configure production lines around these divisions to capture recurring replacement cycles versus premium durability positioning.
Product Type:
Volume concentration favors mass-market formats, while premium tiers exploit hygiene differentiation and extended replacement intervals.
- Blending Sponge:Open-cell polyurethane foam construction enables controlled absorption and release of liquid formulations. United States direct-to-consumer channels and influencer-driven purchasing sustain category dominance through recurring 3-month replacement cycles. Professional makeup artists in Los Angeles and New York metropolitan clusters standardize disposable protocols to reduce cross-contamination liability.
- Silicone Sponge:Non-porous elastomer surfaces eliminate bacterial retention and reduce product waste through zero-absorption deposition. German and French clean-beauty retailers mandate bio-based content thresholds that accelerate silicone surface engineering investments. Extended replacement cycles of 12-18 months compress unit volume but expand margin profiles.
- Powder Puff:Velour and microfiber constructions target pressed powder and setting applications with reusable maintenance protocols.
- Applicator Brush:Synthetic and natural fiber alternatives serve precision placement requirements in professional salon environments.
Mature deployment sits with blending sponge formats. Newer deployment is concentrated in silicone sponge variants gaining share fastest through hygiene-conscious positioning.
Material:
Petrochemical dependency versus bio-based substitution defines competitive positioning as regulatory chemistry restrictions tighten.
- Foam:Open-cell polyurethane dominates production volumes through cost-efficient thermal bonding and precision cutting equipment concentrated in Guangdong province. California Proposition 65 disclosure mandates on residual monomers delay imported formulation launches while accelerating latex-free alternatives.
- Silicone:Platinum-cured elastomers enable non-porous surface engineering with ISO 10993 biocompatibility certification requirements stretching development timelines 12-18 months. REACH substance restrictions on allowable residual monomer levels force reformulation of traditional cosmetic-grade polymers.
- Velvet:Microfiber and velour constructions serve powder application specialists seeking soft-finish deposition.
- Latex:Natural rubber alternatives face dermatological sensitivity concerns and accelerating regulatory phase-out across European retail channels.
Conventional foam formulations anchor current supply. PLA-cellulose composite development represents the steepest expansion trajectory as compostable categories align with retailer clean-beauty certification programs.
Shape:
Ergonomic design patents and professional workflow integration determine premium extraction potential.
- Teardrop:Dual-radius geometry enables precision tip application and broad base blending in a single tool. Professional makeup artists in London and Amsterdam salon cooperatives aggregate purchasing volume around standardized teardrop specifications.
- Oval:Extended surface area accommodates rapid full-face foundation deployment in high-throughput beauty service environments.
- Flat:Contoured edges target baking technique precision and pressed powder setting in theatrical and broadcast applications.
- Round:Symmetrical geometry simplifies manufacturing molds and serves entry-level mass-market distribution through drugstore channels.
Specialized ergonomic patents cluster around teardrop variants. Flat and round geometries concentrate in price-sensitive mass retail procurement.
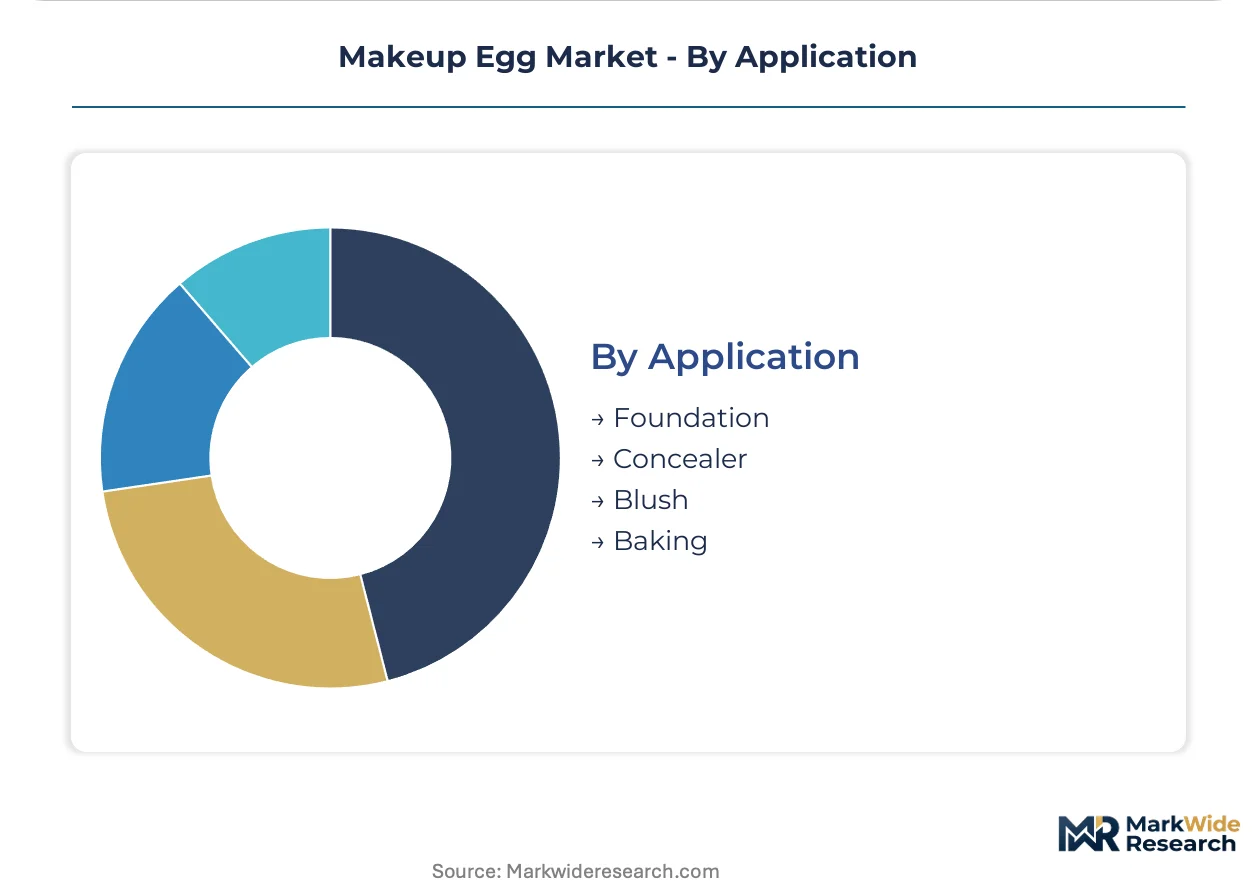
Application:
Professional technique specialization fragments demand across distinct performance requirements and replacement protocols.
- Foundation:Liquid and cream formulation deposition demands controlled absorption-release balance that open-cell foam calibrates through density specification. United States beauty salons standardize single-use protocols to mitigate hygiene liability exposure.
- Concealer:Precision placement requirements favor smaller dimensional formats and targeted tip geometries in professional kits.
- Blush:Cream and powder compatibility drives dual-material tool configurations with distinct surface treatments per formulation type.
- Baking:Setting powder accumulation and press technique demands flat-edged geometries with dense fiber or foam construction for product load retention.
Foundation application anchors volume throughput. Baking technique specialization commands premium positioning through professional education channel integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Guangdong province precision machinery clusters while consumption fragments across distinct regulatory environments and professional beauty service densities. The United States absorbs premium volumes through direct-to-consumer channels and salon cooperatives. European demand bifurcates between REACH-compliant professional supply chains and mass retail clean-beauty certification programs.
United States
Los Angeles and New York metropolitan salon clusters standardize disposable blending sponge protocols to mitigate cross-contamination liability. California's Proposition 65 imposes chemical disclosure burdens on imported silicone formulations that delay product launches. Direct-to-consumer subscription models in these coastal metros anchor recurring replacement revenue that bypasses traditional retail slotting fees.
Germany
Clean-beauty retailers in Berlin and Hamburg mandate bio-based content thresholds for shelf placement that accelerate plant-derived polyurethane development. The EU Green Deal recalibrates material sourcing priorities across cosmetic applicator supply chains entering German distribution. Frankfurt-based professional makeup artist cooperatives aggregate purchasing volume around standardized teardrop geometry specifications.
China
Guangdong province hosts concentrated precision sponge cutting and thermal bonding machinery supply that creates single-source vulnerability for global manufacturers. The country's dual carbon goals pressure petrochemical-dependent foam compounders toward bio-based polymer transition. Shenzhen and Dongguan molding equipment clusters serve contract manufacturers supplying European REACH-compliant formulations.
France
Parisian beauty retailers enforce ECHA substance restriction compliance on residual monomer levels in cosmetic-grade polymers. ANSM oversight of skin-contact biocompatibility testing extends certification timelines for new silicone surface engineering introductions. Lyon and Marseille salon distributors are consolidating procurement through specialized cooperatives that displace fragmented direct-to-brand purchasing.
India
Tier-two cities present first-mover positioning for applicator distributors establishing direct supply relationships with underdeveloped salon infrastructure. BIS standards for cosmetic safety labeling create compliance complexity for imported foam formulations. Mumbai and Bangalore professional beauty service expansion drives demand for certified single-use formats that reduce hygiene liability exposure.
Makeup Egg Market Competitive Landscape
The competitive structure tilts toward brand-architect specialists controlling channel access and manufacturing-integrated compounders securing material compliance. Premium positioning depends on ergonomic design patents and professional education channel integration rather than manufacturing scale alone. Two dominant archetypes occupy the landscape: Los Angeles-based brand houses leveraging influencer-driven distribution and European compounders localizing blending operations to reduce REACH cross-border complexity. Competitive moves concentrate on backward integration into bio-based polymer supply and exclusive retailer certification partnerships.
Within the brand-architect tier, Beautyblender exemplifies premium positioning through domestic manufacturing control, while Real Techniques occupies mass-market channel density across Boots and Ulta networks. e.l.f. Cosmetics anchors the volume-driven end through aggressive digital pricing and mass retail partnership scale. These three entities collectively represent the pricing stratification spanning premium brand equity, mid-tier professional access, and economy-tier volume extraction that defines competitive segmentation.
| Leading Market Players |
|---|
| Beautyblender |
| Real Techniques |
| e.l.f. Cosmetics |
| Revolution Beauty |
| NYX Professional Makeup |
| Sigma Beauty |
| Anastasia Beverly Hills |
| Tarte Cosmetics |
| IT Cosmetics |
| Others |
Pricing and Supply Chain Analysis
Three-tier pricing structure across premium, standard, and economy levels bifurcates procurement behaviors between certified professional supply chains and mass retail channels, with REACH compliance costs and Guangdong manufacturing concentration determining margin capture across each tier. Price premiums for ISO 10993-certified silicone formulations reflect extended certification timelines, while commodity foam volumes compete on thermal bonding equipment utilization rates in Chinese contract manufacturing clusters.
Pricing Analysis
Cost-down pressure on standard-tier foam applicators accelerates because petrochemical input volatility compresses contract manufacturing margins, while premium silicone formats maintain pricing power through extended 12-18 month replacement cycles and hygiene liability reduction claims. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and brand equity, with professional salon cooperatives least price-sensitive and drugstore mass-market channels most sensitive to per-unit procurement costs. Subscription direct-to-consumer models bypass traditional retail slotting fees through recurring replacement revenue anchoring.
Supply Chain Analysis
Polyurethane foam compound supply rests on Guangdong province precision cutting and thermal bonding machinery clusters, with platinum-cured silicone elastomers drawing from Japanese and German specialty chemical producers. Raw material dependencies span petroleum-derived isocyanates, bio-based PLA-cellulose composites, and cosmetic-grade platinum catalysts. Single-source vulnerability concentrates in Chinese molding equipment supply, creating disruption exposure for global manufacturers. Distribution runs through professional salon cooperatives, beauty retailer certification programs, and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restrictions and ECHA residual monomer thresholds erect compliance moats that favor incumbent compounders with localized European blending operations and certified formulation libraries.
For Market Incumbents: Hedge against bio-based polymer transition risk by anchoring backward integration into PLA-cellulose composite supply before German and French retailer mandates harden. Secure exclusive certification partnerships with clean-beauty retail programs to defend channel access against emerging silicone surface engineering specialists. Capacity addition in Spanish and Italian small-batch blending facilities reduces cross-border compliance complexity. For New Entrants and Emerging Players: Silicone surface engineering breakthroughs offer technology-first wedge positioning against legacy foam incumbents. Target Indian tier-two city salon infrastructure gaps through direct supply relationships before established distributors consolidate procurement. Subscription channel innovation with biodegradable polymer convergence provides go-to-market differentiation bypassing retail slotting barriers. For Investors and Strategic Acquirers: Re-rating potential sits with European compounders possessing REACH-certified formulation libraries given tightening ECHA substance restrictions. Long-term viability favors manufacturers with backward integration into bio-based polymer supply chains and professional education channel integration. Watch Indian BIS cosmetic safety labeling implementation as inflection signal for compliance-capable entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polymer Supply | Captures margin from PLA-cellulose composites as German retailers mandate bio-based thresholds. |
| REACH-Certified Formulation Library Expansion | Preserves European retail access amid ECHA residual monomer restriction tightening. |
| Professional Salon Cooperative Partnership | Aggregates purchasing volume in Los Angeles and New York metropolitan clusters. |
| Direct-to-Consumer Subscription Launch | Bypasses traditional retail slotting fees through recurring 3-month replacement cycles. |
| Indian Tier-Two City Distribution Buildout | Establishes first-mover positioning in underdeveloped professional beauty infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cosmetic compounders, professional makeup artists, beauty retailer category buyers, and contract manufacturing procurement leads. ECHA substance restriction guidance, FDA cosmetic safety labeling requirements, and California Proposition 65 disclosure mandates provided regulatory boundary conditions. Bottom-up demand modeling across product type, material composition, and application technique triangulated against top-down market sizing from customs trade flows and retail audit data.
Granularity-level modeling deployed separate frameworks for blending sponge replacement cycles, silicone sponge extended-use economics, and professional versus consumer procurement behaviors. Segmentation dimensions included product type, material composition, shape geometry, and application technique across the analysis window. CAGRs derived from trend extrapolation of replacement frequency data, regulatory compliance cost trajectories, and channel shift dynamics in direct-to-consumer subscription adoption.
Several conditions sit outside the modeled scope, including sudden petrochemical price shocks, unanticipated REACH substance bans, and trade policy disruptions affecting Guangdong equipment imports. Forecasts reflect assumptions around regulatory implementation timelines and bio-based polymer cost curves. A small set of named triggers warrants ongoing watch: ECHA residual monomer threshold revisions, Indian BIS labeling enforcement acceleration, and major retailer clean-beauty certification program expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Bath and Shower Products Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
Cosmetology Market
Beauty & Personal Care
Hair Gel Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Luxury Beauty Devices Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Hair and Nail Accessories Market
Beauty & Personal Care
United States Male Grooming Products Market
Beauty & Personal Care
Global Probiotic Cosmetic Products Market
Beauty & Personal Care
Lip Care Products Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
Facial Cleansers and Toners Market
Beauty & Personal Care
US Color Cosmetics Market