
 DNA and Gene Cloning Services Market | 2026-2036
DNA and Gene Cloning Services Market Size, Share, and Industry Trends Forecast 2026-2036
DNA and Gene Cloning Services Market Outlook
Platform licensing revenue from proprietary vector backbones and CRISPR toolkit access is reshaping how DNA and gene cloning services capture value upstream of commoditized synthesis. Thermo Fisher Scientific leverages its Gibco cell culture franchise to bundle cloning with downstream bioproduction workflows. GenScript anchors its competitive position through automated gene synthesis platforms that compress turnaround times for complex sequences. Charles River Laboratories extends its preclinical service footprint by integrating custom vector construction into safety assessment programs.
DNA and gene cloning services encompass the design, assembly, propagation, and verification of recombinant DNA molecules in host cells, typically requiring sequence fidelity above 99.9 percent and endotoxin levels below 0.1 EU per microgram for therapeutic applications. Gene synthesis and vector construction command premium pricing due to intellectual property complexity and regulatory traceability requirements, while amplification services face margin compression from polymerase commoditization. CRISPR technology segments attract disproportionate R&D investment as pharmaceutical sponsors demand knock-in cell lines and validated guide RNA libraries, whereas restriction enzyme-based cloning retains share in legacy agricultural biotechnology pipelines.
FDA gene therapy guidance and EMA's Advanced Therapy Medicinal Products framework impose stringent documentation burdens on vector manufacturing, favoring service providers with established quality management systems and regulatory inspection histories. ISO 13485 certification and compliance with NIH recombinant DNA research guidelines function as gatekeeping credentials that filter subcontractor eligibility for federally funded projects. Stakeholders must evaluate whether in-house cloning capacity or outsourced partnerships better align with pipeline volatility and the evolving stringency of global gene therapy oversight.
Market Dynamics
CRISPR-based editing workflows are compressing traditional gene synthesis timelines while fragmenting service demand across specialized knock-in cell line providers and bulk guide RNA libraries.
Growth Catalysts
- FDA Gene Therapy Guidance:The 2024 guidance on IND-enabling studies for viral vectors mandates documented clonality verification, driving biopharmaceutical sponsors toward ISO 13485-certified service providers with established regulatory inspection histories.
- NIH Recombinant DNA Research Guidelines:Federal funding eligibility requires compliance documentation that filters subcontractor pools, concentrating contract awards among providers with pre-validated quality management systems.
- Biopharmaceutical Pipeline Expansion:Cell and gene therapy developers are outsourcing vector construction to compress IND-to-clinic timelines, with demand concentrating among CDMOs offering integrated safety assessment programs.
Market Restraints
- Phosphoramidite Supply Concentration:Oligonucleotide synthesis depends on phosphoramidite chemistry inputs sourced primarily from Chinese manufacturers, exposing service providers to tariff volatility and dual-use export control reviews.
- EMA Advanced Therapy Medicinal Products Framework:The documentation burden for vector traceability and adventitious agent testing extends project timelines by four to six months, compressing margins on fixed-price contracts.
- Polymerase Commoditization:Thermostable DNA polymerase manufacturing has consolidated among three suppliers, driving amplification service pricing toward reagent-cost-plus models with minimal value capture.
Strategic Opportunities
- India CDMO Expansion:The country's PLI scheme for biopharmaceutical manufacturing offers capital subsidies for GMP-grade vector facilities, attracting Western sponsors seeking cost arbitrage on late-stage clinical materials.
- AI-Driven Sequence Optimization:Machine learning tools for codon optimization and secondary structure prediction are converging with automated synthesis platforms, enabling providers to quote complex sequences previously rejected as technically infeasible.
- Japan PMDA Regenerative Medicine Framework:The conditional approval pathway for gene therapies accelerates commercial timelines, creating demand for Japanese domestic vector manufacturing capacity that exceeds current supply.
Industry Challenges
- CRISPR Licensing Complexity:The Broad Institute and University of California patent estates impose overlapping royalty obligations on guide RNA design services, requiring legal infrastructure that mid-scale providers struggle to maintain.
- GMP Facility Qualification Timelines:FDA pre-approval inspections for gene therapy vector suites average 18-24 months from construction completion, straining capital deployment schedules for capacity expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA and Gene Cloning Services Market |
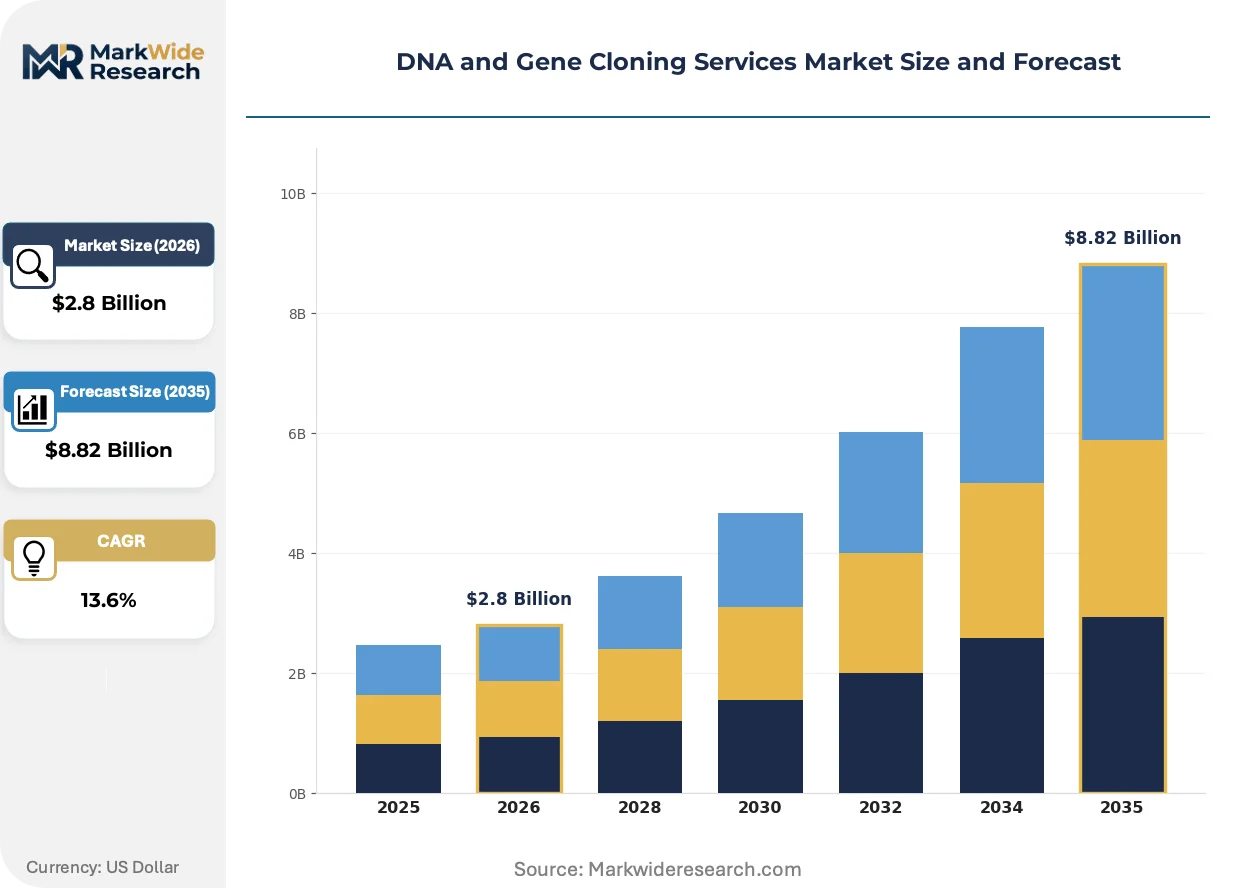
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Vector Construction, Gene Synthesis, Transformation, Amplification Technology: CRISPR, Restriction Enzymes, Polymerase Chain Reaction, Electroporation Application: Biopharmaceuticals, Agricultural Biotechnology, Academic Research, Genomic Engineering End User: Pharmaceutical Companies, Research Institutes, Biotechnology Firms, CROs |
| Companies Covered | Thermo Fisher Scientific, GenScript, Charles River Laboratories, Eurofins Scientific, Bio-Techne, Twist Bioscience, Danaher Corporation, Merck KGaA, Takara Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA and Gene Cloning Services Market Strategic Shifts
Gene editing and synthesis technologies are converging with automated bioproduction platforms, reshaping how service providers capture value upstream of commoditized reagent supply.
Cell-free gene assembly systems are hybridizing traditional bacterial cloning workflows with in vitro enzymatic methods. Biopharmaceutical developers are adopting these platforms for rapid prototype iteration before committing to GMP manufacturing campaigns. This hybridization is compressing early-stage discovery timelines from months to weeks while fragmenting demand between research-grade and regulated service tiers.
EMA's forthcoming revision to the Advanced Therapy Medicinal Products GMP annex will mandate continuous monitoring of adventitious agents in viral vector production. European contract manufacturers are retrofitting facilities with rapid molecular testing capabilities to preempt compliance gaps. Gene therapy sponsors with EU commercialization targets are prioritizing providers with demonstrated EMA inspection histories over lower-cost alternatives.
Service unbundling is separating sequence verification, endotoxin testing, and regulatory documentation into discrete procurement decisions. Large biopharmaceutical procurement functions are disaggregating these components to optimize cost allocation across internal and external capabilities. This pattern is most visible among US-based gene therapy developers managing multi-site manufacturing networks.
DNA and Gene Cloning Services Market Segmentation
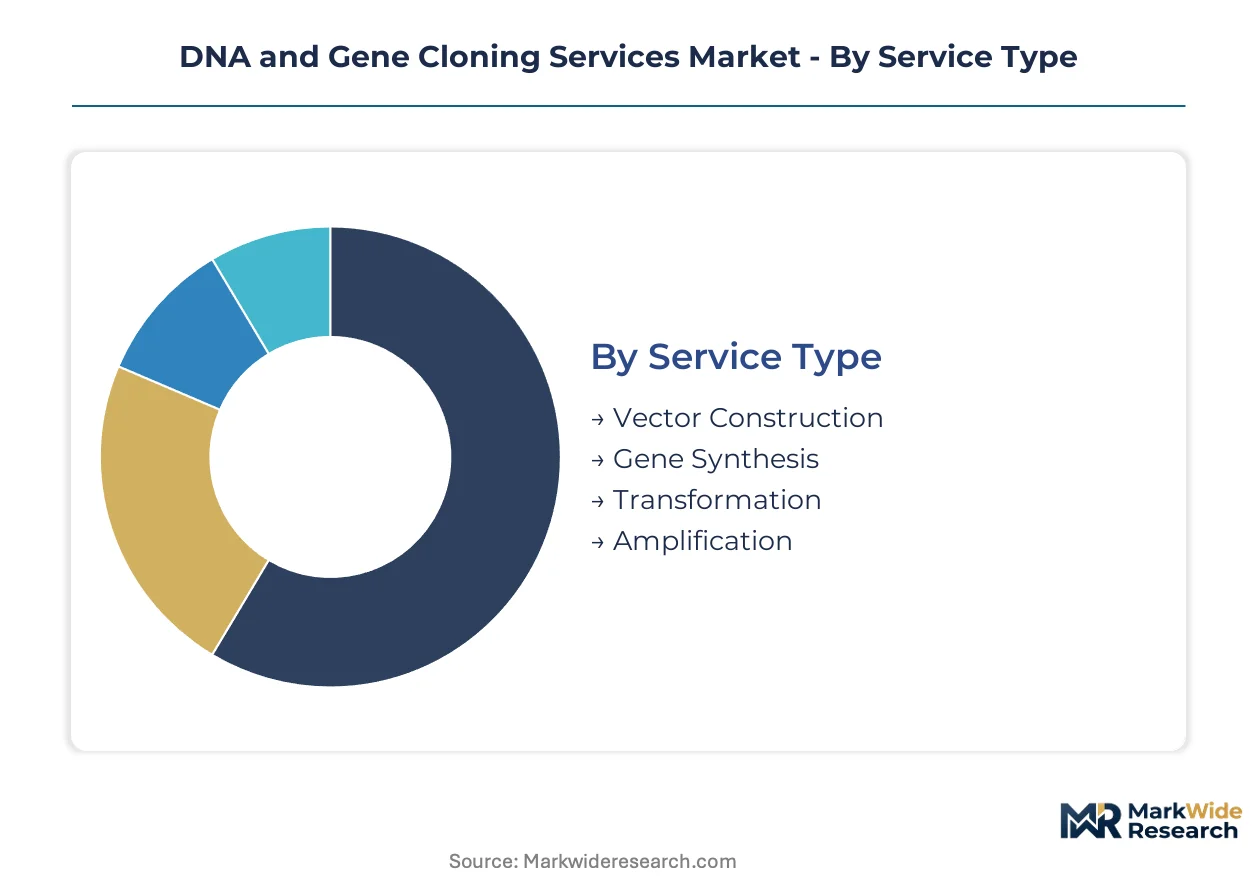
Service differentiation in DNA and gene cloning reflects divergent technical complexity, regulatory burden, and value capture potential across the biopharmaceutical value chain. Procurement patterns increasingly disaggregate research-grade from GMP-qualified workflows, reshaping how providers structure pricing and capacity investments.
Service Type:
The use-case spectrum spans exploratory research through commercial vector manufacturing, with regulatory stringency escalating across each tier.
- Gene Synthesis:De novo DNA assembly from oligonucleotide building blocks achieves sequence fidelity above 99.9 percent for therapeutic applications. Demand concentrates among US-based gene therapy developers seeking IND-enabling documentation under FDA guidance, with automated platforms compressing turnaround times for complex sequences.
- Vector Construction:Design and assembly of plasmid, viral, and non-viral delivery systems requires clonality verification and endotoxin documentation. Biopharmaceutical sponsors outsource this capability to CDMOs with established ISO 13485 certification, avoiding 18-24 month GMP facility qualification timelines.
- Transformation:Introduction of recombinant DNA into bacterial or mammalian host cells for propagation and selection.
- Amplification:Large-scale production of DNA constructs through bacterial culture or PCR-based methods, facing margin compression from polymerase commoditization.
Established volume favors amplification; emerging adoption favors gene synthesis.
Technology:
Cost tier stratification separates premium editing platforms from legacy enzymatic methods.
- CRISPR:RNA-guided nuclease systems enable precise knock-in, knock-out, and base editing with reduced timeline requirements versus traditional homologous recombination. Pharmaceutical sponsors demand validated guide RNA libraries and clonal cell lines, though Broad Institute and University of California patent estates impose overlapping royalty obligations on service providers.
- Polymerase Chain Reaction:Thermostable enzyme-mediated DNA amplification remains foundational for construct verification and insert preparation. Thermo Fisher Scientific and two other suppliers control manufacturing, driving reagent-cost-plus pricing with minimal value capture for amplification service providers.
- Restriction Enzymes:Site-specific DNA cleavage and ligation workflows retain share in agricultural biotechnology pipelines with lower regulatory documentation requirements.
- Electroporation:Physical membrane permeabilization for DNA delivery into recalcitrant cell types, particularly primary cells and organoids.
Legacy infrastructure favors restriction enzymes; steepest expansion trajectory belongs to CRISPR.
Application:
Customer type determines margin structure, with commercial biopharmaceutical sponsors commanding premium pricing for regulatory traceability.
- Biopharmaceuticals:Viral vector and cell therapy manufacturing requires GMP-grade cloning with adventitious agent testing and continuous monitoring capabilities. EMA's forthcoming ATMP GMP annex revision is driving European contract manufacturer retrofit investments.
- Genomic Engineering:CRISPR-based cell line development for functional genomics and therapeutic discovery. Academic and commercial demand converges on knock-in capabilities for disease model generation.
- Agricultural Biotechnology:Trait stacking and crop improvement applications utilize lower-stringency research-grade services with reduced documentation burdens.
- Academic Research:Exploratory cloning for basic science, price-sensitive and fragmented across institutional core facilities and commercial providers.
Regulatory premium favors biopharmaceuticals; volume accessibility favors academic research.
End User:
Supply concentration aligns with procurement sophistication and pipeline volatility tolerance.
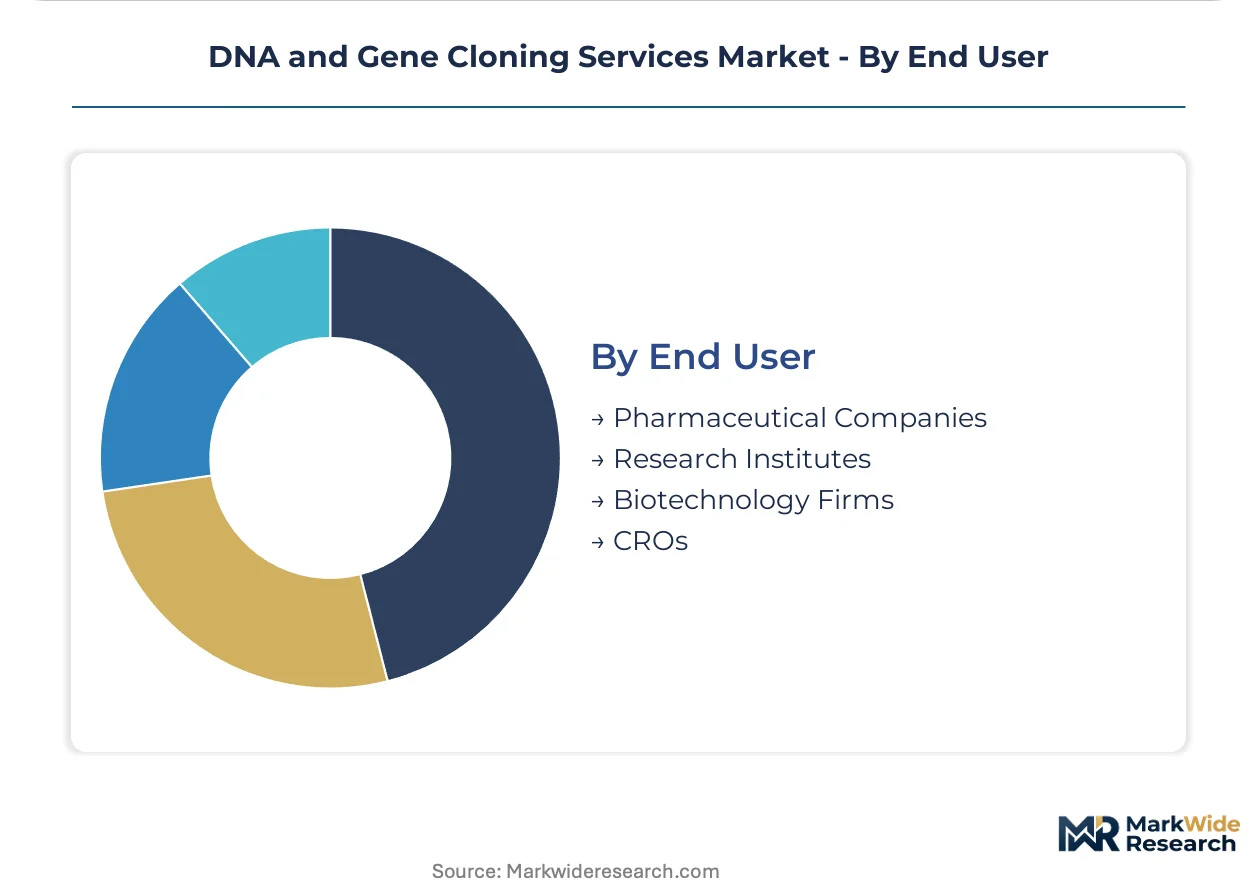
- Pharmaceutical Companies:Integrated biopharmaceutical sponsors outsource vector construction to compress IND-to-clinic timelines, prioritizing providers with FDA inspection histories over cost optimization.
- Biotechnology Firms:Cell and gene therapy developers with asset-specific funding cycles demand flexible capacity without capital-intensive in-house infrastructure.
- Research Institutes:NIH-funded projects require compliance documentation that filters subcontractor pools toward pre-validated quality management systems.
- CROs:Contract research organizations aggregate demand across multiple sponsors, capturing economies of scale in guide RNA library production and safety assessment integration.
Procurement scale favors CROs; technical specification intensity favors pharmaceutical companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy developers in the United States prioritize regulatory traceability over cost optimization, while sponsors in India and China leverage manufacturing subsidies to compress vector production economics. European demand clusters around EMA inspection histories, and Japanese sponsors face acute domestic capacity constraints under accelerated approval pathways.
United States
FDA gene therapy guidance mandates documented clonality verification for IND-enabling studies, driving biopharmaceutical sponsors toward ISO 13485-certified providers. NIH recombinant DNA research guidelines filter federal funding eligibility toward pre-validated quality management systems. The Greater Boston corridor concentrates CRISPR-based cell line development demand alongside Cambridge-area gene therapy developers.
Germany
EMA's Advanced Therapy Medicinal Products framework imposes stringent vector traceability requirements that extend project timelines by four to six months. The country's national pharmaceutical regulator enforces continuous adventitious agent monitoring standards that preempt the forthcoming GMP annex revision. Heidelberg and Munich anchor European contract manufacturing investments for viral vector suites.
China
Phosphoramidite chemistry inputs for oligonucleotide synthesis concentrate among domestic manufacturers, exposing service providers to dual-use export control reviews. The country's national medical products administration maintains evolving oversight frameworks for gene therapy vectors. Shanghai and Suzhou biotech clusters drive automated gene synthesis platform adoption for complex sequence turnaround compression.
India
The PLI scheme for biopharmaceutical manufacturing offers capital subsidies for GMP-grade vector facilities, attracting Western sponsors seeking cost arbitrage on late-stage clinical materials. CDSCO guidelines for gene therapy products remain under development, creating regulatory navigation complexity for domestic providers. Hyderabad and Bengaluru concentrate CDMO expansion investments for viral vector capacity.
Japan
PMDA's conditional approval pathway for regenerative medicine accelerates commercial timelines, creating demand for domestic vector manufacturing capacity that exceeds current supply. METI funding priorities direct investment toward automated bioproduction platforms. The Kanto region around Tokyo faces acute facility qualification bottlenecks as gene therapy sponsors rush to secure local GMP capacity.
DNA and Gene Cloning Services Market Competitive Environment
Capability concentration sits with specialized CRISPR toolkit and vector backbone providers; scale advantage sits with diversified life sciences conglomerates. The market structure fragments across three tiers: research-grade synthesis shops, ISO-certified preclinical service providers, and GMP-qualified CDMOs with regulatory inspection histories. Strategic archetypes include platform licensors capturing upstream value, automated synthesis specialists compressing turnaround times, and integrated safety assessment providers bundling vector construction with toxicology programs. Dominant competitive moves center on AI-driven sequence optimization integration and GMP facility qualification timelines stretching capital deployment schedules.
Among diversified life sciences conglomerates, Thermo Fisher Scientific anchors the scale-driven tier through its Gibco cell culture franchise bundling capabilities. GenScript occupies a position within the automated synthesis specialist archetype, exemplifying platform-based turnaround compression for complex sequences. Charles River Laboratories represents the integrated safety assessment model, sitting within the preclinical service provider tier that extends vector construction into toxicology programs.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| GenScript |
| Charles River Laboratories |
| Eurofins Scientific |
| Bio-Techne |
| Twist Bioscience |
| Danaher Corporation |
| Merck KGaA |
| Takara Bio |
| Others |
Value Chain & Pricing Dynamics
Chinese phosphoramidite manufacturers anchor upstream oligonucleotide chemistry, concentrating margin capture in gene synthesis workflows while downstream service providers face reagent-cost-plus compression in amplification tiers. This supply geography funnels pricing power toward automated platform operators capable of bundling regulatory documentation with synthesis output.
Pricing Analysis
Long-term offtake contracts dominate biopharmaceutical sponsor relationships, locking in capacity for IND-enabling vector construction while spot procurement persists for research-grade amplification. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified CDMOs from ISO 13485 preclinical providers and uncertified synthesis shops. Cost compression in PCR-based amplification intensifies because thermostable polymerase manufacturing consolidated among three suppliers. Academic research institutes exhibit highest price sensitivity; gene therapy developers with FDA submission timelines prioritize regulatory traceability over unit cost.
Supply Chain Analysis
Extended payment terms from large biopharmaceutical sponsors strain working capital for mid-scale service providers, accelerating supply-chain finance facility adoption among automated platform operators. Raw material flows draw from China for phosphoramidite chemistry, the United States for engineered nucleases, and Germany for precision fermentation-derived reagents. Single-source vulnerability concentrates in Chinese phosphoramidite export controls under dual-use technology reviews. Distribution runs through direct CDMO-sponsor relationships for GMP tiers and distributor networks for research-grade catalog products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated biopharmaceutical sponsors with multi-site manufacturing networks, fragmenting procurement decisions across discrete service components and squeezing margin capture for undifferentiated providers.
For Market Incumbents: Pre-empt CRISPR licensing complexity by securing Broad Institute and University of California patent access before royalty stacking escalates. Build ISO 13485-certified capacity in the Kanto region around Tokyo to capture PMDA conditional approval pathway demand that exceeds domestic supply. Defend against polymerase commoditization by bundling downstream toxicology assessment with vector construction workflows. For New Entrants and Emerging Players: Build out automated gene synthesis platforms targeting complex sequence categories previously rejected as technically infeasible, leveraging AI-driven codon optimization to compress turnaround times. Penetrate the India CDMO expansion opportunity under PLI scheme subsidies for GMP-grade vector facilities, where Western sponsors seek cost arbitrage on late-stage clinical materials. Lead with regulatory documentation capabilities rather than price positioning to differentiate from established volume players. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automated synthesis specialists holding proprietary vector backbone IP but lacking GMP facility qualification timelines. Five-to-ten year viability hinges on regulatory inspection histories becoming scarcer relative to gene therapy pipeline expansion. Watch for EMA ATMP GMP annex revision enforcement as signal for European contract manufacturer retrofit investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Qualification | FDA pre-approval inspection histories filter subcontractor eligibility for gene therapy sponsors. |
| AI-Driven Sequence Optimization | Machine learning integration enables automated platforms to quote previously infeasible complex sequences. |
| CRISPR Patent Licensing | Broad Institute and University of California estates impose overlapping royalty obligations on guide RNA services. |
| Regional CDMO Expansion | India PLI scheme subsidies attract Western sponsors seeking cost arbitrage on late-stage clinical materials. |
| Regulatory Documentation Bundling | EMA ATMP framework mandates adventitious agent testing that extends project timelines and favors established providers. |
Study Parameters
Initial hypotheses were tested against primary input from gene therapy development executives, regulatory affairs leads at CDMOs, NIH program officers, and biopharmaceutical procurement managers and refined through secondary validation against FDA guidance documents, EMA ATMP framework revisions, NIH recombinant DNA research guidelines, and ClinicalTrials.gov vector construction disclosures. Bottom-up service provider capacity assessments triangulated with top-down biopharmaceutical pipeline expenditure analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including service type tier, technology platform, therapeutic application, and regulatory certification level. CAGRs derived from fitted growth curves applied to disclosed capacity expansion timelines and sponsor outsourcing penetration rates. Forecast inputs incorporated phosphoramidite supply concentration risk and CRISPR patent estate royalty stacking assumptions.
Practitioners should monitor phosphoramidite export control enforcement, EMA inspection backlog duration, and PMDA conditional approval pathway utilization for early signals of supply constraint or demand acceleration. Forecasts reflect assumptions about regulatory documentation burden stability and gene therapy pipeline continuity; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Global CRISPR and CRISPR-Associated (Cas) Genes Market
Gene Editing & CRISPR
UK Gene Editing Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
Gene Editing Technology Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Genetic Engineering Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
CRISPR Technology Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
Gene Editing Tools Market
Gene Editing & CRISPR
Brazil Gene Editing Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
Cloning and Mutagenesis Market