
 Meal Tray Sealing Machines Market | 2026-2036
Meal Tray Sealing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Meal Tray Sealing Machines Market Foresight
Preventive maintenance contracts and remote monitoring subscriptions is broadening how sealing equipment vendors capture lifetime value. MULTIVAC leverages its global service infrastructure to lock in recurring revenue across installed bases. Omori Machinery Co. Ltd. anchors its competitive position through precision engineering for high-speed aviation catering lines. Proseal America Inc. specializes in modular systems that allow operators to upgrade sealing heads without full line replacement.
Meal tray sealing machines apply heat, pressure, and vacuum to hermetically seal pre-portioned food trays with lidding films, typically operating at temperatures between 120°C and 200°C with cycle speeds from 30 to 120 trays per minute depending on format size. Automatic systems dominate throughput-intensive environments like centralized airline kitchens and ready-meal factories where labor scarcity pushes capital allocation toward continuous-motion rotary sealers. Semi-automatic units retain strong positioning in mid-scale catering operations and regional meal-kit assembly facilities where batch flexibility outweighs speed optimization. Cloud-based deployment models are gaining traction among multi-site food manufacturers seeking centralized parameter control and predictive maintenance scheduling across distributed sealing lines.
FDA food contact substance notifications govern lidding film and tray material approvals in the United States, directly constraining equipment compatibility and retrofit demand. EFSA and EU Packaging and Packaging Waste Regulation requirements on recyclability and minimum recycled content are redirecting R&D investment toward paperboard-compatible sealing systems and aluminum-tray handling modules. Stakeholders must track how diverging national implementation timelines for extended producer responsibility frameworks reshape capital deployment priorities across manufacturing footprints.
Market Dynamics
Aviation catering networks are consolidating production into centralized commissaries, forcing equipment suppliers to engineer for 24/7 continuous operation cycles rather than intermittent batch processing. This operational intensity is redrawing vendor qualification criteria and service contract structures across the installed base.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates are accelerating retrofit demand for paperboard-compatible sealing heads in European airline kitchens.
- Cloud-based deployment models:Multi-site food manufacturers are adopting centralized parameter control platforms to synchronize sealing protocols across distributed production lines.
- Aviation catering automation:Labor scarcity in Germany's centralized food production hubs is pushing capital allocation toward rotary sealers with predictive maintenance capabilities.
Market Restraints
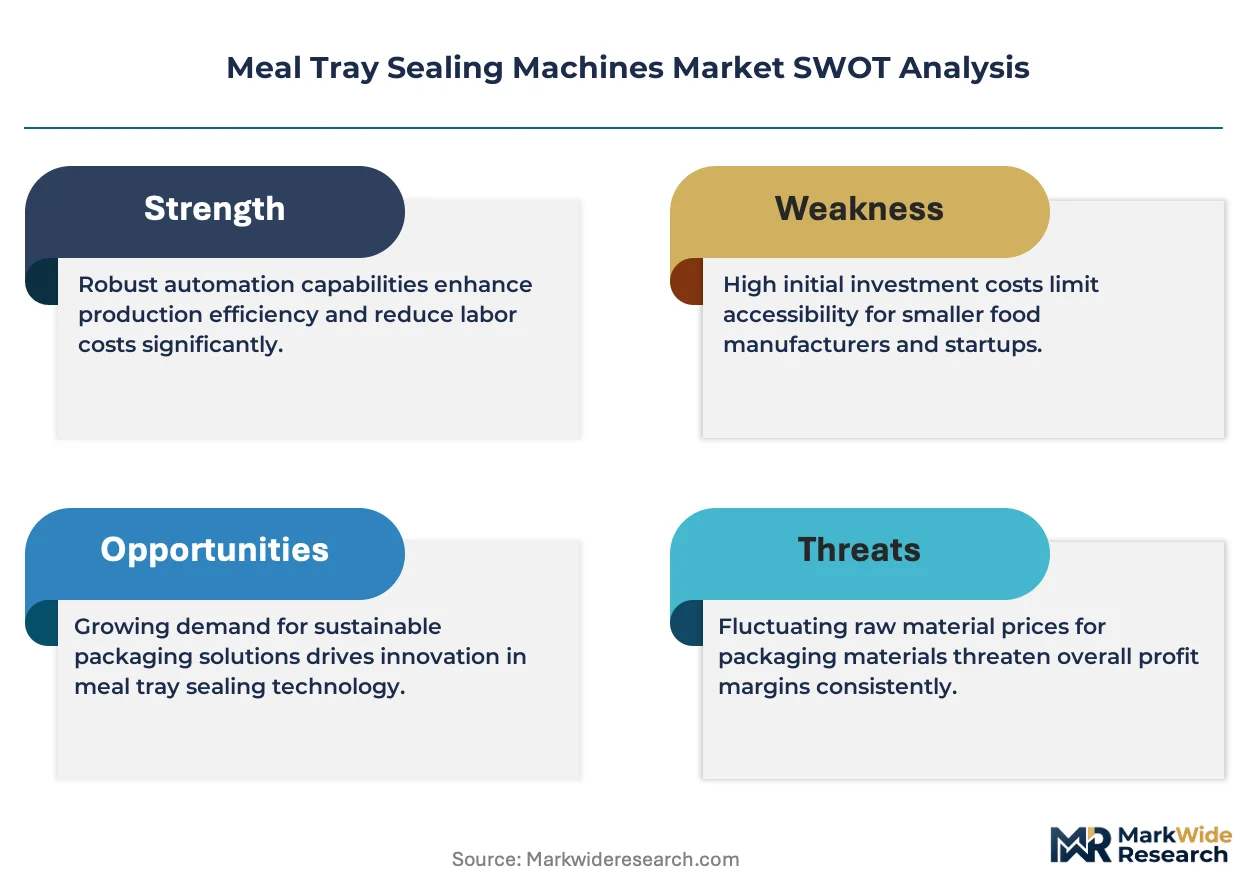
- Stainless steel and precision pneumatic component costs:Input price volatility for food-grade alloys and high-cycle actuators compresses margin structures for mid-tier equipment vendors.
- Technical limitation in film-to-tray compatibility:Hermetic seal integrity degrades across temperature cycling when polypropylene trays interface with novel bio-based lidding films, constraining material transitions.
- Regulatory friction from FDA notification timelines:Food contact substance approval delays for new lidding chemistries extend equipment qualification cycles by 18-24 months in the United States.
Strategic Opportunities
- Underpenetrated ready-meal automation in India:FSSAI-mandated food safety upgrades in institutional catering are creating first-mover openings for semi-automatic tray sealing systems.
- Technology convergence of vacuum sealing and modified atmosphere packaging:Integrated gas-flush modules are enabling shelf-life extension for premium airline meal segments without secondary packaging.
- Extended producer responsibility tailwinds:Germany's packaging licensing reforms are subsidizing equipment upgrades that demonstrate measurable film waste reduction per sealed tray.
Industry Challenges
- Electromechanical technician scarcity:Maintenance teams skilled in servo-driven sealing head calibration and IoT diagnostic interpretation remain concentrated in Western European aviation hubs.
- Capex intensity for continuous-motion rotary systems:Full-line replacement costs for high-speed aviation catering operations exceed the depreciation schedules of existing thermoform-seal equipment by a factor of three.
- Integration complexity with legacy MES architectures:Cloud-native sealing line controllers require protocol translation layers to interface with 1990s-era manufacturing execution systems still prevalent in North American ready-meal plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meal Tray Sealing Machines Market |
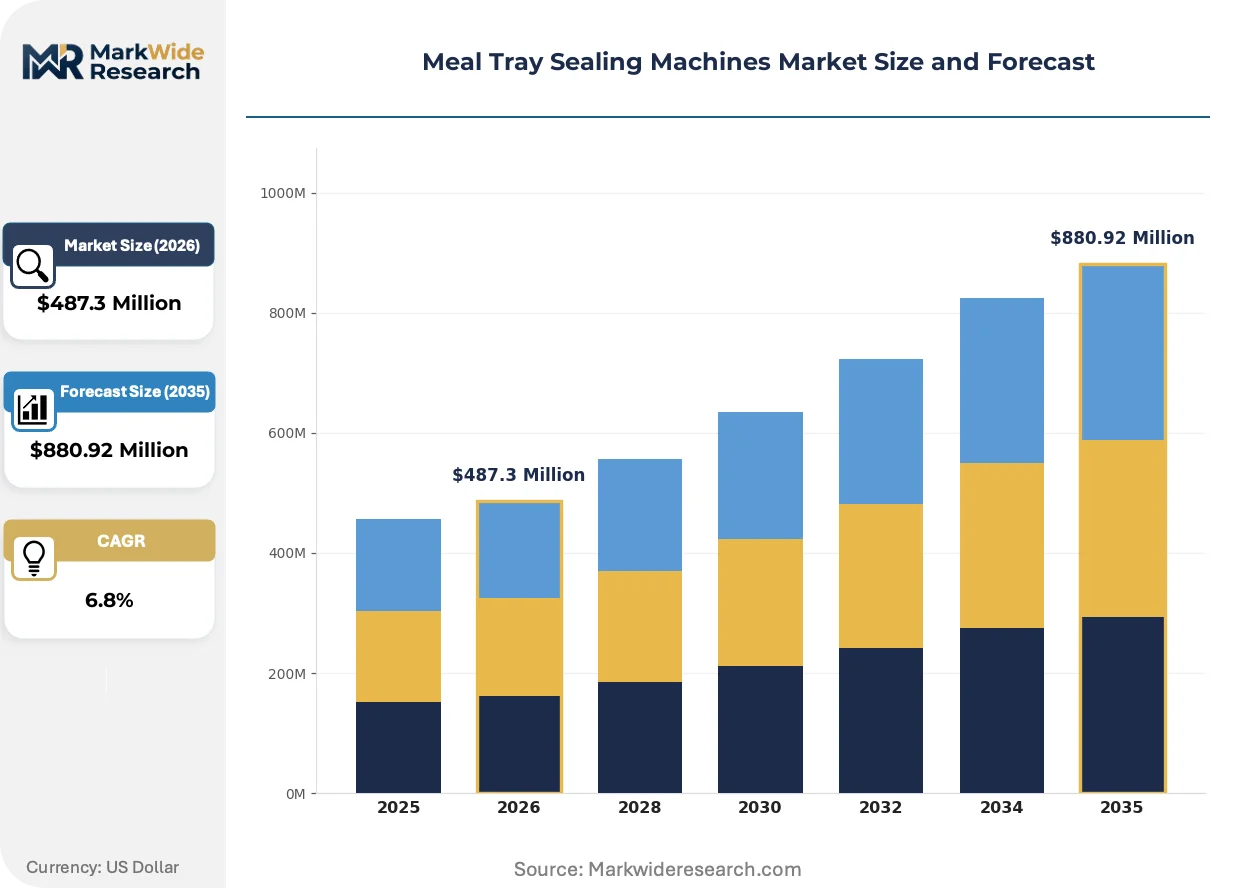
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Multilayer End User: Restaurants, Catering Services, Food Manufacturers, Meal Kit Providers Packaging Material: Plastic, Aluminum, Paperboard, Composite Deployment Model: On-Premise, Cloud-Based, Hybrid, Off-Premise |
| Companies Covered | Packaging Automation Ltd., Omori Machinery Co. Ltd., MULTIVAC, Proseal America Inc., ISHIDA CO. LTD., Ilpra S.p.A., Webomatic, ProMach, Inc., Heat Seal Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meal Tray Sealing Machines Market Shifts & Advancements
Active packaging compatibility and predictive maintenance architectures are converging to redefine equipment specification criteria. Vendors now compete on data integration depth rather than mechanical throughput alone.
Ultrasonic sealing technology is rewriting the competitive landscape for temperature-sensitive meal applications. High-end aviation caterers in Switzerland and Singapore are adopting cold-seal systems to preserve nutritional integrity in premium cabin service offerings. This shift is compressing the addressable market for conventional thermal impulse sealers in first-class and business-class meal production.
REACH restrictions on per- and polyfluoroalkyl substances are forcing lidding film reformulation across European supply chains. Equipment manufacturers must recalibrate sealing temperature profiles and dwell times to accommodate fluorine-free barrier coatings. German aviation catering networks are absorbing the steepest compliance costs as they operate the continent's densest concentration of high-speed sealing lines.
After-sales service unbundling is fragmenting vendor revenue streams. Airlines and institutional operators are separating hardware procurement from maintenance contracts, soliciting third-party technical service providers for preventive scheduling and spare parts logistics. This pattern is most visible in the United States, where centralized kitchen operators leverage FAA safety culture protocols to qualify independent service organizations against OEM standards.
Meal Tray Sealing Machines Market Segmentation
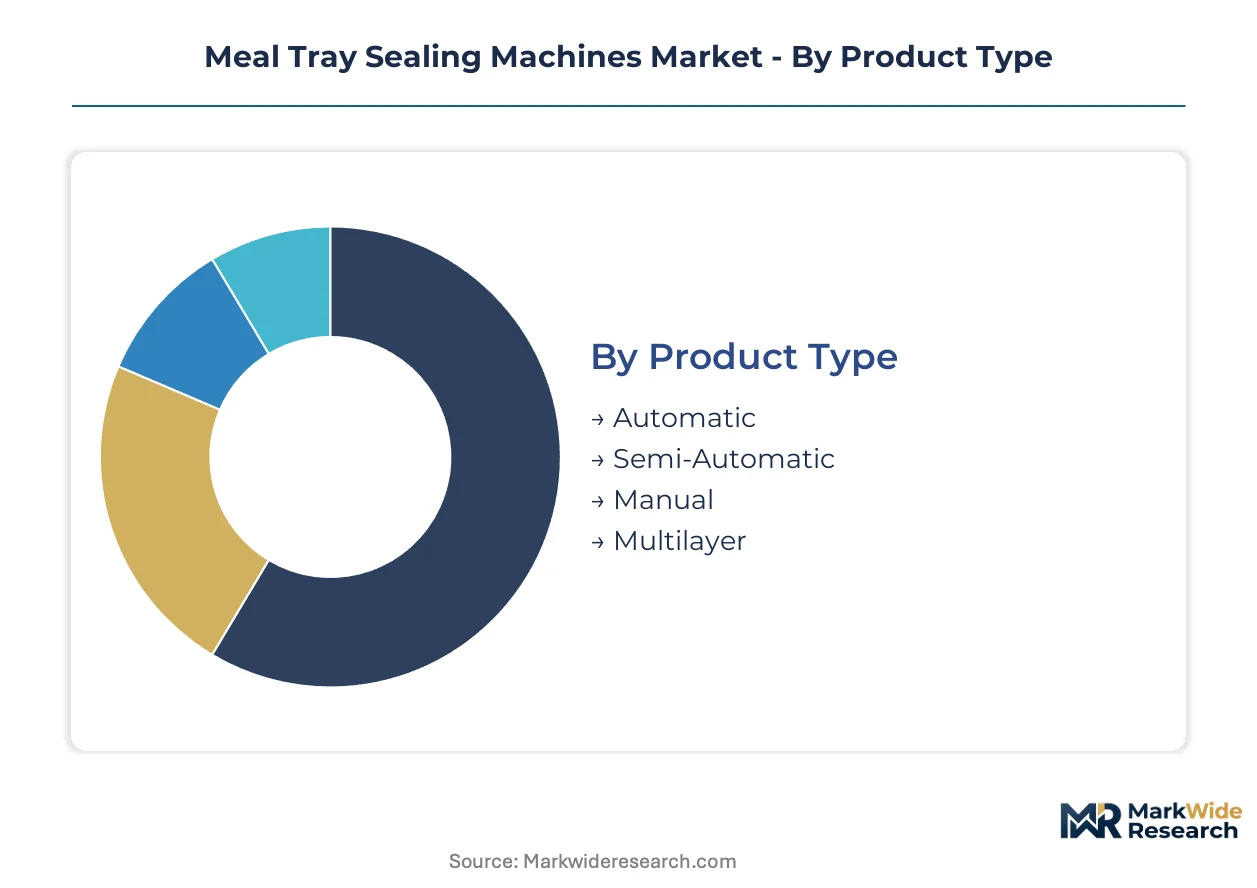
Equipment specification varies sharply across buyer workflows, from 24/7 aviation commissaries demanding continuous-motion rotary sealers to regional meal-kit facilities prioritizing batch flexibility over throughput. Segmentation reveals where capital allocation concentrates and which technology configurations command premium positioning.
Product Type:
Buyers differentiate primarily by labor substitution economics and throughput intensity rather than initial capex thresholds.
- Automatic:Continuous-motion rotary sealers operate at 80-120 trays per minute with servo-driven sealing heads and integrated gas-flush modules. Demand concentrates in Germany's centralized aviation catering hubs where 24/7 operation cycles and predictive maintenance capabilities justify seven-figure capital outlays.
- Semi-Automatic:Intermittent-motion systems with operator-fed tray loading achieve 30-60 trays per minute and retain strong positioning in mid-scale institutional catering where batch flexibility outweighs speed optimization. India's FSSAI-mandated food safety upgrades are creating first-mover openings as regional operators transition from manual sealing.
- Manual:Foot-pedal or hand-lever units serve micro-catering operations and specialty diet meal prep with sub-15 tray per minute throughput and minimal facility infrastructure requirements.
- Multilayer:Configurable systems with interchangeable sealing heads accommodate simultaneous tray formats and lidding film specifications for co-packing operations serving multiple airline clients from single production lines.
Automatic systems lead volumes today; semi-automatic configurations are gaining share fastest in emerging market institutional catering.
End User:
Operational scale and regulatory exposure determine equipment sophistication requirements across buyer categories.
- Restaurants:Single-location and small-chain operators deploy compact countertop sealers for grab-and-go program expansion, with EFSA recyclability mandates in European markets accelerating paperboard-compatible retrofits.
- Catering Services:Institutional and event-focused operators balance throughput demands against menu variability, driving interest in modular systems with rapid format changeover capabilities.
- Food Manufacturers:Ready-meal factories and centralized production facilities represent the most intensive deployment environment, with FDA food contact substance notification requirements directly constraining lidding film and equipment compatibility decisions in United States operations.
- Meal Kit Providers:Subscription-based assembly facilities prioritize portion-control precision and shelf-life extension through modified atmosphere packaging integration, with cloud-based parameter control enabling multi-site synchronization across distributed fulfillment networks.
Food manufacturers command the steepest equipment specifications; meal kit providers are expanding most quickly as subscription models penetrate suburban markets.
Packaging Material:
Material transitions are forcing sealing technology recalibration as regulatory frameworks tighten across major supply chains.
- Plastic:Polypropylene and CPET trays dominate aviation catering for microwave-reheat compatibility, though REACH restrictions on per- and polyfluoroalkyl substances are compelling fluorine-free barrier coating adoption that requires revised temperature profiles and dwell times.
- Aluminum:Ovenable trays retain premium positioning in first-class and business-class meal segments where thermal conductivity and structural rigidity justify higher material costs; German aviation networks operate the densest concentration of aluminum-handling sealing modules.
- Paperboard:Fiber-based trays with barrier coatings are gaining traction as EU Packaging and Packaging Waste Regulation recyclability mandates redirect R&D investment, though hermetic seal integrity challenges persist across temperature cycling.
- Composite:Multi-material laminates combining plastic structural layers with aluminum or paperboard barriers serve specialized shelf-life extension requirements in premium ready-meal segments.
Plastic configurations retain volume leadership; paperboard systems are climbing the fastest as European regulatory deadlines approach.
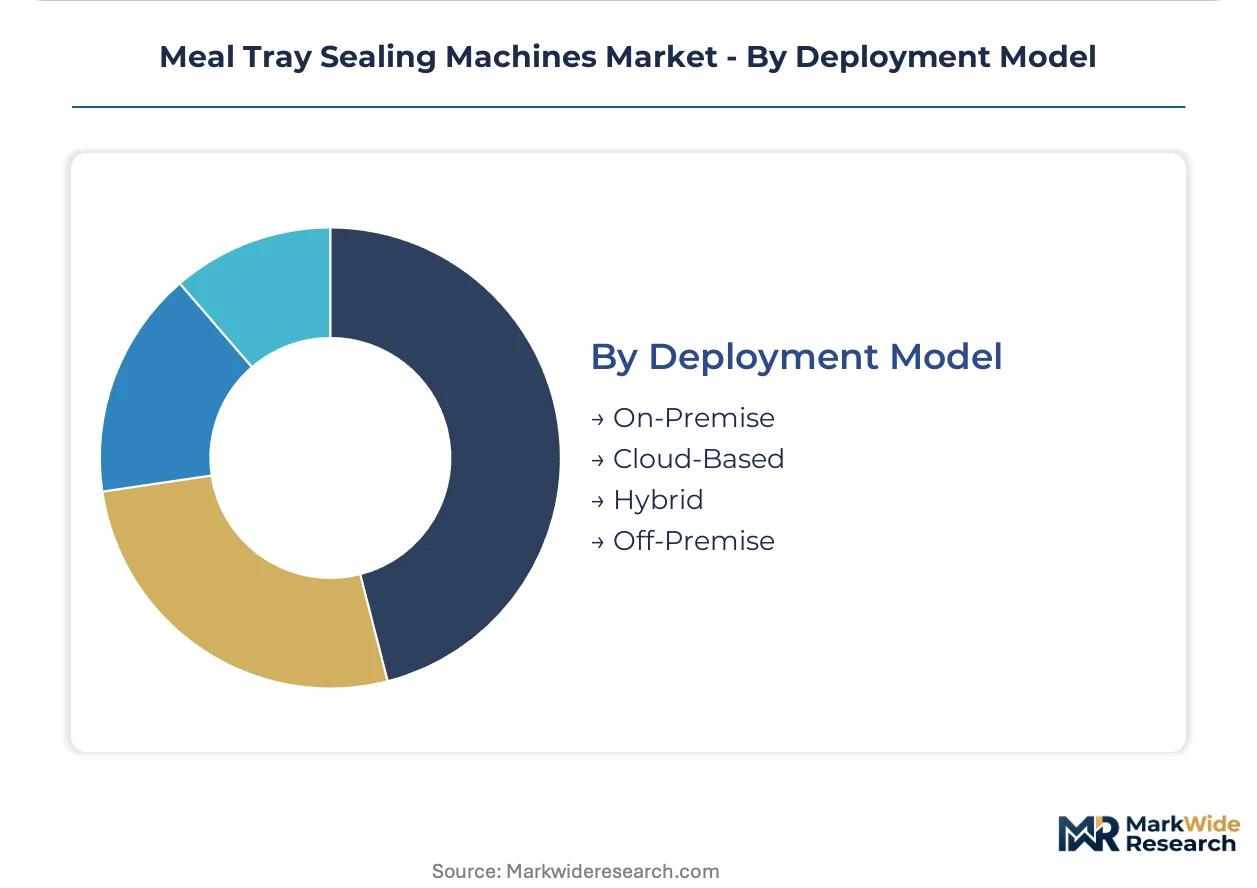
Deployment Model:
Data architecture decisions increasingly separate vendor competitive positioning as connectivity becomes standard specification.
- On-Premise:Localized control systems without external connectivity serve operators with cybersecurity constraints or legacy MES architectures requiring protocol translation layers for integration.
- Cloud-Based:Centralized parameter control platforms enable predictive maintenance scheduling and sealing protocol synchronization across distributed production lines, with multi-site food manufacturers in Switzerland and Singapore adopting these configurations for premium cabin service operations.
- Hybrid:Edge-computing architectures with local execution and cloud-based analytics balance real-time control requirements against centralized oversight needs for mid-scale operators transitioning from legacy infrastructure.
- Off-Premise:Equipment-as-a-service models with vendor-managed maintenance and parameter optimization are emerging in United States markets where airlines leverage FAA safety culture protocols to qualify third-party technical service providers.
On-premise systems dominate installed base today; cloud-based deployment is expanding most quickly among multi-site manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany operates the densest concentration of high-speed aviation catering lines in Europe, while India presents the steepest growth trajectory as FSSAI-mandated food safety upgrades reshape institutional catering infrastructure.
Germany
Centralized food production hubs serving Lufthansa and international airline networks drive demand for continuous-motion rotary sealers with predictive maintenance capabilities. The EU Packaging and Packaging Waste Regulation's recyclability mandates are accelerating retrofit cycles for paperboard-compatible sealing heads. Frankfurt and Munich anchor the continent's most intensive sealing equipment deployment, with 24/7 commissary operations forcing vendor qualification criteria toward electromechanical reliability.
United States
FAA safety culture protocols and centralized kitchen consolidation among major carriers are reshaping procurement toward equipment-as-a-service models with third-party technical service qualification. FDA food contact substance notification timelines extend equipment qualification cycles by 18-24 months for novel lidding chemistries. Chicago and Dallas-Fort Worth metropolitan areas concentrate the densest aviation catering infrastructure, with cloud-native sealing line controllers gaining adoption despite legacy MES integration friction.
India
FSSAI-mandated food safety upgrades in institutional catering are creating first-mover openings for semi-automatic tray sealing systems as regional operators transition from manual processes. The country's national food safety regulator is tightening hygiene protocols across mid-scale catering operations and meal-kit assembly facilities. Mumbai and Bangalore clusters are absorbing the bulk of capital deployment as subscription-based meal services penetrate suburban markets.
Switzerland
Premium cabin service operations for Swiss International Air Lines and luxury hospitality groups are driving adoption of ultrasonic cold-seal systems that preserve nutritional integrity in temperature-sensitive meal applications. Swissmedic-equivalent food safety oversight maintains stringent equipment validation requirements. Zurich and Geneva aviation catering networks are compressing the addressable market for conventional thermal impulse sealers in first-class and business-class segments.
Singapore
Changi Airport's status as a major aviation hub is concentrating demand for high-throughput sealing lines capable of serving multiple airline clients with rapid format changeover. The city-state's food safety authority enforces rigorous equipment hygiene standards that favor modular systems with clean-in-place capabilities. The Seletar aerospace corridor hosts Southeast Asia's most sophisticated centralized commissary infrastructure, with cloud-based parameter control enabling multi-site synchronization across distributed production lines.
Meal Tray Sealing Machines Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with aviation catering networks favoring integrated service contracts while institutional operators separate hardware procurement from maintenance logistics. The vendor base organizes into three tiers: precision-engineering specialists serving high-speed continuous operations, modular-system fabricators targeting batch-flexible environments, and regional assemblers competing on initial capex thresholds. Consolidation pressure is intensifying through strategic partnerships between sealing equipment manufacturers and lidding film suppliers, while technology licensing agreements are accelerating cloud-native control platform deployment.
Among European precision-engineering specialists, MULTIVAC and Omori Machinery Co. Ltd. exemplify archetypes that anchor competitive positioning through global service infrastructure and high-speed aviation catering specialization respectively. Proseal America Inc. occupies a position within the modular-system tier, representing the North American configuration where upgradeable sealing heads address capital-constrained operators. These three entities collectively illustrate how geographic origin and corporate structure shape strategic emphasis across the installed base.
| Leading Market Players |
|---|
| Packaging Automation Ltd. |
| Omori Machinery Co. Ltd. |
| MULTIVAC |
| Proseal America Inc. |
| ISHIDA CO. LTD. |
| Ilpra S.p.A. |
| Webomatic |
| ProMach, Inc. |
| Heat Seal Co. |
| Others |
Supply & Pricing Matrix
Electromechanical technician scarcity in Western European aviation hubs widens pricing-tier spreads between premium predictive-maintenance systems and baseline sealing equipment. Labor-cost differentials between Germany's centralized commissaries and India's emerging institutional catering sector compress margin structures for mid-tier vendors serving price-sensitive regional operators.
Pricing Analysis
Capacity additions in India's mid-scale catering sector are reshaping price floors for semi-automatic tray sealing systems. Three-tier pricing structure across premium rotary sealers, standard intermittent-motion units, and economy manual configurations stratifies by predictive maintenance bundling and FDA food contact substance notification support. Cost compression in stainless steel and precision pneumatic components is intensifying because of alloy price volatility. Regional meal-kit assembly facilities in India exhibit highest price sensitivity, while German aviation networks prioritize electromechanical reliability over initial capex thresholds.
Supply Chain Analysis
Freight cost escalation for food-grade stainless steel and high-cycle pneumatic actuators is redrawing supplier geography preferences. Precision component manufacturing concentrates in Germany, Japan, and South Korea. Sealing equipment production draws from servo motor assemblies, vacuum pump modules, and IoT-enabled control systems. Single-source vulnerability in fluorine-free barrier coating formulations for lidding films persists as REACH restrictions force rapid material transitions. Distribution runs through OEM-direct channels for aviation catering networks and third-party technical service providers for institutional operators in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as aviation catering networks consolidate production into centralized commissaries demanding 24/7 continuous operation cycles. Specification premiums are concentrating in predictive maintenance architectures and cloud-native control platforms.
For Market Incumbents: Cement recurring revenue lock-in through preventive maintenance contract unbundling and remote monitoring subscription expansion. Deepen backward integration into lidding film formulation partnerships to capture compliance-driven retrofit cycles. Electromechanical technician scarcity in Western European hubs threatens service response times; automated diagnostic modules offset this constraint.
For New Entrants and Emerging Players: Enter via India's FSSAI-mandated food safety upgrade wave targeting semi-automatic tray sealing systems for mid-scale institutional catering. White-space concentration exists in regional meal-kit assembly facilities transitioning from manual processes. Cloud-based deployment models with localized parameter control offer differentiated go-to-market positioning against legacy on-premise vendors.
For Investors and Strategic Acquirers: Food manufacturers with captive aviation catering divisions are the most active acquirer in this space, seeking integrated sealing-film-equipment capabilities. Long-term viability hinges on paperboard-compatible sealing technology portfolios as EU Packaging and Packaging Waste Regulation deadlines approach. Monitor REACH implementation timelines for fluorine-free barrier coatings as inflection indicator for retrofit demand velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Cloud-native architectures enable centralized parameter control across MULTIVAC's global installed base. |
| Paperboard-Compatible Sealing Head Retrofit | EU recyclability mandates accelerate R&D investment toward fiber-based tray handling modules. |
| Ultrasonic Cold-Seal Technology Adoption | Swiss and Singaporean aviation caterers preserve nutritional integrity in premium cabin segments. |
| Third-Party Technical Service Qualification | FAA safety culture protocols in the United States fragment vendor revenue through maintenance unbundling. |
| Extended Producer Responsibility Compliance | Germany's packaging licensing reforms subsidize equipment upgrades demonstrating film waste reduction. |
Research Methodology
Multiple input streams — primary interviews with aviation catering operations directors, electromechanical maintenance heads, and food manufacturing procurement leads; secondary validation through FDA food contact substance notification databases, EFSA guidance documents, and EU Packaging and Packaging Waste Regulation implementation trackers; plus customs and trade flow records for sealing equipment imports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, deployment model, packaging material, and end-user workflow dimensions anchored volume and value modeling throughout the forecast period. CAGRs were derived from segment-level growth trajectory analysis incorporating aviation catering automation intensity, regulatory compliance retrofit cycles, and cloud-based platform adoption curves. Forecast inputs included centralized commissary consolidation patterns and REACH restriction implementation timelines.
Inputs from regulatory filing databases and equipment vendor service contract disclosures were available through the study window; gaps in real-time lidding film formulation cost data introduce uncertainty bands around paperboard-compatible system penetration assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Global Blow Molding Machine Market
Packaging Machinery
Carton Folding and Gluing Machine Market
Packaging Machinery
Global Pet Stretch Blow Molding Machines Market
Packaging Machinery
Foil Embossing Machine Market
Packaging Machinery
Pick Fill Seal Machines Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Orbital Wrapping Machine Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
Liquid Pouch Filling and Sealing Machine Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Lamination Systems Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Vial Filling and Capping Machines Market