
 Pine Bark Extract Market | 2026-2036
Pine Bark Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Pine Bark Extract Market Analysis
Direct-to-practitioner distribution is rewriting access patterns for pine bark extract in professional health channels. Horphag Research leverages its Pycnogenol trademark strength to sustain premium positioning among clinicians. Lonza Group anchors pharmaceutical-grade supply through its botanical extraction infrastructure. Nutraceutical Corporation competes on volume scale in private-label standardized extract production.
Pine bark extract comprises oligomeric proanthocyanidins, phenolic acids and flavonoids concentrated through aqueous or hydro-alcoholic extraction of Pinus pinaster or Pinus massoniana bark, serving primarily as an antioxidant active in human health applications. Standardized extract commands the dominant margin pool due to clinical substantiation requirements, while liquid formats grow fastest in functional beverage integration. Pharmaceutical applications retain the highest regulatory barrier but offer the longest contract durations.
EMA guidelines on herbal medicinal products and FDA dietary supplement cGMPs shape extraction purity benchmarks and batch consistency protocols for cross-border commerce. REACH compliance in Europe and EPA biomass sourcing rules in the United States further constrain raw material procurement flexibility. Stakeholders must monitor evolving polyphenol measurement standards and adapt validation protocols before regulatory divergence hardens into market access friction.
Market Dynamics
EU Nutrition and Health Claims Regulation tightening is forcing dietary supplement manufacturers to rebuild substantiation dossiers for polyphenol-based antioxidant positioning, compressing formulation timelines and raising clinical validation costs across European supply chains.
Growth Catalysts
- Antioxidant formulation demand:Dietary supplement manufacturers in France and Germany are expanding procurement of maritime pine bark derivatives for cardiovascular and cognitive health products.
- REACH compliance infrastructure:ECHA registration requirements for botanical extracts have created a moat favoring established European processors with validated supply chains.
- Landes forest cluster concentration:Raw material sourcing around Bordeaux-area processing infrastructure secures year-round bark availability for aqueous extraction facilities.
Market Restraints
- Raw material geographic concentration:Pinus pinaster bark supply concentrates in southwestern France coastal forests, exposing processors to climate and harvest variability.
- Polyphenol measurement standard divergence:Lack of harmonized oligomeric proanthocyanidin quantification methods between EFSA and FDA creates cross-border batch rejection risk.
- Hydro-alcoholic extraction cost structure:Ethanol recovery and solvent handling compliance add fixed cost layers that squeeze margin at smaller batch scales.
Strategic Opportunities
- Functional beverage integration:Liquid extract formats are penetrating sports nutrition and ready-to-drink wellness categories in Germany and the Netherlands.
- Pharmaceutical-grade contract manufacturing:EMA herbal medicinal product guidelines create demand for GMP-certified extraction capacity serving long-duration supply agreements.
- Direct-to-practitioner channel development:Clinician-focused distribution bypasses retail margin stacking for premium standardized extracts in France and Switzerland.
Industry Challenges
- Clinical validation talent scarcity:Polyphenol bioavailability study design expertise sits with a limited pool of contract research organizations in France and Italy.
- Batch-to-batch standardization complexity:Seasonal bark composition variation demands real-time process analytical technology investment that mid-scale extractors struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pine Bark Extract Market |
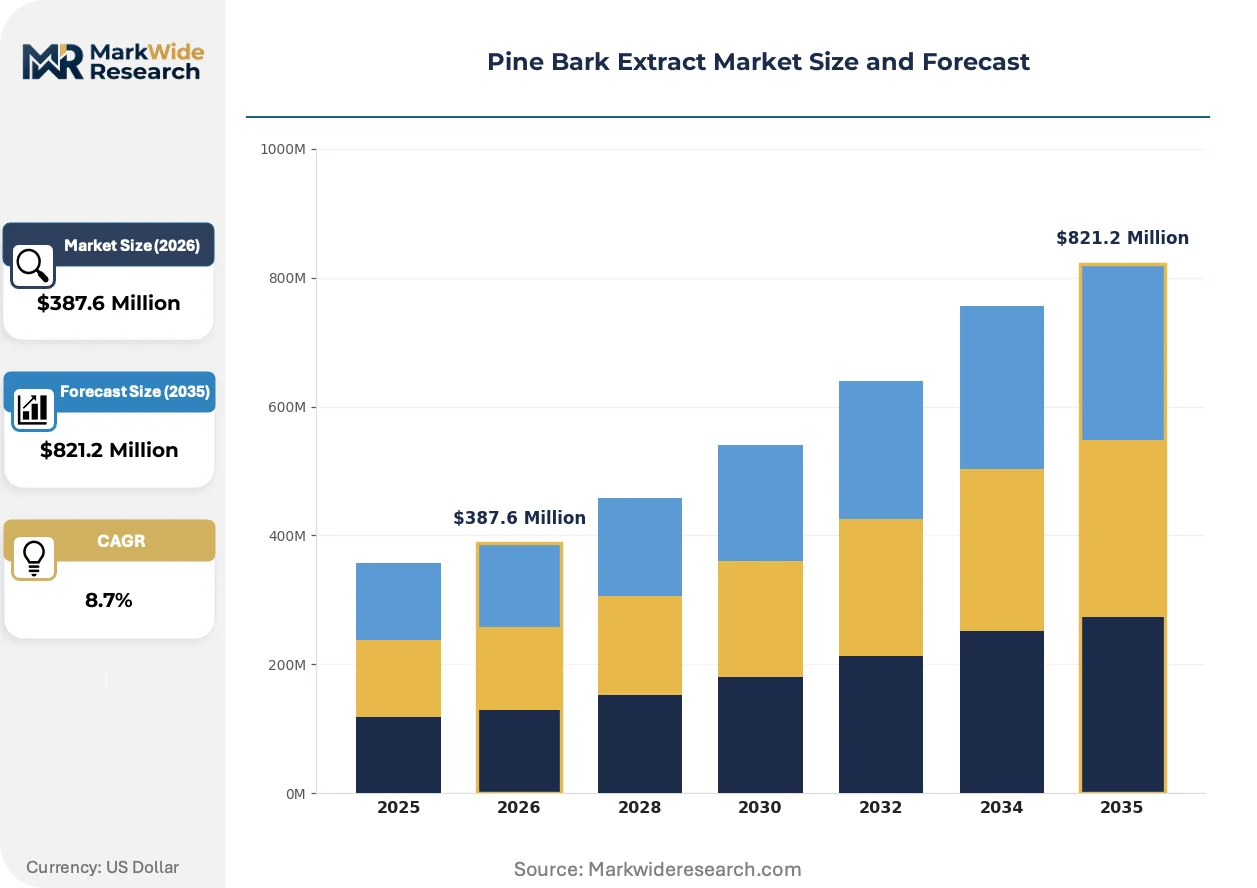
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standardized Extract, Powder, Liquid, Capsules Application: Dietary Supplements, Cosmetics, Pharmaceuticals, Functional Foods End User: Healthcare Providers, Retail Consumers, Beauty Industry, Nutraceutical Companies Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Naturex SA, Lonza Group, Horphag Research, Groupe Berkem, Givaudan, BASF SE, Kemin Industries, Nutraceutical Corporation, Indena S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pine Bark Extract Market Emerging Trajectories
Extraction technology maturation and regulatory substantiation requirements are reshaping competitive advantage toward processors with integrated quality infrastructure and clinical evidence portfolios.
Subcritical water extraction is collapsing the traditional solvent recovery cost structure for polyphenol concentration. German botanical processors are retrofitting extraction lines with pressurized hot water systems to eliminate ethanol handling permits. This technology compression is enabling smaller batch pharmaceutical-grade production without captive solvent infrastructure.
REACH authorization timelines for novel extraction solvents are extending qualification cycles for hydro-alcoholic alternatives. ECHA's 2024 substance evaluation work program prioritizes botanical processing aids, forcing extractors to lock in supply agreements for registered solvents. French and Spanish facilities face the tightest compliance windows for existing capacity.
Practitioner channel preference is fragmenting procurement authority away from centralized supplement retailers. Clinician networks in France and Belgium are consolidating buying power through group purchasing organizations that demand certificate-of-analysis transparency. This channel rotation favors extractors with dedicated medical affairs support and published pharmacokinetic data.
Pine Bark Extract Market Segmentation
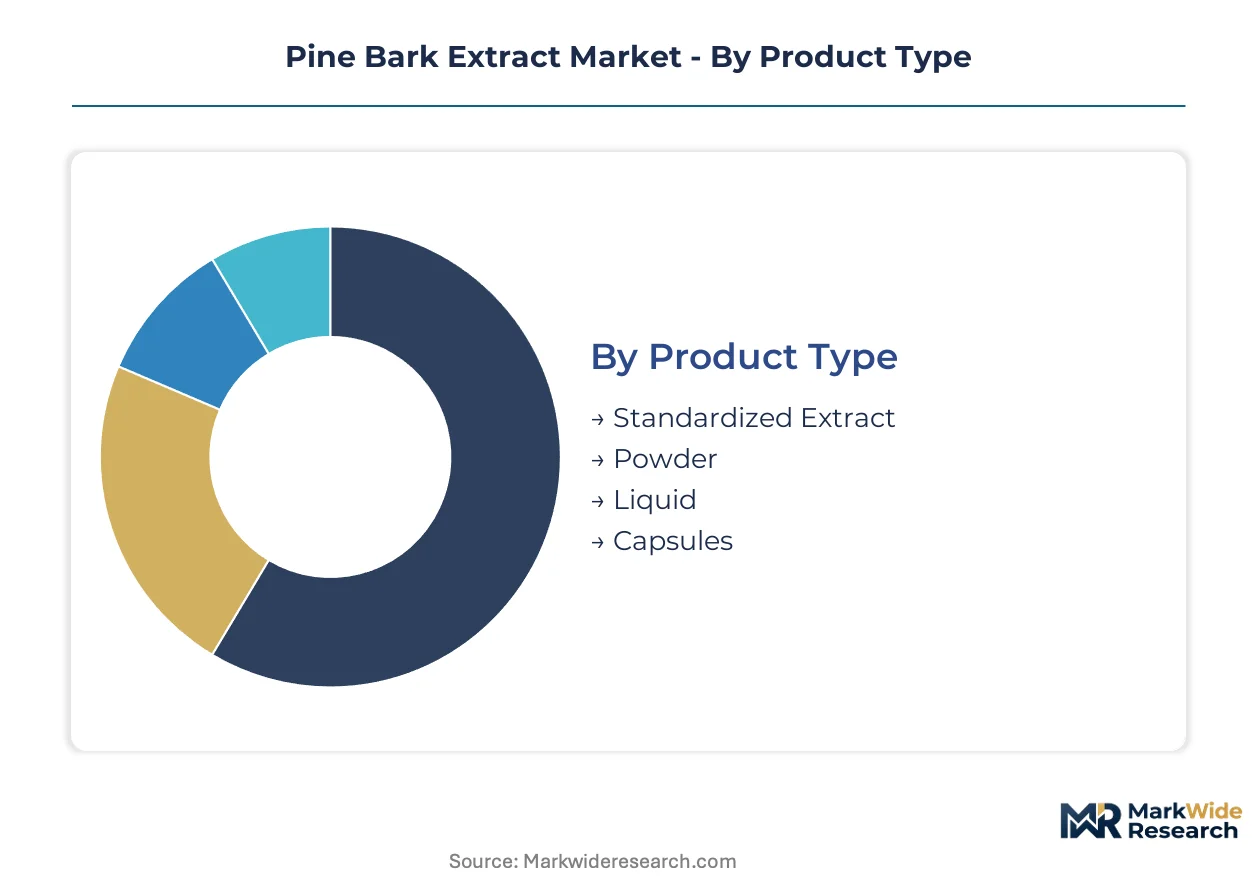
Pine bark extract segmentation reflects divergent purity requirements across pharmaceutical, nutraceutical, and cosmetic value chains. Standardization levels and format suitability determine margin capture and regulatory pathway complexity for processors.
Product Type:
Mature formats dominate current revenue while emerging extraction technologies reshape cost structures for liquid derivatives.
- Standardized Extract:Oligomeric proanthocyanidin content fixed between 65-95% through validated aqueous or hydro-alcoholic processing. Clinical dossier requirements for EMA herbal medicinal product registration concentrate demand among French and Swiss pharmaceutical contract manufacturers seeking batch-to-batch consistency.
- Liquid:Hydro-alcoholic or glycerin-based solutions with lower OPC concentration but superior bioavailability for functional beverage integration. German sports nutrition brands and Dutch ready-to-drink wellness producers are expanding procurement of liquid formats for rapid absorption positioning.
- Powder:Spray-dried extracts for bulk formulation flexibility in private-label supplement manufacturing.
- Capsules:Pre-dosed solid dosage forms serving retail consumer convenience preferences in North American and European mass-market channels.
Standardized extract retains volume leadership; liquid holds the steepest expansion curve.
Application:
Cost tier stratification separates high-validation pharmaceutical contracts from lower-barrier cosmetic and food integrations.
- Dietary Supplements:Antioxidant capsules and tablets targeting cardiovascular and cognitive health positioning. Manufacturers in France and Germany face compressed formulation timelines as EFSA tightens polyphenol health claim substantiation under the EU Nutrition and Health Claims Regulation.
- Pharmaceuticals:EMA-compliant herbal medicinal products requiring GMP-certified extraction, full pharmacokinetic profiling, and multi-year stability data. Long contract durations and highest regulatory barriers create sustained demand for Bordeaux-area processing infrastructure with validated supply chains.
- Cosmetics:Topical antioxidant serums and anti-aging formulations leveraging maritime pine bark photoprotective properties.
- Functional Foods:Fortified beverages and nutrition bars with lower OPC dosing thresholds and reduced clinical validation burdens.
Dietary supplements command current volume; pharmaceuticals maintain the premium margin tier.
End User:
Customer type fragmentation is rotating procurement authority toward clinician networks and away from centralized retail.
- Healthcare Providers:Direct-to-practitioner distribution of premium standardized extracts for integrative medicine protocols. French and Belgian clinician group purchasing organizations now demand certificate-of-analysis transparency and published pharmacokinetic data, favoring extractors with dedicated medical affairs support.
- Nutraceutical Companies:Volume-scale procurement for private-label antioxidant formulations across European and North American retail channels.
- Retail Consumers:Mass-market supplement purchasers through pharmacy and online channels with price-sensitive quality expectations.
- Beauty Industry:Cosmetic formulators sourcing lower-concentration extracts for topical antioxidant positioning.
Healthcare providers represent the fastest-growing procurement channel; nutraceutical companies retain aggregate volume dominance.
Distribution Channel:
Geography of demand concentration shapes channel investment priorities for extractors seeking margin protection.
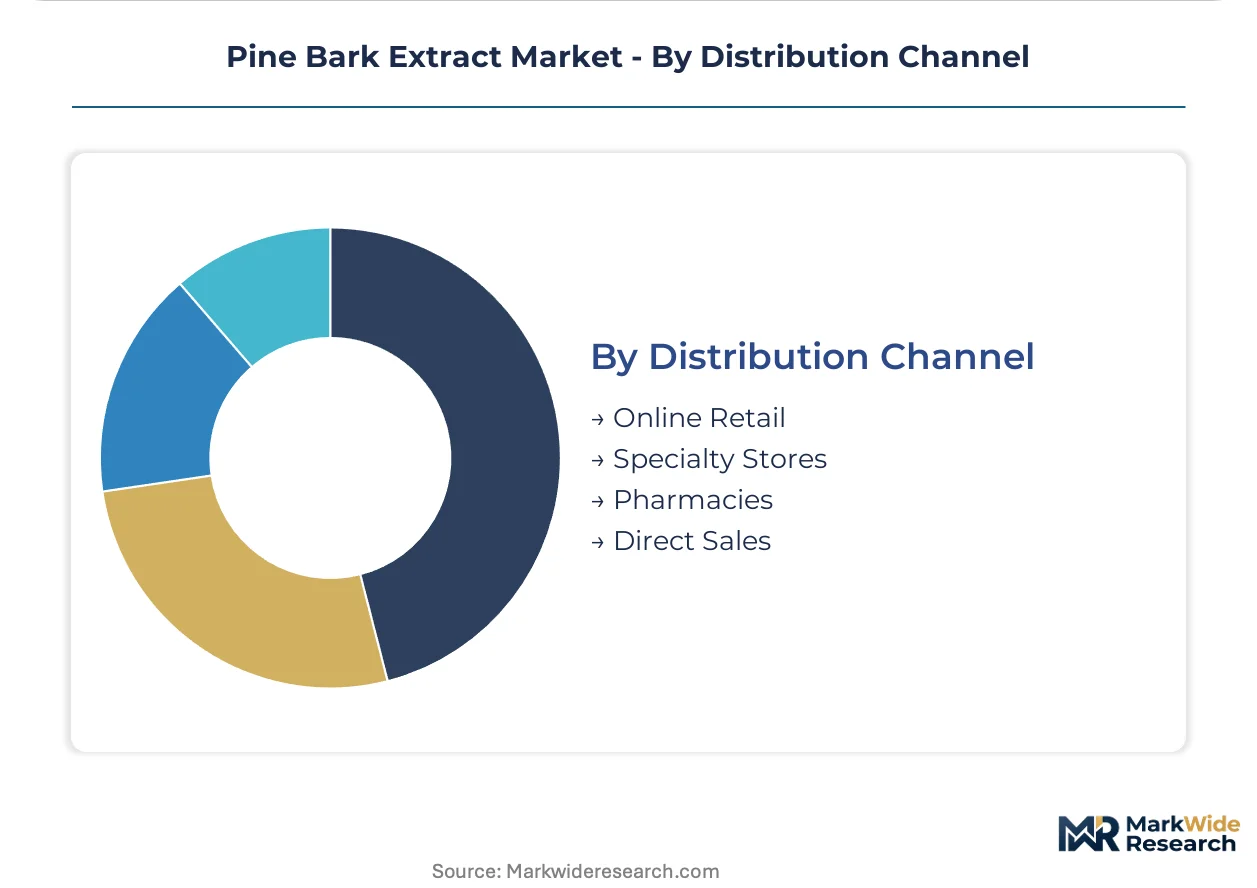
- Online Retail:Direct-to-consumer platforms capturing supplement and cosmetic sales with compressed margin stacking. German and Dutch consumers demonstrate highest e-commerce penetration for pine bark derivative procurement.
- Pharmacies:Regulated point-of-sale for EMA-registered herbal medicinal products with pharmacist consultation requirements.
- Specialty Stores:Health food and sports nutrition retailers serving enthusiast consumers with formulation transparency demands.
- Direct Sales:Practitioner-channel distribution bypassing retail markup for clinical-grade standardized extracts in France and Switzerland.
Pharmacies anchor regulated product volume; online retail is gaining share fastest in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bordeaux-Paris rail freight corridor and Port of Bordeaux container terminal anchor European pine bark extract logistics, enabling year-round maritime pine bark movement from Landes forest harvest zones to aqueous extraction facilities.
France
Dietary supplement manufacturers in Nouvelle-Aquitaine expand procurement for cardiovascular formulations. EFSA polyphenol health claim substantiation requirements under EU Nutrition and Health Claims Regulation compress formulation timelines. The Landes forest supply cluster around Bordeaux secures raw material flow to aqueous extraction plants.
Germany
Sports nutrition brands and ready-to-drink wellness producers drive liquid extract procurement. ECHA REACH registration requirements for botanical extracts favor established processors with validated supply chains. Bavaria-based extraction facilities retrofit lines with pressurized hot water systems to eliminate ethanol handling permits.
Switzerland
Clinician group purchasing organizations consolidate buying power for premium standardized extracts. Swissmedic herbal medicinal product guidelines demand GMP-certified extraction and full pharmacokinetic profiling. Zurich-area medical affairs teams serve direct-to-practitioner distribution channels.
United States
Dietary supplement manufacturers expand antioxidant formulation production for cognitive health positioning. FDA dietary supplement cGMPs shape extraction purity benchmarks and batch consistency protocols. EPA biomass sourcing rules constrain raw material procurement flexibility for coastal processors.
Italy
Contract research organizations concentrate polyphenol bioavailability study design expertise for clinical validation dossiers. EMA herbal medicinal product guidelines create demand for long-duration supply agreements. Piedmont-based extraction facilities face tightening REACH authorization timelines for novel processing solvents.
Pine Bark Extract Market Vendor Landscape
On the supply side, the industry is consolidating around processors with integrated quality infrastructure and clinical evidence portfolios. Three archetypes dominate: trademark-holding specialists commanding premium positioning, pharmaceutical-grade contract manufacturers anchoring long-term supply agreements, and volume-scale private-label producers competing on batch scale. Competitive moves concentrate on capacity expansion in GMP-certified extraction and strategic partnerships for functional beverage integration.
Within the trademark-specialist tier, Horphag Research occupies a position exemplifying premium clinician-channel positioning. Lonza Group and Nutraceutical Corporation represent divergent scale vectors, with the former anchoring pharmaceutical-grade supply through botanical extraction infrastructure and the latter exemplifying volume-scale private-label standardized extract production.
| Leading Market Players |
|---|
| Naturex SA |
| Lonza Group |
| Horphag Research |
| Groupe Berkem |
| Givaudan |
| BASF SE |
| Kemin Industries |
| Nutraceutical Corporation |
| Indena S.p.A. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Landes forest Pinus pinaster bark determines both three-tier pricing spreads and supply chain configuration. EFSA health claim substantiation requirements compress margin capture for non-validated processors while concentrating pricing power among GMP-certified Bordeaux-area facilities.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade standardized extracts from nutraceutical mid-tier and cosmetic economy grades. Price differentiation hinges on EMA herbal medicinal product certification and batch-scale OPC consistency. Cost compression in liquid extract segments is intensifying because German sports nutrition brands demand rapid-absorption positioning at commodity-equivalent pricing. Retail consumers show highest price sensitivity; healthcare providers demonstrate lowest sensitivity due to reimbursement-adjacent procurement authority.
Supply Chain Analysis
Upstream feedstock draws from southwestern France coastal forests, with secondary sourcing from Portuguese and Spanish maritime pine plantations. Raw material dependencies center on seasonal bark harvest timing, aqueous extraction solvent availability, and spray-drying capacity. Single-source vulnerability concentrates around Bordeaux-area processing infrastructure exposed to climate-driven harvest variability. Distribution runs through direct-to-practitioner channels for clinical grades and online retail for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by EMA herbal medicinal product registration backlog clearance. Tightening EU Nutrition and Health Claims Regulation is compressing formulation timelines and accelerating consolidation around validated processors.
For Market Incumbents: Insulate margin position through backward integration into Landes forest harvesting cooperatives and captive aqueous extraction capacity. EFSA polyphenol measurement standard divergence threatens cross-border batch rejection; invest in dual-validation protocols for FDA and EMA alignment. Prioritize medical affairs team expansion to serve clinician group purchasing organizations demanding pharmacokinetic transparency.
For New Entrants and Emerging Players: Pursue functional beverage integration in German and Dutch ready-to-drink wellness categories where liquid extract demand outpaces validated supply. Subcritical water extraction technology eliminates ethanol handling permits and enables smaller-batch pharmaceutical-grade entry. Target sports nutrition brands with rapid-absorption positioning and certificate-of-analysis transparency.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors processors with integrated GMP-certified extraction and clinical evidence portfolios. Long-term viability rests on EMA registration moats and REACH-compliant solvent infrastructure. Acquisition target archetype: mid-scale Bordeaux-area extractors with validated supply chains and underutilized pressurized hot water capacity. Watch ECHA substance evaluation timelines for novel extraction solvents as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Landes forest harvesting cooperative agreements secure year-round bark availability for aqueous extraction. |
| GMP-Certified Extraction Capacity Expansion | EMA herbal medicinal product guidelines create sustained demand for validated Bordeaux-area processing infrastructure. |
| Subcritical Water Extraction Retrofit | Pressurized hot water systems eliminate ethanol handling permits and collapse solvent recovery cost structures. |
| Direct-to-Practitioner Channel Development | Clinician group purchasing organizations in France and Switzerland demand certificate-of-analysis transparency. |
| Dual-Validation Protocol Investment | Harmonized EFSA-FDA oligomeric proanthocyanidin quantification methods reduce cross-border batch rejection risk. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs and secondary validation layers. Stakeholder roles included dietary supplement formulation directors, GMP-certified extraction facility managers, clinician group purchasing organization contracts managers, EMA regulatory affairs specialists, and sports nutrition brand procurement leads. Secondary sources comprised EFSA health claim substantiation dossiers, EMA herbal medicinal product registration databases, REACH authorization timelines, and customs trade flow records for maritime pine bark derivatives. Bottom-up volume modeling and top-down value reconciliation ensured cross-verification.
Calibration against historical EMA registration completion rates and seasonal bark harvest yields anchored projection reliability. Segmentation dimensions spanned product type, application tier, end-user channel, and distribution geography. CAGRs were derived from regression analysis of procurement volume trends and pricing trajectory patterns. Forecast inputs incorporated ECHA solvent evaluation timelines and clinician network expansion rates.
Sensitivities concentrate around EFSA-FDA measurement standard harmonization outcomes and REACH authorization delays for novel extraction solvents. Forecasts reflect documented assumptions on regulatory timeline stability and raw material harvest consistency. Cross-checking against EMA herbal medicinal product registration pipeline data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
Global Paprika Oleoresin Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Natural Food Colors and Flavors Market
Flavorings and Food Additives
Middle East Food Premix Market
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Flavor Emulsions Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market