
 India Sealants Market | 2026-2036
India Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
India Sealants Market Foresight
Multi-sourced procurement of specialty polymers and curing agents is decoupling from the traditional single-supplier model that dominated India's sealant value chain. Pidilite Industries Limited leverages its deep distribution network across tier-2 and tier-3 cities to sustain volume leadership in consumer-grade construction sealants. Henkel AG & Co. KGaA competes through technology leadership in high-performance automotive and electronics-grade formulations. Sika AG anchors its position with specialized waterproofing and structural bonding solutions for infrastructure megaprojects.
India sealants are viscoelastic materials formulated from silicone, polyurethane, acrylic, or polysulfide bases that cure through moisture, heat, or chemical reaction to form impermeable bonds with elongation capacities typically exceeding 200%. Their primary industrial purpose spans adhesion, waterproofing, insulation, and soundproofing across load-bearing joints, glazing systems, and electronic enclosures where thermal cycling and chemical exposure demand elastic recovery. Silicone formulations lead the product type landscape due to superior UV resistance and temperature stability in building facades and solar installations. Polyurethane segments capture expanding share in automotive underbody sealing and flexible construction joints where toughness and paintability matter. The construction end user category remains the dominant demand pool, though electronics applications in semiconductor packaging and consumer device assembly represent the fastest-growing margin segment.
BIS mandates compliance with IS 15477 for silicone sealants and IS 15476 for polyurethane variants, creating a compliance barrier that shapes product development budgets and certification timelines for both domestic manufacturers and importers. CDSCO oversight intersects where medical-grade sealants enter device assemblies, adding biocompatibility testing requirements that filter supplier eligibility. The CEA's building energy codes and state-level green building directives in Maharashtra and Tamil Nadu are pushing low-VOC and energy-efficient formulations into specification sheets. Stakeholders must monitor how BIS harmonization with ISO 11600 standards proceeds, as this will determine whether domestic producers can substitute imported high-performance grades or cede that tier to established multinationals.
Market Dynamics
BIS certification tightening for silicone and polyurethane sealants is forcing domestic manufacturers to restructure R&D budgets and certification timelines, compressing margins for uncertified suppliers while elevating compliant producers into specification-grade project pipelines.
Growth Catalysts
- Metro Rail Expansion:Mumbai, Bengaluru and Hyderabad metro corporations are specifying structural silicone glazing for station envelopes, pulling high-performance formulations into public infrastructure procurement cycles.
- IS 15477 Compliance Mandate:BIS certification requirements for silicone sealants in building facades are filtering uncertified imports from Gujarat and Maharashtra construction tenders, protecting qualified domestic supply.
- Solar Installation Surge:Rajasthan and Gujarat solar parks are specifying UV-stable silicone for module frame bonding and junction box sealing, creating sustained pull for temperature-resistant grades.
Market Restraints
- Specialty Polymer Import Dependence:Silane-terminated polyethers and tin catalysts concentrate in German and Japanese supplier networks, exposing Indian formulators to freight cost volatility and forex risk.
- Curing Agent Bottlenecks:Moisture-cure tin catalysts face supply concentration among three global chemical houses, creating input cost instability for polyurethane sealant producers.
- Acrylic Substitution Pressure:Water-based acrylic caulks are capturing interior residential share where elasticity requirements fall below 150%, compressing silicone volume in tier-3 housing.
Strategic Opportunities
- Semiconductor Packaging:Tamil Nadu and Karnataka electronics manufacturing clusters are qualifying thermally conductive silicone gels for chip underfill applications, opening margin-rich supply contracts.
- Green Building Directives:Maharashtra's state-level low-VOC mandates for commercial construction are pushing water-based and solvent-free formulations into specification sheets ahead of national adoption.
- E-commerce Distribution:Pidilite and regional distributors are building direct-to-contractor digital channels for standard-grade construction sealants, bypassing traditional hardware retail markups in tier-2 cities.
Industry Challenges
- Formulation Chemist Scarcity:Indian technical institutes produce limited polymer chemistry specialists with sealant-specific rheology and adhesion science training, constraining domestic innovation pipelines.
- Certification Timeline Compression:BIS testing cycles for new silicone formulations extend 14-18 months, delaying product launches and locking working capital in pre-revenue R&D phases.
- Legacy Equipment Retrofit Costs:Batch mixing and extrusion lines built for solvent-based systems require capital-intensive modification to handle moisture-cure silicones with atmospheric sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Sealants Market |
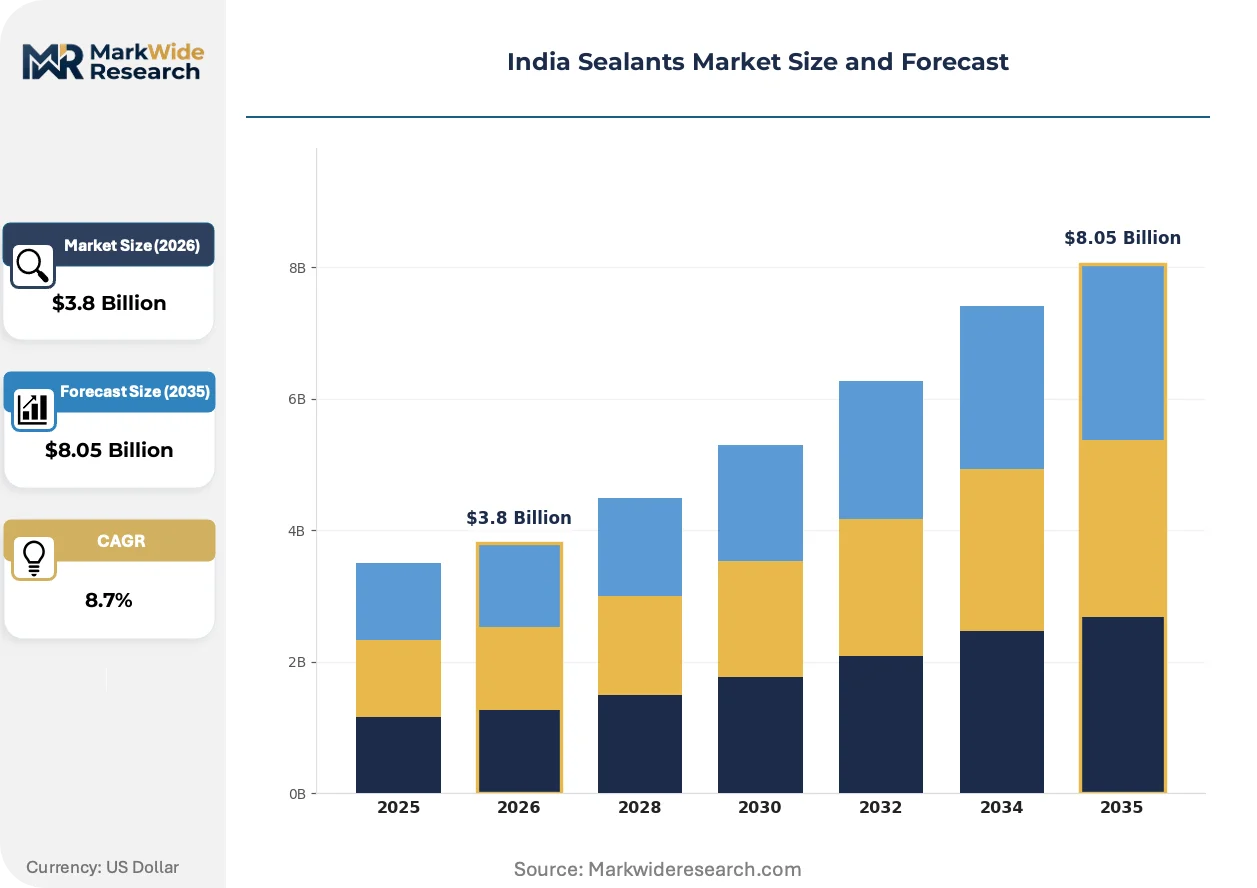
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylic, Polysulfide End User: Construction, Automotive, Aerospace, Electronics Application: Adhesives, Waterproofing, Insulation, Soundproofing Form: Cylindrical, Cartridge, Tube, Bulk |
| Companies Covered | 3M, Arkema AG, Pidilite Industries Limited, Ashland, BASF SE, Henkel AG & Co. KGaA, H.B. Fuller Company, MAPEI S.p.A., Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Sealants Market Shifts & Advancements
Formulation chemistry and procurement architecture are converging to reshape competitive position in India's sealant value chain, with sustainability mandates and electronics-grade specifications driving technical differentiation.
Hybrid silicone-polyurethane polymers are integrating the UV stability of siloxane backbones with polyurethane toughness for automotive underbody and structural glazing applications. Tier-1 automotive suppliers in Chennai and Pune are qualifying these grades for paint-line compatibility and acoustic damping. This convergence is integrating mid-tier formulators into OEM supply chains previously reserved for imported specialty grades.
BIS harmonization with ISO 11600 standards is compressing the performance gap between domestic silicone sealants and established multinational imports. The standards body is aligning movement capability classifications and modulus specifications with global benchmarks, forcing domestic producers to elevate testing infrastructure. Western and southern Indian manufacturers with existing ISO 9001 quality systems are responding fastest, capturing early-mover advantage in institutional project specifications.
Project developers in Gujarat and Maharashtra are consolidating procurement around certified master distributors who bundle technical specification support with logistics coordination. Large residential developers are displacing fragmented local hardware sourcing with annual framework agreements covering silicone, polyurethane and acrylic grades across multiple project sites. This concentration is most visible in Ahmedabad and Mumbai high-rise construction, where single-source supply reduces specification risk and warranty complexity.
India Sealants Market Segmentation
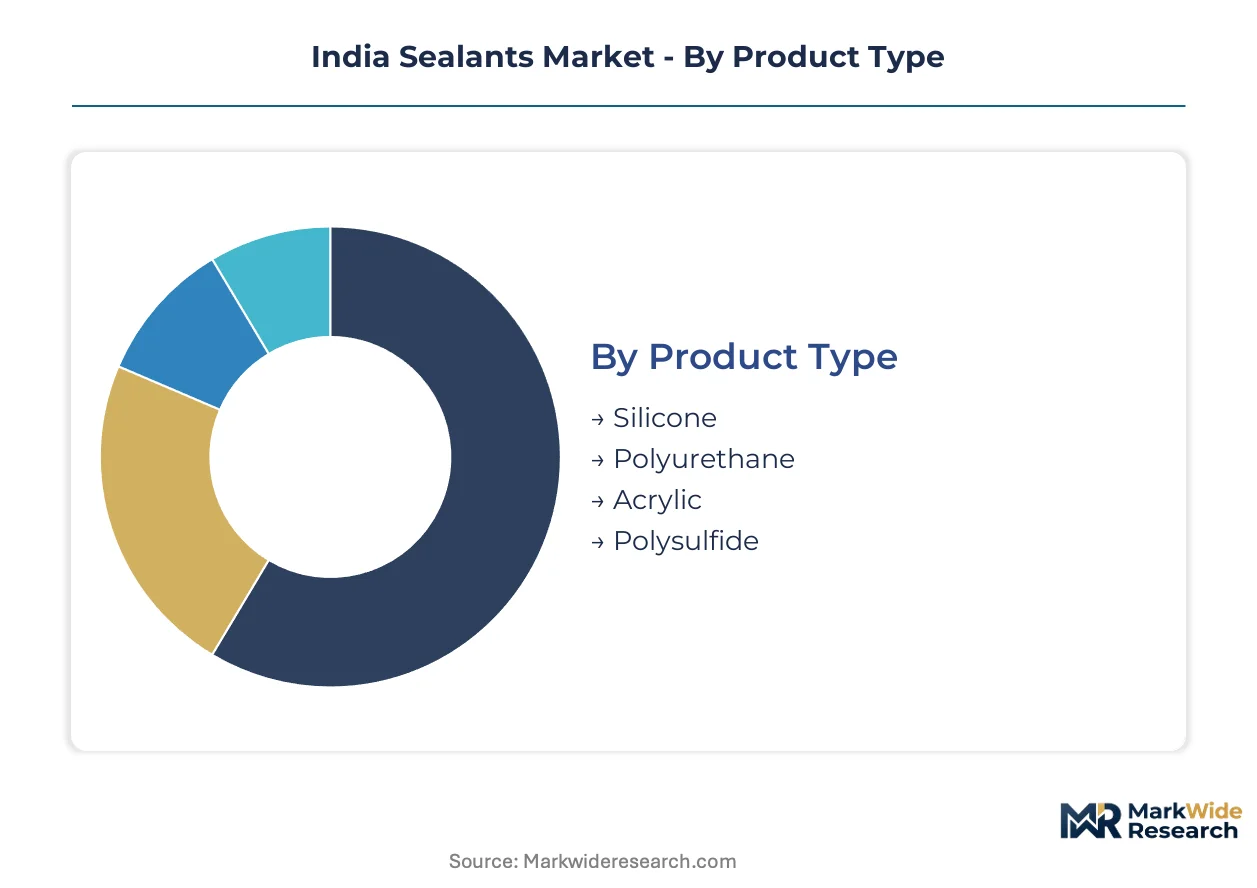
India's sealants market fragments across formulation chemistry, end-use intensity, and packaging economics that dictate procurement patterns. Each segmentation axis reveals distinct margin structures and certification barriers that shape supplier positioning in western and southern industrial corridors.
Product Type:
Replacement cycles for sealant formulations are shortening as BIS compliance deadlines force upgrades from uncertified legacy grades to specification-compliant alternatives.
- Silicone:Siloxane backbone formulations cure through atmospheric moisture to deliver UV-stable elastic bonds with movement capability exceeding 25%. Demand concentrates in Gujarat and Maharashtra high-rise glazing where IS 15477 certification filters tenders toward qualified suppliers.
- Polyurethane:Isocyanate-terminated prepolymers crosslink with atmospheric moisture to form paint-compatible elastomers with superior toughness and abrasion resistance. Automotive underbody sealing in Chennai and Pune clusters pulls solvent-free grades as OEMs tighten VOC specifications.
- Acrylic:Water-based emulsion caulks deliver cost-effective interior sealing where elongation requirements stay below 150%, capturing tier-3 residential volume through hardware retail channels.
- Polysulfide:Liquid polymer grades formulated with manganese dioxide curing agents provide fuel-resistant sealing for jointing applications in chemical processing infrastructure.
Volume placements concentrate in Silicone; the faster expansion belongs to Polyurethane as automotive specification requirements tighten.
End User:
Cost tier segmentation separates specification-grade institutional buyers from price-sensitive residential contractors.
- Construction:Load-bearing joint sealing, structural glazing, and waterproofing dominate absolute consumption across high-rise residential and metro rail infrastructure in Mumbai, Bengaluru, and Hyderabad.
- Automotive:Underbody sealing, seam sealing, and direct glazing applications in Chennai and Pune assembly plants specify paint-compatible formulations with acoustic damping properties.
- Aerospace:Fuel tank sealing and cabin pressure boundary applications demand polysulfide and fluorosilicone grades certified to MIL-SPEC standards for maintenance, repair, and overhaul operations.
- Electronics:Thermally conductive silicone gels for semiconductor packaging in Tamil Nadu and Karnataka clusters represent the steepest expansion trajectory as chip assembly localizes.
Construction commands absolute volume; Electronics climbs fastest on semiconductor packaging localization.
Application:
Application segmentation tracks functional performance requirements that determine formulation selection and pricing bandwidth.
- Adhesives:Structural bonding applications in curtain wall systems and transportation assembly require high-modulus formulations with tensile adhesion exceeding 0.6 MPa to concrete and aluminum substrates.
- Waterproofing:Basement, podium, and terrace sealing in coastal Maharashtra and Tamil Nadu specifications demand elastomeric membranes with 400% elongation and hydrostatic pressure resistance.
- Insulation:Thermal and electrical isolation in solar module junction boxes and high-voltage switchgear specifies silicone compounds with dielectric strength above 15 kV/mm.
- Soundproofing:Acoustic damping layers in automotive floor pans and railway rolling stock utilize polyurethane foam-in-place formulations with loss factor optimization.
Waterproofing dominates project value; Adhesive applications gain share fastest on structural glazing specification.
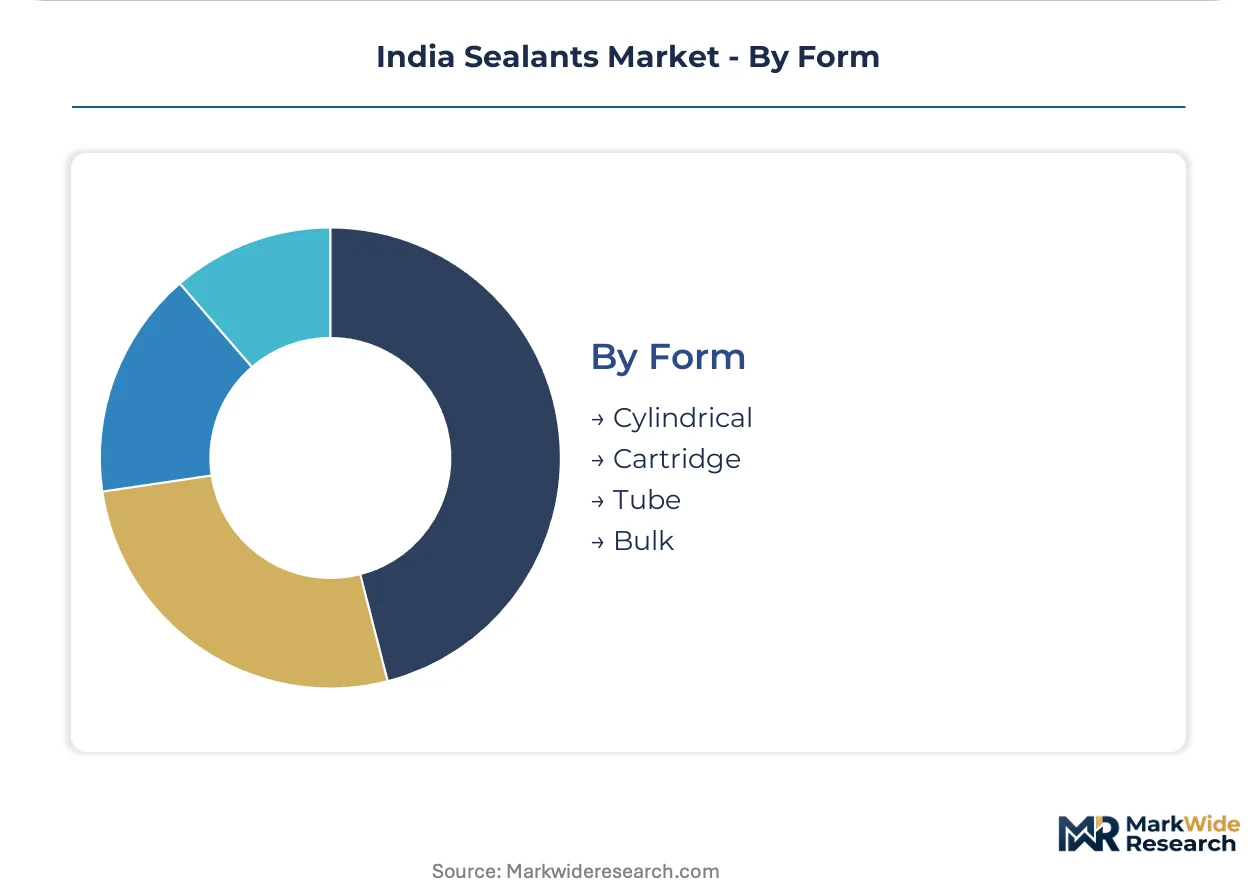
Form:
Packaging format selection hinges on application scale, equipment compatibility, and shelf-life requirements across contractor and industrial buyer segments.
- Cylindrical:Sausage-pack formats for pneumatic dispensing guns reduce packaging waste and enable continuous bead application in large-scale facade projects.
- Cartridge:Standard 300ml and 600ml cartridges serve professional applicators through hardware distribution with caulking gun compatibility.
- Tube:Small-format squeeze tubes target consumer DIY and touch-up applications through retail channels in tier-2 and tier-3 cities.
- Bulk:Drum and pail formats supply automated dispensing systems in automotive OEM plants and continuous manufacturing lines.
Cartridge formats dominate unit volume; Bulk packaging expands fastest on OEM line automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in western and southern India where industrial clustering and metro rail expansion create sustained consumption pools. Gujarat and Maharashtra construction activity pulls silicone and polyurethane formulations into high-rise residential and infrastructure projects. Karnataka and Tamil Nadu electronics manufacturing clusters are emerging as new demand centers for specialty grades.
Maharashtra
Mumbai metro corporations specify structural silicone glazing for station envelopes, pulling high-performance formulations into public infrastructure procurement cycles. The state's low-VOC mandates for commercial construction push water-based and solvent-free formulations into specification sheets ahead of national adoption. Pune automotive assembly plants specify paint-compatible polyurethane grades for underbody sealing and acoustic damping applications.
Gujarat
Ahmedabad high-rise residential developers consolidate procurement around certified master distributors who bundle technical specification support with logistics coordination. BIS certification requirements for silicone sealants in building facades filter uncertified imports from construction tenders, protecting qualified domestic supply. Solar parks in the state specify UV-stable silicone for module frame bonding and junction box sealing, creating sustained pull for temperature-resistant grades.
Karnataka
Bengaluru metro rail expansion drives structural glazing specifications for station infrastructure across multiple corridor phases. Electronics manufacturing clusters in the state qualify thermally conductive silicone gels for chip underfill applications, opening margin-rich supply contracts as semiconductor packaging localizes. The capital's high-rise residential construction specifies IS 15477-certified silicone for curtain wall systems and waterproofing membranes.
Tamil Nadu
Chennai automotive OEM plants drive demand for solvent-free polyurethane grades as manufacturers tighten VOC specifications for underbody and seam sealing. Electronics manufacturing clusters in the state are qualifying specialty silicone formulations for semiconductor packaging applications. Coastal construction specifications demand elastomeric waterproofing membranes with hydrostatic pressure resistance for basement and podium sealing.
Telangana
Hyderabad metro rail infrastructure specifies structural silicone glazing for station envelopes, integrating high-performance sealants into public procurement cycles. The state's pharmaceutical and electronics manufacturing investments create demand for cleanroom-grade and chemically resistant sealing solutions. Residential construction in the capital specifies certified silicone formulations for high-rise glazing and waterproofing applications.
India Sealants Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit batch mixing and extrusion lines to handle moisture-cure silicones with atmospheric sensitivity. The market structure organizes around three tiers: multinational chemical conglomerates with global formulation libraries, domestic specialists with deep distribution networks in tier-2 and tier-3 cities, and regional formulators serving price-sensitive construction segments. Strategic archetypes include technology leaders competing through high-performance automotive and electronics-grade formulations, volume players leveraging distribution density in consumer-grade construction sealants, and infrastructure specialists anchoring positions with waterproofing and structural bonding solutions. M&A activity and certification-driven R&D investments represent the dominant competitive moves as BIS compliance timelines compress product development cycles.
Among multinational chemical conglomerates, 3M and BASF SE occupy positions as technology leaders with global formulation capabilities. Pidilite Industries Limited exemplifies the domestic volume player archetype through its distribution network penetration. Sika AG and Henkel AG & Co. KGaA represent infrastructure and automotive specialists respectively, anchoring premium-tier positions through application-specific expertise. These named entities sit within a broader competitive set that includes Arkema AG, Ashland, H.B. Fuller Company, and MAPEI S.p.A., alongside regional formulators captured in the aggregate "Others" category.
| Leading Market Players |
|---|
| 3M |
| Arkema AG |
| Pidilite Industries Limited |
| Ashland |
| BASF SE |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| MAPEI S.p.A. |
| Sika AG |
| Others |
Supply & Pricing Matrix
Maharashtra's low-VOC mandates for commercial construction gate qualified supply and premium-tier pricing access, compressing margins for uncertified formulators while elevating compliant producers into specification-grade procurement pipelines.
Pricing Analysis
Volume placements concentrate in standard-grade silicone cartridges through hardware retail, while margin-rich electronics-grade thermally conductive gels command substantial premiums. Price differentiation separates IS 15477-certified facade grades from uncertified alternatives, with BIS compliance timelines and freight cost volatility from German and Japanese catalyst suppliers intensifying cost compression in mid-tier polyurethane segments. Residential contractors in tier-3 cities exhibit highest price sensitivity, whereas automotive OEMs in Chennai and Pune prioritize paint compatibility and acoustic performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive assembly plants and electronics manufacturing clusters, while master distributors bundle technical specification support for high-rise residential developers. Raw material dependencies center on silane-terminated polyethers and tin catalysts concentrated in German and Japanese supplier networks, with moisture-cure catalyst supply concentration among three global chemical houses creating single-source vulnerability. Distribution runs through certified master distributors in Gujarat and Maharashtra, Pidilite's tier-2 and tier-3 network, and direct digital channels for standard-grade construction sealants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as BIS certification timelines compress R&D budgets and filter uncertified suppliers from institutional procurement pipelines.
For Market Incumbents: Cement specification-grade positioning by accelerating ISO 11600 harmonization investments and capturing early-mover advantage in institutional project tenders. Deepen backward integration into specialty polymer supply through long-term offtake agreements with German and Japanese catalyst suppliers, insulating margin structures from forex volatility and freight cost spikes.
For New Entrants and Emerging Players: Tier-3 residential contractors underserved by certified distribution present the most penetrable entry point, with water-based acrylic caulks capturing interior sealing share where elasticity requirements stay below 150%. Semiconductor packaging applications in Tamil Nadu and Karnataka clusters offer white-space expansion, with thermally conductive silicone gels for chip underfill qualifying through direct technical engagement with EMS providers.
For Investors and Strategic Acquirers: BIS harmonization completion with ISO 11600 standards is the leading indicator that domestic producers can substitute imported high-performance grades or cede that tier to established multinationals. Long-term viability favors manufacturers with existing ISO 9001 quality systems and moisture-cure silicone production capabilities, with acquisition targets screening for 14-18 month certification pipeline visibility and western or southern Indian manufacturing footprints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Supply | Long-term offtake agreements with German and Japanese suppliers reduce forex exposure and input cost volatility. |
| ISO 11600 Harmonization Investment | Alignment with global benchmarks accelerates domestic substitution for imported high-performance silicone grades. |
| Direct-to-Contractor Digital Channel Buildout | Pidilite's tier-2 and tier-3 penetration demonstrates bypass potential around traditional hardware retail markups. |
| Semiconductor Packaging Qualification | Thermally conductive silicone gel approvals in Tamil Nadu and Karnataka clusters unlock margin-rich electronics supply contracts. |
| Moisture-Cure Silicone Capacity Retrofit | Batch mixing and extrusion line modification enables atmospheric-sensitive formulation production for specification-grade tenders. |
Research Methodology
Independent corroboration across formulation chemists at domestic manufacturers, procurement leads at automotive OEMs and electronics EMS providers, and distribution channel partners in western and southern India underwrites the qualitative findings. Secondary validation draws from BIS certification records, CDSCO medical device filings, customs and trade data for specialty polymer imports, and state-level green building directive documentation. Bottom-up demand modeling across construction, automotive, and electronics end-uses triangulates with top-down value chain analysis.
Rate-of-change decomposition across formulation chemistry, end-use intensity, and packaging economics segments the market into silicone, polyurethane, acrylic, and polysulfide grades; construction, automotive, aerospace, and electronics buyers; and cartridge, bulk, cylindrical, and tube formats. CAGRs derive from elasticity-adjusted consumption curves and certification-driven replacement cycle acceleration, with semiconductor packaging localization and metro rail expansion as key demand inflection inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to BIS harmonization timelines, specialty polymer import tariff shifts, and catalyst supply concentration risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Global Specialty Amines Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Thiocolchicoside Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
Silicone Potting Compounds Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Galactoarabinan Market