
 Enterprise Capture Software Market | 2026-2036
Enterprise Capture Software Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Capture Software Market Analytics
Subscription-based licensing for software-defined capture features is hardening as the dominant commercial model in enterprise deployments. Kofax leverages its installed base in high-volume scanning environments to sustain recurring revenue streams. ABBYY anchors its competitive position through specialized intelligent document processing engines that differentiate on extraction accuracy for complex layouts.
Enterprise capture software encompasses systems that digitize, classify, and extract structured data from physical and electronic documents using optical character recognition engines with throughput rates exceeding thousands of pages per hour. These platforms serve primary commercial purposes in automating document-centric workflows, reducing manual data entry, and ensuring audit-ready information governance across regulated industries. Cloud-based deployment now leads growth trajectories as organizations retire legacy on-premises infrastructure, while the BFSI end-user segment occupies the deepest margin pools due to compliance-driven refresh cycles and complex multi-channel capture requirements.
The FDA enforces 21 CFR Part 11 requirements for electronic records integrity in pharmaceutical and medical device applications, directly shaping validation protocols for capture software deployed in life sciences environments. EMA's Good Manufacturing Practice guidelines and Japan's METI data governance frameworks similarly constrain vendor design choices and create certification barriers for market access. Stakeholders must monitor evolving AI transparency obligations under the EU AI Act as automated classification and extraction capabilities attract heightened regulatory scrutiny.
Market Dynamics
Cloud migration mandates under the EU AI Act and HIPAA data portability rules are forcing enterprise buyers to retire legacy on-premises capture infrastructure and procure compliance-ready SaaS platforms.
Growth Catalysts
- HIPAA data portability enforcement:Healthcare providers in the United States must modernize patient records systems, accelerating intelligent document processing procurement for audit-ready information governance.
- EU AI Act transparency obligations:Automated classification and extraction capabilities face heightened regulatory scrutiny, compelling enterprises to upgrade to certified platforms with explainable AI features.
- Pharmaceutical validation protocols:FDA 21 CFR Part 11 requirements for electronic records integrity drive refresh cycles in life sciences environments where document integrity underpins regulatory submissions.
Market Restraints
- Specialized engineering talent scarcity:Optical character recognition engine optimization and machine learning model training for complex layouts require rare skill sets concentrated in Germany and Japan.
- Legacy system integration friction:Enterprises with decades-old document management architectures face protracted migration timelines that delay SaaS subscription conversions.
- Input cost volatility in GPU compute:Training and inference workloads for intelligent extraction models depend on NVIDIA hardware subject to supply constraints and tariff exposure.
Strategic Opportunities
- Underpenetrated Japanese healthcare digitization:METI data governance frameworks create certification barriers that favor established vendors with local compliance expertise.
- Convergence of capture and robotic process automation:Integration between document extraction engines and workflow bots enables end-to-end straight-through processing for BFSI operations.
- India's PLI scheme for IT hardware:Domestic manufacturing incentives reduce landed costs for scanning hardware bundled with software-defined capture solutions.
Industry Challenges
- EMA Good Manufacturing Practice certification timelines:Pharmaceutical capture deployments require 12-18 month validation cycles that compress vendor revenue recognition windows.
- Interoperability with heterogeneous legacy repositories:Enterprises maintain documents across IBM FileNet, OpenText, and SharePoint environments with incompatible metadata schemas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Capture Software Market |
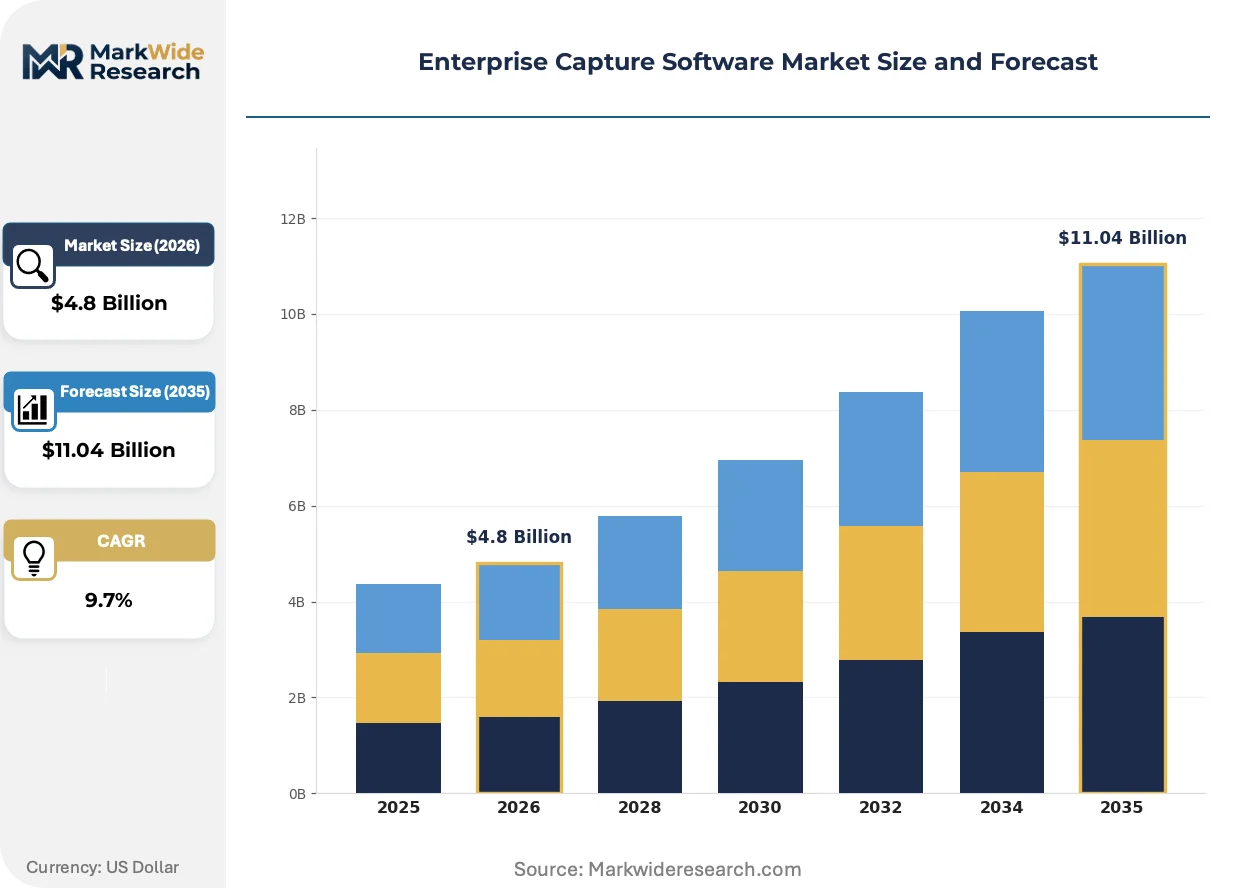
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: BFSI, Healthcare, Retail, Education Solution: Document Management, Data Extraction, Workflow Automation, OCR Industry Vertical: Legal, Government, Manufacturing, Telecommunications |
| Companies Covered | Kofax, ABBYY, OpenText, Hyland, Oracle, IBM, Microsoft, SAP, M-Files, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Capture Software Market Evolving Landscape
Intelligent document processing capabilities are migrating from standalone capture products to embedded features within broader enterprise automation suites, compressing pure-play vendor margins while expanding total addressable workflow spend.
Large language model-powered extraction is electrifying accuracy rates for unstructured document layouts previously resistant to template-based approaches. Insurance carriers and legal services firms in Germany are deploying these systems for policy document and contract analysis. The technology is electrifying competitive positioning for vendors with proprietary training data moats versus those dependent on third-party foundation models.
EU AI Act risk classification requirements for automated decision systems are forcing capture vendors to implement technical documentation and human oversight provisions. Systems performing automated document classification now face conformity assessment obligations that add six-figure certification costs. Life sciences and financial services deployments in France and Germany are prioritizing vendors with existing notified body relationships.
Consumption-based pricing for extraction volumes is displacing perpetual licenses in enterprise procurement negotiations. BFSI buyers in the United States now demand tiered subscription models aligned to monthly page throughput rather than upfront capital expenditure. This shift concentrates purchasing power with centralized procurement functions and extends vendor sales cycles by 40-60 days.
Enterprise Capture Software Market Segmentation
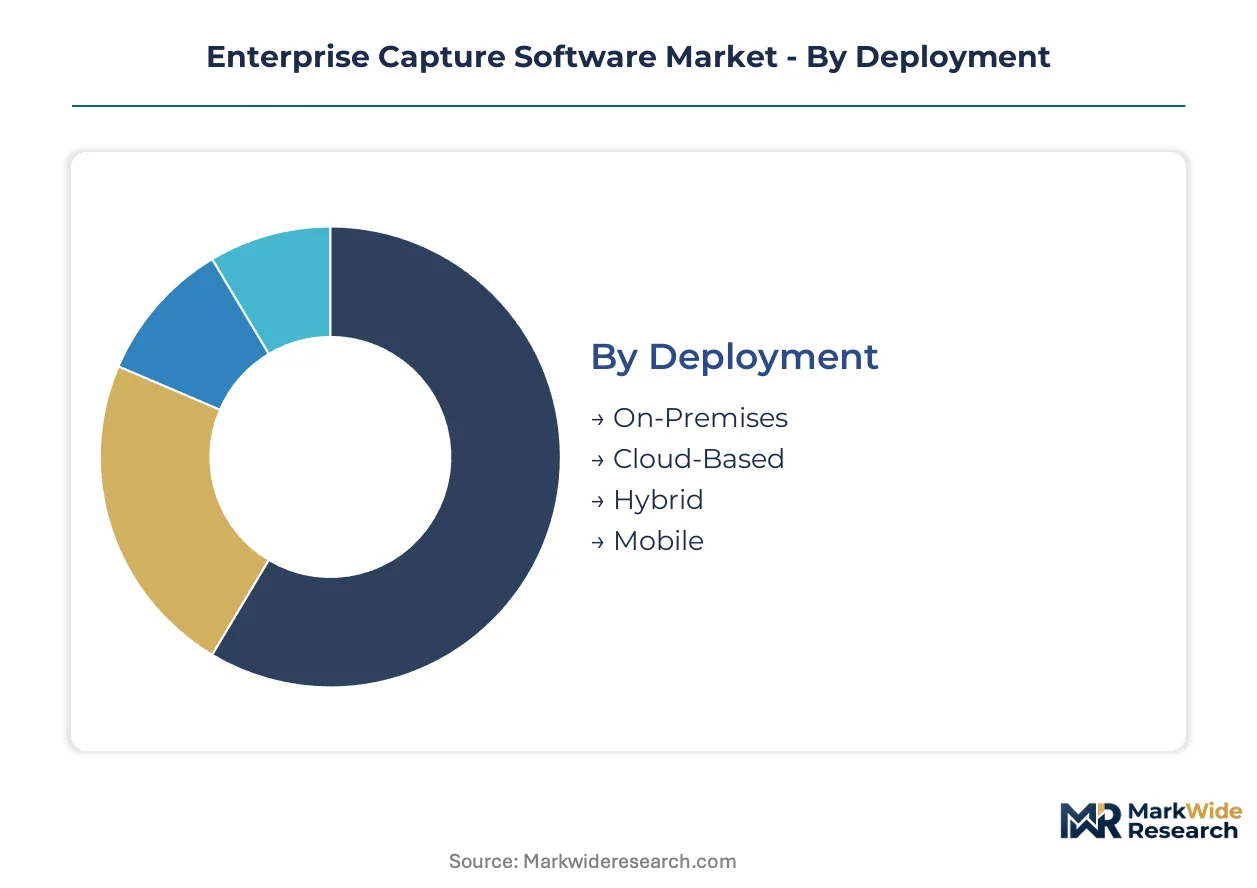
Enterprise capture software procurement patterns diverge sharply across deployment architectures and end-user requirements, with compliance mandates and legacy infrastructure constraints dictating upgrade timelines. Understanding these segment boundaries clarifies where vendors must tailor certification protocols versus where standard SaaS configurations suffice.
Deployment:
Upgrade cycles for deployment modes track regulatory validation burdens and infrastructure amortization schedules, with cloud migration accelerating where data sovereignty rules permit.
- On-Premises:Systems installed within client data centers retain dominance in pharmaceutical manufacturing and defense contracting where air-gapped environments satisfy FDA 21 CFR Part 11 and ITAR requirements. Life sciences buyers in the United States maintain these deployments despite higher total cost of ownership due to 12-18 month revalidation risks associated with platform changes.
- Cloud-Based:Multi-tenant SaaS architectures with ISO 27001 and SOC 2 Type II certifications are capturing healthcare provider spend as HIPAA data portability enforcement compels patient records modernization. German insurers and Japanese regional banks are prioritizing EU AI Act-compliant instances with explainable AI documentation.
- Hybrid:Configurations splitting sensitive extraction workloads on-premises while routing archival storage to cloud tiers accommodate financial services firms with uneven data classification policies.
- Mobile:Smartphone and tablet capture applications with edge OCR processing serve field inspection teams in utilities and logistics where network connectivity is intermittent.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest as regulated industries pursue phased migration strategies.
End User:
End-user concentration correlates with compliance-driven refresh budgets and document complexity, creating divergent margin profiles across verticals.
- BFSI:Banking, financial services, and insurance operations generate the deepest margin pools due to multi-channel capture requirements spanning branch scanning, mobile deposit, and correspondence management. Jurisdictions with stringent anti-money laundering documentation rules—Germany, Japan, and the United States—concentrate procurement authority.
- Healthcare:Hospitals and health systems are expanding intelligent document processing adoption to streamline patient records management under HIPAA data portability mandates. United States provider networks dominate current procurement volumes.
- Retail:Invoice processing and supplier onboarding applications concentrate among omnichannel merchants with high transaction volumes.
- Education:Student records digitization and research administration workflows drive adoption at research-intensive universities with grant compliance obligations.
BFSI commands the highest revenue concentration per account, with Healthcare expanding most quickly as federal enforcement intensifies.
Solution:
Solution bundling strategies reflect a shift from standalone products to embedded automation features, compressing pure-play positioning.
- Document Management:Repository systems with version control, retention policies, and audit trails form the foundational layer for enterprise information governance. Legal and government buyers in France and Germany prioritize ANSM and CNIL-aligned certification.
- Data Extraction:Intelligent document processing engines leveraging machine learning for unstructured content classification are gaining share fastest in insurance and legal services. German policy document analysis deployments illustrate this trajectory.
- Workflow Automation:Business process management layers that route extracted data to downstream ERP and CRM systems.
- OCR:Optical character recognition engines with throughput rates exceeding thousands of pages per hour remain essential for high-volume scanning environments.
Document Management retains the largest installed base, while Data Extraction is gaining share fastest as large language models improve accuracy.
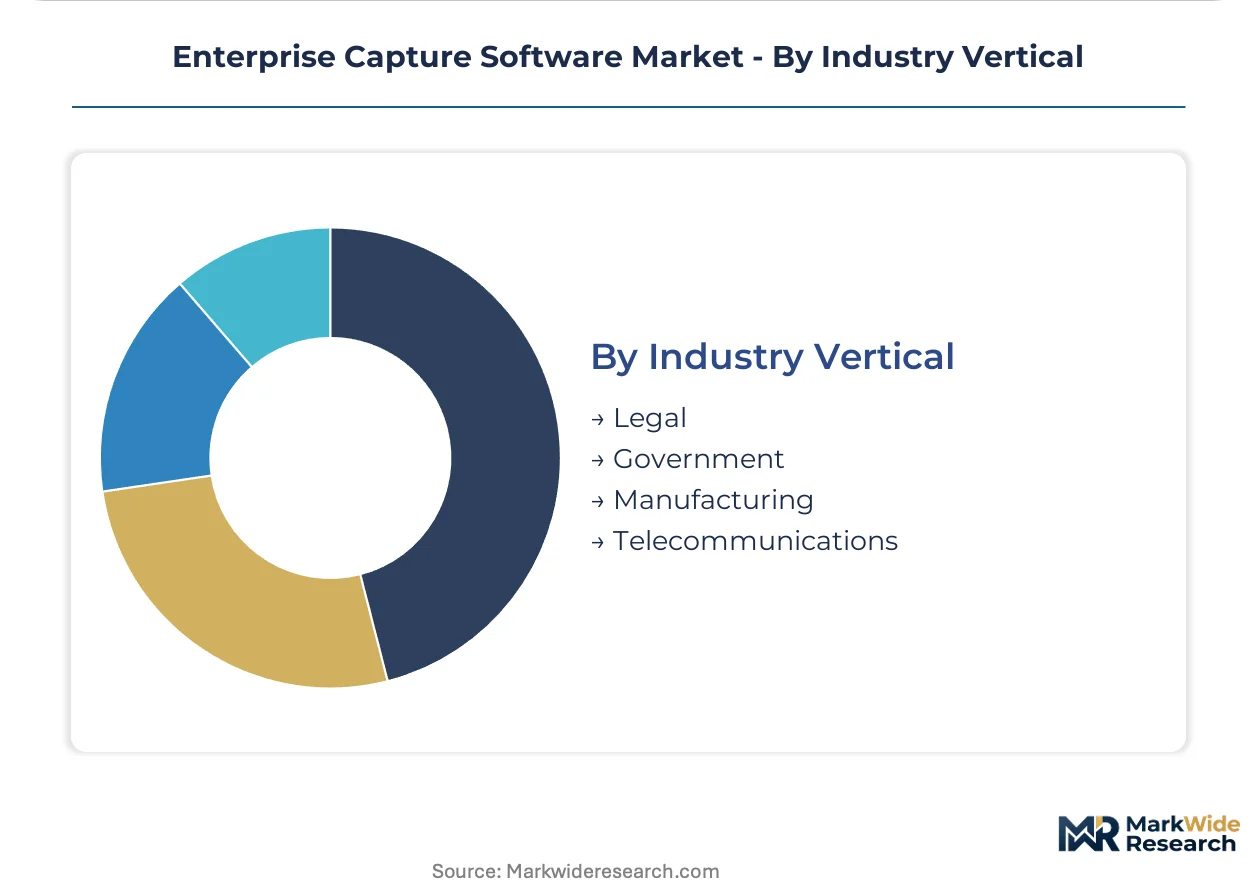
Industry Vertical:
Vertical-specific requirements create certification barriers that favor vendors with pre-existing regulatory relationships.
- Legal:Law firms and corporate legal departments demand extraction accuracy for contract analysis and discovery workflows. German legal services firms are deploying large language model-powered systems for due diligence automation.
- Government:Public sector procurement prioritizes FedRAMP, IL5, or equivalent national security certifications with lengthy vendor onboarding timelines.
- Manufacturing:Quality documentation and supplier record management drive adoption among pharmaceutical and medical device producers subject to EMA Good Manufacturing Practice guidelines.
- Telecommunications:Customer onboarding and regulatory filing automation for operators in Japan and Germany.
Legal commands premium pricing tiers, with Manufacturing expanding fastest as FDA and EMA validation protocols drive replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's regulatory density around EMA compliance and France's AI Act enforcement timeline create starker procurement constraints than the United States, where HIPAA portability rules drive volume without equivalent certification friction.
United States
Healthcare provider networks in Texas and Florida are modernizing patient records systems under intensifying HIPAA enforcement. FDA 21 CFR Part 11 requirements anchor validation protocols for pharmaceutical deployments in New Jersey and North Carolina manufacturing corridors. Boston's life sciences cluster sustains on-premises capture infrastructure despite cloud migration pressure elsewhere.
Germany
Automotive suppliers in Baden-Württemberg and insurers in Munich are prioritizing EU AI Act-compliant platforms with explainable AI documentation. KBA data governance frameworks intersect with EMA Good Manufacturing Practice guidelines to extend vendor certification timelines. Frankfurt's banking concentration demands multi-channel capture spanning branch operations and mobile deposit workflows.
Japan
Regional banks in Osaka and pharmaceutical manufacturers in Kansai operate under METI data governance frameworks that favor established vendors with local compliance expertise. Tokyo's insurance sector deploys large language model-powered extraction for policy document analysis. PMDA validation requirements sustain longer procurement cycles than comparable European markets.
United Kingdom
London's financial services firms are refreshing capture infrastructure ahead of anticipated divergence from EU AI Act implementation timelines. NHS trusts in Manchester and Birmingham face patient records digitization mandates with constrained capital budgets. Legal services clusters in the City prioritize contract analysis accuracy for due diligence automation.
India
IT services exporters in Bengaluru and Hyderabad are bundling software-defined capture solutions with scanning hardware benefiting from PLI scheme manufacturing incentives. RBI data localization requirements shape cloud deployment decisions for banking clients. Mumbai's financial institutions represent the deepest procurement budgets for intelligent document processing among emerging markets.
Enterprise Capture Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pure-play capture vendors defending margin position against enterprise automation suites embedding document extraction as a feature. The vendor base concentrates around three strategic archetypes: legacy information management platforms with installed base leverage, specialized intelligent document processing engines with accuracy differentiation, and cloud-native automation suites acquiring capture capabilities through partnership. M&A activity targets IDP engine technology, while geographic expansion focuses on Japanese and German compliance-certified deployments.
Within the pure-play tier, Kofax and ABBYY occupy positions exemplifying divergent competitive strategies—Kofax leveraging high-volume scanning environment relationships for recurring revenue, ABBYY anchoring positioning through specialized extraction engines. Oracle and IBM sit within the enterprise platform archetype, representing how document capture functionality consolidates into broader automation suites. These groupings illustrate how competitive pressure compresses standalone product margins while expanding addressable workflow spend for integrated offerings.
| Leading Market Players |
|---|
| Kofax |
| ABBYY |
| OpenText |
| Hyland |
| Oracle |
| IBM |
| Microsoft |
| SAP |
| M-Files |
| Others |
Value Network & Pricing Analysis
EU AI Act conformity assessment obligations for automated document classification systems gate qualified supply and premium-tier pricing access, as vendors absorbing six-figure certification costs pass through compliance premiums to enterprise buyers in Germany and France while economy-tier providers remain locked out of regulated verticals.
Pricing Analysis
Capacity additions in cloud infrastructure regions are reshaping price floors for SaaS-tiered subscription models as hyperscale data center expansions in the United States and Germany reduce compute hosting costs. Pricing stratifies across EU AI Act-certified premium tiers, standard SOC 2-compliant mid-market offerings, and economy self-hosted licenses with limited extraction accuracy. Cost compression in the economy tier is intensifying because open-source OCR engines commoditize basic capture functionality. Healthcare provider networks in the United States exhibit the highest price sensitivity due to constrained capital budgets, while pharmaceutical manufacturers in New Jersey and North Carolina accept premium pricing for FDA 21 CFR Part 11 validation support.
Supply Chain Analysis
Freight cost volatility for GPU hardware shipments from Taiwan and South Korea to assembly facilities in the United States and Germany elevates landed costs for training infrastructure essential to intelligent document processing engines. Optical character recognition optimization talent concentrates in Germany, Japan, and the United States, creating geographic skill scarcity that feeds from university research pipelines and specialized immigration channels. Single-source vulnerability around NVIDIA accelerator supply constrains vendor capacity to train large language model-powered extraction systems. Distribution runs through direct enterprise sales teams for regulated verticals and hyperscaler marketplaces for mid-market SaaS deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Japanese METI certification timelines and German EMA validation burdens creates margin capture opportunities for vendors with dual-jurisdiction compliance infrastructure, as twelve-month Japanese procurement cycles contrast with eighteen-month German pharmaceutical deployments.
For Market Incumbents: Lock in recurring revenue streams by embedding capture functionality within broader enterprise automation suites before pure-play margins compress further. Defend against cloud-native automation suites acquiring IDP engines through partnership by deepening vertical integration into proprietary training data pipelines for life sciences document layouts. Prioritize certification investment in FDA 21 CFR Part 11 and EU AI Act notified body relationships to sustain pricing power in regulated segments.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in German legal services contract analysis creates white-space entry at the mid-market tier with large language model-powered extraction accuracy comparable to incumbent engines. Target underpenetrated Japanese regional banks lacking local vendor relationships for METI-compliant deployments. Pursue consumption-based pricing aligned to monthly page throughput as the dominant go-to-market angle, mirroring BFSI procurement demands in the United States.
For Investors and Strategic Acquirers: Roll-up economics work for specialized intelligent document processing engines because accuracy differentiation rests on proprietary training data moats that resist rapid replication. Long-term viability favors vendors with dual-deployment flexibility across cloud and on-premises configurations to capture pharmaceutical manufacturing refresh cycles. Watch FDA enforcement intensity around 21 CFR Part 11 validation protocols as the inflection indicator for life sciences capture software replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Notified body relationships in Germany and France unlock regulated vertical procurement authority. |
| Large Language Model Training Pipeline | Proprietary document corpora from insurance and legal verticals electrify extraction accuracy differentiation. |
| Hybrid Deployment Architecture | Split processing configurations accommodate financial services firms with uneven data classification policies. |
| Healthcare Provider Direct Sales | HIPAA data portability enforcement in Texas and Florida concentrates procurement decision authority. |
| Japanese Compliance Localization | METI data governance framework expertise reduces certification barriers for regional bank and pharmaceutical clients. |
Research Methodology
Multiple input streams — structured interviews with healthcare CIOs and pharmaceutical quality directors, regulatory filing analysis from FDA and EMA databases, and hyperscaler partnership disclosure reviews — were reconciled to construct demand estimates. Primary fieldwork engaged IT procurement officers at German insurers, platform engineers at cloud-native automation vendors, and integration specialists at systems integrators. Secondary validation drew from SEC 10-K software segment disclosures, ISO 27001 certification registries, and hospital procurement database extracts. Bottom-up account-level sizing and top-down vertical spend analysis were triangulated to constrain estimate variance.
Historical revenue trajectories were cross-referenced against panel input from vendor executives and channel partners to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, solution bundling configuration, organization size tier, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation adjusted for compliance-driven refresh cycle timing. Industry-specific forecast inputs encompass EU AI Act implementation phase schedules and FDA 21 CFR Part 11 enforcement intensity indicators.
Caveats apply where GPU supply constraints, tariff regime shifts, or accelerated EU AI Act risk reclassifications could materially shift the outlook. Forecasts embed assumptions about certification timeline stability and cloud migration willingness in pharmaceutical manufacturing environments. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Real Estate Software Market
Software & Services
Consignment Software Market
Software & Services
Fitness App Market
Software & Services
Electronic Batch Records Market
Software & Services
Animation Design Software Market
Software & Services
Braking Systems Software Market
Software & Services
Vlog Editing Software Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Cursor Reviewer Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
Global Feed Software Market
Software & Services
Global Software Composition Analysis Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Global Application Platform Market
Software & Services
EDA Tools Market