
 Architectural Rendering Software Market | 2026-2036
Architectural Rendering Software Market Size, Share, and Industry Trends Forecast 2026-2036
Architectural Rendering Software Market Analysis
EU Green Deal building performance standards is expanding the cost-of-entry calculus for rendering vendors by mandating energy-simulation integration alongside visual output. Lumion sustains its position through real-time engine optimization for mid-market architecture firms. V-Ray dominates high-end visualization pipelines with path-tracing accuracy for film and luxury residential projects. Enscape leverages live-plugin architecture that eliminates file-export friction for Revit and SketchUp users.
Architectural rendering software generates photorealistic or stylized visualizations from building information models, typically processing polygon counts exceeding fifty million while simulating global illumination, material reflectance, and atmospheric conditions for design validation and stakeholder communication. Cloud-based deployment leads adoption as studios distribute rendering workloads across elastic GPU clusters, while virtual reality segments capture expanding margin pools by converting static outputs into immersive walkthrough experiences for developer pre-sales.
EMA's medical device facility design guidelines, OSHA workplace visualization training mandates, and ISO 19650 building information management standards collectively shape product certification requirements and procurement criteria across regulated construction sectors. Stakeholders must monitor whether real-time ray-tracing hardware commoditization shifts competitive advantage from engine optimization to AI-assisted scene composition workflows.
Market Dynamics
The architectural rendering software market pivots on real-time ray-tracing hardware commoditization, which redistributes competitive advantage from proprietary engine optimization toward AI-assisted scene composition workflows and cloud-native delivery architectures.
Growth Catalysts
- EU Green Deal building performance standards:Mandates for energy-simulation-integrated visualization tools accelerate procurement cycles among European architectural studios serving commercial tower developments.
- Pre-construction investor presentation requirements:Real estate developers in Germany and the United Arab Emirates now mandate photorealistic visualization pipelines for capital-raising documentation.
- Live-plugin architecture:Direct Revit and SketchUp integration eliminates file-export friction, compressing workflow timelines for mid-market architecture firms.
Market Restraints
- GPU cluster cost volatility:Cloud-based elastic rendering workloads expose studios to spot-price fluctuations in NVIDIA A100 and H100 compute instances.
- Path-tracing accuracy limitations:Real-time engines sacrifice caustic light simulation precision, disqualifying them from luxury residential and film production pipelines.
- ISO 19650 certification friction:Building information management compliance adds 12-18 month procurement validation cycles for regulated construction sectors.
Strategic Opportunities
- Saudi Arabian giga-project pipeline:Neom and Red Sea tourism developments generate demand for immersive VR walkthrough capabilities in pre-sales marketing.
- OSHA workplace visualization training mandates:Industrial safety simulation creates adjacent revenue streams for rendering vendors with physics-engine capabilities.
- AI-assisted scene composition:Machine learning convergence with traditional ray-tracing architectures enables automated material assignment and lighting calibration.
Industry Challenges
- Computational geometry specialist scarcity:Global illumination algorithm development requires rare expertise in bidirectional path tracing and Metropolis light transport.
- Legacy BIM platform integration complexity:Heterogeneous data formats between Autodesk, Bentley, and Nemetschek ecosystems force costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architectural Rendering Software Market |
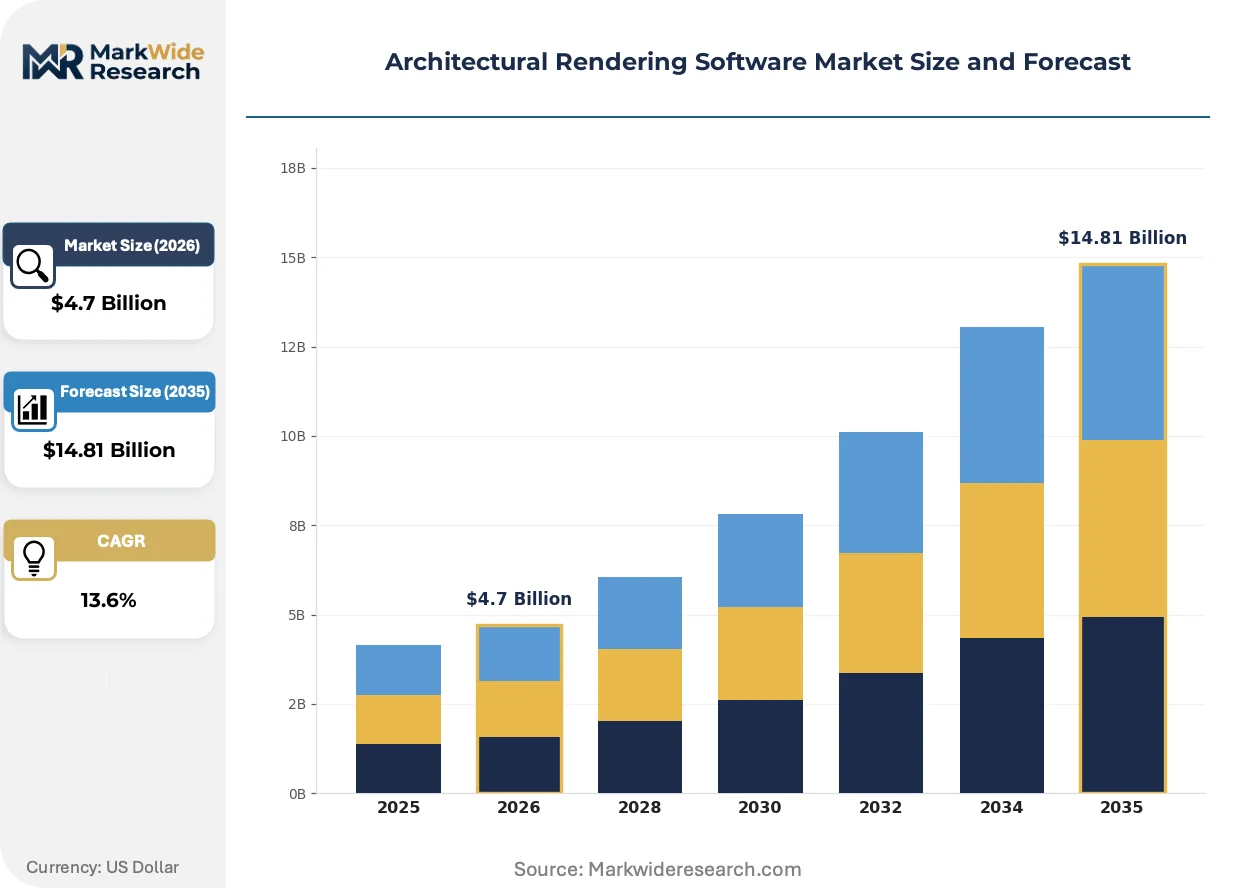
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Rendering, 3D Rendering, Virtual Reality, Augmented Reality End User: Architects, Interior Designers, Landscape Designers, Developers Technology: Raster Graphics, Vector Graphics, Cloud-Based, On-Premise Application: Residential Projects, Commercial Projects, Urban Planning, Visualization |
| Companies Covered | Twinmotion, Blender, Lumion, Revit, SketchUp, Enscape, D5 Render, 3ds Max, V-Ray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architectural Rendering Software Market Emerging Trajectories
Neural rendering architectures and hardware-accelerated ray tracing are compressing the traditional trade-off between visual fidelity and interactivity, forcing incumbents to rearchitect around cloud-native delivery and generative scene construction.
Real-time path-tracing GPUs is unifying previously separate pre-visualization and final-output pipelines. High-end visualization studios in Los Angeles and London adopt NVIDIA RTX Ada generation hardware for simultaneous client review and production-grade output. This convergence collapses the traditional two-stage workflow into single-environment iteration, eliminating overnight render farm queues and accelerating stakeholder feedback cycles.
EMA medical device facility design guidelines now mandate contamination-control visualization for sterile manufacturing environments. Pharmaceutical construction projects in Switzerland and Ireland require particle-flow simulation integrated with architectural geometry. Vendors serving this segment must embed computational fluid dynamics engines alongside surface rendering capabilities.
Subscription-based access models displace perpetual license structures among smaller architectural practices. Mid-market firms in Spain and Italy prioritize predictable monthly expenditure over capital-intensive upfront investment. Channel partners now bundle rendering software with workstation leasing arrangements, capturing hardware margin alongside recurring software revenue.
Architectural Rendering Software Market Segmentation
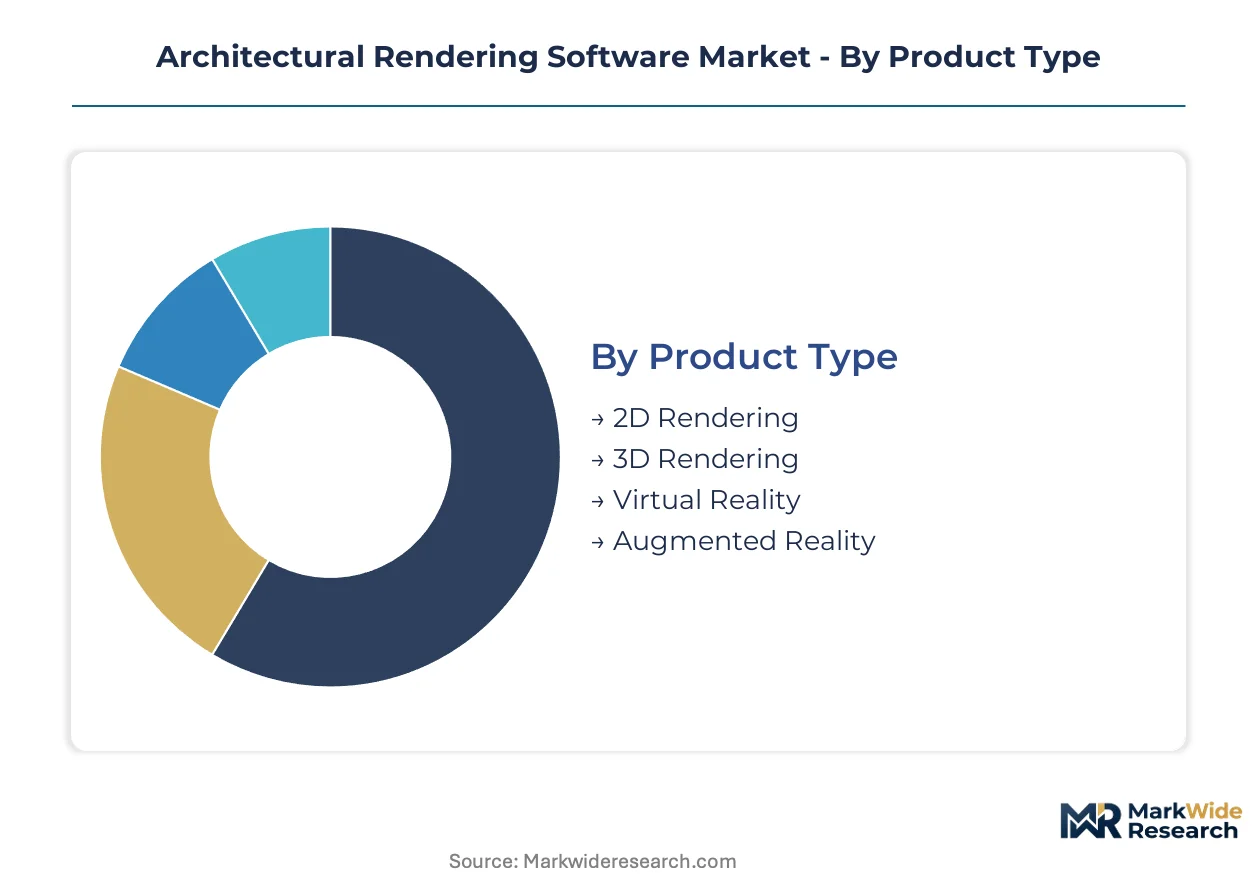
Architectural rendering software segments diverge sharply by computational infrastructure requirements and client workflow integration depth. Capital allocation decisions across product types, end users, technologies, and applications determine vendor R&D prioritization and partnership strategies.
Product Type:
Capital intensity escalates dramatically from 2D workflows through immersive spatial computing, with GPU cluster requirements and talent acquisition costs scaling nonlinearly across the spectrum.
- 3D Rendering:Polygon processing engines handle fifty-million-plus geometry counts with global illumination simulation. German visualization studios serving Middle Eastern commercial towers drive procurement here, demanding path-tracing accuracy for investor presentations.
- Virtual Reality:Real-time stereoscopic output requires dedicated HMD optimization and motion-to-photon latency below twenty milliseconds. Saudi Arabian giga-projects generate demand for immersive pre-sales walkthrough capabilities at Neom and Red Sea developments.
- 2D Rendering:Vector-based elevation and plan generation remains essential for regulatory submission packages. Spanish and Italian mid-market firms favor subscription access for predictable cost structures.
- Augmented Reality:Mobile AR overlays spatial models onto physical environments for on-site client review. Site supervision applications in Switzerland and Ireland leverage tablet-based visualization for pharmaceutical facility construction.
3D Rendering absorbs the bulk of installed capacity; Virtual Reality is expanding most quickly.
End User:
Workflow complexity and software customization requirements fragment the customer base by professional discipline and project scale.
- Developers:Capital-raising documentation mandates photorealistic visualization pipelines for pre-construction investor materials. UAE and German real estate developers now require energy-simulation-integrated outputs compliant with EU Green Deal standards.
- Architects:Live-plugin integration with Revit and SketchUp eliminates file-export friction. Mid-market firms prioritize real-time engine optimization over overnight render farm queues.
- Interior Designers:Material reflectance accuracy and lighting calibration dominate selection criteria. Subscription models displace perpetual licenses among smaller practices.
- Landscape Designers:Vegetation scattering algorithms and atmospheric condition simulation drive specialized tool requirements. Urban greening projects in European cities accelerate adoption.
Developers command the highest per-seat expenditure; Architects represent the broadest installed base.
Technology:
Infrastructure deployment models determine scalability constraints and total cost of ownership across customer segments.
- Cloud-Based:Elastic GPU clusters distribute rendering workloads without capital-intensive hardware procurement. Studios face exposure to NVIDIA A100 and H100 spot-price volatility.
- On-Premise:Dedicated workstation farms maintain data sovereignty for confidential luxury residential projects. High-end Los Angeles and London studios adopt RTX Ada generation hardware for simultaneous client review.
- Raster Graphics:Pixel-based processing dominates real-time preview workflows where interactivity supersedes final-output precision.
- Vector Graphics:Mathematical curve representation enables infinite scalability for technical documentation and regulatory submissions.
Cloud-Based deployment captures expanding share among distributed teams; On-Premise retains dominance where data sensitivity governs procurement.
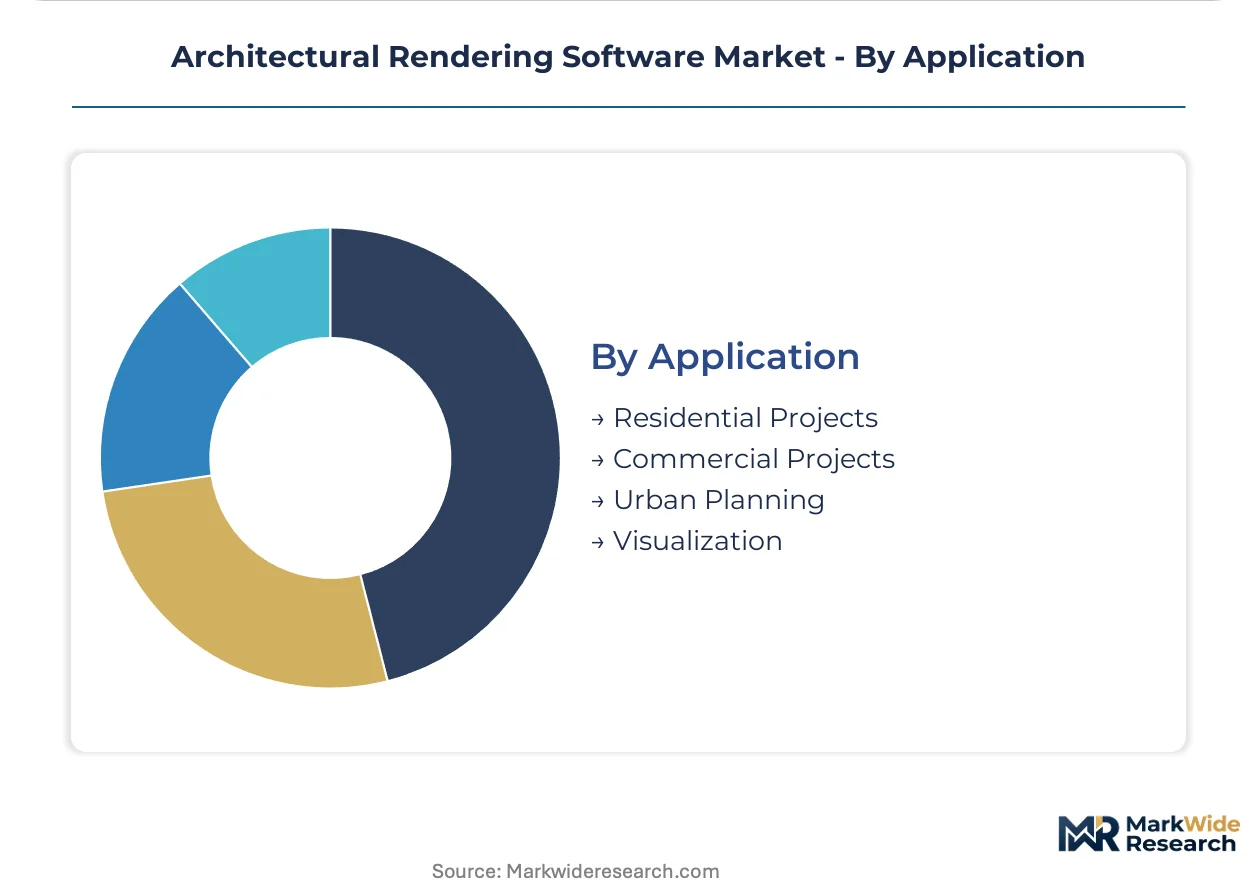
Application:
Project type dictates rendering fidelity requirements, simulation complexity, and stakeholder presentation formats.
- Commercial Projects:Contamination-control visualization for sterile manufacturing environments now mandates particle-flow simulation per EMA guidelines. Swiss and Irish pharmaceutical construction requires computational fluid dynamics integration.
- Residential Projects:Luxury segment demands caustic light simulation precision that real-time engines sacrifice. Path-tracing accuracy remains non-negotiable for film and high-end residential pipelines.
- Urban Planning:Large-scale master visualization requires geographic information system integration and population-density modeling.
- Visualization:General-purpose output spans design validation, marketing materials, and stakeholder communication across project phases.
Commercial Projects absorb the greatest simulation complexity; Residential Projects maintain the largest volume of discrete engagements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Visualization studios cluster in Germany, the United States, and the United Arab Emirates, where developer mandates for pre-construction investor materials concentrate procurement expenditure. EU Green Deal building performance standards and Saudi giga-project pipelines are redistributing R&D investment across these demand centers.
United States
Los Angeles and New York visualization studios drive demand for simultaneous client review and production-grade output. OSHA workplace training mandates create adjacent revenue for physics-engine capabilities. High-end residential pipelines in California and luxury commercial towers in Manhattan maintain path-tracing accuracy requirements that disqualify real-time engines.
Germany
Architectural visualization studios in Berlin and Munich serve Middle Eastern commercial tower projects, compressing procurement cycles for energy-simulation-integrated tools. EU Green Deal building performance standards mandate contamination-control visualization for pharmaceutical facilities. Bavarian construction technology clusters export rendering expertise to Swiss and Irish pharmaceutical construction projects.
United Arab Emirates
Dubai and Abu Dhabi real estate developers mandate photorealistic pipelines for capital-raising documentation on commercial and residential towers. MOHAP facility guidelines accelerate demand for sterile environment visualization. Local studios distribute rendering workloads across elastic GPU clusters to manage spot-price volatility in NVIDIA compute instances.
Saudi Arabia
Neom and Red Sea tourism developments generate procurement for immersive VR walkthrough capabilities in pre-sales marketing. SFDA medical device facility standards require particle-flow simulation integration. Riyadh-based visualization firms are expanding capacity to serve giga-project pipelines with real-time stereoscopic output.
Switzerland
Swissmedic pharmaceutical construction guidelines mandate computational fluid dynamics integration with architectural geometry. Basel and Zurich visualization studios specialize in contamination-control visualization for sterile manufacturing environments. EMA-aligned facility design standards position Swiss vendors as compliance specialists for European pharmaceutical construction.
Architectural Rendering Software Market Vendor Landscape
United States and European producers anchor the premium visualization tier; Asian specialists hold the real-time optimization segment. Market structure fragments across three capability layers: path-tracing accuracy engines, live-plugin integration tools, and cloud-native elastic rendering platforms. Strategic archetypes include engine optimization specialists, BIM-native integrators, and GPU-cluster operators. Competitive moves concentrate on technology licensing partnerships and AI-assisted scene composition R&D.
Within the engine optimization tier, V-Ray and Lumion exemplify divergent fidelity-interactivity trade-offs. Enscape occupies a position as the live-plugin architecture standard for Revit and SketchUp workflows. Blender represents the open-source archetype with global developer community network effects. These three anchors illustrate how competitive positioning splits between accuracy-maximizing pipelines and friction-minimizing integration tools.
| Leading Market Players |
|---|
| Twinmotion |
| Blender |
| Lumion |
| Revit |
| SketchUp |
| Enscape |
| D5 Render |
| 3ds Max |
| V-Ray |
| Others |
Supply Flow & Price Mechanics
GPU compute instance costs cascade through architectural rendering software pricing tiers, with NVIDIA A100 and H100 spot-price volatility compressing margins for cloud-native vendors while on-premise workstation investments anchor premium positioning for data-sovereign studios serving confidential luxury residential projects in Los Angeles and London.
Pricing Analysis
Short lead-time delivery commands premium positioning in architectural rendering procurement, with same-day elastic GPU cluster access priced above reserved instance contracts. Three-tier pricing structure across premium, standard, and economy levels segments by path-tracing accuracy, real-time interactivity, and AI-assisted scene composition depth. Pricing pressure stems from subscription model proliferation among Spanish and Italian mid-market firms seeking predictable monthly expenditure. Interior designers and smaller architectural practices exhibit highest price sensitivity, while German visualization studios serving Middle Eastern commercial towers prioritize accuracy over cost.
Supply Chain Analysis
ISO 19650 certification requirements gate vendor participation in regulated European construction sectors, extending procurement validation cycles. GPU manufacturing concentrates in Taiwan and South Korea, with NVIDIA's Ada generation hardware feeding high-end Los Angeles and London studios. Software development talent clusters in Germany and the United States, while cloud infrastructure draws from hyperscaler networks across Ireland, Frankfurt, and Singapore. Single-source vulnerability in specialized ray-tracing hardware exposes studios to semiconductor supply constraints. Distribution runs through direct vendor relationships and workstation-leasing channel partners bundling software with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Architectural rendering software markets consolidate around AI-assisted scene composition capabilities and cloud-native delivery architectures, with real-time ray-tracing hardware commoditization eliminating engine optimization as a sustainable moat for subscale vendors.
For Market Incumbents: Cement defensible positioning through backward integration into proprietary GPU cluster operations, capturing margin from elastic rendering workloads while insulating against NVIDIA spot-price volatility. Prioritize certification investment for ISO 19650 compliance to lock out unqualified competitors from European pharmaceutical construction pipelines serving Swiss and Irish EMA-aligned facilities.
For New Entrants and Emerging Players: Begin with AI-assisted scene composition tools targeting mid-market Revit and SketchUp users in Spain and Italy, where subscription pricing sensitivity has displaced perpetual license loyalty. White-space opportunity concentrates in OSHA workplace visualization training mandates, where physics-engine capabilities create adjacent revenue streams beyond traditional architectural pipelines.
For Investors and Strategic Acquirers: Neom and Red Sea giga-project procurement acceleration is the leading indicator that Saudi Arabian immersive VR walkthrough demand will sustain premium valuation multiples for real-time stereoscopic output specialists. Target acquisition profiles center on computational fluid dynamics-integrated rendering vendors serving Swissmedic pharmaceutical construction guidelines, with hardware-accelerated ray-tracing convergence signaling inflection toward cloud-native delivery dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Scene Composition Development | Machine learning integration with V-Ray and Lumion engines automates material assignment for German visualization studios. |
| Cloud-Native Platform Migration | Elastic GPU cluster architecture eliminates overnight render farm queues for Los Angeles and London high-end residential pipelines. |
| ISO 19650 Certification Investment | Building information management compliance unlocks 12-18 month procurement cycles in regulated European construction sectors. |
| Computational Fluid Dynamics Integration | Particle-flow simulation capabilities address EMA contamination-control visualization mandates for Swiss and Irish pharmaceutical facilities. |
| Live-Plugin Architecture Expansion | Direct Revit and SketchUp integration compresses workflow timelines for mid-market architecture firms in Spain and Italy. |
Methodological Framework
Multi-period observation of GPU hardware release cycles, subscription pricing migration patterns, and EU Green Deal procurement acceleration anchored the trend analysis, supplemented by interviews with visualization studio technical directors, architectural firm IT procurement officers, BIM platform integration specialists, and cloud infrastructure channel partners. Secondary validation drew from NVIDIA quarterly datacenter revenue disclosures, Autodesk SEC filings, hyperscaler capex breakdowns, and EU regulatory implementation timelines. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models, end-user disciplines, and regional adoption clusters.
Segment-weighting approaches distributed value projections across cloud-based and on-premise infrastructure, developer and architect end-user categories, and commercial versus residential application types. CAGRs derived from elasticity modeling of hardware commoditization effects, AI capability diffusion curves, and regulatory mandate implementation schedules across the analysis window. Industry-specific forecast inputs incorporated NVIDIA RTX Ada generation adoption rates and Saudi giga-project visualization procurement pipelines.
GPU supply chain disruptions, EU building performance standard enforcement delays, and real-time engine accuracy limitations are the dominant revision risks warranting forecast reassessment. A model refresh is warranted upon material change in hyperscaler GPU instance pricing architecture or path-tracing hardware capability convergence timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
API Design Software Market
Software & Services
Data Exchange Platform Services Market
Software & Services
OCR Scanning Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Global Restaurant Management Software Market
Software & Services
General Ledger Accounting Software Market
Software & Services
Metal Fabrication Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Sales Gamification Software Market
Software & Services
Android Emulator Market
Software & Services
Saas for Spa Management Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Global Test Data Management Market
Software & Services
CAM Software Market
Software & Services
Germany HR Payroll Software Market
Software & Services
Truck Dispatch Software Market