
 Office Productivity Software Market | 2026-2036
Office Productivity Software Market Size, Share, and Industry Trends Forecast 2026-2036
Office Productivity Software Market Analysis
India's SaaS corridor in Bengaluru is rewriting competitive dynamics for productivity software development. Microsoft leverages its cloud infrastructure dominance to bundle workplace applications across enterprise accounts. Google competes through workspace integration that anchors real-time collaboration in browser-native environments. Atlassian specializes in project-centric productivity tools that extend into developer workflows and IT service management.
Office productivity software comprises applications for document creation, data analysis, visual communication, and team coordination, typically delivered through local installation or network-accessible platforms with multi-tenant architecture supporting concurrent users. The primary commercial purpose centers on accelerating information work, reducing friction in business processes, and enabling distributed teams to maintain output continuity without physical proximity. Cloud-based deployment now leads license model transitions as enterprises abandon perpetual licenses for subscription frameworks that shift capital expenditure to operational budgets. Collaboration tools represent the fastest-expanding product type as synchronous and asynchronous teamwork applications displace standalone document editors in procurement priorities.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that vendors must embed in European deployments, while the SEC's cybersecurity disclosure rules for US-listed companies elevate software supply chain audit demands. India's Digital Personal Data Protection Act introduces localization obligations that affect cloud routing decisions for multinational providers. Stakeholders must monitor how fragmented regulatory timelines across jurisdictions fragment product standardization and inflate compliance engineering costs.
Market Dynamics
Hybrid work stabilization has permanently altered enterprise software procurement, shifting buyer priorities from individual productivity licenses toward integrated collaboration platforms that bind distributed teams into coherent workflows.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for automated decision-making tools are forcing enterprise buyers to replace shadow IT solutions with auditable vendor platforms, accelerating formal procurement cycles.
- Healthcare sector digitization:HIPAA-covered entities in the United States are consolidating point solutions into unified productivity suites to streamline audit trails and reduce breach exposure surface area.
- Cloud-native architecture:Browser-based delivery models eliminate client-side installation friction, enabling IT departments to deploy updates instantaneously across global workforces without endpoint management overhead.
Market Restraints
- Data residency engineering costs:India's Digital Personal Data Protection Act and comparable localization statutes in Saudi Arabia and Indonesia require redundant infrastructure deployment, inflating operational expenditure for multinational vendors.
- Concentrated hyperscaler dependency:Three cloud providers control the underlying compute and storage substrate for the majority of SaaS productivity platforms, creating single-point-of-failure risk and margin compression from upstream pricing power.
- Interoperability fragmentation:Proprietary real-time collaboration protocols prevent seamless document exchange between competing ecosystems, locking enterprises into vendor stacks and retarding competitive switching.
Strategic Opportunities
- Indonesia's digital economy expansion:Southeast Asia's largest workforce remains underpenetrated by enterprise-grade productivity suites, presenting first-mover advantage for localized compliance engineering and Bahasa Indonesia interface investment.
- Generative AI integration:Convergence of large language models with traditional document editors creates new SKU tiers commanding premium subscription pricing for automated drafting and data synthesis capabilities.
- SEC cybersecurity disclosure rules:Mandated software supply chain transparency for US-listed companies elevates procurement preference toward vendors with SOC 2 Type II and ISO 27001 certifications, favoring established platforms over emerging competitors.
Industry Challenges
- Generative AI governance expertise scarcity:Enterprises lack personnel capable of configuring retrieval-augmented generation systems without exposing proprietary data to training pipelines, slowing deployment timelines.
- Legacy on-premise integration complexity:Mainframe and client-server document management systems in regulated industries resist API-based connectivity, requiring costly middleware development for hybrid cloud transitions.
- Cross-border data routing ambiguity:Conflicting judicial interpretations of GDPR extraterritoriality and Schrems II adequacy decisions create legal exposure for synchronous collaboration sessions spanning multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Office Productivity Software Market |
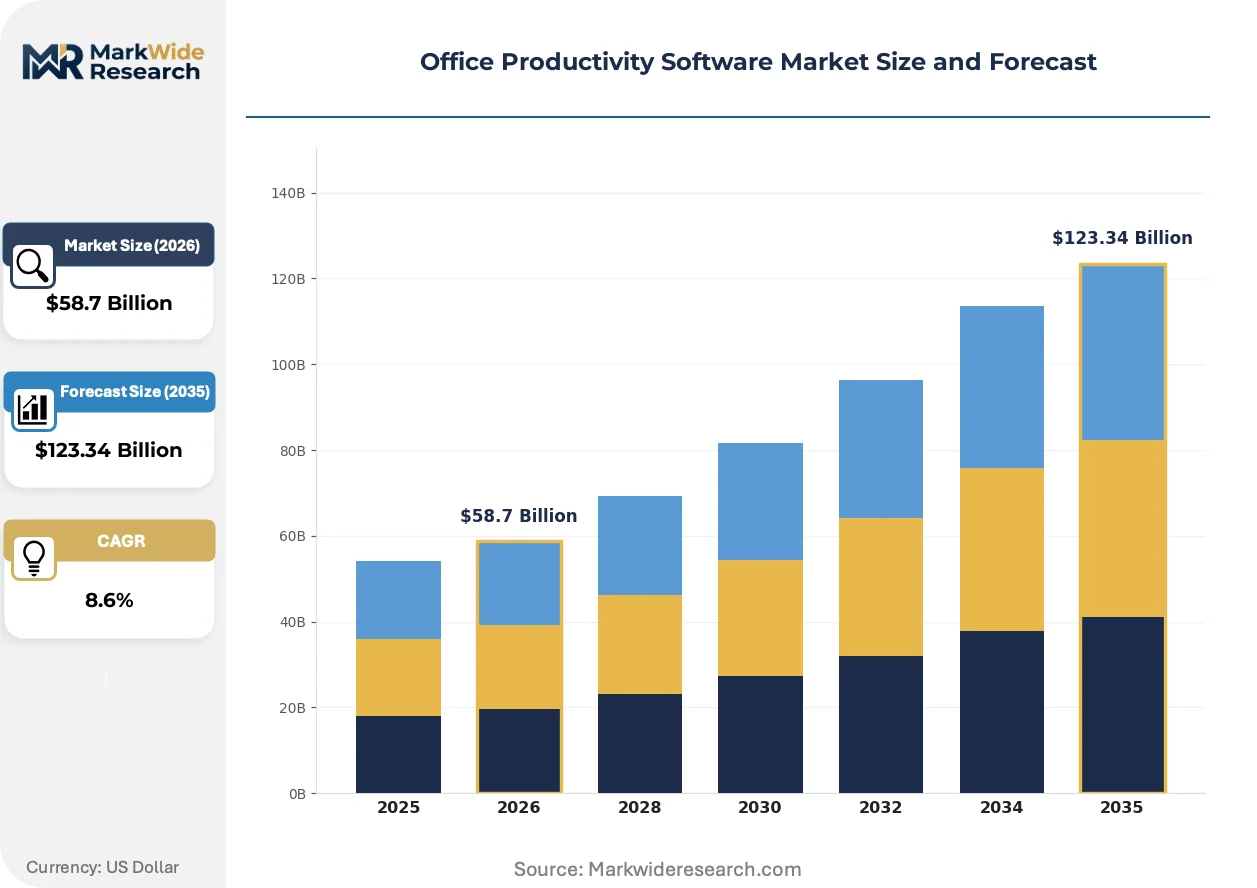
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $123.34 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Word Processing, Spreadsheet, Presentation, Collaboration Tools Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Small Businesses, Enterprises, Educational Institutions, Freelancers License Model: Subscription, Perpetual, Freemium, Enterprise Licensing |
| Companies Covered | Slack Technologies, Asana, Microsoft, Zoho, Monday.com, Google, Zoom Video Communications, SoftMaker, Atlassian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Office Productivity Software Market Emerging Trajectories
Artificial intelligence infusion is compressing the traditional document creation lifecycle, while regulatory fragmentation and procurement centralization are restructuring how vendors compete for enterprise accounts.
Generative AI copilots embedded within word processors and spreadsheets automate routine drafting, data formatting, and visualization tasks that previously consumed knowledge worker hours. Mid-market enterprises in the United States and Germany are deploying these tools at the fastest velocity, often bypassing traditional IT governance channels through departmental credit-card purchases. This shadow adoption pattern is rendering obsolete the centralized software evaluation committees that historically governed enterprise productivity procurement.
The EU AI Act's risk classification framework for biometric emotion recognition and workplace surveillance tools imposes conformity assessment obligations on vendors selling into European enterprises. Product teams must now document training data provenance and algorithmic decision logic before market release, extending development timelines. Collaboration platforms with embedded sentiment analysis or productivity scoring features face the steepest compliance engineering burden, particularly for deployments in France and the Netherlands where CNIL and AP regulators maintain aggressive enforcement postures.
Enterprise buyers are consolidating vendor relationships through platform-level contracts that bundle communication, document creation, project management, and low-code automation into single master service agreements. This relationship compression displaces the previous best-of-breed accumulation strategy where departments independently selected specialized tools. The pattern is most visible among US-based financial services firms and healthcare systems seeking to rationalize security review overhead and reduce integration tax from fragmented software portfolios.
Office Productivity Software Market Segmentation
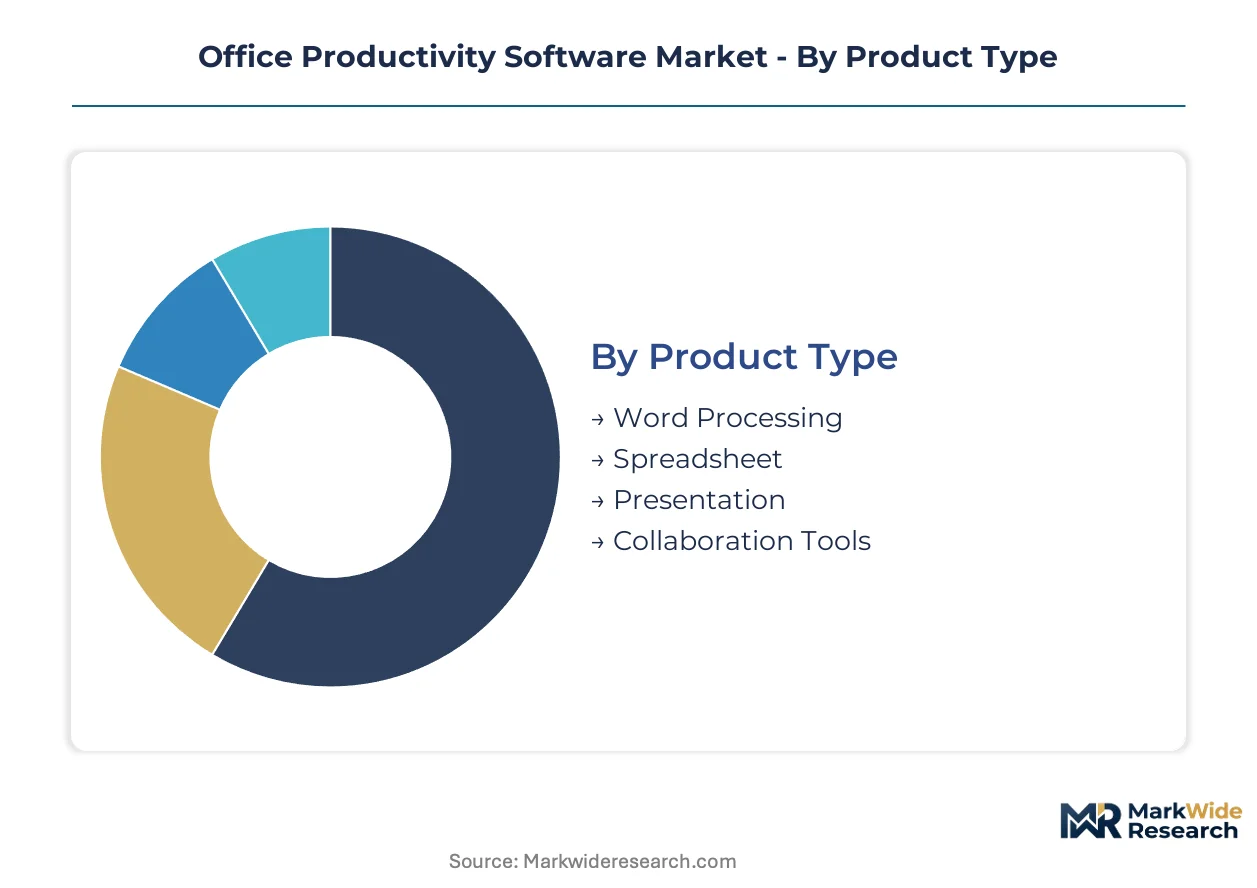
Segmentation in office productivity software reveals how procurement patterns diverge across technical architectures and buyer profiles. Vendors calibrate engineering investments and pricing architectures to match the distinct operational constraints and compliance postures of each segment cluster.
Product Type:
After-sales-service intensity varies sharply across product types, with collaboration tools demanding continuous infrastructure monitoring and real-time troubleshooting that document editors rarely require.
- Word Processing:Core document creation engines handle text formatting, template management, and revision tracking. Enterprises in Germany and France prioritize GDPR-compliant audit trails over feature breadth, driving procurement toward vendors with EU data residency guarantees. Collaboration Tools hold the largest share; momentum sits with Presentation software as generative AI automates visual asset generation.
- Spreadsheet:Computational engines for data analysis, financial modeling, and visualization with embedded formula libraries and pivot architectures. Financial services firms in the United States consolidate around platforms offering SEC-compliant calculation auditability and automated scenario testing.
- Presentation:Visual communication platforms integrating animation engines, template libraries, and real-time co-authoring for stakeholder-facing deliverables.
Collaboration Tools hold the largest share; momentum sits with Presentation software as generative AI automates visual asset generation.
Deployment:
Cost tier stratification dominates deployment choices, with cloud-native delivery commanding premium subscriptions while hybrid architectures absorb compliance-driven engineering overhead.
- Cloud-Based:Browser-delivered applications with multi-tenant infrastructure eliminating client-side installation. Small businesses across India adopt these fastest due to minimal upfront capital requirements and automatic security patching.
- SaaS:Subscription-native architectures with API-first design enabling third-party integration ecosystems. SaaS represents the fastest-expanding deployment model as IT departments abandon perpetual license maintenance burdens.
- On-Premises:Locally installed software with data storage confined to organizational infrastructure, persisting in defense and intelligence sectors with air-gapped security mandates.
- Hybrid:Split architectures combining cloud accessibility with sensitive data localization, prevalent in German manufacturing and Japanese healthcare where regulatory fragmentation demands jurisdictional partitioning.
Cloud-Based deployments dominate volume; Hybrid configurations gain share fastest among regulated industries.
End User:
Application context shapes feature prioritization, with educational institutions demanding administrative oversight tools that freelance workflows rarely utilize.
- Enterprises:Large organizations with centralized IT governance, multi-department procurement committees, and compliance audit requirements. United States healthcare systems consolidate productivity suites to streamline HIPAA audit trails and reduce breach exposure surface area.
- Small Businesses:Organizations with limited IT staff relying on out-of-box configurations and vendor-managed security updates. India's SaaS corridor targets this segment with localized pricing and Bahasa Indonesia interface options for Southeast Asian expansion.
- Educational Institutions:Universities and K-12 systems requiring administrative dashboards, plagiarism detection integration, and student data privacy controls.
- Freelancers:Individual practitioners purchasing through direct-to-consumer channels with minimal configuration overhead and cross-device synchronization priorities.
Enterprises generate the highest revenue per seat; Small Businesses expand most quickly as digital adoption penetrates developing economies.
License Model:
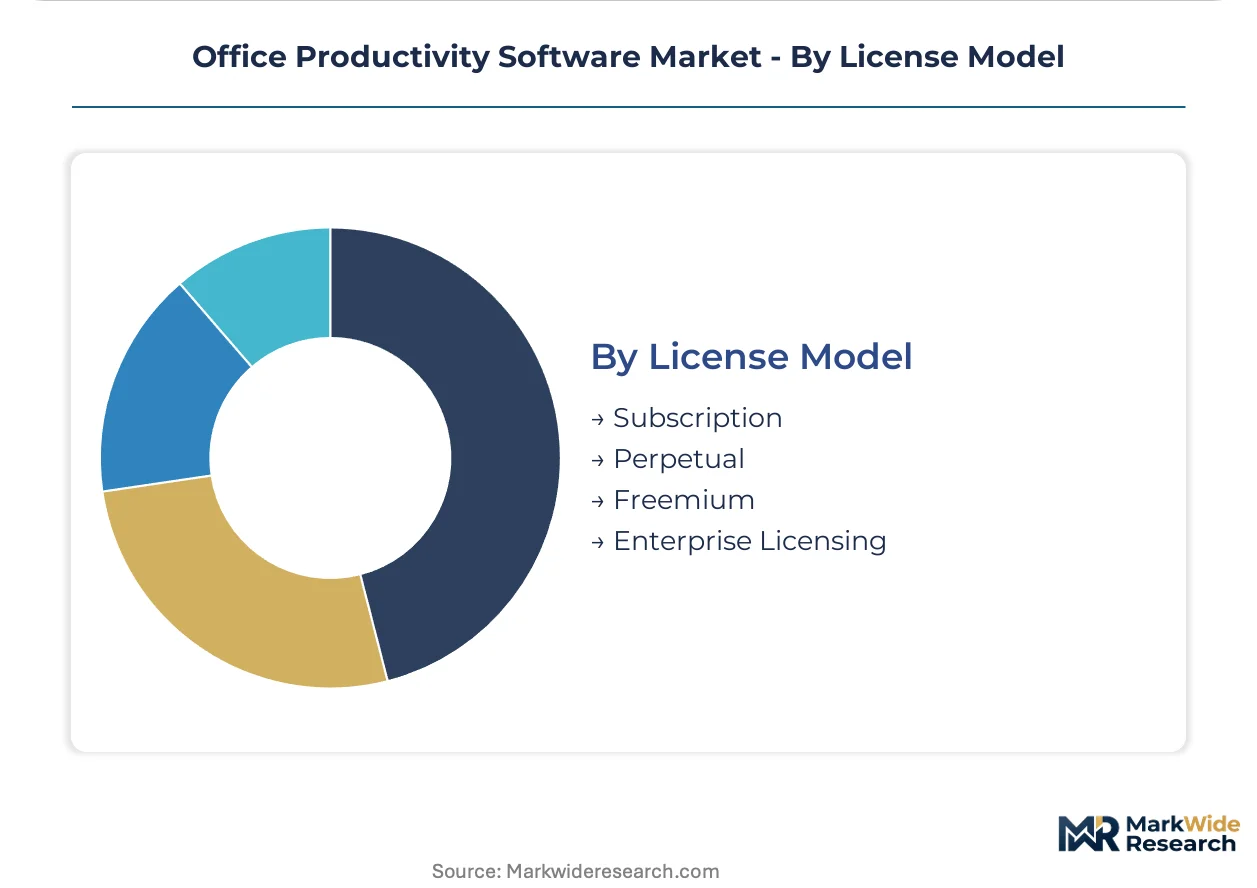
Customer type and procurement maturity dictate license architecture preferences, with centralized enterprise procurement favoring predictable operational expenditure over capital-intensive perpetual commitments.
- Subscription:Recurring payment structures shifting software from capital to operational budgets. Mid-market firms in the United States and Germany deploy generative AI copilots through departmental credit-card purchases, bypassing traditional IT governance channels.
- Enterprise Licensing:Master service agreements bundling communication, document creation, and project management into unified contracts with volume discounts and dedicated support tiers. US financial services firms leverage these to rationalize security review overhead.
- Perpetual:One-time purchase models with maintenance fee attachments, persisting in legacy manufacturing environments with depreciation schedules resistant to subscription transitions.
- Freemium:Tiered access models converting free users through feature gates and storage limitations, dominant in individual and micro-business acquisition funnels.
Subscription models command the largest installed base; Enterprise Licensing climbs fastest as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler infrastructure concentrates in the United States, while compliance engineering investments reshape vendor deployment patterns across fragmented regulatory jurisdictions. Enterprise procurement centralization accelerates fastest in North America and Western Europe. India's SaaS corridor emerges as a development cost arbitrage hub for productivity software engineering.
United States
Healthcare systems consolidate productivity suites to streamline HIPAA audit trails and reduce breach exposure. The SEC's cybersecurity disclosure rules elevate procurement preference toward vendors with SOC 2 Type II certifications. Silicon Valley hyperscalers anchor cloud infrastructure supply, while New York financial services firms drive enterprise licensing consolidation.
Germany
Manufacturing enterprises demand hybrid architectures combining cloud accessibility with sensitive data localization. The GDPR and EU AI Act impose algorithmic transparency requirements that extend vendor development timelines. Baden-Württemberg's automotive sector leads adoption of project-centric productivity tools for supply chain coordination.
India
Small businesses adopt cloud-based deployments fastest due to minimal upfront capital requirements. The Digital Personal Data Protection Act introduces localization obligations affecting cloud routing decisions. Bengaluru's SaaS corridor rewrites competitive dynamics through cost-engineered productivity software development.
United Kingdom
Financial services firms rationalize security review overhead through platform-level master service agreements. The UK Information Commissioner's Office maintains aggressive GDPR enforcement postures on cross-border data transfers. London anchors procurement centralization for European enterprise accounts.
Indonesia
Southeast Asia's largest workforce remains underpenetrated by enterprise-grade productivity suites. Localization statutes require Bahasa Indonesia interface investment and redundant infrastructure deployment. Jakarta's digital economy expansion presents first-mover advantage for compliant vendor entry.
Office Productivity Software Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in workflow automation and developer tooling. The vendor base stratifies between hyperscale bundlers and vertical specialists. Three archetypes dominate: cloud infrastructure bundlers, project-centric workflow specialists, and browser-native collaboration platforms. Competitive moves center on API ecosystem expansion and generative AI SKU tiering.
Within the bundler tier, Microsoft and Google anchor enterprise account consolidation through infrastructure-integrated workplace applications. Atlassian occupies a specialist position exemplifying project-centric productivity extension into developer workflows. These three represent the dominant competitive anchors shaping procurement committee evaluations.
| Leading Market Players |
|---|
| Slack Technologies |
| Asana |
| Microsoft |
| Zoho |
| Monday.com |
| Zoom Video Communications |
| SoftMaker |
| Atlassian |
| Others |
Supply Flow & Price Mechanics
Hyperscaler infrastructure concentration in the United States anchors downstream margin capture, with Amazon Web Services, Microsoft Azure, and Google Cloud controlling the compute substrate that SaaS productivity vendors must lease. This upstream triopoly compresses vendor margins while concentrating pricing power in the infrastructure tier.
Pricing Analysis
EU AI Act compliance mandates dictate the pricing tier structure for European deployments, forcing vendors to absorb algorithmic transparency engineering costs or pass them through as regional premiums. Three-tier pricing structure across premium, standard, and economy levels segments by certification depth and data residency guarantees. Cost compression in the mid-market tier is intensifying because departmental credit-card procurement bypasses enterprise volume discounts. Small businesses in India exhibit the highest price sensitivity, while US healthcare systems prioritize auditability over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced GPU clusters and AI training hardware limit flows to Chinese and Russian endpoints, fragmenting global cloud routing decisions. Software development labor concentrates in India, the United States, and Poland, with Bengaluru's SaaS corridor feeding engineering talent into productivity platform R&D. Cloud infrastructure draws from hyperscaler data centers in Virginia, Frankfurt, and Singapore. Single-source vulnerability sits with the three dominant cloud providers. Distribution runs through direct enterprise sales teams and self-serve web portals for lower-tier subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network effects embedded in document format standards and real-time collaboration protocols create defensible moats for established productivity platforms. Regulatory entrenchment through SOC 2 and ISO 27001 certifications compounds switching costs for enterprise buyers.
For Market Incumbents: Build switching-cost moats through API ecosystem lock-in and generative AI copilot integration that trains on proprietary organizational data. Consolidate position by acquiring workflow automation specialists in the project management layer. Vertical integration into sovereign cloud infrastructure in Germany and India addresses data residency threats. Certification investment in EU AI Act conformity assessment procedures secures procurement preference among European enterprises. For New Entrants and Emerging Players: Indonesia's underpenetrated enterprise workforce represents the most penetrable entry point for localized productivity suites with Bahasa Indonesia interfaces and Jakarta-based data residency. Mid-market professional services firms in Southeast Asia lack integrated platforms combining document creation with client portal functionality. Channel partnerships with regional systems integrators bypass direct competition with hyperscaler sales teams. For Investors and Strategic Acquirers: Capital is best deployed toward vertical specialists with embedded workflow knowledge in healthcare or financial services compliance. Long-term viability hinges on generative AI integration depth rather than standalone feature parity. Watch for inflection signals in enterprise procurement committee consolidation toward platform-level master service agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI SKU Tiering | Premium subscription tiers for automated drafting command pricing power from mid-market US and German enterprises. |
| Strategic Partnership | Alliances with hyperscalers secure preferential compute pricing and co-selling access to enterprise accounts. |
| Geographic Expansion | Indonesia localization investments capture first-mover advantage in Southeast Asia's largest workforce. |
| Platform Integration | API-first architectures embed productivity tools into existing enterprise software stacks, reducing churn. |
| Acquisition of Specialist Firm | Workflow automation targets extend core document creation into adjacent project management revenue pools. |
Methodological Framework
The analysis maps collaboration tools, document editors, and workflow automation platforms, each validated through CTOs, IT procurement officers, platform engineers, and channel partners. Primary interviews with enterprise software buyers and secondary validation against SEC filings, hyperscaler capex disclosures, App Annie usage data, and EU regulatory filings triangulate demand signals. Bottom-up seat-count modeling and top-down enterprise IT spend allocation cross-check volume estimates.
Assumptions held fixed include hybrid work stabilization rates and current regulatory enforcement postures across GDPR, EU AI Act, and SEC cybersecurity rules, while cloud infrastructure pricing and generative AI adoption velocity were varied across sensitivity scenarios. Segmentation dimensions modeled include deployment architecture, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs were derived from trend extrapolation with elasticity adjustments for compliance-driven procurement acceleration. Inputs included enterprise licensing contract values and departmental shadow IT spending patterns.
Stress conditions across hyperscaler pricing power, regulatory timeline fragmentation, and generative AI governance expertise scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about procurement centralization velocity and compliance engineering cost trajectories. Material shifts in EU AI Act enforcement posture or Schrems II adequacy decisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
3D CAD Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Microsoft Office 365 Integration Services Market
Software & Services
Global Coworking Space Management Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Global Maintenance Management Software Market
Software & Services
Human Resource Management Software Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Email Marketing Software Market
Software & Services
Sales Force Automation Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Global Application Development Software Market
Software & Services
ELD Compliance Software Market
Software & Services
Global Ad Server Software Market
Software & Services
Language Translation Software Market
Software & Services
Multivariate Testing Software Market