
 Shift Planning Software Market | 2026-2036
Shift Planning Software Market Size, Share, and Industry Trends Forecast 2026-2036
Shift Planning Software Market Insights
Healthcare facility demand is consolidating as the fastest-expanding end-use vertical for shift planning platforms. UKG leverages deep workforce management heritage to anchor enterprise hospital contracts. Dayforce competes through unified HCM-to-scheduling architecture. SAP extends ERP-native deployment advantages into manufacturing unit accounts.
Shift planning software automates employee schedule creation, shift swapping, and labor compliance tracking through algorithmic constraint-solving and real-time communication protocols. The primary commercial purpose is minimizing labor overage while ensuring regulatory staffing minimums across variable-demand operations. Cloud deployment leads volume due to lower IT overhead and faster rollout cycles, though hybrid solutions capture margin pools from data-sensitive healthcare buyers. Mobile application interfaces represent the fastest-growing product type as deskless worker populations expand. On-premises installations persist in defense and critical infrastructure settings with strict air-gap requirements.
FDA 21 CFR Part 11 documentation standards shape healthcare buyer expectations for audit trails in scheduling systems. EU GDPR and emerging state-level US privacy laws force vendors to regionalize data residency and consent architectures. OSHA recordkeeping linkages drive manufacturing procurement checklists. Stakeholders must weigh interoperability investments against the fragmentation risk of point solutions versus integrated HCM suites.
Market Dynamics
Algorithmic constraint-solving engines are displacing rule-based scheduling templates across hospital networks and retail chains, compressing deployment timelines from quarters to weeks while hardening compliance documentation for OSHA and FDA audit requirements.
Growth Catalysts
- OSHA Recordkeeping Integration:Manufacturing facilities in the United States are mandating scheduling systems that automatically log hours against safety incident databases, pulling capital into compliant platforms.
- Cloud Deployment Economics:Healthcare buyers are prioritizing SaaS models that eliminate server maintenance overhead and accelerate multi-site rollouts across dispersed clinic networks.
- GDPR-Aligned Data Residency:European procurement committees now require regional server hosting and granular consent architectures, filtering vendor shortlists to compliant providers.
Market Restraints
- Hybrid Infrastructure Costs:Healthcare systems seeking air-gapped on-premises nodes face 40-60% higher total cost of ownership versus pure cloud, constraining budget-constrained regional hospitals.
- API Fragmentation:Point solutions with proprietary data formats create integration friction with existing HCM suites, locking buyers into suboptimal single-vendor contracts.
- Legacy System Entrenchment:Defense contractors and critical infrastructure operators maintain decades-old scheduling databases with no migration path, capping addressable market expansion.
Strategic Opportunities
- Deskless Worker Mobile Interfaces:Warehouse and logistics operators are demanding smartphone-native shift swapping and real-time notification systems, opening product development lanes outside traditional desktop-first vendors.
- State-Level Privacy Legislation:Emerging US state laws beyond California are forcing multi-jurisdictional compliance tooling, creating first-mover advantage for vendors with flexible consent frameworks.
- AI-Assisted Predictive Scheduling:Machine learning demand forecasting layered atop shift planning is overtaking historical pattern matching in grocery and quick-service restaurant chains.
Industry Challenges
- Interoperability Engineering Talent:Vendors struggle to hire sufficient HL7 and FHIR specialists to build healthcare-compliant data exchange layers at pace with contract demands.
- FDA 21 CFR Part 11 Validation Timelines:Electronic signature and audit trail documentation requirements extend sales cycles by 6-12 months for hospital network deals.
- Multi-Union Collective Bargaining Complexity:Municipal transit and public safety departments require engines that simultaneously process dozens of overlapping work-rule sets, taxing algorithmic flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shift Planning Software Market |
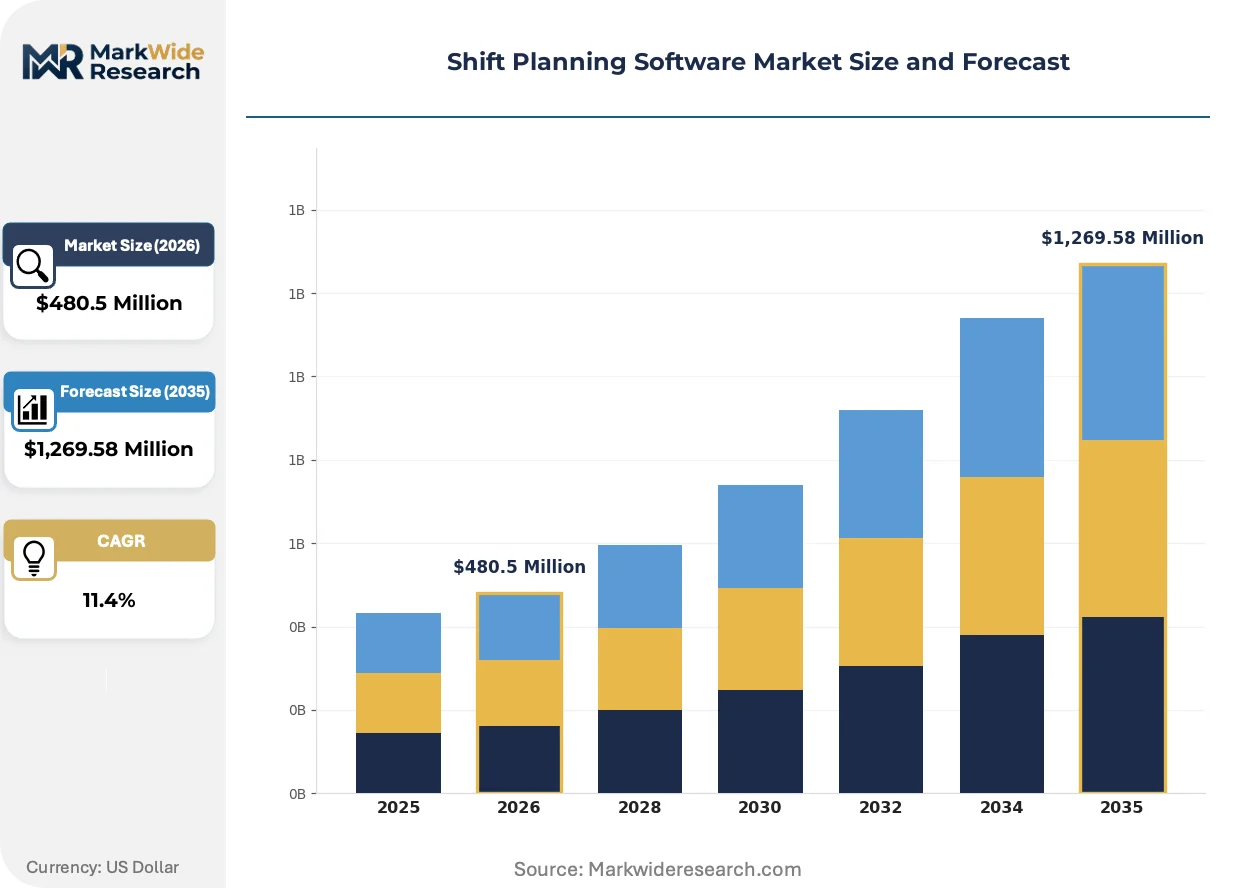
| Market Size in 2026 | $480.5 Million |
| Market Size in 2035 | $1,269.58 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-Based, Mobile Application, Hybrid Solution, On-Premises End User: Healthcare Facilities, Retail Chains, Hospitality Industry, Manufacturing Units Deployment Model: Cloud Deployment, On-Premises Deployment, Hybrid Deployment, Managed Services Feature: Automated Scheduling, Time Tracking, Real-Time Updates, Reporting Tools |
| Companies Covered | UKG, Dayforce, Workday, QGenda, ADP, Oracle, SAP, Planday, Humanity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shift Planning Software Market Trends and Innovations
Mobile-first architectures and predictive algorithms are compressing the gap between labor forecasting and real-time schedule adjustment, while regulatory data residency mandates are forcing vendors to regionalize cloud infrastructure.
AI-driven demand forecasting engines are overtaking static template-based scheduling in quick-service restaurant and grocery chains. These systems ingest POS traffic patterns, weather data, and local event calendars to generate shift recommendations 72 hours forward. Multi-unit operators are adopting these tools to reduce labor overage by double-digit percentages while maintaining service-level targets.
GDPR Article 44-49 data transfer restrictions are compelling European healthcare buyers to reject US-hosted SaaS platforms without EU-based server clusters. Vendors are responding by standing up Frankfurt and Dublin data centers, adding 15-20% infrastructure cost that is being passed through as geographic pricing premiums. German hospital networks are now requiring contractual data processing agreements with explicit third-country transfer prohibitions.
Frontline managers are bypassing IT procurement channels to purchase departmental scheduling tools on corporate credit cards, then forcing enterprise-wide consolidation after adoption spreads. This shadow-IT pattern is most visible in US retail and hospitality verticals where store-level autonomy remains high. Vendors are responding with freemium entry pricing and viral expansion features designed to capture this bottom-up demand before formal RFP processes begin.
Shift Planning Software Market Segmentation
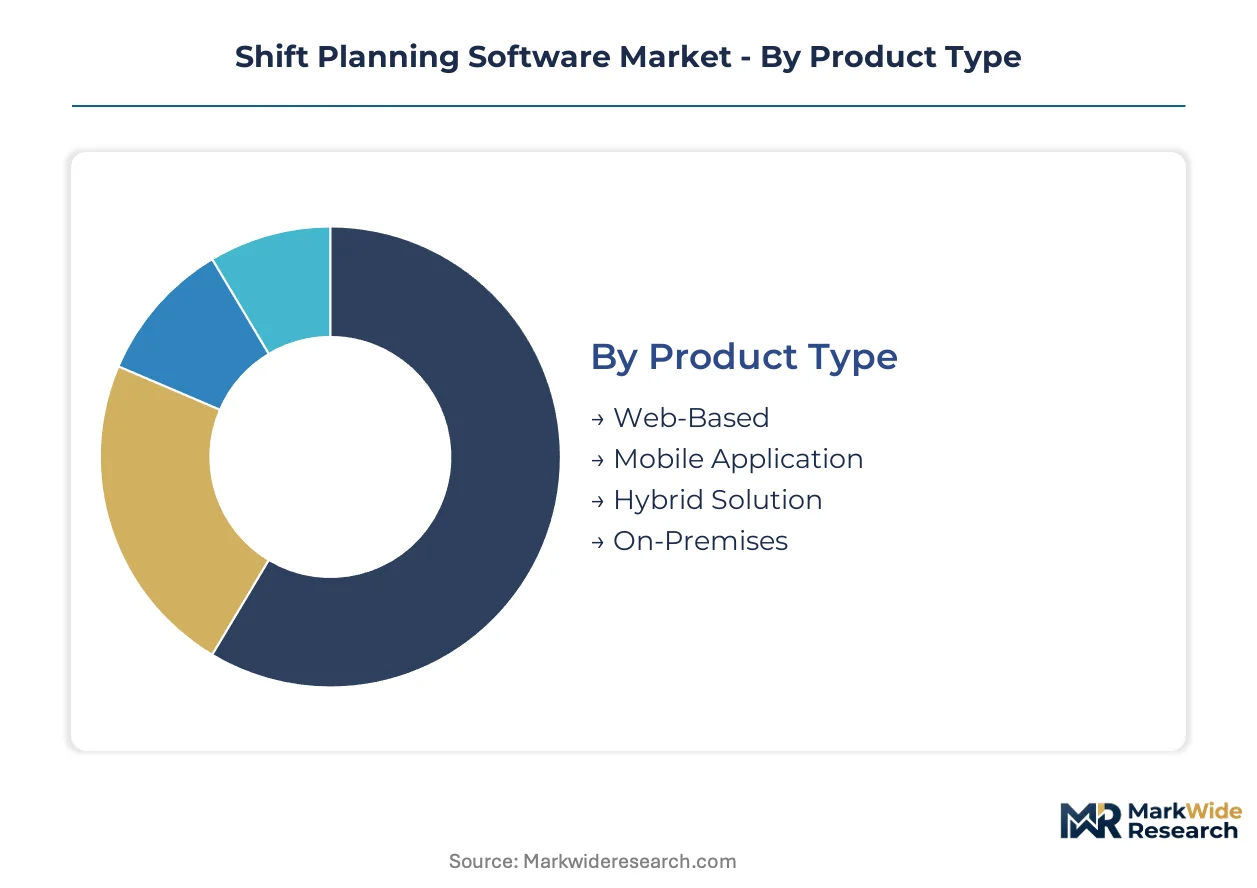
Segmentation in shift planning software reveals how procurement criteria diverge across buyer archetypes. Hospital networks prioritize FDA-compliant audit trails while retail chains optimize for mobile-first workforce engagement. Understanding these fault lines enables vendors to align product roadmaps with segment-specific compliance and usability requirements.
Product Type:
Deployment architecture determines integration complexity and total cost of ownership for buyers with varying IT maturity.
- Web-Based:Browser-accessible platforms eliminate client-side installation overhead. Hospital networks in the United States favor these systems for centralized IT governance across dispersed clinic sites, though GDPR-sensitive European buyers increasingly demand regional hosting assurances.
- Mobile Application:Native smartphone interfaces enable real-time shift swapping and push notifications for deskless workers. Warehouse and logistics operators in Germany and the Netherlands are driving fastest adoption here as frontline employee populations expand beyond traditional workstation access.
- Hybrid Solution:Combines cloud orchestration with on-premises data nodes for air-gapped compliance requirements. Defense contractors and critical infrastructure operators mandate these architectures despite 40-60% higher ownership costs.
- On-Premises:Fully localized server installations serve environments with strict network isolation policies. Municipal transit authorities in France and public safety departments maintain legacy procurement preferences for this model.
Web-Based leads on scale; Mobile Application leads on momentum.
End User:
Vertical-specific regulatory pressures reshape feature prioritization and sales cycle duration across buyer categories.
- Healthcare Facilities:Hospital networks and clinic systems require FDA 21 CFR Part 11 compliant electronic signatures and immutable audit trails. UK and German hospital procurement committees now embed GDPR Article 44-49 data residency clauses as mandatory evaluation criteria.
- Retail Chains:Multi-location operators demand algorithmic demand forecasting tied to POS systems. Quick-service restaurant chains in the United States are layering machine learning atop scheduling engines to compress labor overage.
- Hospitality Industry:Seasonal workforce volatility drives demand for rapid onboarding and shift marketplace functionality. Shadow-IT purchasing patterns concentrate here as property-level managers bypass centralized procurement.
- Manufacturing Units:OSHA recordkeeping integration is becoming a non-negotiable requirement. US-based automotive and electronics assembly plants mandate automatic hour-logging against safety incident databases.
Healthcare Facilities lead on scale; Retail Chains lead on momentum.
Deployment Model:
Infrastructure location strategy directly impacts compliance posture and operational resilience for regulated industries.
- Cloud Deployment:SaaS delivery eliminates server maintenance overhead and accelerates multi-site rollouts. Healthcare buyers across France, Germany, and the Netherlands prioritize this model for clinic network expansion despite emerging data sovereignty requirements.
- On-Premises Deployment:Complete physical control over hardware and data satisfies air-gap mandates. Defense sector buyers in the United States and critical infrastructure operators maintain entrenched preferences here.
- Hybrid Deployment:Selective cloud bursting with sensitive data retained locally bridges compliance and agility needs. Regional hospital systems with constrained IT budgets are adopting this middle path.
- Managed Services:Outsourced infrastructure operations with vendor-assumed maintenance liability. Mid-market manufacturing facilities in Germany leverage this model to access enterprise-grade uptime without internal DevOps investment.
Cloud Deployment leads on scale; Hybrid Deployment leads on momentum.
Feature:
Functional module selection reveals where buyers extract operational value versus mere administrative automation.
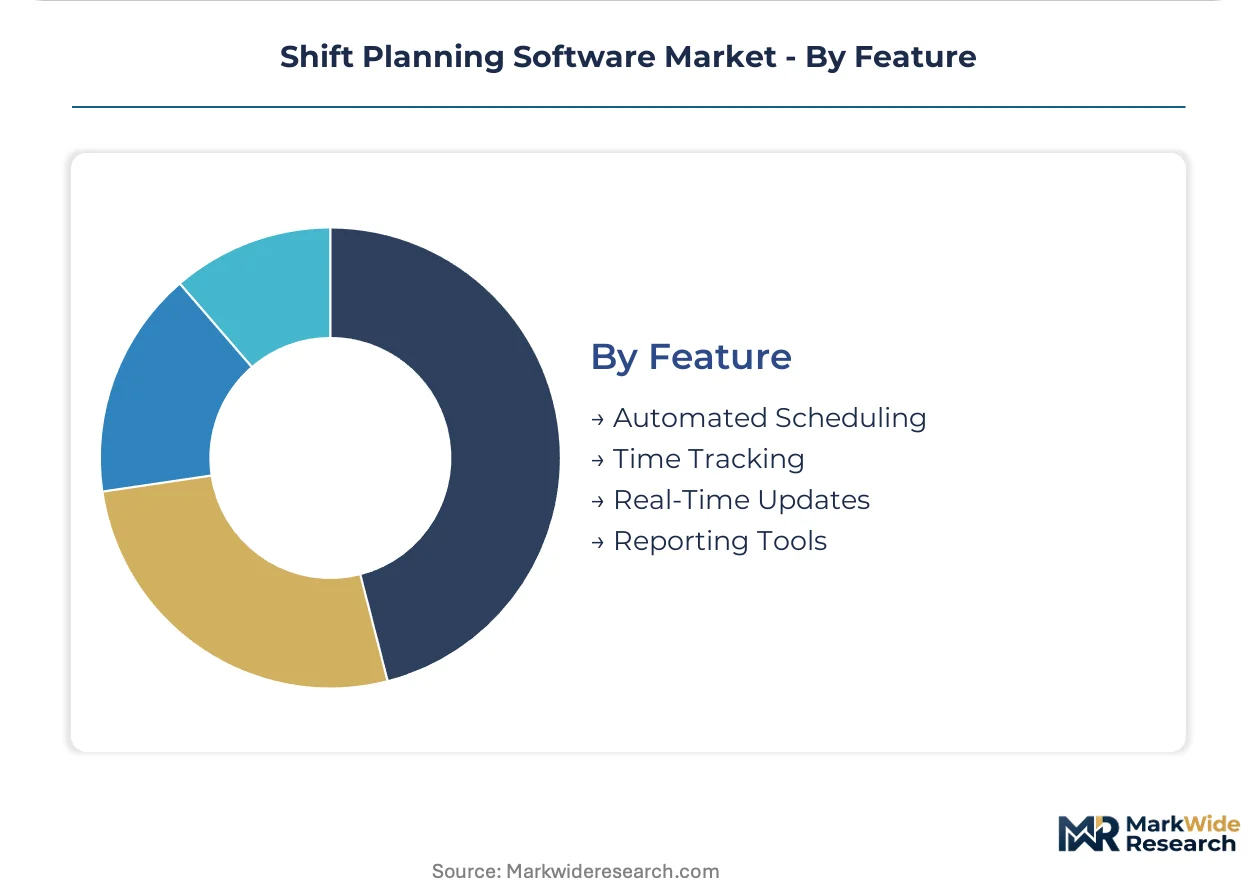
- Automated Scheduling:Algorithmic constraint-solving engines displace rule-based templates. Hospital networks deploy these to harden Joint Commission staffing compliance while reducing scheduler overtime.
- Time Tracking:Biometric and geofenced clock-in systems tighten payroll accuracy. Manufacturing facilities integrate these with OSHA recordkeeping for automated safety incident correlation.
- Real-Time Updates:Push notification systems enable instantaneous shift change propagation. Hospitality and retail frontline managers leverage these to fill coverage gaps within minutes rather than hours.
- Reporting Tools:Compliance documentation and labor analytics dashboards serve audit and optimization use cases. GDPR-mandated consent reporting is emerging as a specialized sub-requirement in European deployments.
Automated Scheduling leads on scale; Real-Time Updates leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital networks in the United States anchor procurement volume for shift planning platforms, while GDPR enforcement and data residency mandates reshape vendor selection criteria across European healthcare systems.
United States
Large hospital networks and retail chains drive demand for algorithmic scheduling engines with FDA 21 CFR Part 11 compliance. OSHA recordkeeping integration is becoming mandatory for manufacturing facilities in automotive and electronics assembly clusters. Greater Boston and the Pacific Northwest host dense concentrations of SaaS vendors serving healthcare buyers with multi-site rollout requirements.
Germany
GDPR Article 44-49 data transfer restrictions filter vendor shortlists to providers with EU-based server clusters in Frankfurt or Dublin. Hospital procurement committees require explicit third-country transfer prohibitions in data processing agreements. Bavaria and North Rhine-Westphalia concentrate manufacturing facilities mandating automated hour-logging against safety incident databases.
United Kingdom
NHS trusts prioritize cloud deployment models that eliminate server maintenance overhead across dispersed clinic networks. UKG leverages deep workforce management heritage to anchor enterprise hospital contracts in London and the Southeast. CNIL-aligned consent architectures are embedding into procurement specifications following post-Brexit data adequacy negotiations.
France
Municipal transit authorities maintain legacy preferences for on-premises installations with strict network isolation policies. ANSM documentation standards shape buyer expectations for audit trails in scheduling systems across Île-de-France hospital networks. The country's national pharmaceutical regulator influences compliance tooling requirements in clinical research settings.
Netherlands
Warehouse and logistics operators in the Randstad region drive fastest adoption of mobile application interfaces for deskless worker populations. Dutch healthcare buyers prioritize SaaS models for clinic network expansion despite emerging data sovereignty requirements. Eindhoven's manufacturing clusters are integrating predictive scheduling with POS traffic pattern analysis.
Shift Planning Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors race to embed shift planning modules into broader workforce management suites. The vendor base organizes around three tiers: ERP-native incumbents with scheduling extensions, pure-play workforce management specialists, and emerging mobile-first point solutions. Two archetypes define competitive positioning: unified HCM-to-scheduling architectures versus best-of-breed algorithmic engines. M&A activity and API ecosystem expansion represent the dominant competitive moves as buyers resist proprietary data lock-in.
Within the enterprise healthcare tier, UKG and Dayforce exemplify contrasting strategic bets—one leveraging decades of workforce management heritage, the other competing through unified human capital management integration. Oracle and SAP occupy positions as ERP-native incumbents extending deployment advantages into manufacturing accounts with existing infrastructure relationships. QGenda represents the specialist archetype, anchoring market presence through vertical depth in clinical scheduling rather than horizontal platform breadth.
| Leading Market Players |
|---|
| UKG |
| Dayforce |
| Workday |
| QGenda |
| ADP |
| Oracle |
| SAP |
| Planday |
| Humanity |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure cost indices cascade through SaaS vendor pricing tiers, compressing margins for US-hosted platforms while EU data residency requirements inflate regional pricing premiums by 15-20% for compliant Frankfurt and Dublin server clusters.
Pricing Analysis
Input-cost pass-through from cloud compute and storage services drives SaaS subscription pricing stratification across deployment tiers. Pricing separates enterprise-grade FDA-validated suites with audit trail documentation from mid-market offerings and entry-level departmental tools without compliance certification. Cost compression in the mid-tier intensifies as hyperscaler infrastructure commoditizes, forcing vendors toward value-added AI forecasting modules. Regional hospital systems exhibit highest price sensitivity due to constrained IT budgets, while large US hospital networks prioritize compliance over cost.
Supply Chain Analysis
Logistics and freight cost escalation in semiconductor delivery channels feeds into server hardware lead times, indirectly constraining vendor capacity expansion timelines. Software development talent concentrates in the United States, Germany, and India, with algorithmic engineering expertise clustering around Boston, Berlin, and Bangalore. The supply chain draws from hyperscaler infrastructure providers, specialized HL7/FHIR interoperability consultants, and mobile development studios. Single-source vulnerability sits with AWS, Azure, and GCP dominance in healthcare cloud hosting. Distribution runs through direct enterprise sales teams, value-added resellers, and viral freemium self-serve channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GDPR Article 44-49 enforcement creates a 15-20% cost arbitrage between US-hosted SaaS platforms and EU data-resident alternatives, rewarding vendors with flexible regional infrastructure deployment.
For Market Incumbents: Anticipate margin compression from AI-native scheduling entrants by accelerating predictive forecasting module roadmaps and hardening API interoperability layers against point-solution fragmentation. Defensive consolidation through specialist acquisitions in clinical scheduling verticals preserves enterprise hospital contract renewals against unified HCM suite competition.
For New Entrants and Emerging Players: Mobile-first shift swapping architectures with real-time notification systems offer the most penetrable wedge into deskless worker populations in warehouse and logistics verticals. Target German and Dutch manufacturing clusters with OSHA-aligned hour-logging integrations. Freemium departmental adoption bypasses centralized procurement friction in US retail and hospitality.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing FDA 21 CFR Part 11 validation infrastructure and existing hospital network references. Long-term viability favors vendors bridging algorithmic scheduling depth with modular HCM integration flexibility. Watch for inflection when state-level US privacy legislation multiplies beyond California, forcing multi-jurisdictional compliance tooling demand.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Data Center Expansion | Frankfurt and Dublin clusters satisfy GDPR Article 44-49 transfer restrictions for hospital procurement committees. |
| AI Forecasting Module Launch | Machine learning demand prediction overtakes static templates in quick-service restaurant and grocery chains. |
| HL7/FHIR Interoperability Investment | Healthcare-compliant data exchange layers accelerate sales cycles through FDA validation timelines. |
| Mobile-Native Platform Development | Smartphone-native interfaces capture deskless worker expansion in warehouse and logistics verticals. |
| Strategic Partnership with Hyperscalers | AWS, Azure, and GCP alliances ensure regional hosting flexibility for data sovereignty requirements. |
Research Methodology
Multiple input streams — primary interviews with workforce management executives, IT procurement officers at hospital networks, and platform integration specialists; secondary validation against SEC filings, hyperscaler capex disclosures, and hospital procurement databases; plus customs records for software services trade — were reconciled through bottom-up and top-down triangulation.
Historical adoption curves were cross-referenced against panel input from CTOs and HR technology leads to model deployment velocity across cloud, hybrid, and on-premises architectures. Segmentation dimensions included organization size, vertical regulatory cluster, integration complexity, and regional data residency pattern. CAGRs were derived from algorithmic constraint-solving adoption rates and mobile interface penetration curves.
The model holds under stable regulatory enforcement timelines; deviation in GDPR interpretation stringency or OSHA recordkeeping mandate expansion would shift vendor competitive positioning. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
CAM Software Market
Software & Services
France HR Payroll Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
Productivity Software Publishing Market
Software & Services
Global Membership Management Software Market
Software & Services
Microsoft Office 365 Integration Services Market
Software & Services
Software Release Management Tools Market
Software & Services
Android Emulator Market
Software & Services
SRM Software Market
Software & Services
Global Voip Software Market
Software & Services
Financial Corporate Performance Management (FCPM) Software Market
Software & Services
Network Documentation Software Market
Software & Services
Asia-Pacific ERP Software Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Global Software Resellers Market
Software & Services
Mobile Application Stores Market