
 Legal AI Software Market | 2026-2036
Legal AI Software Market Size, Share, and Industry Trends Forecast 2026-2036
Legal AI Software Market Insights
Subscription-based deployment is shifting how legal AI vendors monetize their platforms, moving buyers from perpetual licenses toward recurring revenue models. LexisNexis leverages its vast proprietary legal database to anchor AI training pipelines for research automation. Harvey competes by positioning generative AI for elite law firm workflows, while Ironclad specializes in contract lifecycle management with embedded machine learning for clause extraction.
Legal AI software encompasses computational systems that apply natural language processing and machine learning to analyze legal documents, extract obligations, predict outcomes, and automate drafting workflows, operating primarily on unstructured text corpora such as contracts, case law, and regulatory filings. The technology serves commercial and governmental users by compressing review timelines and surfacing risk patterns that manual processes overlook. Contract analysis captures substantial margin pools as enterprises prioritize pre-execution risk identification over post-signature management. E-discovery sustains mature revenue bases amid litigation volume, while legal research represents the fastest-expanding segment as generative AI reduces query-to-answer latency for practitioner queries.
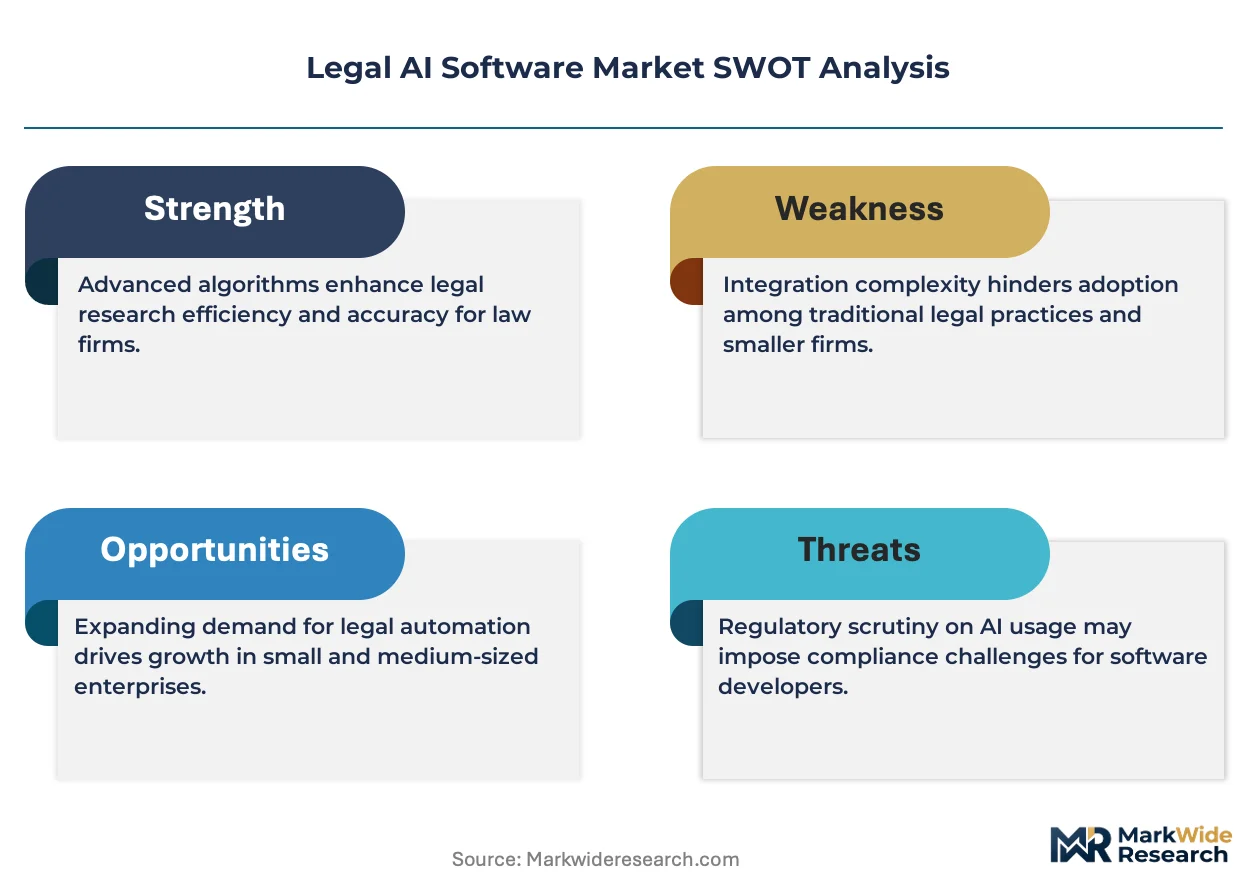
The EU AI Act imposes risk-classification obligations on legal AI providers operating in Europe, pushing vendors toward explainable model architectures and human-in-the-loop validation. The SEC and FTC in the United States scrutinize AI-generated advice for investment and consumer protection compliance, shaping product design requirements for cross-border deployment. ISO standards for AI management systems are gaining traction as procurement criteria for corporate legal departments evaluating vendor risk. Stakeholders must monitor how divergent regulatory timelines across jurisdictions affect product roadmaps and certification investments.
Market Dynamics
Generative AI architectures are compressing query-to-insight timelines for legal practitioners, forcing incumbent research platforms to retrain proprietary models on annotated case law corpora or cede share to specialized challengers.
Growth Catalysts
- EU AI Act risk-classification mandates:European compliance obligations favor auditable AI systems with human-in-the-loop validation, accelerating procurement of explainable contract analysis platforms by multinational corporate legal departments.
- Corporate legal department automation priorities:Enterprise buyers are redirecting budget from billable hour containment toward pre-execution contract risk identification, expanding addressable spend for clause extraction and obligation management tools.
- Natural language processing pipeline maturation:Transformer-based architectures trained on legal corpora now achieve sub-second inference on multi-thousand-page document sets, collapsing due diligence timelines that previously required associate attorney teams.
Market Restraints
- Training data access concentration:Comprehensive annotated legal datasets remain concentrated among established information services providers, creating barriers for new entrants seeking to match retrieval accuracy on case law and regulatory precedent.
- Cross-border regulatory friction:Divergent AI governance timelines between the EU AI Act, SEC disclosure requirements, and emerging frameworks in Asia-Pacific jurisdictions force vendors to maintain multiple product variants, inflating compliance engineering costs.
- Substitution by managed legal services:Alternative legal service providers offering offshore attorney review at compressed rates compete directly with AI-powered contract analysis for cost-sensitive mid-market buyers.
Strategic Opportunities
- Underpenetrated mid-market law firms:Firms with 50-200 attorneys in the United States lack dedicated legal operations functions, creating whitespace for vertically integrated platforms combining research, drafting, and practice management.
- Regulatory tailwind from ISO 42001:The emerging AI management systems standard is gaining traction as a procurement criterion, enabling early-certified vendors to differentiate in enterprise RFP processes.
- Convergence of contract lifecycle management and e-signature workflows:Integration of machine learning clause extraction with execution platforms creates stickier deployments and expands per-seat pricing potential.
Industry Challenges
- Attorney trust calibration:Practitioners require transparent model provenance and source attribution to rely on AI-generated research, demanding engineering investment in explainability interfaces that slow product velocity.
- Legacy practice management system integration:Time-and-billing software, document management systems, and conflict checking databases use fragmented data architectures, complicating unified workflow deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legal AI Software Market |
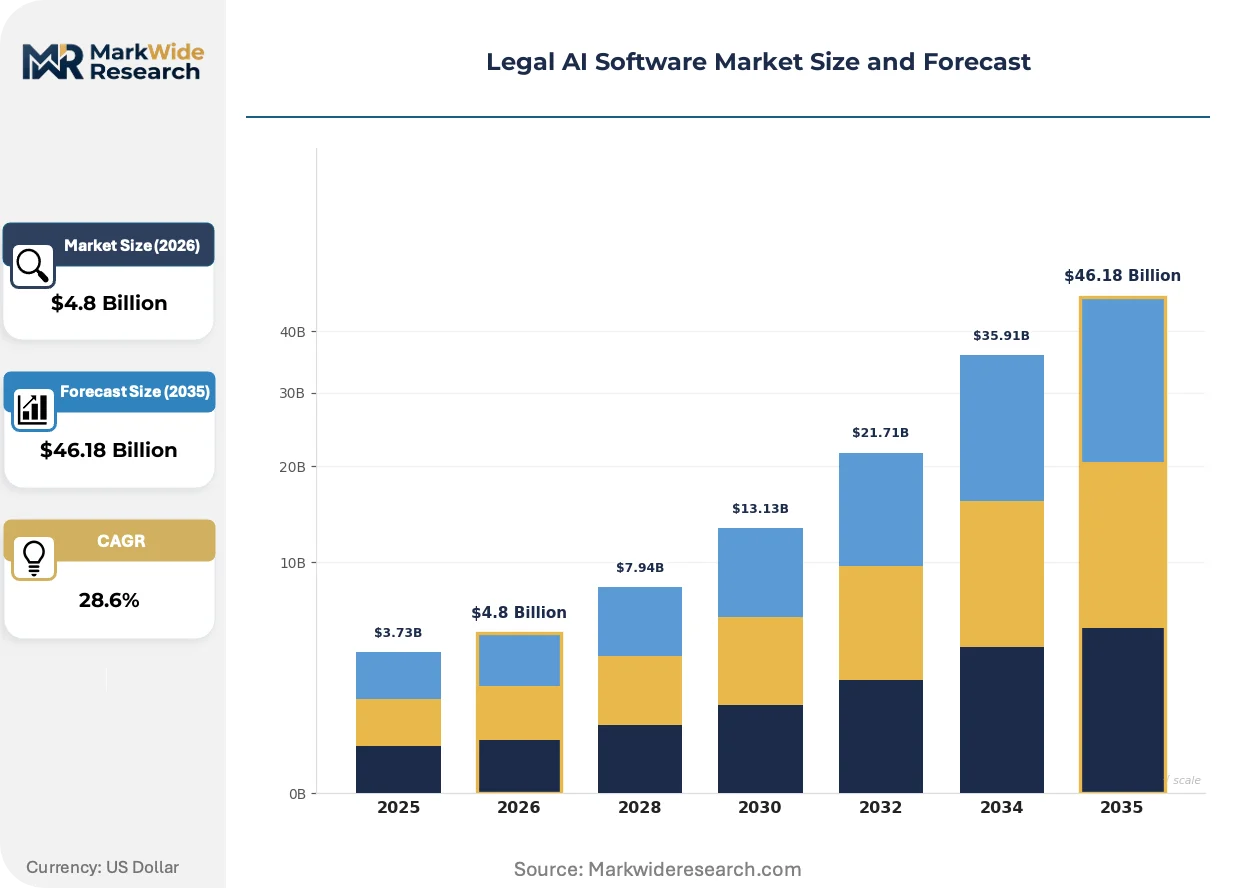
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contract Analysis, E-Discovery, Legal Research, Document Automation Client Type: Law Firms, Corporate Legal Departments, Government Agencies, Solo Practitioners Deployment: Cloud-Based, On-Premises, Hybrid, Subscription-Based Technology: Natural Language Processing, Machine Learning, Predictive Analytics, Knowledge Management |
| Companies Covered | Everlaw, LexisNexis, Brightflag, Kira Systems, Luminance, Harvey, Casetext, Ironclad, Relativity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legal AI Software Market Trends and Innovations
Multimodal AI systems are expanding beyond text analysis to process deposition video, audio recordings, and handwritten evidentiary materials, creating new competitive vectors beyond traditional NLP capabilities.
Retrieval-augmented generation architectures are unifying large language model outputs with proprietary legal databases, enabling platforms to cite verifiable sources rather than hallucinate precedent. Elite law firms in the United States and United Kingdom are piloting these systems for brief drafting and regulatory comment preparation. This unification is compressing the traditional research-to-drafting workflow from hours to minutes, threatening hourly billing models.
The EU AI Act's high-risk system classification for legal AI used in judicial or administrative proceedings is forcing vendors to implement conformity assessment procedures and post-market monitoring. European national regulators are beginning to coordinate enforcement approaches. Vendors targeting cross-border deployment are prioritizing European certification to preempt market access barriers.
Corporate legal departments are consolidating vendor relationships around integrated platforms rather than point solutions for contract analysis, research, and matter management. This consolidation favors vendors with broad functional coverage and API extensibility. The United States exhibits the most visible concentration, with Fortune 500 legal operations teams reducing preferred vendor lists from twelve to three or four strategic partnerships.
Legal AI Software Market Segmentation
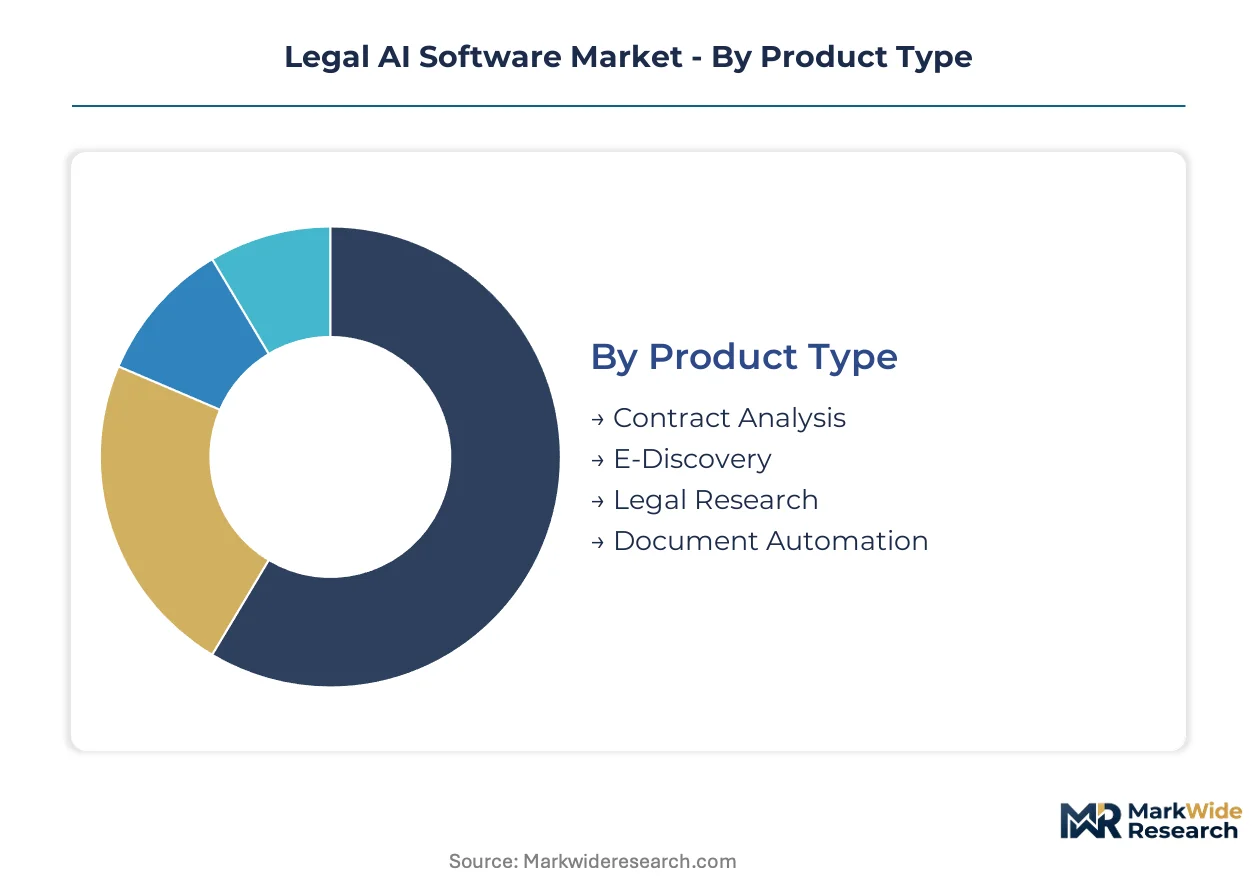
Segmentation in legal AI software reveals how buyer priorities diverge across practitioner workflows, compliance postures, and technology maturity. Understanding these splits enables vendors to calibrate pricing, feature depth, and sales motion to specific procurement contexts rather than pursuing undifferentiated platform strategies.
Product Type:
Buyer investment priority follows document volume intensity and risk exposure timing, with pre-execution tools commanding premium pricing over post-signature or reactive applications.
- Contract Analysis:Clause extraction engines trained on annotated agreement corpora identify indemnification, termination, and liability provisions across multi-thousand-page document sets. Corporate legal departments in the United States prioritize these tools to compress third-party paper review cycles ahead of execution deadlines. The segment leads on scale.
- E-Discovery:Technology-assisted review platforms apply machine learning to privilege identification and responsive document classification in litigation contexts. Law firms with active securities and antitrust practices sustain mature deployment bases despite compressed matter timelines. This segment leads on momentum.
- Legal Research:Retrieval-augmented generation systems unify large language model outputs with proprietary case law databases to surface precedent with verifiable citations.
- Document Automation:Template-driven drafting systems populate standard agreements from structured intake questionnaires, reducing associate attorney hours on repetitive documentation.
Contract analysis captures the largest addressable spend; legal research climbs fastest as generative AI compresses query-to-answer latency.
Client Type:
Procurement authority and budget source determine sales cycle length, with enterprise legal operations teams consolidating vendor relationships faster than distributed practitioner bases.
- Law Firms:AmLaw 200 firms in the United States deploy integrated platforms across research, drafting, and matter management to defend realization rates against alternative legal service providers. Mid-market firms with 50-200 attorneys represent underpenetrated whitespace lacking dedicated legal operations functions.
- Corporate Legal Departments:Fortune 500 legal operations teams redirect budget from outside counsel containment toward pre-execution risk identification, expanding clause extraction and obligation management procurement. These buyers concentrate demand in the United States.
- Government Agencies:Public sector procurement emphasizes auditable decision trails and explainable model architectures to satisfy administrative procedure requirements.
- Solo Practitioners:Individual attorneys prioritize cost-accessible research tools with per-matter pricing over platform subscriptions requiring operational overhead.
Corporate legal departments drive volume concentration; law firms exhibit steepest expansion trajectory as competitive pressure forces technology adoption.
Deployment:
Data sovereignty requirements and integration complexity shape infrastructure choices, with regulated industries maintaining on-premises or hybrid configurations despite cloud-native feature velocity.
- Cloud-Based:Multi-tenant SaaS architectures enable sub-second model inference and continuous training pipeline updates without client-side infrastructure investment. Financial services and healthcare legal teams in the United States increasingly accept cloud deployments where SOC 2 and ISO 27001 certifications satisfy risk committees.
- On-Premises:Air-gapped installations host models and document corpora within client data centers to address classified matter handling and foreign data transfer restrictions. National security and intelligence community legal offices require these configurations.
- Hybrid:Split architectures process sensitive documents locally while leveraging cloud inference for non-privileged workflows, balancing latency and compliance.
- Subscription-Based:Recurring revenue models displace perpetual licenses across all infrastructure types, aligning vendor incentives with client success metrics and expanding addressable markets through lower initial commitments.
Cloud-based deployments dominate new procurement; hybrid configurations gain share fastest in regulated industries with compartmentalized security requirements.
Technology:
Underlying architecture sophistication determines competitive differentiation, with transformer-based natural language processing now table stakes and multimodal capabilities emerging as the next capability frontier.
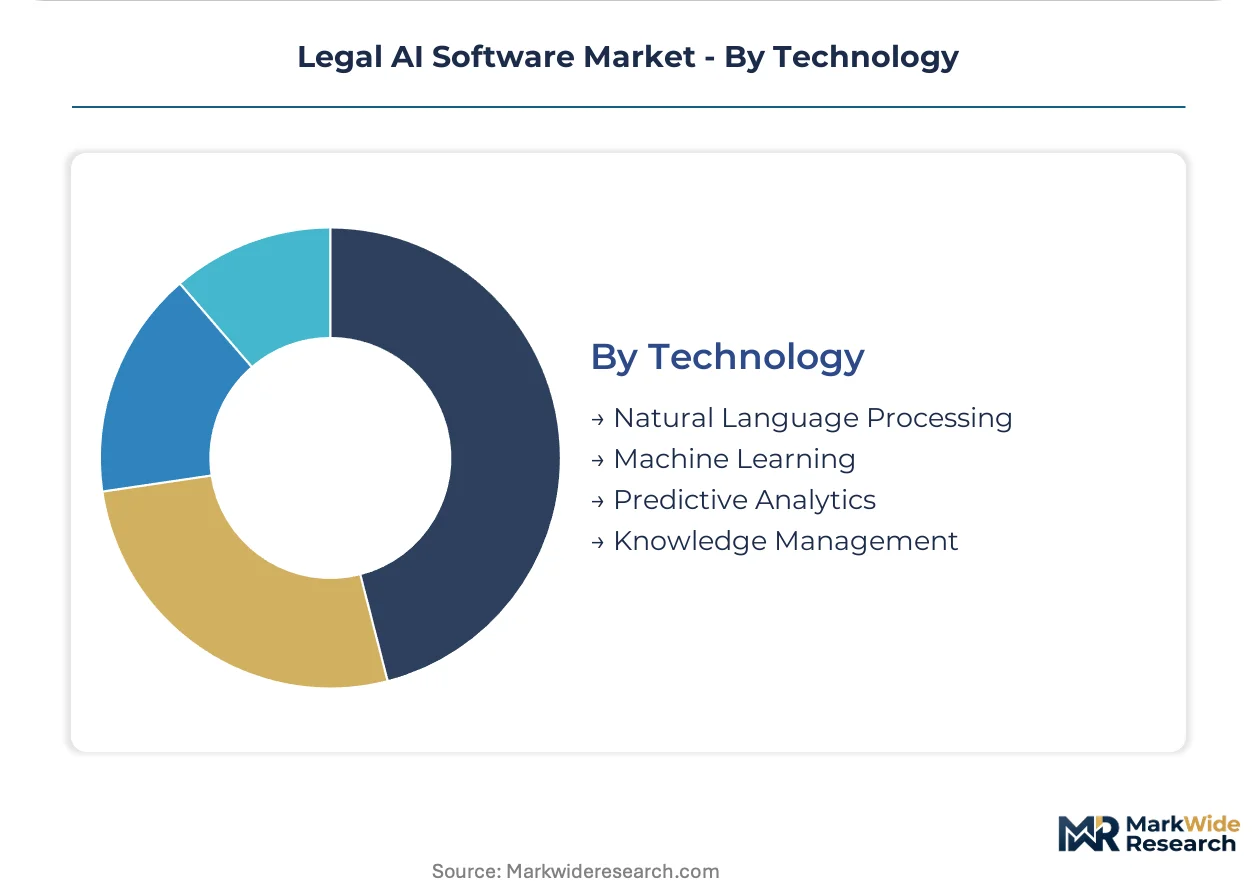
- Natural Language Processing:Transformer architectures trained on legal corpora achieve semantic understanding of contractual obligations, regulatory requirements, and judicial reasoning patterns. These pipelines power core functionality across contract analysis, research, and drafting applications.
- Machine Learning:Supervised classification models trained on attorney-labeled document sets automate privilege review, responsive determination, and clause extraction with measurable accuracy against manual benchmark reviews.
- Predictive Analytics:Outcome modeling applies historical case data to forecast litigation duration, settlement ranges, and judicial behavior, supporting resource allocation and strategy decisions.
- Knowledge Management:Enterprise search and expertise location systems capture and surface internal precedent, deal terms, and practitioner specializations to prevent reinvention and accelerate matter staffing.
Natural language processing anchors platform functionality; predictive analytics expands most quickly as data asset accumulation enables model refinement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing Legal AI Software Market investment as vendors seek jurisdictions with clearer compliance pathways and lower certification friction. The United States, United Kingdom, Germany, Japan, and Singapore each present distinct cost-of-compliance profiles that shape vendor market entry sequencing.
United States
SEC disclosure requirements and FTC consumer protection scrutiny are accelerating procurement of auditable AI systems by Fortune 500 legal operations teams. New York and Washington DC host the densest concentrations of elite law firms deploying NLP-powered platforms for due diligence. The American Bar Association's evolving guidance on AI competency is creating procurement pressure across AmLaw 200 firms.
United Kingdom
The Solicitors Regulation Authority's technology competence mandate is driving mid-market law firm adoption of contract analysis tools. London's financial services legal cluster prioritizes explainable model architectures for regulatory submission workflows. Post-Brexit divergence from EU AI Act timelines is creating interim uncertainty for cross-border deployment strategies.
Germany
Federal data protection authorities are enforcing GDPR Article 22 restrictions on automated legal decision-making, favoring human-in-the-loop validation architectures. Frankfurt's banking legal sector and Munich's technology law practices are consolidating vendor relationships around ISO 42001-certified platforms. The KBA's emerging AI governance framework for automotive legal compliance is creating specialized demand.
Japan
METI's AI governance guidelines for enterprise deployment are shaping procurement criteria for corporate legal departments in Tokyo and Osaka. The Japan Federation of Bar Associations' caution toward generative AI in litigation contexts is slowing adoption relative to contract analysis applications. Osaka's growing fintech legal cluster is piloting machine learning clause extraction for cross-border transaction documentation.
Singapore
The Monetary Authority of Singapore's AI governance framework for financial services is creating reference architectures adopted by legal technology vendors across Southeast Asia. Singapore's arbitration hub status is driving demand for multilingual contract analysis capable of processing English, Mandarin, and Bahasa Indonesia documentation. The country's data sovereignty requirements favor hybrid deployment configurations for regional headquarters legal functions.
Legal AI Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with research automation platforms exhibiting greater concentration than contract lifecycle management tools. The vendor base organizes into three tiers: established information services providers with proprietary legal databases, generative AI challengers targeting elite law firm workflows, and vertical specialists embedding machine learning in specific practice areas. Consolidation pressures are intensifying as enterprise legal operations teams reduce preferred vendor lists, while technology licensing partnerships enable faster feature parity for mid-tier competitors.
Within the established information services tier, LexisNexis anchors a position built on decades of annotated case law accumulation, while Harvey occupies a position exemplifying the generative AI challenger archetype targeting premium law firm segments. Ironclad represents the vertical specialist model, embedding machine learning capabilities within contract lifecycle management workflows. These three companies collectively illustrate the strategic segmentation defining competitive positioning: database depth versus architectural innovation versus workflow integration.
| Leading Market Players |
|---|
| Everlaw |
| LexisNexis |
| Brightflag |
| Kira Systems |
| Luminance |
| Harvey |
| Casetext |
| Ironclad |
| Relativity |
| Others |
Pricing and Supply Chain Analysis
GPU compute pricing indices from hyperscaler spot markets cascade through legal AI vendor cost structures, compressing margins for training-intensive platforms while rewarding inference-optimized architectures with pricing flexibility across enterprise tiers.
Pricing Analysis
Distributor margins in legal AI software rarely exceed single-digit percentages because direct-to-enterprise sales dominate procurement channels. Subscription-based SaaS tiers anchor the dominant pricing model, with differentiation driven by API call volume entitlements and SOC 2 certification status. Cost compression in mid-market segments stems from alternative legal service providers offering hybrid human-AI review at compressed rates. Corporate legal departments exhibit lowest price sensitivity due to outside counsel budget reallocation, while solo practitioners face acute affordability constraints.
Supply Chain Analysis
Freight costs exert minimal direct pressure on legal AI supply chains because software distribution is entirely digital, though data center energy pricing in Northern Virginia and Frankfurt indirectly shapes hosting economics. Model development concentrates in the United States, United Kingdom, and Canada, drawing from annotated case law corpora, synthetic training data, and transformer compute clusters. Single-source vulnerability rests on hyperscaler cloud infrastructure concentration. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Legal AI software functions as a stable compounder anchored by regulatory compliance mandates that perpetually refresh procurement cycles across corporate and governmental buyers.
For Market Incumbents: Anticipate generative AI challengers eroding research automation margins by retraining open-source models on public legal corpora. Defend position by deepening proprietary database moats through exclusive court filing partnerships and accelerating ISO 42001 certification to preempt procurement gatekeeping. Channel control through embedded workflow integrations represents the critical retention lever. For New Entrants and Emerging Players: The premium-to-economy pricing gap in contract analysis tools exceeds five-fold, creating accessible entry points for mid-market law firms lacking dedicated legal operations. Target United States-based firms with 50-200 attorneys through vertically integrated platforms combining clause extraction with practice management. Go-to-market through state bar association endorsed partnerships reduces customer acquisition friction. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists embedding machine learning in regulatory compliance workflows rather than horizontal research platforms facing commoditization. Long-term viability favors vendors with captive training data generation through matter management system usage. Watch EU AI Act enforcement consistency as the inflection signal for European market access valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Retrieval-Augmented Generation Deployment | Unifies LLM outputs with proprietary case law databases to eliminate hallucination risk in judicial filings. |
| ISO 42001 Certification Investment | Enables differentiation in Fortune 500 RFP processes where AI management systems standards gain procurement traction. |
| Contract Lifecycle Management Integration | Embeds clause extraction within e-signature workflows to expand per-seat pricing and reduce churn. |
| Mid-Market Law Firm Platform Launch | Captures whitespace among 50-200 attorney practices lacking dedicated legal operations functions. |
| EU AI Act Conformity Assessment | Secures market access for high-risk system classifications in European judicial and administrative proceedings. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with legal operations directors, AmLaw 200 technology committee chairs, corporate procurement officers, and AI ethics compliance leads informed demand-side perspectives. Secondary sources include SEC disclosure filings, EU AI Act implementation guidance, state bar association technology surveys, and hyperscaler AI infrastructure expenditure reports. Bottom-up vendor revenue estimates triangulate against top-down legal technology spending allocations.
Granularity-level modeling distinguishes deployment modes, organization size tiers, and practice area specializations across the projection horizon. Segmentation dimensions include product type, client category, infrastructure configuration, and underlying technology architecture. CAGRs derive from fitted growth curves calibrated to adoption velocity patterns in comparable enterprise software categories. Forecast inputs incorporate regulatory timeline assumptions and training data accessibility trajectories.
Caveats apply where EU AI Act enforcement divergence or SEC disclosure requirement expansion could materially shift the outlook. Forecasts reflect assumptions about attorney trust calibration timelines and legacy system integration friction. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
North America Conversational AI Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Multimodal AI Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
AI Datasets Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Consumer Facing AI Products Market
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
Edge AI Software Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market