
 Mlops Market | 2026-2036
Mlops Market Size, Share, and Industry Trends Forecast 2026-2036
Mlops Market Analysis
The capital-intensity divergence between hyperscaler-backed platforms and specialist tooling vendors is redrawing competitive boundaries in MLOps infrastructure. Amazon Web Services leverages its integrated SageMaker-Vertex AI compute stack to anchor enterprise retention. Domino Data Lab differentiates through governance-centric workflows that sustain premium pricing in regulated sectors.
MLOps denotes the engineering discipline for automating machine learning lifecycle management, encompassing model training orchestration, feature store governance, and inference monitoring through CI/CD pipelines. Cloud-Based Solutions dominate procurement as enterprises prioritize elastic compute for training workloads, while Hybrid Solutions capture growing share among organizations managing sovereign data requirements across public and private infrastructure. Large Enterprises represent the primary service-type revenue pool, though Startups drive fastest adoption velocity for Open Source Tools to avoid vendor lock-in.
The EU AI Act and FDA guidance on AI-enabled medical devices impose divergent compliance architectures that fragment platform standardization. ISO/IEC 23053 and NIST AI Risk Management Framework shape procurement criteria for cross-border deployments. Stakeholders must monitor regulatory divergence between Brussels and Washington to anticipate certification burdens that reshape total cost of ownership.
Market Dynamics
Regulatory fragmentation between the EU AI Act and FDA guidance on AI-enabled medical devices is forcing platform vendors to maintain multiple compliance architectures simultaneously, inflating engineering overhead and slowing standardization.
Growth Catalysts
- FDA AI/ML-Based Software as Medical Device (SaMD) Guidance:Healthcare enterprises in the United States accelerate MLOps procurement to automate documentation trails for algorithm change control protocols.
- Cloud hyperscaler compute stacks:Elastic GPU clusters reduce training infrastructure capital requirements for mid-market financial services firms deploying real-time fraud detection pipelines.
- Feature store governance automation:Retail and logistics operators adopt centralized feature repositories to eliminate training-serving skew across distributed inference endpoints.
Market Restraints
- Specialized MLOps engineering talent scarcity:Organizations face 6-12 month hiring cycles for practitioners with production-grade Kubernetes and ML pipeline orchestration expertise.
- NVIDIA GPU supply concentration:Training workload elasticity remains constrained by single-source dependency on advanced semiconductor fabrication capacity.
- EU AI Act documentation mandates:Risk-classification requirements for high-risk AI systems impose 30-40% additional platform customization costs for European deployments.
Strategic Opportunities
- Sovereign cloud infrastructure in Germany and France:National data localization requirements create demand for hybrid MLOps platforms operating across public and government-certified private clouds.
- Edge inference optimization for manufacturing:Convergence of TinyML runtimes with 5G private networks enables sub-10 millisecond quality control automation at production lines.
- ISO/IEC 23053 framework alignment:Vendors certifying against this AI system lifecycle standard gain preferential procurement status in cross-border enterprise RFPs.
Industry Challenges
- Legacy data warehouse integration:Enterprise MLOps deployments require 8-14 month migration timelines to connect modern feature stores with on-premise Hadoop and Teradata environments.
- Model reproducibility certification:Financial regulators in the United States and European Union demand version-controlled experiment tracking that most open-source tooling lacks natively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mlops Market |
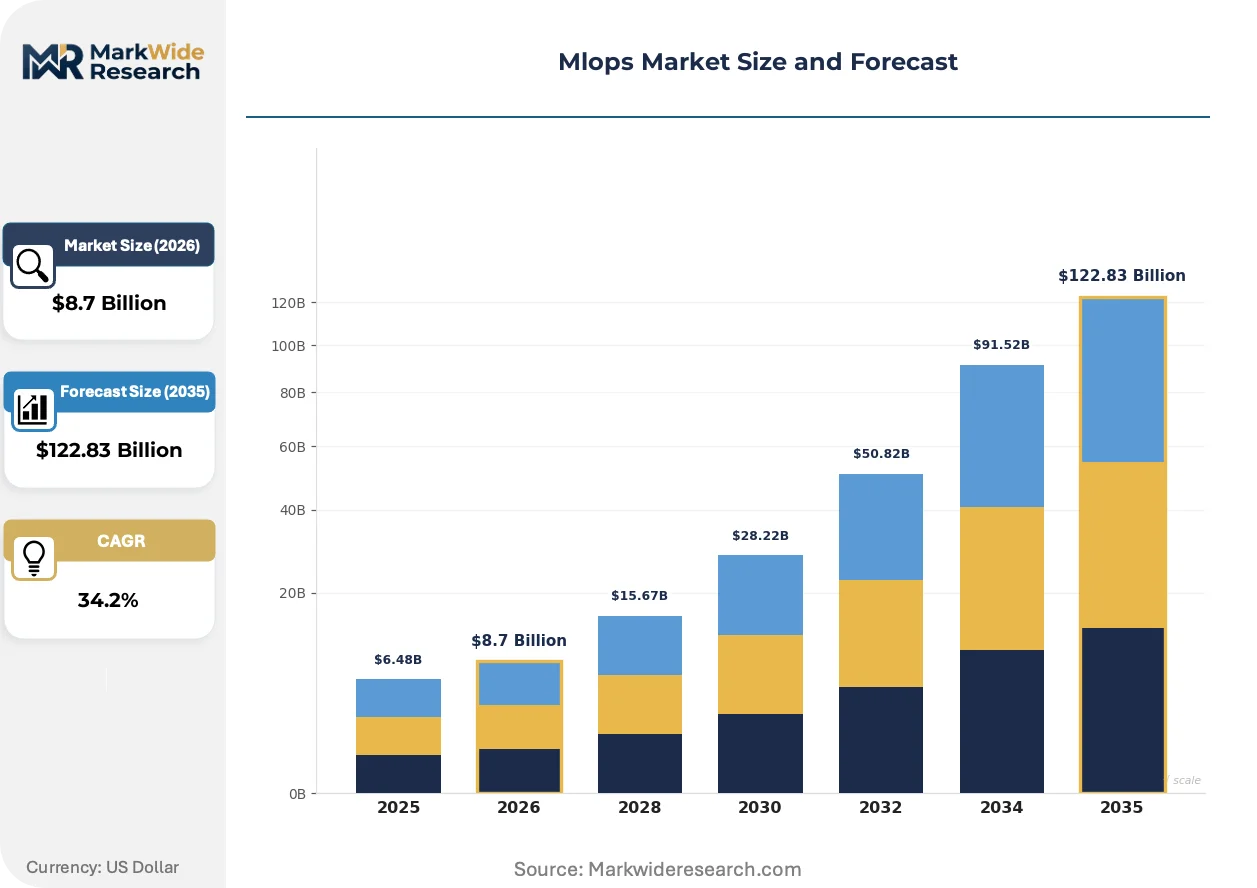
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $122.83 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Solutions, Hybrid Solutions, Open Source Tools Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Edge Computing End User: Small Enterprises, Large Enterprises, Startups, Research Institutions Service Type: Consulting Services, Integration Services, Managed Services, Support Services |
| Companies Covered | Databricks, DataRobot, Amazon Web Services, Google, Microsoft, IBM, Domino Data Lab, Vertex AI, Amazon SageMaker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mlops Market Emerging Trajectories
Foundation model fine-tuning pipelines are compressing the traditional ML lifecycle from months to weeks, forcing incumbent platform vendors to rearchitect orchestration layers around parameter-efficient adaptation methods rather than full retraining workflows.
Automated machine learning (AutoML) orchestration is supplanting manual hyperparameter tuning across enterprise data science teams. Mid-market manufacturers without dedicated ML engineering functions adopt managed AutoML services to deploy predictive maintenance models within 30-day implementation windows. This capability compression is eroding pricing power for boutique consulting arrangements that previously dominated industrial AI adoption.
The EU AI Act's risk-based classification system imposes documentation and human oversight mandates on high-risk AI applications including credit scoring and medical diagnosis. Platform vendors must embed model cards, bias auditing, and explainability modules directly into CI/CD workflows. European financial institutions now require MLOps vendors to demonstrate conformity assessment procedures before contract execution.
Consumption-based pricing for training compute is displacing reserved instance commitments among venture-backed AI startups. These organizations prioritize granular cost attribution across experiments to extend runway, favoring platforms with per-second billing and automatic workload suspension. This pattern is most pronounced in the United States, where cloud marketplace procurement accelerates vendor switching.
Mlops Market Segmentation
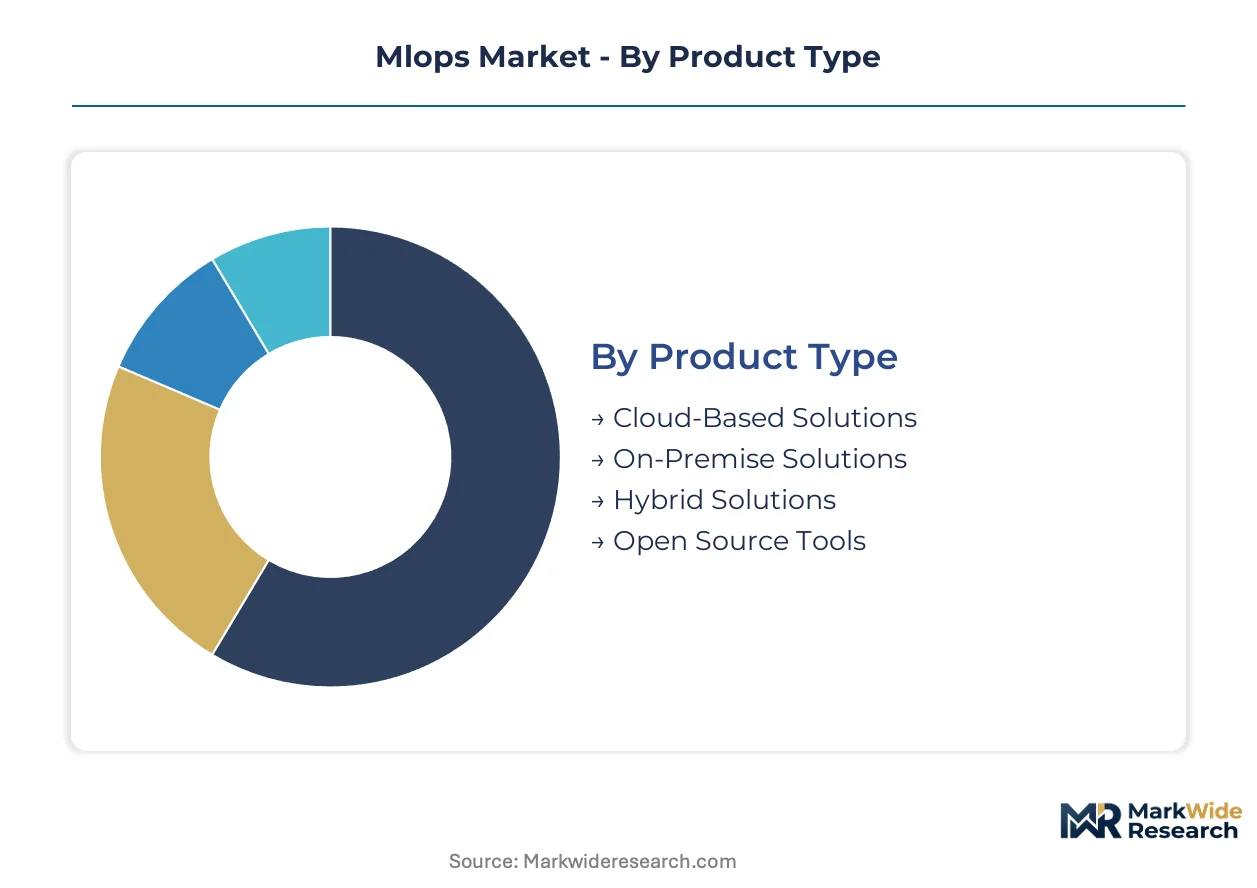
MLOps procurement patterns diverge sharply across infrastructure preferences and organizational maturity. Platform vendors must align delivery models with customer scale, compliance posture, and cloud-native readiness to capture wallet share.
Product Type:
Cloud hyperscalers dominate channel economics for elastic training workloads, while specialist vendors capture margin through sovereign and hybrid configurations.
- Cloud-Based Solutions:Fully managed infrastructure abstracts Kubernetes orchestration and GPU cluster management. Financial services firms in the United States favor consumption-based billing for fraud detection model retraining cycles.
- Hybrid Solutions:Split architectures route sensitive feature engineering to private infrastructure while pushing inference to public endpoints. German automotive manufacturers deploy these configurations to satisfy national data localization requirements.
- On-Premise Solutions:Air-gapped deployments serve defense and intelligence agencies with classified training datasets.
- Open Source Tools:Kubeflow and MLflow adoption concentrates among venture-backed startups avoiding vendor lock-in.
By volume, Cloud-Based Solutions leads. By growth pace, Hybrid Solutions is expanding most quickly.
Deployment Model:
Cost tier stratification separates commodity public workloads from premium edge and multi-cloud orchestration with specialized latency requirements.
- Public Cloud:Shared infrastructure pools deliver lowest per-hour training costs. Mid-market retailers leverage auto-scaling for seasonal demand forecasting spikes.
- Multi-Cloud:Abstraction layers prevent single-vendor dependency. European pharmaceutical companies adopt these architectures to negotiate compute pricing across AWS, Azure, and GCP.
- Private Cloud:Dedicated tenancy satisfies HIPAA and FDA audit requirements for healthcare AI systems.
- Edge Computing:Containerized inference runtimes deploy to factory floors and autonomous vehicle fleets. Japanese manufacturers prioritize sub-50 millisecond quality control feedback loops.
Public Cloud captures the highest transaction volume. Edge Computing shows the steepest expansion trajectory as 5G private networks mature.
End User:
Customer type determines sales cycle length and solution complexity, with procurement authority concentrating in centralized IT functions.
- Large Enterprises:Dedicated ML engineering teams demand customizable pipelines with enterprise-grade access controls. Banking conglomerates in the United States require FedRAMP-authorized platforms for model governance.
- Startups:Lean technical staff prioritize managed services with minimal configuration overhead. Venture-backed AI companies favor per-second billing to extend runway.
- Small Enterprises:Limited data science headcount drives adoption of AutoML-centric platforms with pre-built model templates.
- Research Institutions:Academic compute grants favor open-source tooling with reproducible experiment tracking for publication requirements.
Large Enterprises dominate current revenue contribution. Startups are gaining share fastest as foundation model APIs lower technical barriers.
Service Type:
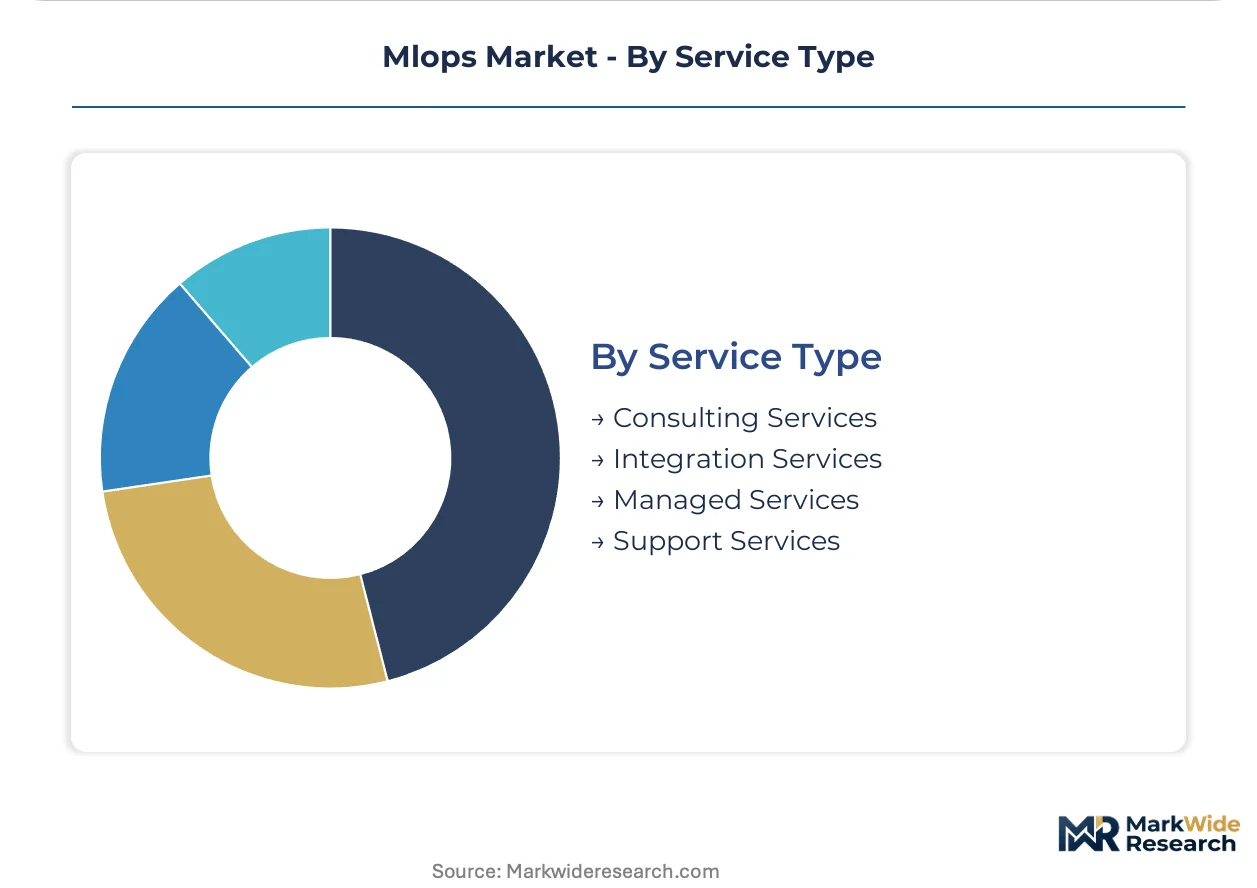
Margin concentration favors recurring managed services over one-time integration engagements, reshaping vendor business models.
- Managed Services:24/7 pipeline monitoring and model drift detection command premium pricing. Healthcare systems in the United States outsource FDA SaMD compliance documentation to specialized providers.
- Consulting Services:Strategic advisory on MLOps maturity assessment and team structure design. French financial institutions engage boutique firms for EU AI Act readiness programs.
- Integration Services:Legacy data warehouse connectivity and feature store migration projects carry 6-14 month timelines.
- Support Services:Tiered response SLAs for production incident resolution with escalating severity protocols.
Managed Services leads by recurring revenue volume. Consulting Services is climbing the fastest as regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity, absorbing premium platform costs for integrated governance stacks. German and French enterprises exhibit moderate sensitivity, trading off sovereignty requirements against hyperscaler efficiency. Indian and Brazilian markets show highest elasticity, with procurement gravitating toward open-source tooling and managed service alternatives.
United States
Venture-backed AI startups and cloud hyperscalers drive platform procurement velocity. FDA AI/ML-Based Software as Medical Device guidance compels healthcare enterprises to automate documentation trails. The San Francisco Bay Area and Seattle tech corridors concentrate MLOps engineering talent and hyperscaler headquarters operations.
Germany
Automotive manufacturers and industrial conglomerates demand hybrid configurations for sovereign data control. National data localization requirements under the EU AI Act shape procurement specifications for high-risk AI systems. Bavarian automotive clusters and Stuttgart engineering hubs deploy edge-optimized pipelines for factory-floor quality control.
United Kingdom
Financial services firms in London prioritize model governance automation for algorithmic trading compliance. The Bank of England's operational resilience expectations intersect with EU AI Act documentation mandates for cross-border deployments. The London-Edinburgh corridor hosts specialist MLOps consultancies serving European banking conglomerates.
Japan
Manufacturing enterprises adopt TinyML-integrated MLOps for sub-50 millisecond inference on production lines. METI industrial digitalization incentives accelerate private 5G network deployments for edge computing. The Nagoya-Toyota industrial belt leads adoption of containerized quality control automation.
India
IT services exporters and domestic fintechs drive fastest adoption velocity for open-source tooling. RBI guidelines on AI governance in financial services create compliance demand for model risk management platforms. Bengaluru and Hyderabad tech clusters concentrate MLOps engineering talent serving global enterprise clients.
Mlops Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Cloud hyperscalers anchor the integrated-stack segment through elastic compute provisioning and consumption-based billing. Specialist vendors occupy governance-centric niches with premium pricing for regulated industries. The dominant competitive moves center on vertical integration into semiconductor supply chains and strategic partnerships for sovereign cloud certifications.
Among hyperscaler-backed platforms, Amazon Web Services, Google, and Microsoft exemplify the integrated-stack archetype through their managed Kubernetes and GPU cluster abstractions. Databricks and DataRobot occupy positions within the specialist tier, anchoring workflow automation for enterprises without dedicated ML engineering functions. Domino Data Lab sits within the governance-focused segment, serving financial services and healthcare clients with compliance-centric orchestration layers.
| Leading Market Players |
|---|
| Databricks |
| DataRobot |
| Amazon Web Services |
| Microsoft |
| IBM |
| Domino Data Lab |
| Vertex AI |
| Amazon SageMaker |
| Others |
Supply Flow & Price Mechanics
Consumption-based billing contracts lock in supply access to NVIDIA GPU clusters while anchoring price visibility for venture-backed AI startups extending runway. This structure concentrates procurement leverage among cloud hyperscalers and fragments pricing power across specialist MLOps vendors.
Pricing Analysis
Managed service tiers drive lifetime value through 24/7 pipeline monitoring and automated drift detection subscriptions. Pricing stratifies across enterprise governance stacks, mid-market AutoML bundles, and open-source support contracts, with differentiation hinging on FedRAMP authorization and EU AI Act conformity assessment. Cost compression in startup-facing tiers intensifies as per-second billing and automatic workload suspension become table stakes. Indian and Brazilian buyers exhibit highest price sensitivity, gravitating toward Kubeflow and MLflow alternatives, while United States financial services firms absorb premium costs for integrated compliance automation.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes amplify lead time volatility for GPU server shipments destined to European sovereign cloud facilities. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with advanced node capacity feeding NVIDIA accelerator production. The MLOps infrastructure stack draws from specialized memory components, high-bandwidth interconnects, and custom ASIC designs. Single-source dependency on TSMC advanced packaging creates vulnerability to geopolitical export controls. Distribution runs through hyperscaler-owned data centers, specialist systems integrators, and government-certified private cloud operators serving defense and intelligence clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MLOps platform economics are approaching an interoperability inflection as foundation model APIs collapse technical barriers and Kubernetes-native tooling standardizes deployment patterns.
For Market Incumbents: Fortify governance-centric differentiation against hyperscaler price compression by embedding EU AI Act conformity assessment and FDA SaMD documentation modules directly into CI/CD workflows. Deepen certification investment in ISO/IEC 23053 alignment to sustain premium positioning in cross-border enterprise RFPs. Channel control through strategic partnerships with sovereign cloud operators in Germany and France defends margin position against multi-cloud abstraction layers. For New Entrants and Emerging Players: Edge inference optimization for manufacturing quality control represents an underserved service-layer gap where incumbents under-serve sub-50 millisecond latency requirements. Target Japanese automotive clusters and German industrial conglomerates deploying TinyML runtimes on private 5G networks. A go-to-market angle anchored to METI digitalization incentives and KBA data localization mandates accelerates penetration without direct hyperscaler competition. For Investors and Strategic Acquirers: Specialist consultancies with EU AI Act readiness programs and boutique FDA SaMD compliance practices constitute the most attractive acquisition target archetype. These assets command scarcity premiums as regulatory divergence between Brussels and Washington deepens certification burdens. The signal to watch is conformity assessment procedure standardization across European financial institutions, which would trigger consolidation demand for pre-certified workflow automation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding governance modules into CI/CD pipelines satisfies EU AI Act mandates for financial services. |
| Strategic Partnership | Sovereign cloud certifications with German and French operators unlock public sector procurement channels. |
| Acquisition of Specialist Firm | Consultancies with FDA SaMD expertise accelerate healthcare compliance automation capabilities. |
| Product Launch | TinyML-optimized edge inference targets manufacturing sub-50 millisecond quality control requirements. |
| Geographic Expansion | Hybrid deployments in India address RBI AI governance guidelines for domestic fintech compliance. |
Methodological Framework
Initial hypotheses were tested against primary input from ML engineering directors, cloud procurement officers, regulatory compliance leads, and healthcare IT architects and refined through secondary validation. Primary interviews concentrated on platform selection criteria, budget allocation patterns, and vendor switching triggers across financial services, healthcare, and manufacturing verticals. Secondary sources encompassed hyperscaler capex disclosures, FDA 510(k) and De Novo filing databases, EU AI Act implementation guidance, and ISO/IEC standard development records. Bottom-up triangulation across customer deployment scales and top-down validation against infrastructure spending forecasts anchored market size estimates.
Variance decomposition across deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segmented growth rate reconciliation across cloud-based, hybrid, and on-premise infrastructure preferences. Industry-specific forecast inputs included foundation model API adoption curves, GPU cluster availability constraints, and sovereign data localization mandate implementation timelines across the analysis window.
Underlying assumptions cover sustained venture capital deployment to AI startups, stable NVIDIA supply allocation to cloud hyperscalers, and phased EU AI Act enforcement without retroactive compliance waivers, with deviation risk concentrated in semiconductor export control expansion and foundation model commoditization velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
Decision Intelligence Market
Artificial Intelligence (AI)
Voice User Interface Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market
Artificial Intelligence (AI)
Cognitive Collaboration Market
Artificial Intelligence (AI)
Intelligent Personal Assistant Market
Artificial Intelligence (AI)
AI Image Recognition Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Global Conversational AI Platform Software Market