
 LED Tube Drivers Market | 2026-2036
LED Tube Drivers Market Size, Share, and Industry Trends Forecast 2026-2036
LED Tube Drivers Market Analytics
Chinese driver assembly capacity is recalibrating as export certification requirements tighten for North American and European destinations. Signify (Philips) leverages its luminaire-to-driver integration to command premium positioning in commercial specification channels. Mean Well Enterprises anchors the mid-power segment through standardized form factors and broad distributor coverage. Inventronics specializes in high-efficiency outdoor-rated platforms that sustain margin pools in industrial retrofit applications.
LED tube drivers are power conversion modules that regulate electrical current to light-emitting diode arrays within linear tube housings, typically operating at power factors above 0.9 and efficiencies exceeding 90% to minimize thermal losses and extend LED lifespan. Their primary purpose is to replace legacy fluorescent ballasts while enabling dimming, sensor integration, and networked lighting control in commercial and institutional buildings. Constant current architectures dominate volume shipments because they align with LED forward-voltage characteristics, though dimmable variants capture disproportionate value as building automation systems penetrate the commercial end-user segment. Switching-mode technology leads across all power classes due to superior efficiency and compact form factors, while magnetic driver production contracts to legacy replacement demand in price-sensitive residential channels.
The EU Ecodesign Directive and CE marking requirements under the RoHS framework constrain component selection and recyclability design for drivers entering European markets. In the United States, DOE appliance efficiency standards and FCC Part 15 electromagnetic compatibility rules shape product development timelines and testing expenditures. China's GB standards and CCC certification govern domestic manufacturing quality benchmarks that increasingly influence export-tier production. Stakeholders must monitor regulatory divergence between efficiency test methods and harmonic limits as jurisdictions tighten performance thresholds without harmonizing measurement protocols.
Market Dynamics
Commercial building retrofit mandates across Germany, France, and the United States are compressing replacement cycles for legacy fluorescent ballasts, forcing specification-grade driver procurement toward intelligent, networked platforms that integrate with building automation systems.
Growth Catalysts
- EU Ecodesign Directive:Efficiency mandates under this framework are phasing out magnetic ballast systems across office complexes and educational facilities, creating immediate replacement demand for high-power-factor LED drivers.
- Commercial Retrofit Projects:Municipal building renovation programs in Germany prioritize LED tube retrofits with driver compatibility for sensor networks and daylight harvesting controls.
- Switching-Mode Technology:Superior efficiency and compact form factors in these architectures are displacing magnetic alternatives in volume shipments across all power classes.
Market Restraints
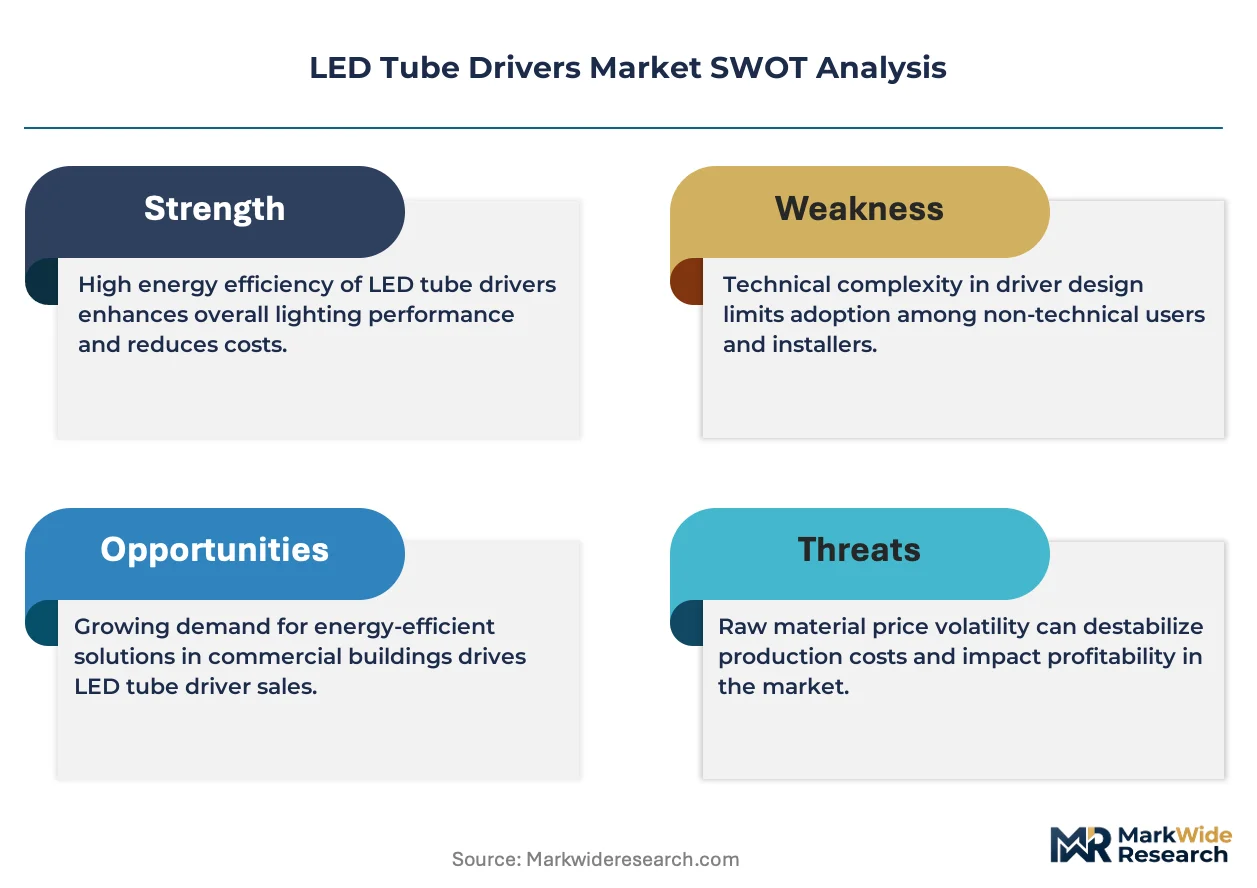
- Input Cost Volatility:Rare earth magnet prices and semiconductor component costs create margin pressure for driver manufacturers sourcing from concentrated Asian supply bases.
- Regulatory Friction:Divergent efficiency test methods and harmonic limit thresholds between the EU Ecodesign Directive and US DOE appliance standards inflate testing expenditures and delay product launches.
- Technical Limitation:Thermal management constraints in compact form factors restrict maximum power density for outdoor-rated industrial applications.
Strategic Opportunities
- Underpenetrated Geography:India offers substantial white space as BIS certification requirements and CEA efficiency mandates accelerate formal market development for quality-tier LED drivers.
- Technology Convergence:Driver platforms integrating powerline communication with DALI-2 control protocols enable granular fixture-level monitoring in smart building deployments.
- Regulatory Tailwind:China's dual carbon goals under MEE oversight are expanding subsidies for high-efficiency lighting retrofits in manufacturing facilities.
Industry Challenges
- Certification Timeline Compression:FCC Part 15 electromagnetic compatibility testing and CE marking under RoHS create multi-month validation bottlenecks for North American and European market entry.
- Integration Complexity:Retrofit installations demand backward compatibility with legacy fluorescent socket configurations while enabling forward-compatible networked control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Tube Drivers Market |
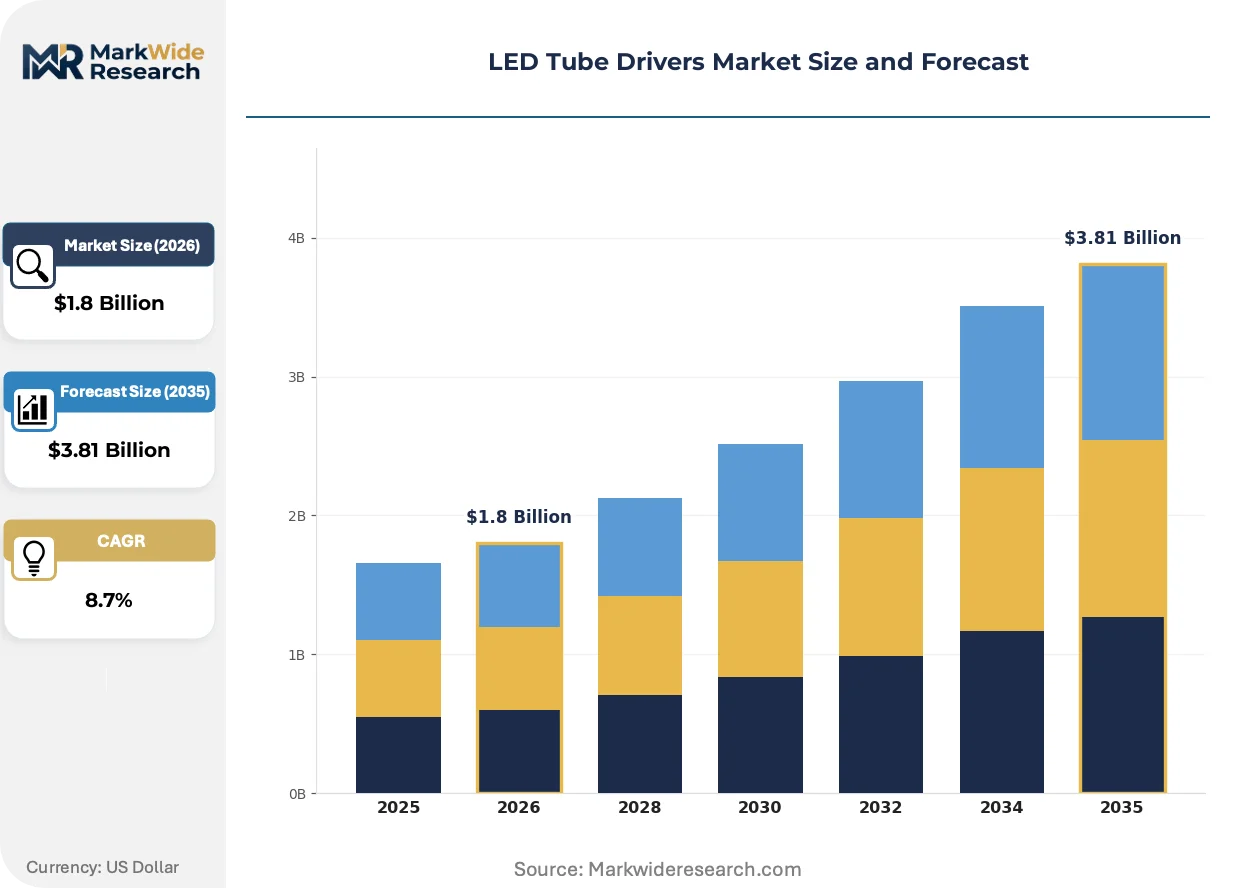
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Constant Current, Constant Voltage, Dimmable, Non-Dimmable Technology: Linear, Switching, Magnetic, Electronic End User: Commercial, Residential, Industrial, Retail Installation: Surface Mount, Recessed, Pendant, Integrated |
| Companies Covered | Signify (Philips), ams OSRAM, Mean Well Enterprises, Inventronics, Tridonic, Lifud Technology, Eaglerise, Texas Instruments, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Tube Drivers Market Evolving Landscape
Power electronics architectures are advancing toward tighter integration with building management systems, while regulatory pressure on efficiency and recyclability forces component-level redesign across all major export markets.
Intelligent driver platforms with embedded powerline communication capabilities are converging with DALI-2 and wireless mesh protocols to enable fixture-level energy monitoring. Large commercial real estate operators in Germany and the Netherlands are specifying these integrated systems for new construction and deep retrofit projects. This convergence is compressing demand for standalone, non-communicating driver variants in specification channels.
REACH substance restrictions and RoHS recyclability requirements under the EU framework are constraining capacitor electrolyte formulations and PCB substrate selections. Manufacturers serving European markets must redesign thermal management architectures to accommodate lead-free solder processes and halogen-free laminates. The industrial outdoor segment faces the steepest compliance cost escalation due to reliability demands on alternative chemistries.
Facility managers in US office complexes are consolidating lighting procurement under master service agreements with national electrical distributors. These agreements bundle driver specification, installation, and extended warranty coverage into multi-year contracts. This channel consolidation is most visible in Class A commercial real estate markets where landlord-tenant utility allocation structures incentivize granular energy accountability.
LED Tube Drivers Market Segmentation
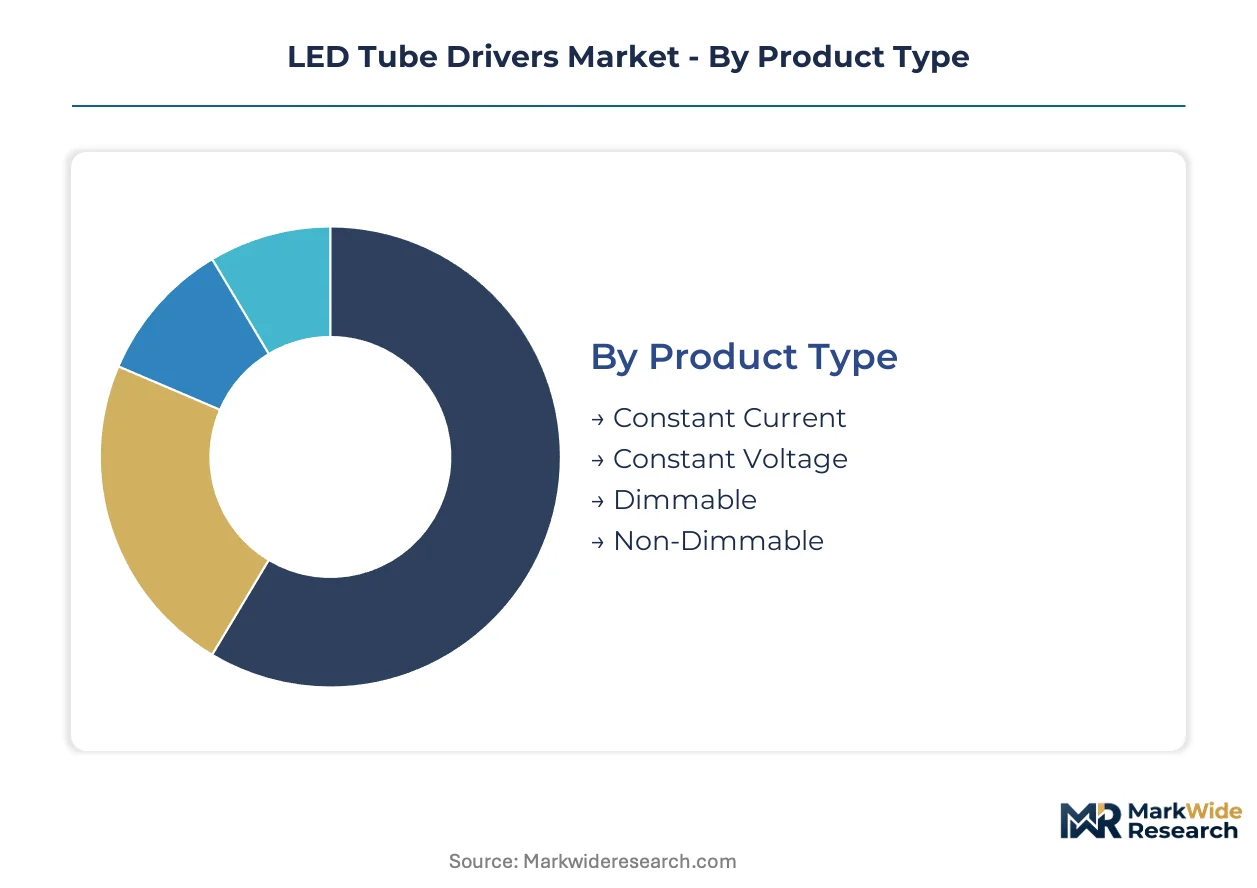
LED tube driver procurement decisions hinge on retrofit compatibility, control sophistication, and thermal envelope constraints. Specification engineers weigh power architecture against dimming protocol requirements while balancing first cost against lifecycle energy recovery.
Product Type:
Buyer selection prioritizes forward-voltage matching precision and control granularity needed for building automation integration.
- Constant Current:These architectures deliver fixed amperage across variable LED forward-voltage ranges, optimizing lumen maintenance and thermal stability. Demand concentrates in German municipal retrofit programs where specification-grade efficiency mandates exceed 90% driver efficacy. The EU Ecodesign Directive's phase-out of magnetic ballasts accelerates volume procurement through electrical distributors serving office complex renovations.
- Dimmable:Drivers incorporating 0-10V, DALI-2, or wireless control interfaces enable daylight harvesting and occupancy-based intensity modulation. Large commercial real estate operators in the Netherlands specify these variants for master service agreements bundling installation with extended warranty coverage. Networked control penetration in Class A office markets favors this segment disproportionately.
- Constant Voltage:Fixed-voltage output modules suit LED tube arrays with tightly matched forward-voltage bins, common in standardized residential retrofit SKUs.
- Non-Dimmable:Basic power conversion without control interfaces serves price-sensitive replacement demand in legacy fluorescent socket configurations.
Constant Current leads on scale; Dimmable leads on momentum.
Technology:
Power conversion efficiency and form factor density determine technology selection across installation environments.
- Switching:High-frequency switching-mode architectures achieve power densities above 90% efficiency in compact enclosures, displacing magnetic alternatives across all power classes. Mean Well Enterprises anchors mid-power volume through standardized form factors with broad distributor coverage. Thermal management constraints in outdoor-rated industrial applications nonetheless restrict maximum power density for this architecture.
- Magnetic:Legacy line-frequency ballast designs persist in residential replacement channels where first cost dominates procurement criteria. REACH substance restrictions and RoHS recyclability requirements under the EU framework accelerate decline as manufacturers redesign thermal management for lead-free solder processes.
- Linear:Simplified regulator circuits without switching elements serve low-power decorative applications with minimal electromagnetic interference concerns.
- Electronic:Hybrid architectures combining active power factor correction with resonant conversion address harmonic limit compliance in commercial specification channels.
Switching dominates absolute volume; Electronic gains specification share fastest.
End User:
Facility type dictates driver performance tier, warranty duration, and networked control requirements.
- Commercial:Office complexes, educational facilities, and healthcare institutions drive specification-grade procurement with intelligent driver compatibility for sensor networks. Germany's municipal building renovation programs prioritize LED tube retrofits with DALI-2 integration and powerline communication capability. FCC Part 15 electromagnetic compatibility testing creates multi-month validation bottlenecks for US market entry.
- Industrial:Manufacturing facilities and warehousing operations demand outdoor-rated platforms with extended temperature ranges and surge protection. China's dual carbon goals under MEE oversight expand subsidies for high-efficiency lighting retrofits in this segment. Inventronics specializes in sustaining margin pools through reliability-focused designs.
- Residential:Single-family and multi-unit dwelling retrofits emphasize backward compatibility with legacy fluorescent sockets and minimal installation labor.
- Retail:Merchandising environments balance color rendering requirements with daylight integration for customer experience optimization.
Commercial leads on scale; Industrial leads on momentum.
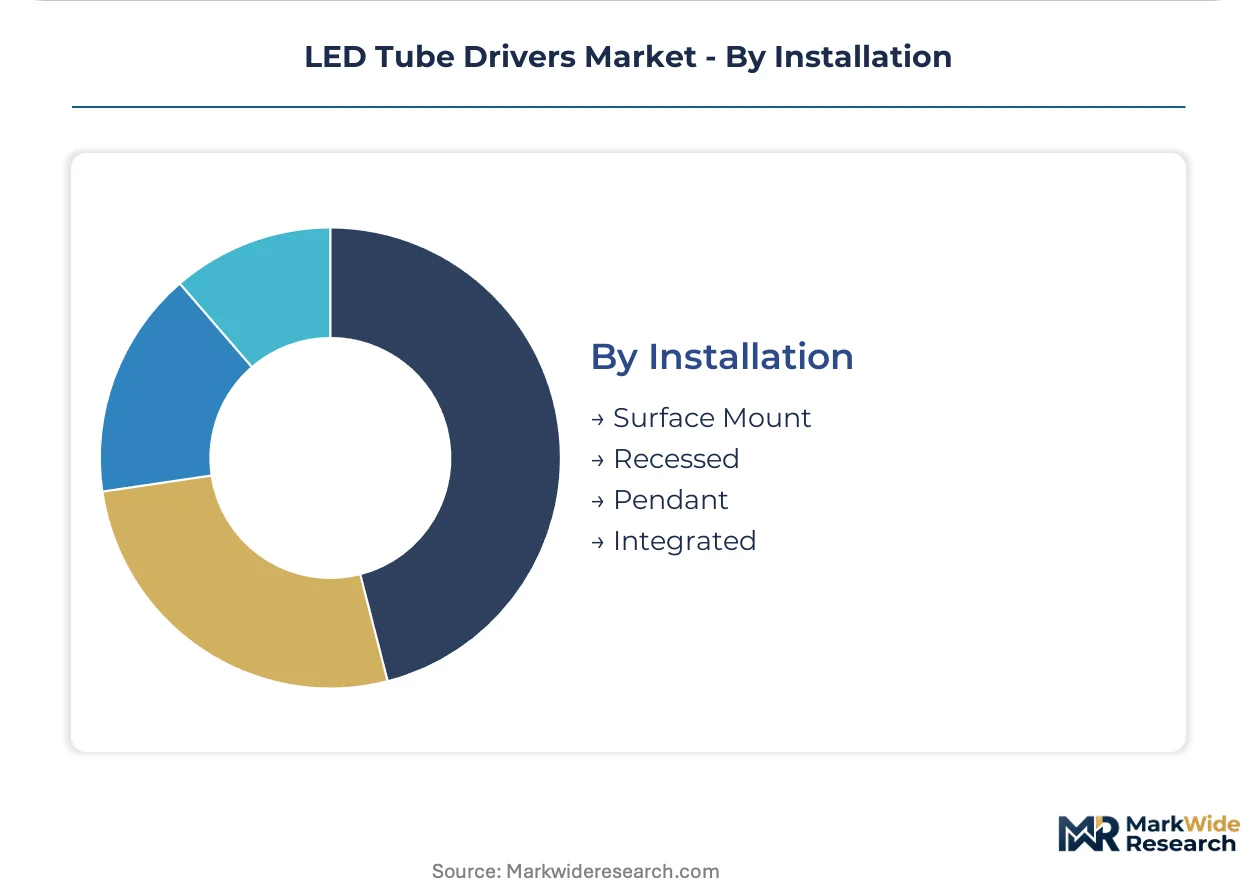
Installation:
Mounting configuration determines thermal dissipation pathways and retrofit labor intensity.
- Integrated:Driver electronics embedded within luminaire housings during original equipment manufacture streamline supply chains for new construction. Signify leverages luminaire-to-driver integration for premium positioning in specification channels. This configuration eliminates field wiring complexity but complicates future driver replacement.
- Surface Mount:Exposed driver enclosures attached to ceiling planes or walls facilitate access for maintenance in high-bay industrial environments.
- Recessed:Flush-mounted installations within ceiling cavities demand compact form factors and passive thermal management without obstructing architectural finishes.
- Pendant:Suspended luminaire configurations with remote driver placement separate heat-generating electronics from LED arrays in decorative applications.
Integrated leads on scale; Surface Mount leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in specification-grade LED driver procurement, while China's export certification recalibration reshapes supply availability across multiple continents.
United States
Commercial real estate operators in Class A office markets specify intelligent drivers with DALI-2 integration for master service agreements. DOE appliance efficiency standards and FCC Part 15 electromagnetic compatibility rules create multi-month validation bottlenecks for market entry. Facility managers in New York and Chicago consolidate procurement under national electrical distributor contracts.
Germany
Municipal building renovation programs prioritize LED tube retrofits with powerline communication capability and sensor network compatibility. The EU Ecodesign Directive phases out magnetic ballast systems across office complexes and educational facilities. Specification engineers in Munich and Frankfurt anchor procurement volume for high-power-factor architectures exceeding 90% driver efficacy.
China
Domestic manufacturing quality benchmarks under GB standards and CCC certification increasingly influence export-tier production. MEE oversight of dual carbon goals expands subsidies for high-efficiency lighting retrofits in manufacturing facilities. Driver assembly clusters in Shenzhen and Dongguan recalibrate as North American and European certification requirements tighten.
India
BIS certification requirements and CEA efficiency mandates accelerate formal market development for quality-tier LED drivers. Municipal building programs in Delhi-NCR and Maharashtra prioritize retrofit compatibility with legacy fluorescent socket configurations. Distribution networks in Bangalore and Chennai expand specification-grade inventory for commercial installation channels.
Netherlands
Large commercial real estate operators specify networked driver platforms for new construction and deep retrofit projects. REACH substance restrictions and RoHS recyclability requirements constrain capacitor electrolyte formulations and PCB substrate selections. Amsterdam and Rotterdam building automation integrators drive demand convergence with wireless mesh protocols.
LED Tube Drivers Market Competitive Landscape
Chinese producers anchor the volume tier; European specialists hold specification-grade positioning. The vendor base stratifies across three performance tiers: premium luminaire-integrated platforms, mid-power standardized form factors, and price-sensitive magnetic alternatives. Three strategic archetypes dominate: full-system integrators, component specialists, and contract manufacturers. Capacity expansion and backward integration into semiconductor sourcing represent the dominant competitive moves.
Among the named participants, Signify (Philips) and ams OSRAM occupy positions within the full-system integrator archetype, leveraging luminaire-to-driver integration for premium specification channels. Mean Well Enterprises and Inventronics exemplify the component specialist tier, with the former anchoring mid-power volume through standardized form factors and the latter representing high-efficiency outdoor-rated reliability. Tridonic sits within the European specialist cluster alongside Eaglerise, while Texas Instruments and Delta Electronics represent semiconductor and power electronics fabricators respectively. Lifud Technology occupies a position among Chinese volume producers serving export markets.
| Leading Market Players |
|---|
| Signify (Philips) |
| ams OSRAM |
| Mean Well Enterprises |
| Inventronics |
| Tridonic |
| Lifud Technology |
| Eaglerise |
| Texas Instruments |
| Delta Electronics |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Guangdong province anchor tier-two production capacity, their financing constraints limiting aggressive price competition while reinforcing supply discipline across export-certified output tiers.
Pricing Analysis
Capacity additions in Shenzhen and Dongguan are reshaping price floors for standard-grade constant current drivers as CCC-certified producers expand into CE-marked export tiers. Pricing stratifies across premium specification-grade, standard commercial retrofit, and economy residential replacement tiers, with differentiation driven by efficiency certification level and DALI-2 control integration. Cost compression in the economy tier intensifies because magnetic ballast substitution demand concentrates in price-sensitive legacy socket retrofits. Residential end-users exhibit highest price sensitivity, while German municipal procurement teams prioritize lifecycle efficiency over first cost.
Supply Chain Analysis
Export certification gating under RoHS and FCC Part 15 electromagnetic compatibility rules fragments supplier eligibility across destination markets. Manufacturing concentrates in China, Taiwan, and South Korea, with semiconductor component sourcing drawing from concentrated Asian foundry bases. Rare earth magnet prices and MLCC ceramic capacitor supply create single-source vulnerability for high-power-density switching architectures. Distribution runs through national electrical distributors in developed markets and direct OEM supply agreements in industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive's magnetic ballast phase-out functions as a regulatory compounder, compressing replacement cycles and mandating efficiency thresholds that reshape procurement specifications across commercial building portfolios.
For Market Incumbents: Extend luminaire-to-driver integration capabilities to defend specification-grade positioning against emerging platform specialists. Backward integration into semiconductor sourcing addresses margin pressure from rare earth and MLCC cost volatility. Prioritize DALI-2 and powerline communication certification investment to maintain access to German municipal retrofit programs. For New Entrants and Emerging Players: National electrical distributors represent the most accessible channel partners for penetrating US Class A commercial real estate markets without incumbent specification relationships. Target India's quality-tier formal market development under BIS certification requirements, where CEA efficiency mandates accelerate replacement demand ahead of entrenched supply relationships. Lead with retrofit compatibility engineering to reduce installation labor differentiation against integrated luminaire offerings. For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists with outdoor-rated industrial platforms and limited specification channel presence. Long-term viability centers on regulatory tailwinds from efficiency mandates tightening across multiple jurisdictions simultaneously. Watch for inflection in India's BIS enforcement intensity as the signal for quality-tier market formalization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | CE marking under RoHS and FCC Part 15 compliance unlocks German and US specification channels. |
| Backward Integration into Semiconductors | In-house power MOSFET sourcing buffers margin pressure from Asian foundry concentration. |
| DALI-2 Protocol Integration | Building automation convergence in Dutch and German commercial real estate favors networked drivers. |
| Industrial Outdoor Platform Development | Extended temperature range designs capture subsidy-driven retrofit demand under China's MEE oversight. |
| Master Service Agreement Bundling | Multi-year installation and warranty contracts consolidate procurement under national distributor relationships. |
Research Methodology
Bottom-up commercial and industrial installation modeling reconciled against top-down driver assembly capacity tracking forms the analytical core of this study. Primary interviews with specification engineers at electrical distributors, procurement leads for German municipal building programs, and product managers at driver manufacturers were validated against secondary sources including EU Ecodesign Directive implementation reports, FCC equipment authorization databases, and customs trade data for LED driver HS codes. Cross-referencing bottom-up project pipelines with top-down production capacity surveys ensures demand-supply balance integrity.
Input-output matrices map driver shipments by product architecture, control sophistication, and end-use facility type across the projection horizon. Segmentation dimensions include power conversion technology, dimming protocol compatibility, installation configuration, and regional regulatory framework. CAGRs derive from trend extrapolation of replacement cycle compression under efficiency mandates, calibrated against historical penetration rates of switching-mode architectures displacing magnetic alternatives. Forecast inputs incorporate semiconductor component lead time dynamics and certification timeline variability across destination markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to divergence between EU and US efficiency test methods and harmonic limit thresholds. Model assumptions reflect current regulatory enforcement intensity and subsidy program continuity. A model refresh is warranted upon material change in India's BIS certification enforcement or China's dual carbon goal subsidy allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Lighting Market
LED
East Africa LED Lighting Market
LED
Small Pitch LED Display Market
LED
Smart LED Indoor Signage Market
LED
LED Light Market
LED
North America Outdoor LED Lighting Market
LED
US and Europe LED Lighting Market
LED
UV-C LED Market
LED
LED Floodlight Drivers Market
LED
Germany Automotive LED Lighting Market
LED
Gan Micro LED Market
LED
US LED Downlight Market
LED
North America LED Lighting Market
LED
High-Brightness LED Market
LED
7 Segment LED Displays Market
LED
Arrow LED Displays Market