
 Global Multichannel Campaign Management Market | 2026-2036
Global Multichannel Campaign Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multichannel Campaign Management Market Foresight
Market Context
The multichannel campaign management landscape is pivoting on a widening capability gap between premium orchestration suites and stripped-down commodity tools. Salesforce.com Inc. leverages its Customer 360 architecture to anchor high-value enterprise accounts seeking unified identity resolution. Adobe Inc. competes through deep creative-to-activation workflow integration that sustains pricing power in media-intensive verticals. Pegasystems Inc. differentiates via real-time decisioning engines that dominate regulated industries requiring deterministic AI governance.
Technical Definition and Segment Structure
Multichannel campaign management denotes software systems that coordinate audience targeting, content personalization, and performance measurement across email, social, SMS, web, and direct mail channels through centralized data layers and automated journey orchestration. These platforms ingest behavioral signals from CRM, DMP, and CDP sources to trigger contextually relevant communications at individual cadences, serving chief marketing officers who must demonstrate attributable revenue return on media spend. Cloud deployment now leads outright as latency-sensitive personalization workloads migrate from on-premise data centers to distributed edge infrastructure, while hybrid configurations retain traction among financial services firms with sovereign data requirements. Email marketing persists as the mature revenue base within solution types, yet social media marketing captures the fastest expansion as short-form video formats fragment audience attention and demand native creative adaptation. The BFSI end user industry harbors the deepest margin pools due to compliance-driven customization needs and long contract tenors that resist vendor displacement.
Regulatory Environment
The European GDPR and the EU AI Act impose algorithmic transparency and consent-documentation burdens that reshape platform architecture requirements for any vendor serving European enterprises. The US FTC and state-level privacy frameworks including California's CPRA create a patchwork compliance environment that inflates implementation costs and favors modular solutions with jurisdiction-configurable rule engines. Stakeholders must monitor whether emerging interoperability mandates from the US FCC and EU Digital Markets Act force open API standards that erode proprietary data moats.
Market Dynamics
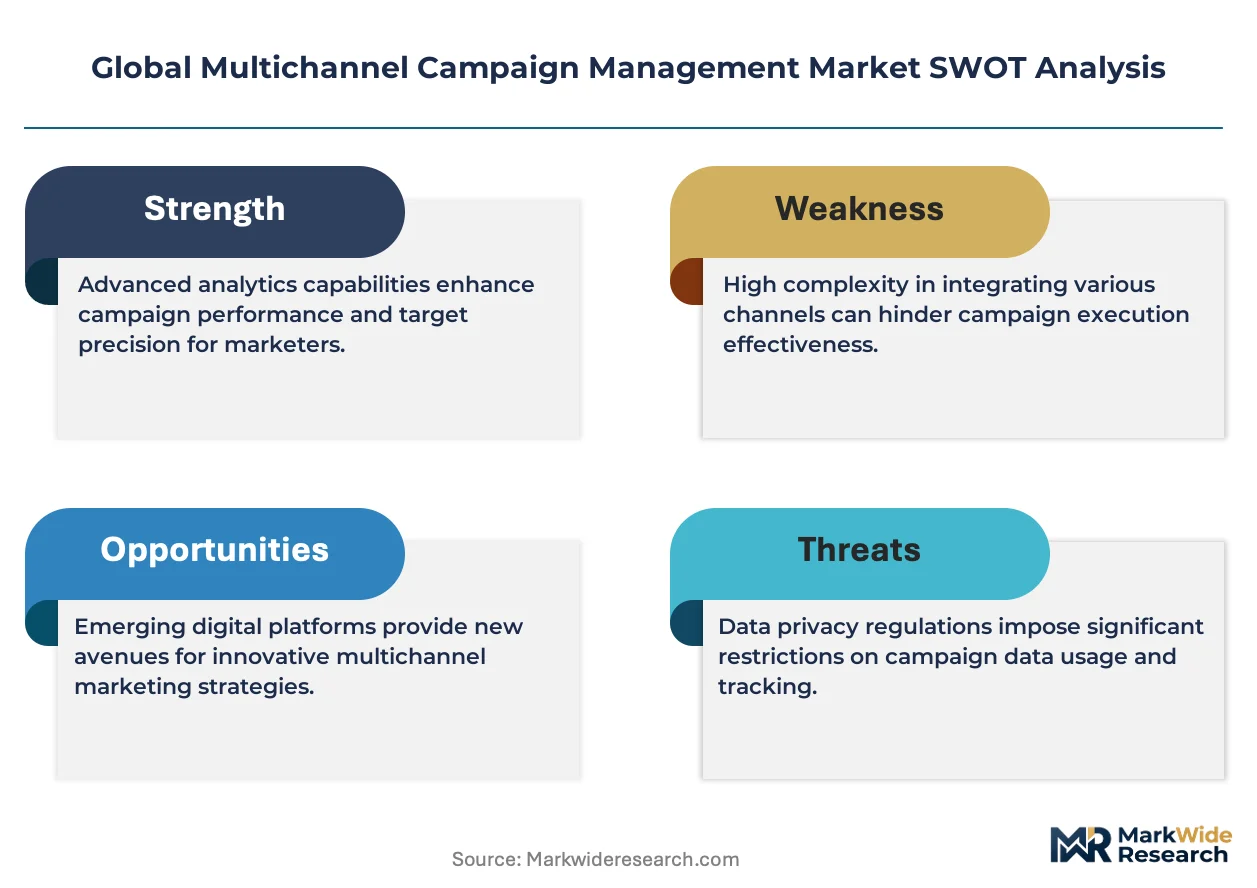
First-party data deprecation and privacy regulation fragmentation are forcing enterprises to rebuild campaign infrastructure around consented identity graphs rather than third-party cookies, compressing vendor replacement cycles and favoring modular, jurisdiction-configurable platforms.
Growth Catalysts
- CPRA Compliance Mandates:California's privacy framework compels Fortune 500 retailers to replace legacy batch-processing systems with real-time consent management, driving platform refresh spending.
- Edge Computing Maturation:Distributed cloud infrastructure now supports sub-100-millisecond personalization latency, enabling in-the-moment journey orchestration for streaming media buyers.
- Retail Media Networks:Closed-loop attribution capabilities embedded in multichannel platforms capture advertising budgets migrating from open-web programmatic to retailer-owned inventory.
Market Restraints
- CDP Integration Tax:Customer data platform connectivity consumes 30-40% of implementation budgets, inflating total cost of ownership for mid-market buyers.
- EU Regulatory Friction:GDPR Article 22 automated decisioning restrictions and the EU AI Act's risk-classification requirements impose architectural constraints that slow European deployment velocity.
- Talent Scarcity:Shortage of data engineers proficient in both Apache Kafka stream processing and marketing operations logic extends implementation timelines.
Strategic Opportunities
- India Digital Acceleration:TRAI's data localization guidelines and UPI payment integration create demand for sovereign-cloud campaign orchestration among domestic fintech and e-commerce platforms.
- Healthcare Vertical Expansion:HIPAA-compliant journey automation for patient engagement and prescription adherence programs represents an underpenetrated application with 5-7 year contract tenors.
- Generative-CRM Convergence:Large language models natively embedded within campaign workflows enable dynamic creative generation at segment-of-one scale, compressing production cycles.
Industry Challenges
- Fragmented Identity Resolution:Proliferation of proprietary identity graphs across walled gardens complicates unified measurement and attribution modeling.
- Cross-Border Data Governance:Conflicting sovereignty requirements between EU GDPR, China's PIPL, and US state laws force redundant infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multichannel Campaign Management Market |
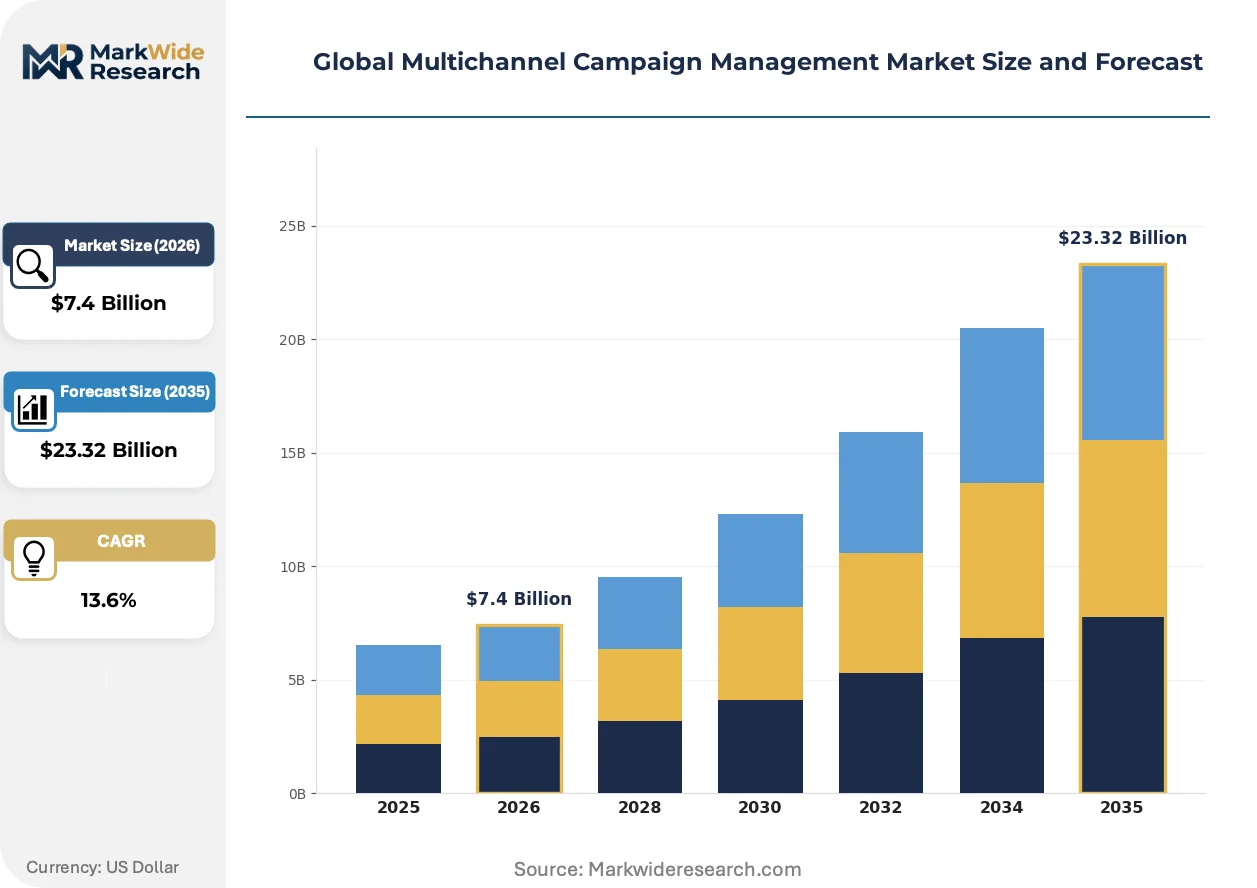
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $23.32 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premise, Hybrid, SaaS Solution Type: Email Marketing, Social Media Marketing, SMS Marketing, Web Analytics, Direct Mail End User Industry: BFSI, Telecommunications, Consumer Electronics, Travel & Hospitality, Education Sales Channel: Direct Sales, Partner Networks, Online Marketplaces, System Integrators |
| Companies Covered | Salesforce.com Inc., Oracle Corporation, IBM Corporation, Adobe Inc., SAP SE, SAS Institute, Inc., Teradata Corporation, Infor Inc., Pegasystems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multichannel Campaign Management Market Shifts & Advancements
Artificial intelligence is migrating from analytic overlay to core orchestration engine, while regulatory pressure and buyer consolidation reshape how platforms prove attributable revenue return.
Real-time decisioning engines are integrating deterministic AI governance frameworks that satisfy financial services compliance requirements while maintaining sub-second latency for next-best-action triggers. Tier-1 banks in the United States and United Kingdom are deploying these systems at scale, replacing rules-based campaign logic with adaptive models that compress test-and-learn cycles from weeks to hours. This capability is integrating previously siloed risk, marketing, and product systems into unified engagement layers.
The EU AI Act's risk-based classification system imposes documentation and human-oversight obligations on high-risk automated decisioning applications, including credit and insurance marketing. Platform vendors must now embed explainability modules and audit trails that satisfy notified body scrutiny. BFSI deployments across Germany, France, and the Netherlands are prioritizing vendors with pre-certified algorithmic transparency architectures.
Enterprise procurement of campaign management capabilities is consolidating around outcome-based commercial models that tie vendor compensation to attributable revenue lift rather than seat-based or message-volume pricing. Retail and direct-to-consumer brands in North America are leading this shift, unbundling creative production from platform licensing to align incentives. This transformation is most visible among digitally native vertical brands seeking to demonstrate unit economics discipline to investors.
Global Multichannel Campaign Management Market Segmentation
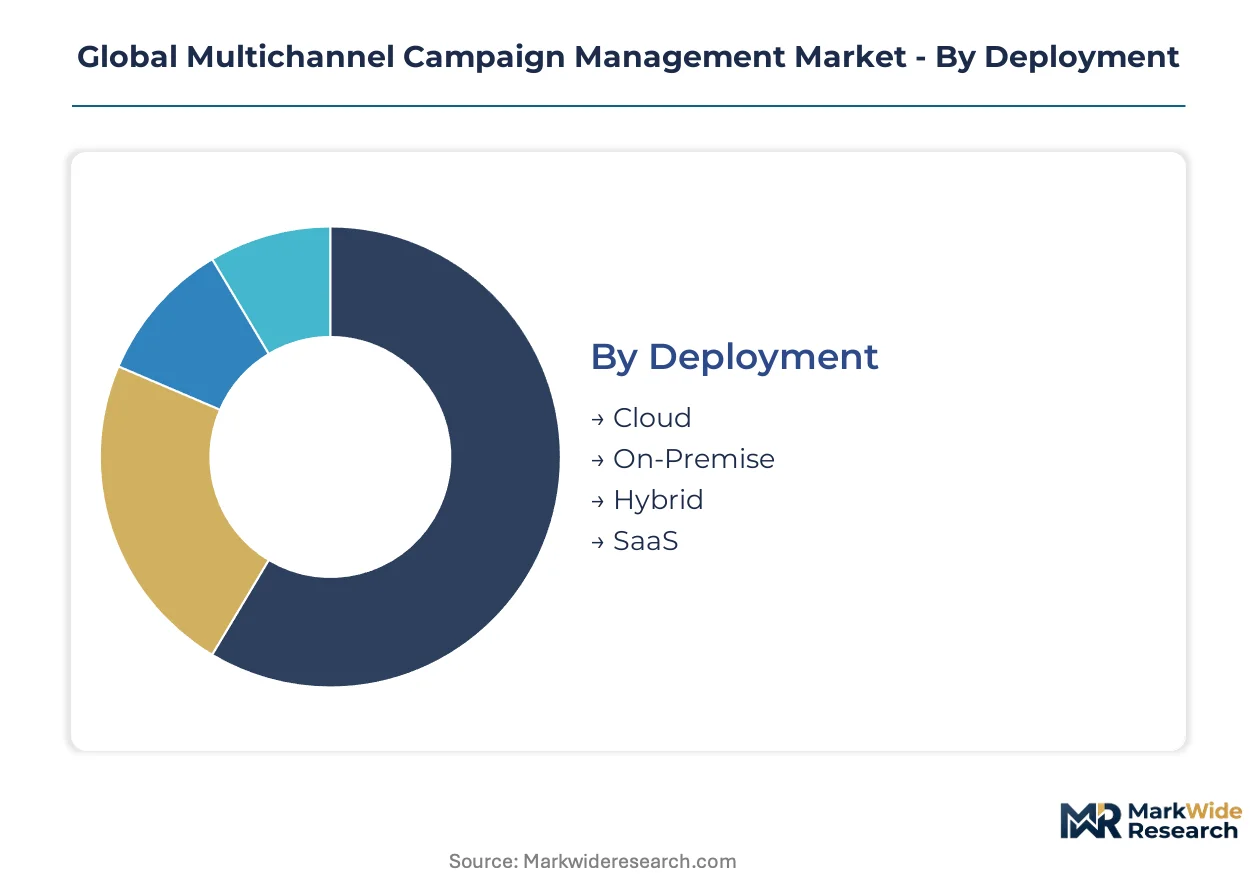
Segmentation in multichannel campaign management reveals how infrastructure choices, channel priorities, and procurement pathways diverge across buyer sophistication levels. Deployment architecture and solution type selections directly determine implementation cost structures and time-to-value horizons for enterprise marketing organizations.
Deployment:
Volume deployments favor standardized cloud configurations with minimal customization overhead, while premium engagements demand sovereign data controls and dedicated infrastructure isolation.
- Cloud:Distributed edge infrastructure now supports sub-100-millisecond personalization latency for streaming media buyers. United States retailers with high-velocity transaction volumes dominate demand as real-time journey orchestration becomes table stakes for customer acquisition.
- Hybrid:Split workloads separate consented identity data in sovereign on-premise vaults from activation layers in public cloud. German and French financial institutions lead adoption as the EU AI Act's risk-classification requirements impose algorithmic transparency obligations that complicate pure-cloud architectures.
- On-Premise:Legacy data center retention persists among Japanese and South Korean conglomerates with multi-decade IT asset depreciation cycles.
- SaaS:Subscription-based delivery compresses upfront capital requirements for mid-market buyers in India's domestic fintech sector.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud.
Solution Type:
Channel-specific capabilities command pricing premiums based on creative production complexity and attribution granularity, with automation depth separating commodity from differentiated offerings.
- Email Marketing:Batch-and-blast legacy systems persist as revenue base despite declining engagement rates. North American B2B technology vendors sustain spending on deliverability optimization and inbox placement technology.
- Social Media Marketing:Native creative adaptation for short-form video formats fragments audience attention and demands platform-specific production workflows. Direct-to-consumer brands in the United Kingdom and Brazil allocate the fastest-growing share of platform budgets here.
- SMS Marketing:Regulatory consent requirements under the US TCPA and India's TRAI guidelines constrain broadcast volume but lift per-message pricing power.
- Web Analytics:First-party data collection infrastructure rebuilds around server-side tracking to circumvent browser cookie deprecation.
- Direct Mail:Physical retargeting integrations with digital identity graphs sustain relevance for luxury customer segments in Switzerland and the UAE.
Established revenue concentration sits with Email Marketing. Steepest expansion trajectory belongs to Social Media Marketing.
End User Industry:
Margin capture varies sharply by compliance burden and contract tenor, with regulated verticals resisting vendor displacement through embedded workflow complexity.
- BFSI:Deterministic AI governance frameworks satisfy credit and insurance marketing compliance while maintaining sub-second latency. Tier-1 banks in the United States and United Kingdom deploy these systems at scale, replacing rules-based campaign logic with adaptive models.
- Telecommunications:Subscriber churn prediction and upsell orchestration demand real-time decisioning across prepaid and postpaid segments. Indian and Indonesian carriers invest heavily as ARPU compression intensifies competitive pressure.
- Consumer Electronics:Product launch cycles and seasonal demand spikes favor modular platforms with burst capacity scaling.
- Travel & Hospitality:Dynamic pricing integration with inventory systems requires specialized connector ecosystems.
- Education:Student recruitment and alumni engagement programs represent emerging application with extended evaluation timelines.
Deepest margin pools sit with BFSI. Fastest-growing demand concentration is in Telecommunications.
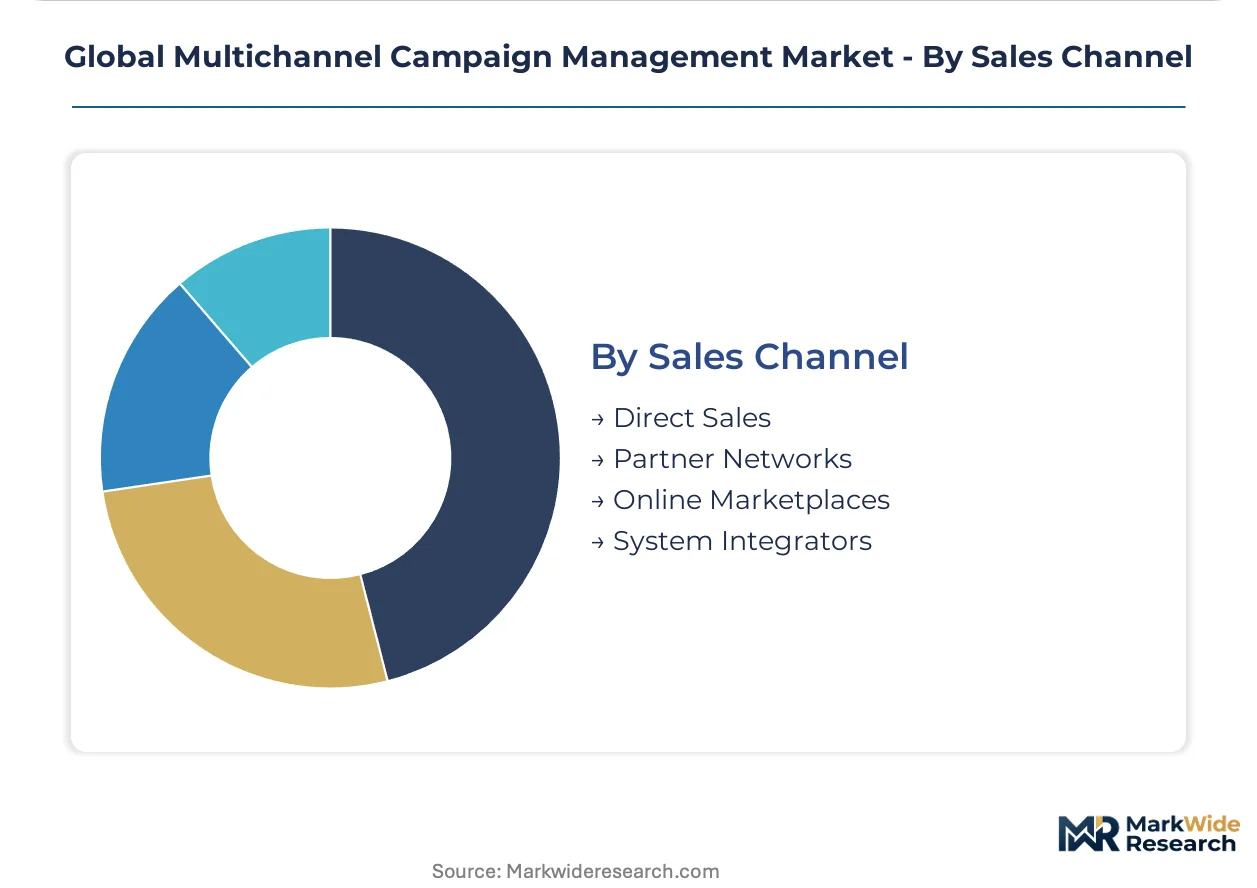
Sales Channel:
Procurement complexity and implementation risk tolerance determine whether buyers favor direct vendor relationships or intermediary-mediated engagements.
- Direct Sales:Enterprise accounts with complex data integration requirements negotiate outcome-based commercial models tying vendor compensation to attributable revenue lift. North American digitally native vertical brands lead this shift.
- System Integrators:CDP connectivity consumes substantial implementation budget, inflating total cost of ownership and driving mid-market buyers toward packaged deployment services. Accenture and Deloitte practices in the United States and United Kingdom capture significant attach rates.
- Partner Networks:Regional value-added resellers dominate in markets with localization requirements.
- Online Marketplaces:Self-service provisioning attracts small and medium enterprises with standardized use cases.
Highest contract value concentration sits with Direct Sales. Fastest channel expansion is in System Integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the densest concentration of multichannel campaign management deployment, where Salesforce.com Inc. and Adobe Inc. headquarters proximity accelerates enterprise adoption cycles among Fortune 500 retailers rebuilding first-party data infrastructure.
United States
Fortune 500 retailers in California and New York drive platform refresh spending around CPRA compliance mandates, replacing legacy batch-processing systems with real-time consent management. The FTC's evolving privacy enforcement posture creates patchwork compliance complexity that favors modular, jurisdiction-configurable solutions. New York Metro's financial services corridor dominates deterministic AI governance deployments as Tier-1 banks replace rules-based campaign logic with adaptive models.
Germany
Frankfurt's banking cluster demands pre-certified algorithmic transparency architectures satisfying the EU AI Act's risk-classification requirements for credit and insurance marketing. The CNIL's interpretation of GDPR Article 22 automated decisioning restrictions imposes architectural constraints slowing pure-cloud deployments. Bavaria's automotive manufacturers invest in hybrid configurations separating consented identity data in sovereign on-premise vaults from activation layers.
United Kingdom
London's direct-to-consumer brands allocate the fastest-growing platform budgets toward social media marketing with native creative adaptation for short-form video formats. The Information Commissioner's Office enforcement of GDPR consent-documentation burdens reshapes procurement criteria toward audit-trail capabilities. Manchester's emerging fintech corridor experiments with outcome-based commercial models tying vendor compensation to attributable revenue lift.
India
Mumbai's domestic e-commerce platforms and Bangalore's fintech unicorns demand sovereign-cloud campaign orchestration responding to TRAI's data localization guidelines and UPI payment integration requirements. The RBI's digital lending regulations intensify compliance-driven customization needs among non-banking financial companies. Hyderabad's IT services cluster supplies implementation talent for Apache Kafka stream processing and marketing operations logic integration.
Japan
Tokyo's conglomerates with multi-decade IT asset depreciation cycles retain legacy on-premise data center configurations despite cloud infrastructure maturation. METI's industrial data governance frameworks influence procurement specifications for campaign management platforms serving precision manufacturing marketers. Osaka's consumer electronics manufacturers favor modular platforms with burst capacity scaling for seasonal product launch cycles.
Global Multichannel Campaign Management Market Competitive Landscape
Capital-heavy enterprise software suites compete with asset-light specialized orchestration tools across deployment modalities, creating a tiered structure where unified identity resolution capabilities separate premium vendors from commodity alternatives. The vendor base concentrates around three strategic archetypes: cloud-native platforms with distributed edge infrastructure, hybrid-configured systems serving sovereign data requirements, and legacy on-premise suites with deep workflow embedding. Dominant competitive moves include outcome-based commercial model adoption and generative-CRM convergence embedding large language models within campaign workflows.
Within the premium enterprise tier, Salesforce.com Inc. and Adobe Inc. anchor positions through Customer 360 architecture and creative-to-activation workflow integration respectively, while Pegasystems Inc. occupies a specialized position serving regulated industries requiring deterministic AI governance. These three exemplify divergent competitive vectors: unified identity resolution, media-intensive vertical penetration, and real-time decisioning compliance. Oracle Corporation and SAP SE represent alternative enterprise archetypes with ERP-anchored data layer integration, though their campaign management offerings sit within broader cloud application portfolios rather than standalone orchestration specialization.
| Leading Market Players |
|---|
| Salesforce.com Inc. |
| Oracle Corporation |
| IBM Corporation |
| Adobe Inc. |
| SAP SE |
| SAS Institute, Inc. |
| Teradata Corporation |
| Infor Inc. |
| Pegasystems Inc. |
| Others |
Supply & Pricing Matrix
Apache Kafka proficiency clusters in Hyderabad and Bangalore compress implementation labor costs for Indian SaaS vendors, widening pricing-tier spreads between premium enterprise suites and mid-market cloud offerings as North American buyers absorb CDP integration premiums.
Pricing Analysis
Outcome-based commercial models tying vendor compensation to attributable revenue lift anchor value-based pricing for enterprise accounts. Pricing stratifies across premium orchestration suites with deterministic AI governance, standard cloud configurations with modular consent management, and economy-tier self-service tools with stripped-down journey orchestration. Cost compression in mid-market SaaS tiers intensifies as CDP connectivity consumes substantial implementation budgets and inflates total cost of ownership. Fortune 500 retailers in California demonstrate lowest price sensitivity given CPRA compliance mandates, while Indian domestic fintech platforms exhibit highest sensitivity to upfront licensing costs.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for unified identity resolution and real-time decisioning engines. Software development concentrates in the United States, India, and Ireland as cloud infrastructure maturation and AI talent density shape vendor location decisions. Core inputs draw from proprietary identity graph technologies, distributed edge computing infrastructure, and Apache Kafka stream processing frameworks. Single-source vulnerability sits with hyperscaler cloud dependencies for latency-sensitive personalization workloads. Distribution runs through system integrators for mid-market buyers and direct sales teams for enterprise accounts with complex data integration requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
First-party data deprecation and privacy regulation fragmentation are forcing consolidation as weaker vendors lack jurisdiction-configurable architectures to serve multinational enterprise procurement.
For Market Incumbents: Hedge against modular platform encroachment by embedding generative-CRM capabilities natively within campaign workflows, compressing creative production cycles that specialized tools exploit. Deepen deterministic AI governance certification for EU AI Act risk-classification requirements to defend BFSI margin pools from compliance-native challengers. Acquire CDP connectivity specialists to neutralize the 30-40% implementation tax eroding mid-market competitiveness. For New Entrants and Emerging Players: Self-service provisioning portals offer the most penetrable route for small and medium enterprises with standardized email and SMS use cases, bypassing system integrator gatekeepers. Target sovereign-cloud campaign orchestration for Indian fintech platforms responding to TRAI data localization guidelines and RBI digital lending regulations. Lead with UPI payment integration and localized consent management as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid-deployment specialists given EU AI Act algorithmic transparency obligations complicating pure-cloud architectures for German and French financial institutions. Long-term viability favors vendors with pre-certified explainability modules and audit-trail capabilities serving 5-7 year contract tenors in healthcare and BFSI verticals. Watch for outcome-based commercial model adoption among North American digitally native vertical brands as inflection indicator for incentive-aligned platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Generative-CRM Convergence | Large language models embedded in campaign workflows compress creative production cycles for segment-of-one personalization at scale. |
| Deterministic AI Governance Certification | Pre-certified algorithmic transparency architectures satisfy EU AI Act risk-classification requirements for Tier-1 bank deployments. |
| Sovereign-Cloud Infrastructure Buildout | Data localization compliance for TRAI guidelines and RBI regulations captures Indian fintech and e-commerce platform demand. |
| CDP Connectivity Acquisition | Neutralizing implementation tax erosion restores mid-market competitiveness against modular platform alternatives. |
| Outcome-Based Commercial Model Adoption | Vendor compensation tied to attributable revenue lift aligns incentives with digitally native vertical brand procurement criteria. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and CDP vendor technical documentation formed the secondary backbone for market sizing and competitive positioning validation. Primary interviews with chief marketing officers, IT procurement officers, platform engineers, and system integrator practice leads combined with secondary sources through bottom-up deployment volume analysis and top-down enterprise spending surveys. Triangulation across stakeholder perspectives verified segmentation assumptions for cloud, hybrid, and on-premise deployment modalities.
Historical trendline analysis of vendor revenue disclosures and enterprise procurement database patterns established baseline growth trajectories across the projection horizon. The analytical framework modeled deployment architecture, solution type, end user industry, and sales channel dimensions alongside integration complexity tiers. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion patterns, incorporating edge computing latency benchmarks and consent-management regulatory enforcement timelines as industry-specific forecast inputs.
The model holds under steady privacy regulation enforcement and cloud infrastructure cost curves; deviation in EU AI Act implementation timelines or hyperscaler pricing volatility would shift deployment modality preferences. Forecasts reflect base-case assumptions regarding first-party data strategy adoption and martech stack consolidation velocity. Periodic stress-testing of base assumptions is recommended given regulatory fragmentation and talent scarcity variables.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Inventory Management Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Global Workflow Orchestration Market
Digital Solutions
Communication Intelligence Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Smart Government Market
Digital Solutions
Computer Aided Design (CAD) Market
Digital Solutions
Online Recruitment Market
Digital Solutions
Global Data Collection and Labeling Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
Global Commerce Cloud Solution Market