
 Spain Payment Gateway Market | 2026-2036
Spain Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Payment Gateway Market Insights
Small and medium retailers is redrawing the Spain Payment Gateway Market as they abandon legacy POS systems for unified omnichannel checkout. Stripe leverages its API-first architecture to capture developer-centric merchants building custom storefronts. BBVA anchors its position through deep banking relationships and proprietary merchant acquiring infrastructure across Iberia.
A payment gateway is a technology layer that encrypts, routes, and authorizes transaction data between merchants, acquirers, and card networks using TLS protocols and tokenization standards. Its commercial purpose is to reduce fraud exposure while enabling real-time settlement across multiple payment rails. Transaction processing services dominate revenue pools due to per-transaction fee structures, while fraud prevention modules represent the fastest-expanding margin segment as merchants face escalating chargeback liability. API integration methods lead developer adoption, though hosted payment pages retain share among non-technical merchants prioritizing PCI-DSS compliance outsourcing.
The European Banking Authority enforces PSD2 strong customer authentication requirements that shape product roadmaps for gateway providers operating in Spain. Spain's national cybersecurity institute, INCIBE, collaborates with the Bank of Spain to audit critical payment infrastructure operators under national resilience frameworks. Stakeholders must monitor how the EU AI Act classifies automated fraud-scoring algorithms, as reclassification could force algorithmic transparency investments or operational redesigns.
Market Dynamics
Spanish small and medium retailers are abandoning legacy POS terminals for integrated omnichannel checkout systems, compressing merchant acquisition timelines and forcing gateway providers to embed fraud prevention and acquiring services into unified stacks.
Growth Catalysts
- PSD2 Strong Customer Authentication:The European Banking Authority's mandate for two-factor authentication on electronic payments has accelerated tokenization adoption among Spanish merchants seeking streamlined compliance.
- API-First Architecture:Developer-centric merchants in Madrid and Barcelona are demanding programmable checkout layers that embed directly into custom storefronts and mobile applications.
- E-commerce Density:Madrid and Barcelona account for disproportionate transaction volumes, concentrating infrastructure investment and partnership activity in these metropolitan clusters.
Market Restraints
- Acquiring Concentration:Spain's merchant acquiring landscape remains dominated by incumbent banking groups, limiting pricing leverage for independent gateway providers.
- DORA Compliance Burden:The EU's Digital Operational Resilience Act mandates penetration testing and incident reporting that elevates operational costs for smaller payment service providers.
- Technical Legacy:Thousands of Spanish retailers still operate on isolated POS systems that resist cloud migration without expensive terminal replacement.
Strategic Opportunities
- Andalusian E-commerce Penetration:Seville and Málaga exhibit lower gateway saturation than Madrid or Barcelona, presenting whitespace for localized merchant onboarding.
- AI-Act Tailwind:Pending EU AI Act classifications for automated fraud scoring could create first-mover advantages for transparent algorithmic platforms.
- Embedded Finance Convergence:Payment gateways that integrate lending, insurance, and treasury services into checkout flows can capture merchant banking relationships.
Industry Challenges
- PCI-DSS Certification Timelines:Annual audits and quarterly network scans delay product launches for gateway startups lacking dedicated compliance teams.
- ISO 20022 Migration:Spanish banks are transitioning messaging standards, forcing gateways to maintain dual-format compatibility during extended cutover periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Payment Gateway Market |
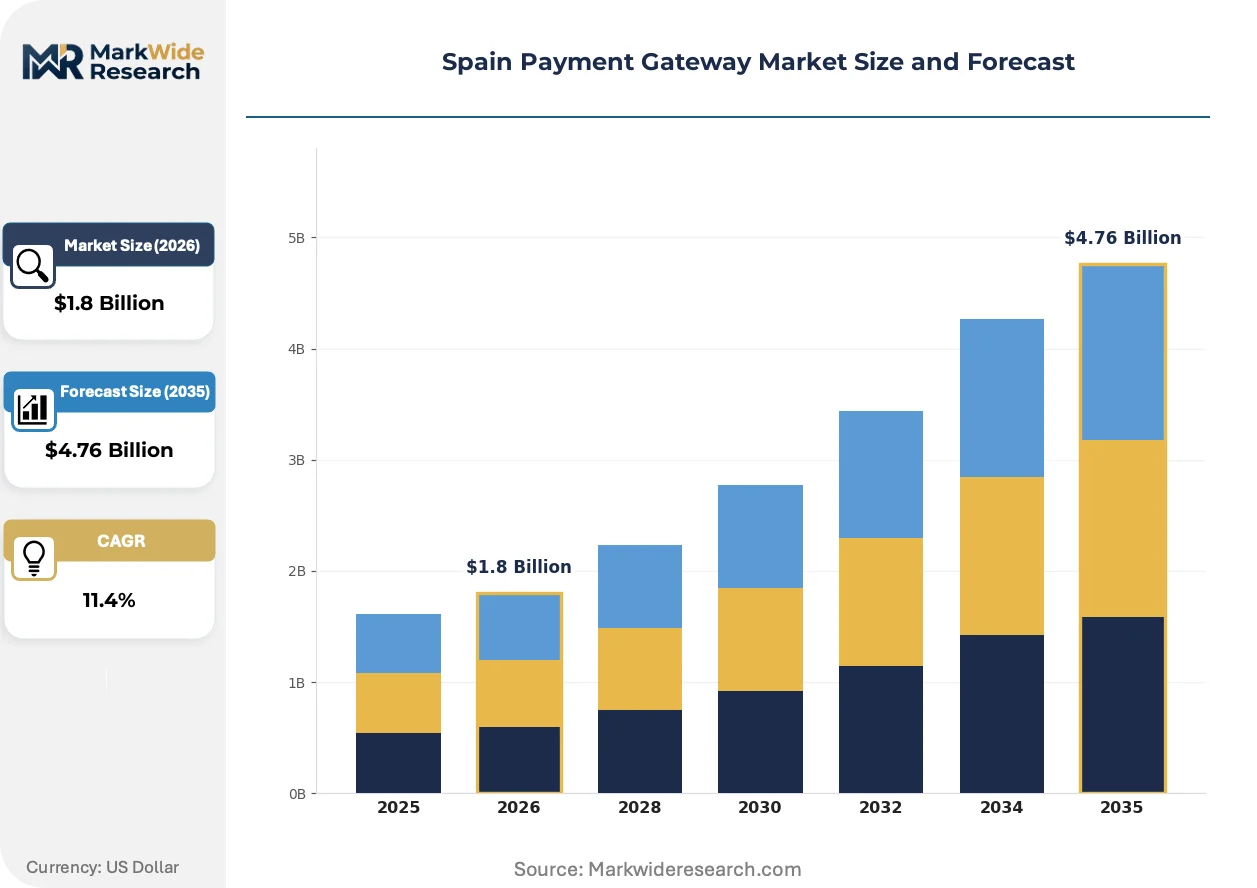
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transaction Processing, Fraud Prevention, Currency Conversion, Reporting Tools Integration Method: API, Hosted Payment Page, Plug-in, Mobile SDK End User: E-commerce Platforms, Retailers, Subscription Services, Nonprofits Payment Method: Credit Card, Debit Card, Digital Wallet, Bank Transfer |
| Companies Covered | Stripe, BBVA, Redsys, CaixaBank Payments & Consumer, Worldline, Bizum, PayPal, Mollie, Adyen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Payment Gateway Market Trends and Innovations
Gateway architectures are fragmenting between low-code hosted solutions and developer-native APIs, while regulatory pressure on fraud prevention and operational resilience accelerates capability consolidation among surviving providers.
Tokenization technology is bifurcating the Spanish gateway landscape. Network tokens issued by Visa and Mastercard reduce PCI scope for merchants while preserving card-on-file functionality. Large retailers with dedicated development teams are adopting vault-level tokenization, whereas smaller merchants rely on gateway-managed tokens. This technical split is compressing margin pools for mid-tier providers caught between premium API services and commodity hosted pages.
DORA's penetration testing mandates are reshaping vendor procurement. Spanish payment service providers must now demonstrate annual resilience audits and 24-hour incident reporting capabilities to maintain Bank of Spain operating licenses. Gateway vendors are responding by embedding security operations centers directly into their service stacks, particularly affecting providers serving high-volume merchants in Catalonia.
Merchant buying patterns are compressing vendor selection cycles. Spanish retailers previously evaluated gateway partnerships over 6-12 month procurement processes; accelerated digital transformation timelines have collapsed this to 8-12 weeks. Independent software vendors and systems integrators in Valencia and Bilbao are capturing influence as trusted intermediaries, displacing direct sales relationships that dominated legacy acquiring arrangements.
Spain Payment Gateway Market Segmentation
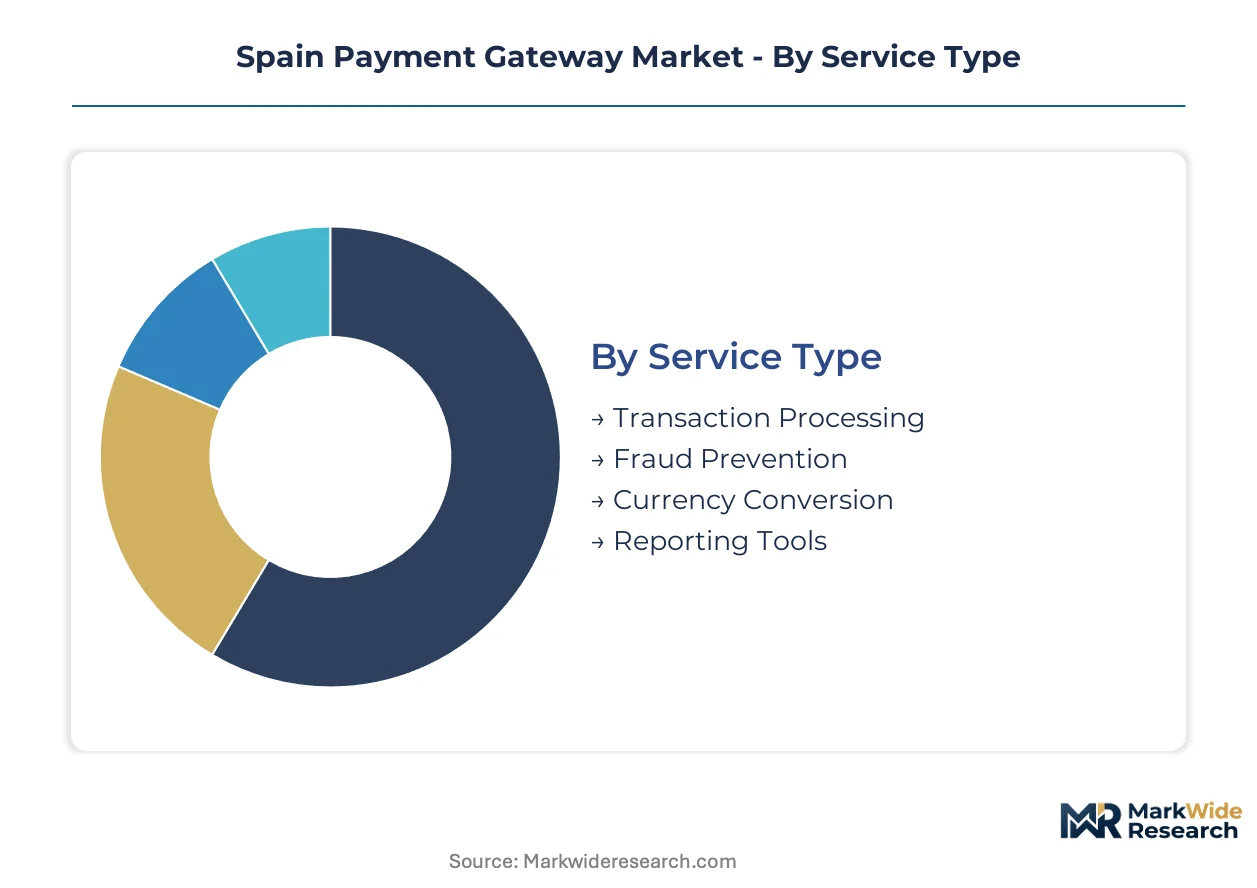
Spanish payment gateway providers architect their product portfolios around distinct service tiers and integration modalities, each commanding different margin profiles and compliance obligations. Merchant technical sophistication and transaction velocity determine which segments capture disproportionate infrastructure investment from vendors competing across Madrid and Barcelona.
Service Type:
Channel mix varies sharply across service tiers, with transaction processing flowing through direct bank relationships while fraud prevention modules increasingly route through specialized cybersecurity vendors.
- Transaction Processing:Core authorization and settlement engines handle encryption, routing, and real-time communication with card networks via TLS protocols. Madrid-based high-volume merchants drive concentration here, motivated by per-transaction economics and acquiring bank integration requirements.
- Fraud Prevention:Machine learning scoring layers and chargeback mitigation tools reduce merchant liability exposure. Barcelona fintech clusters exhibit strongest demand, pressured by PSD2 dispute resolution timelines and escalating friendly fraud rates in cross-border e-commerce.
- Currency Conversion:Dynamic pricing engines enabling euro-denominated settlement for international card schemes.
- Reporting Tools:Reconciliation dashboards and transaction analytics for merchant finance teams.
By volume, Transaction Processing leads. By growth pace, Fraud Prevention is climbing the fastest.
Integration Method:
Cost tier stratification separates developer-intensive implementations from plug-and-play alternatives, with API deployments commanding premium pricing against commoditized hosted solutions.
- API:Programmable checkout layers embed directly into custom storefronts and mobile applications via REST or GraphQL endpoints. Developer-centric merchants in Barcelona's startup density concentrate demand here, requiring granular control over user experience and tokenization workflows.
- Hosted Payment Page:Vendor-controlled checkout interfaces redirect customers away from merchant domains. Small retailers across Andalusia and Valencia prefer this modality, outsourcing PCI-DSS scope reduction without internal security teams.
- Plug-in:Pre-built connectors for major e-commerce platforms requiring minimal configuration.
- Mobile SDK:Native iOS and Android libraries for in-app payment flows.
By deployment count, Hosted Payment Page leads. By revenue per merchant, API is expanding most quickly.
End User:
Application context dictates feature prioritization, with subscription services demanding vault-level tokenization against retailers' focus on omnichannel reconciliation.
- E-commerce Platforms:Marketplace operators and direct-to-consumer brands requiring high-availability checkout infrastructure. Madrid's fashion and electronics verticals concentrate here, driven by seasonal traffic spikes and cross-border selling complexity.
- Retailers:Brick-and-mortar merchants migrating from isolated POS terminals to unified payment stacks. Catalonian retail chains lead adoption, compelled by DORA operational resilience mandates and terminal replacement subsidies.
- Subscription Services:Recurring billing providers needing card-on-file persistence and dunning management.
- Nonprofits:Donation processors with simplified compliance requirements and lower transaction volumes.
By transaction value, E-commerce Platforms lead. By onboarding velocity, Retailers are gaining share fastest.
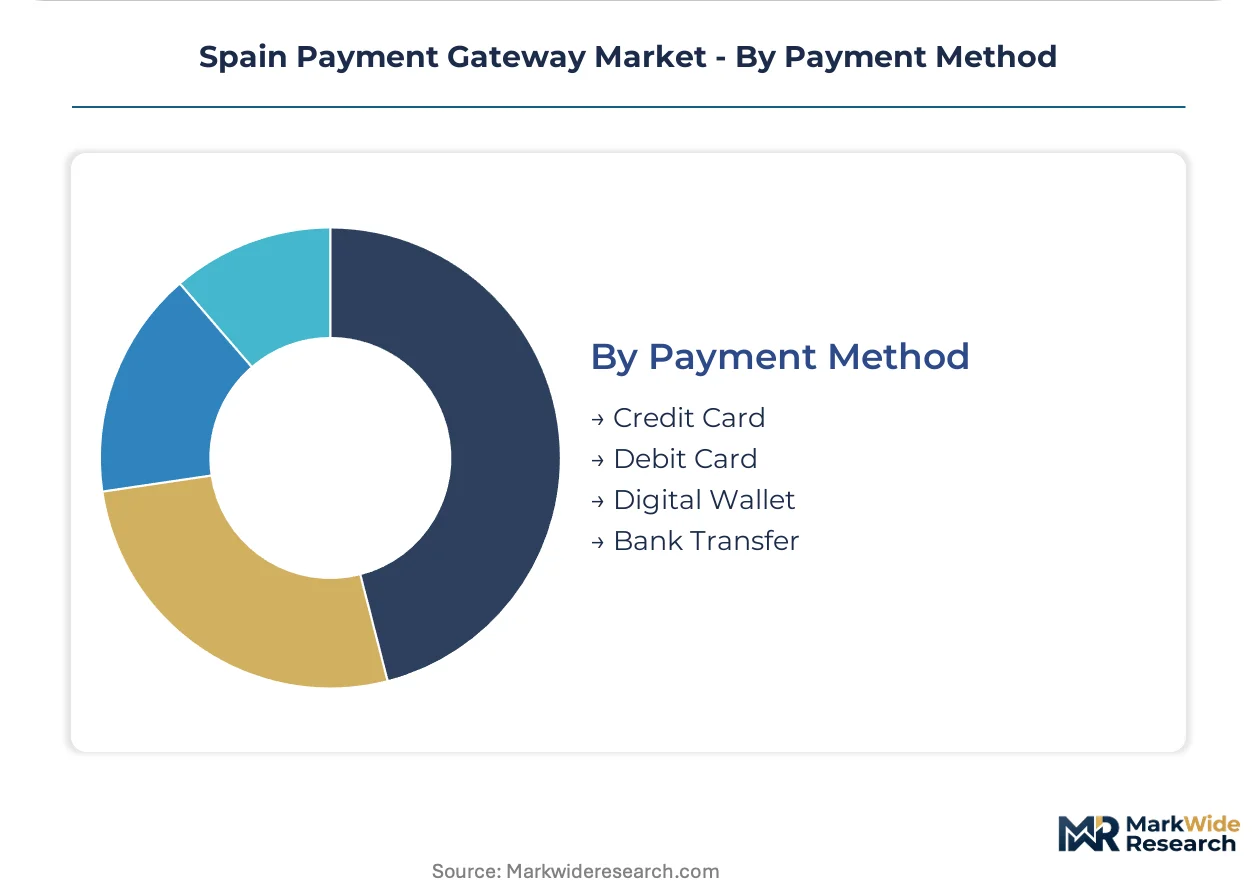
Payment Method:
Customer type and geography shape method acceptance patterns, with digital wallets capturing urban youth demographics against bank transfer persistence in B2B invoicing.
- Credit Card:Revolving credit products from Visa and Mastercard networks dominate high-ticket e-commerce. Affluent consumer segments in Madrid and Barcelona drive concentration, supported by strong issuer bank marketing and rewards program density.
- Debit Card:Direct-account deduction instruments preferred for everyday purchasing. Widespread adoption across Spanish provinces reflects conservative consumer debt attitudes and ING-DiBa, BBVA, and Santander debit product penetration.
- Digital Wallet:Apple Pay, Google Pay, and PayPal tokenized credentials. Urban millennials in Barcelona and Valencia exhibit strongest uptake, accelerated by in-app commerce and contactless terminal deployment.
- Bank Transfer:SEPA direct debit and instant credit transfer rails. B2B merchants and utility billers concentrate demand here, leveraging low-cost settlement against longer authorization windows.
By transaction count, Debit Card leads. By acceptance expansion, Digital Wallet shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish payment gateway infrastructure flows outward from Madrid and Barcelona toward secondary commercial centers, with regulatory harmonization under EU frameworks enabling cross-border service provision into Portugal and Latin American markets.
Madrid
Madrid concentrates Spain's highest e-commerce transaction density and fintech startup formation. The Bank of Spain's oversight of payment service providers under PSD2 frameworks shapes local compliance architecture. The capital's fashion and electronics verticals drive demand for high-availability checkout infrastructure capable of handling seasonal traffic spikes.
Catalonia
Catalonia anchors merchant acquiring relationships through Barcelona's dense banking cluster and terminal infrastructure. INCIBE collaborates with regional authorities to audit critical payment operators under national cybersecurity frameworks. Retail chains across the province lead cloud-migration adoption, compelled by DORA operational resilience mandates and terminal replacement subsidies.
Andalusia
Andalusia presents whitespace opportunity as Seville and Málaga exhibit lower gateway saturation than northern metros. EU cohesion funds support digital transformation programs for regional retailers. Merchant onboarding velocity accelerates as independent software integrators capture procurement influence previously held by direct bank sales channels.
Basque Country
The Basque Country maintains industrial B2B payment concentration through manufacturing and logistics corridors. Local cooperative banking structures shape merchant acquiring preferences distinct from Madrid-centric commercial banking. Bilbao's systems integrator community displaces traditional vendor relationships through compressed 8-12 week procurement cycles.
Valencia
Valencia's tourism and hospitality sectors drive seasonal payment volume volatility requiring elastic infrastructure. The region's mid-market retailers favor hosted payment page solutions that outsource PCI-DSS compliance scope. Valencia's independent software vendors increasingly intermediate between gateway providers and merchant end-users.
Spain Payment Gateway Market Competitive Landscape
Player mix skews toward banking-affiliated incumbents and developer-centric fintech platforms, creating a bifurcated structure where scale advantages concentrate with diversified financial groups while agility resides with API-native specialists. Strategic archetypes include full-stack merchant acquirers, pure-play gateway technologists, and consortium-based domestic networks. Competitive moves center on embedded finance convergence and fraud-prevention capability consolidation.
Within the banking-affiliated tier, BBVA and CaixaBank Payments & Consumer anchor positions through proprietary acquiring infrastructure and deep Iberian merchant relationships. Stripe exemplifies the API-first archetype, capturing developer-centric merchants building custom storefronts. Redsys occupies a distinctive position as a domestic network consortium, reflecting Spain's historically fragmented card processing landscape.
| Leading Market Players |
|---|
| Stripe |
| BBVA |
| Redsys |
| CaixaBank Payments & Consumer |
| Worldline |
| Bizum |
| PayPal |
| Mollie |
| Adyen |
| Others |
Pricing and Supply Chain Analysis
PCI-DSS certification tiers gate both supplier qualification and price differentiation simultaneously in Spain's payment gateway sector, forcing vendors to absorb audit costs or pass them through to merchants based on integration complexity and transaction scale.
Pricing Analysis
Next-generation API-first architectures command 40-60% premiums over legacy hosted payment pages, while prior-generation POS-terminal gateways face accelerating price erosion. Three-tier pricing structure across enterprise API, mid-market plug-in, and small-merchant hosted solutions dominates, with certification grade and transaction volume scale as primary differentiation drivers. Cost compression in the hosted tier is intensifying because BBVA and CaixaBank bundle gateway services below standalone rates. Small retailers in Andalusia exhibit highest price sensitivity, whereas Barcelona fintechs prioritize developer experience over per-transaction economics.
Supply Chain Analysis
Hardware security module inventory cycles and TLS certificate provisioning lead times have compressed from 12 weeks to 4 weeks as vendors regionalize procurement. Spain's gateway infrastructure draws from Netherlands-based data centers, Irish cloud regions, and German cybersecurity vendors for core components. Tokenization engines, fraud-scoring APIs, and SEPA rail connectivity constitute critical input dependencies. Single-source vulnerability concentrates in Visa and Mastercard network token provisioning, where dual-format ISO 20022 migration creates temporary interoperability risk. Distribution runs through Madrid and Barcelona systems integrators who displace direct vendor relationships.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's payment gateway sector represents early-cycle expansion as DORA compliance mandates force terminal replacement and cloud migration across thousands of legacy POS-dependent merchants.
For Market Incumbents: Consolidate fraud-prevention capabilities through targeted API acquisitions before EU AI Act transparency requirements crystallize competitive positioning. BBVA and CaixaBank should deepen acquiring infrastructure control in Catalonia, where DORA penetration testing mandates are compressing vendor selection cycles and threatening independent gateway margins. For New Entrants and Emerging Players: Lead with embedded finance convergence in Seville and Málaga, where Andalusian whitespace and EU cohesion fund subsidies accelerate merchant onboarding velocity. Target mid-market retailers through independent software vendor partnerships rather than direct sales channels, mirroring Valencia's procurement pattern shift. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-powered fraud scoring sub-segments as algorithmic transparency investments become mandatory. Five-to-ten year viability favors platforms with Bank of Spain operating licenses and established INCIBE audit relationships. Monitor EU AI Act classification timelines for automated scoring algorithms as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fraud Prevention Capability Acquisition | Consolidates machine learning scoring layers ahead of EU AI Act compliance deadlines. |
| Embedded Finance Integration | Captures merchant banking relationships through lending and treasury services at checkout. |
| Andalusian Geographic Expansion | Exploits lower gateway saturation in Seville and Málaga via EU-funded digital programs. |
| API-First Architecture Investment | Serves Barcelona developer density with programmable checkout layers and tokenization control. |
| DORA Compliance Infrastructure Buildout | Enables 24-hour incident reporting and penetration testing certifications for Bank of Spain licensing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with payment gateway CTOs, merchant acquiring executives at Iberian banks, systems integrators in Valencia and Bilbao, and cybersecurity compliance officers at INCIBE. Secondary validation drew from Bank of Spain PSD2 implementation reports, European Banking Authority DORA guidance documents, EU AI Act legislative texts, and SEPA instant credit transfer statistics. Bottom-up merchant adoption modeling triangulated against top-down transaction volume projections.
Across the analysis window, forecasts reflect segmentation across service type, integration method, end-user vertical, and payment method dimensions, with Madrid-Barcelona transaction density and Andalusian penetration rates as Spain-specific inputs. CAGRs were derived from historical e-commerce growth trajectories, terminal replacement subsidy disbursement schedules, and regulatory compliance timeline assumptions.
Forecasts assume regulatory continuity in EU PSD2, DORA, and AI Act regimes; material policy shifts or delayed implementation would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Fingerprint Payment Market
Payments
Global Utility Billing Software Market
Payments
Indonesia Prepaid Cards Market
Payments
Asia Pacific Mobile Wallet Market
Payments
E-Commerce Payments Market
Payments
India Forex Cards Market
Payments
Australia Buy Now Pay Later Services Market
Payments
Egypt Mobile Payments Market
Payments
Malta POS Terminal Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Africa Mobile Money Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Canada Buy Now Pay Later Market
Payments
Germany POS Terminal Market
Payments
M Commerce Payment Market
Payments
Global Bitcoin Payments Ecosystem Market