
 China Mobile Payments Market | 2026-2036
China Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
China Mobile Payments Market Analysis
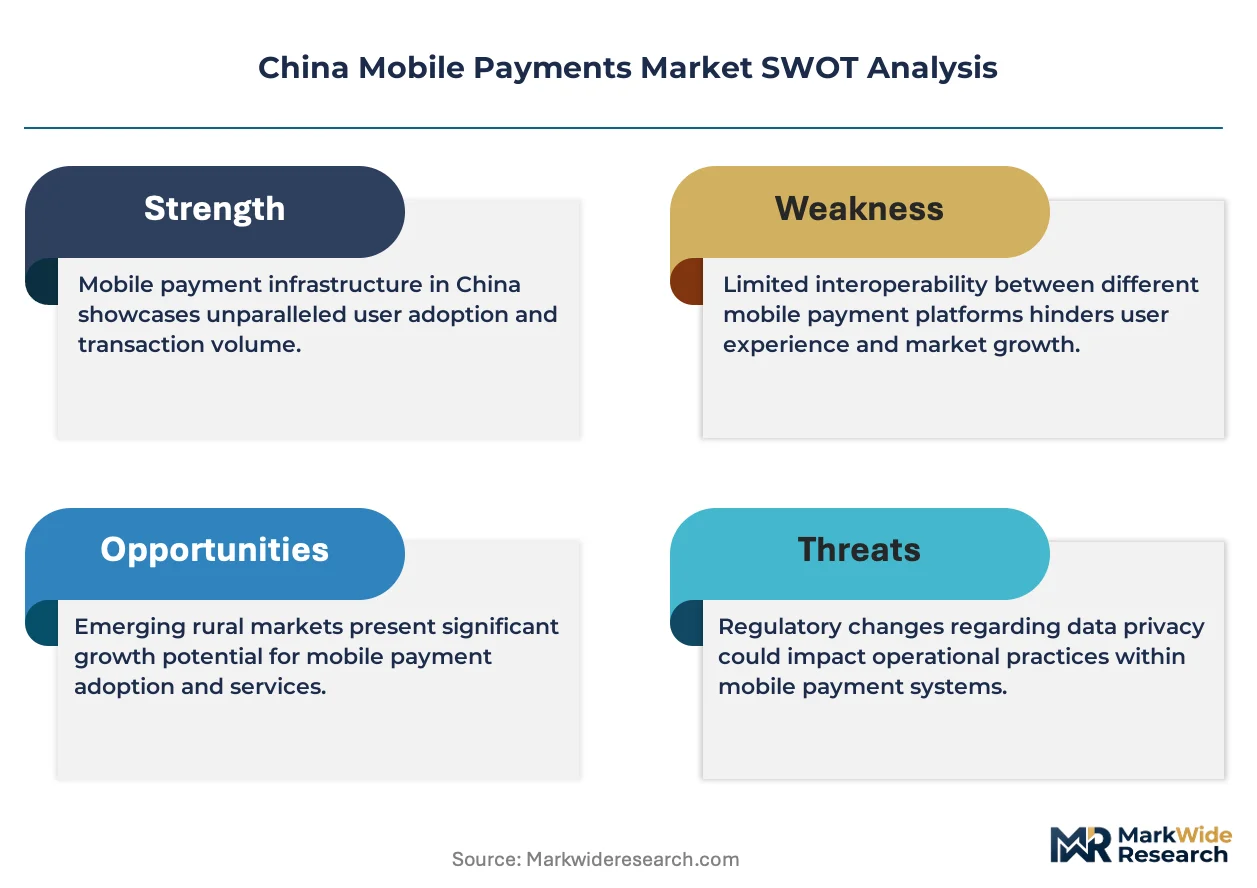
Buyer concentration among China's small and micro-merchants is pivoting from fragmented street vendors toward organized rural e-commerce sellers integrating digital checkout tools. Alipay leverages its embedded finance architecture to sustain merchant lock-in across tier-three and tier-four cities. WeChat Pay anchors consumer habit formation through mini-program ecosystems that merge social engagement with transaction completion. JD Pay competes by specializing in supply-chain finance linkages that tie payment flows to inventory management for agricultural cooperatives.
China mobile payments encompass funds transfer, settlement, and account services executed through wireless-enabled devices using near-field communication, tokenized credentials, or dynamically generated quick-response matrices. These systems process renminbi-denominated transactions through encrypted channels connecting consumer bank accounts, licensed non-bank payment institutions, and merchant acquiring networks. QR code penetration dominates transaction volume among payment methods due to minimal hardware requirements and ubiquitous smartphone compatibility. Peer-to-peer transfers represent the fastest-expanding transaction type, driven by social gifting conventions and informal lending circles. Smartphone-based execution maintains structural primacy across device types, though wearable form factors gain traction among transit-integrated urban commuters.
SAMR licensing requirements govern market access for non-bank payment institutions, while PBOC's digital currency trials reshape competitive dynamics between private platforms and state-issued e-CNY infrastructure. MIIT data-localization mandates constrain cross-border data routing, compelling platform operators to expand domestic server capacity. Stakeholders must monitor how PBOC's central bank digital currency expansion alters fee structures and deposit displacement risks for incumbent wallet providers.
Market Dynamics
PBOC's e-CNY trials are compressing fee structures and forcing private wallet providers to defend merchant relationships through embedded finance expansion.
Growth Catalysts
- Dual carbon policy framework:MIIT mandates for green data centers are accelerating renewable-powered server investments by fintech platforms seeking carbon-neutral payment processing.
- Rural e-commerce merchant onboarding:Agricultural cooperatives in Henan and Sichuan provinces are digitizing procurement workflows, creating sustained transaction volume growth for supply-chain-integrated payment tools.
- Tokenized credential infrastructure:NMPA data-security protocols are standardizing encrypted biometric authentication, reducing fraud friction for high-value peer-to-peer transfers.
Market Restraints
- Data-localization capex burden:MIIT server-residency requirements compel platforms to duplicate infrastructure across provincial nodes, elevating fixed-cost intensity.
- State payment infrastructure substitution:PBOC's e-CNY wallet threatens to displace private deposit pools, compressing interest-income models for incumbent non-bank institutions.
- Cross-border settlement friction:SAMR licensing restrictions block outbound data routing, isolating Chinese payment rails from ASEAN merchant networks.
Strategic Opportunities
- Western province penetration:Gansu and Qinghai exhibit sub-40% digital-wallet adoption among rural merchants, offering first-mover expansion potential for QR-code acquirers.
- Wearable-transit convergence:Shenzhen hardware manufacturers are integrating payment chips into transit wristbands, opening subscription-based commuter revenue streams.
- Agricultural supply-chain finance:Provincial rural credit cooperatives seek API partnerships to embed payment triggers into harvest-season inventory financing.
Industry Challenges
- Biometric-engineering talent scarcity:NMPA-grade facial-recognition algorithm development requires specialized computer-vision expertise concentrated in Beijing and Hangzhou.
- Legacy bank core-system integration:State-owned commercial banks operate on decades-old mainframe architectures that resist real-time API connectivity for wallet top-ups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Mobile Payments Market |
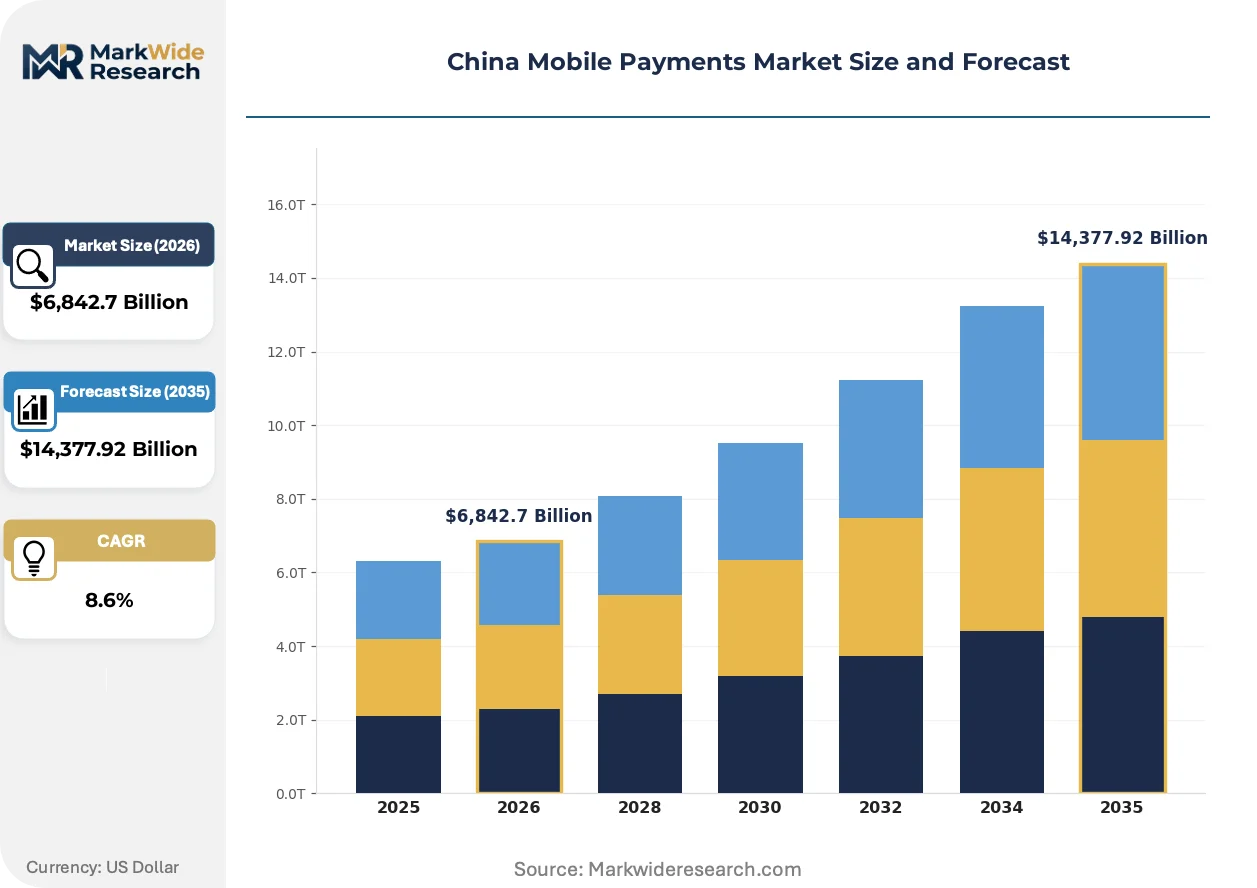
| Market Size in 2026 | $6,842.7 Billion |
| Market Size in 2035 | $14,377.92 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Digital Wallet, QR Code, Online Banking End User: Retailers, Consumers, Corporates, Service Providers Device Type: Smartphone, Tablet, Wearable, POS Terminal Transaction Type: In-Store, Online, Peer-to-Peer, Bill Payment |
| Companies Covered | Alipay, WeChat Pay, China UnionPay, JD Pay, Baidu Wallet, LianLian Pay, Ping An Pay, Tenpay, Bestpay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Mobile Payments Market Emerging Trajectories
Payment infrastructure is fragmenting across state-issued and private rails while hardware form factors diversify beyond smartphones into ambient transaction surfaces.
Blockchain-based settlement layers are decentralizing clearing architecture for high-value B2B transfers. Manufacturing supply-chain managers in the Pearl River Delta are piloting distributed-ledger reconciliation to compress multi-day settlement windows into hours. This compression is decentralizing correspondent-banking relationships that historically dominated cross-border trade finance.
SAMR's 2024 revisions to non-bank payment institution licensing rules are tightening capital-reserve requirements and mandating real-time transaction monitoring. Platforms must now maintain segregated reserve accounts at designated commercial banks, elevating compliance operational costs. Tier-two city acquirers are responding by consolidating merchant portfolios to achieve economies of scale in audit infrastructure.
Social-commerce purchasing patterns are displacing standalone e-commerce checkout flows. Mini-program ecosystems within super-apps now capture the majority of discretionary spending by consumers in tier-three cities, collapsing the traditional browse-cart-pay funnel into single-interface discovery-to-payment completion. This behavioral shift is most pronounced in Guangdong and Jiangsu provinces where live-streaming merchant density exceeds national averages.
China Mobile Payments Market Segmentation
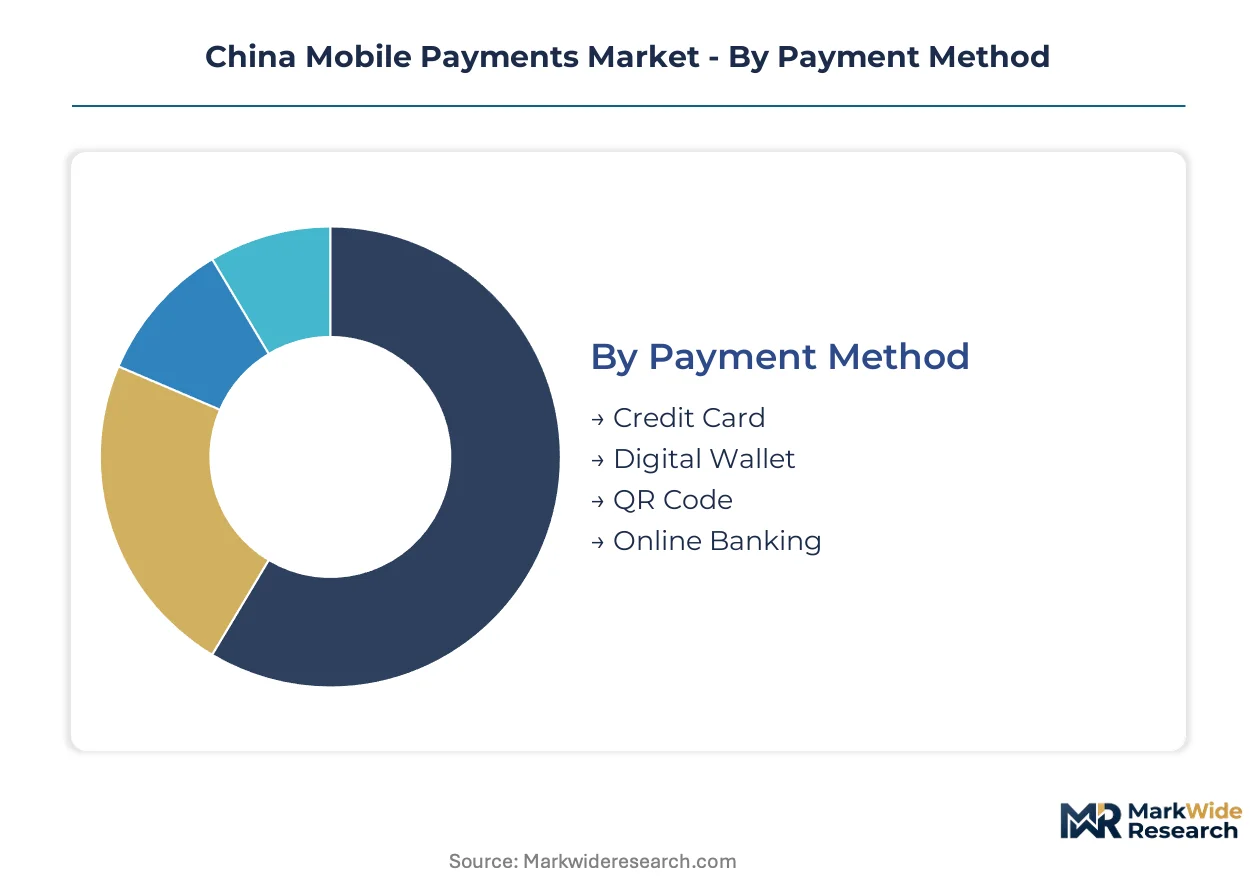
Segmentation in China's mobile payments market reveals how regulatory requirements and infrastructure investments fragment across transaction modalities. SAMR licensing tiers, MIIT data-localization mandates, and NMPA security protocols create distinct compliance burdens that shape platform economics and competitive positioning within each category.
Payment Method:
QR Code and Digital Wallet segments carry the heaviest certification load under NMPA data-security protocols and SAMR capital-reserve requirements, while Credit Card and Online Banking operate under established PBOC banking regulations with lighter fintech-specific compliance overlays.
- QR Code:Two-dimensional matrix codes encode tokenized transaction credentials readable by merchant smartphone cameras or dedicated scanners. Demand concentrates among rural e-commerce merchants in Henan and Sichuan provinces where minimal hardware requirements enable rapid onboarding without POS terminal investment. NMPA encryption standards for dynamic QR generation elevate engineering costs but reduce fraud friction for agricultural cooperatives.
- Digital Wallet:Stored-value accounts maintained by licensed non-bank payment institutions, integrating funds transfer, loyalty programs, and embedded finance services. Shenzhen's technology corridor anchors super-app ecosystem development where Alipay and WeChat Pay sustain merchant lock-in through mini-program architectures. SAMR's 2024 capital-reserve revisions compel segregated account structures that compress interest-income models.
- Credit Card:Bank-issued revolving credit instruments tokenized for mobile execution, governed by PBOC card association rules rather than fintech licensing frameworks.
- Online Banking:Direct account-to-account transfers through licensed commercial bank mobile applications, requiring MIIT-grade data localization but avoiding SAMR non-bank payment institution oversight.
Leading the category by volume: QR Code. Growing fastest: Digital Wallet.
End User:
Cost tier differentiation separates high-frequency low-margin Consumer transactions from infrastructure-intensive Corporate deployments requiring API integration and supply-chain finance linkages.
- Retailers:Merchant acquirers spanning street vendors to organized rural e-commerce sellers, with tier-three and tier-four city penetration driving aggregate transaction volume growth. Agricultural cooperatives in Gansu and Qinghai provinces exhibit sub-40% digital-wallet adoption, creating first-mover expansion potential for QR-code acquirers willing to absorb MIIT server-residency capex.
- Consumers:Individual account holders executing peer-to-peer transfers, social gifting, and discretionary spending through super-app interfaces. Guangdong and Jiangsu provinces concentrate demand where live-streaming merchant density exceeds national averages and mini-program ecosystems collapse discovery-to-payment funnels.
- Corporates:Enterprise treasury management, payroll disbursement, and B2B procurement workflows requiring real-time API connectivity with state-owned commercial bank core systems.
- Service Providers:Utility billing platforms, transit operators, and municipal service aggregators integrating payment triggers into subscription-based revenue models.
Dominating transaction count: Consumers. Commanding highest revenue per transaction: Corporates.
Device Type:
Application context determines hardware selection, with transit-integrated urban commuters driving wearable adoption while agricultural merchants rely on smartphone-based QR scanning.
- Smartphone:Ubiquitous touchscreen devices executing NFC, QR, and app-based transactions through encrypted wireless channels. Structural primacy persists across all user segments due to minimal incremental hardware cost and universal consumer penetration.
- Wearable:Transit wristbands and payment-enabled accessories integrating with Shenzhen hardware manufacturer supply chains. Subscription-based commuter revenue streams emerge as Shenzhen manufacturers embed payment chips into form factors targeting urban rail networks.
- Tablet:Larger-screen devices deployed in fixed retail locations for inventory management integration and customer-facing checkout interfaces.
- POS Terminal:Dedicated acquiring hardware with NFC and QR capabilities, concentrated in tier-one and tier-two city retail environments where merchant scale justifies dedicated infrastructure investment.
Highest installed base: Smartphone. Steepest expansion trajectory: Wearable.
Transaction Type:
Volume concentration versus margin structure differentiates high-frequency low-value Peer-to-Peer transfers from infrastructure-intensive Online commerce requiring cart integration and dispute resolution systems.
- Peer-to-Peer:Direct account transfers between individuals, driven by social gifting conventions and informal lending circles. Fastest-expanding transaction type as NMPA biometric authentication standards reduce friction for high-value transfers between trusted counterparties.
- Online:E-commerce and service purchases through integrated checkout flows, with social-commerce mini-programs displacing standalone marketplace transactions. Guangdong Province concentrates demand where super-app ecosystems merge social engagement with payment completion.
- In-Store:Physical merchant location transactions via QR scan or NFC tap, dominating aggregate volume through rural e-commerce merchant onboarding in western provinces.
- Bill Payment:Recurring utility, subscription, and municipal service settlements, often executed through automated wallet deduction or dedicated payment mini-programs.
Greatest transaction volume: In-Store. Climbing the fastest: Peer-to-Peer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province concentrates transaction volume through Shenzhen's technology corridor, where super-app ecosystems anchor merchant-acquiring networks and live-streaming commerce density exceeds national benchmarks.
Guangdong Province
Shenzhen's hardware manufacturers drive wearable-transit convergence through payment-integrated wristbands, while Guangzhou's merchant acquirers process QR-code volumes for tier-one retail corridors. SAMR licensing requirements govern non-bank payment institutions operating across the Pearl River Delta. Shenzhen anchors super-app ecosystem development where mini-program architectures collapse discovery-to-payment funnels for social-commerce merchants.
Zhejiang Province
Hangzhou's fintech clusters concentrate biometric-engineering talent for NMPA-grade facial-recognition algorithms, reducing fraud friction for high-value peer-to-peer transfers. MIIT data-localization mandates compel platform operators to expand domestic server capacity across provincial nodes. Hangzhou technology parks host algorithm development centers serving wallet providers competing on authentication speed.
Beijing Municipality
PBOC's digital currency trials reshape competitive dynamics between private platforms and state-issued e-CNY infrastructure across the capital region. The central bank's regulatory oversight compresses fee structures for incumbent wallet providers. Zhongguancun software parks anchor API development for agricultural supply-chain finance partnerships with provincial rural credit cooperatives.
Sichuan Province
Agricultural cooperatives in Chengdu and surrounding prefectures digitize procurement workflows, creating sustained transaction volume growth for supply-chain-integrated payment tools. NMPA data-security protocols standardize encrypted biometric authentication for rural e-commerce merchant onboarding. Chengdu's technology incubators host QR-code acquirers targeting sub-40% digital-wallet adoption among western province merchants.
Henan Province
Zhengzhou's logistics hubs integrate payment triggers into harvest-season inventory financing for grain and livestock cooperatives. Provincial rural credit cooperatives seek API partnerships to embed payment flows into agricultural supply-chain finance. Zhengzhou-based acquirers expand QR-code penetration among rural e-commerce sellers upgrading from fragmented street-vendor operations.
China Mobile Payments Market Vendor Landscape
Shenzhen-based technology conglomerates anchor one tier; Hangzhou specialists hold algorithmic differentiation in biometric authentication. The market structure concentrates around super-app ecosystems that merge social engagement with transaction completion, while tier-two city acquirers consolidate merchant portfolios to achieve compliance economies of scale. Three archetypes dominate: vertically integrated super-apps, supply-chain finance specialists, and state-backed payment infrastructure operators. Competitive moves center on embedded finance expansion and MIIT-compliant server-residency investments.
Within the super-app tier, Alipay and WeChat Pay exemplify merchant-lock-in strategies through mini-program architectures that collapse traditional e-commerce funnels. JD Pay occupies a position among supply-chain finance specialists, anchoring payment-flow integration for agricultural inventory management. China UnionPay represents the state-backed infrastructure archetype, bridging private wallet rails with PBOC's e-CNY trials and legacy banking networks.
| Leading Market Players |
|---|
| Alipay |
| WeChat Pay |
| China UnionPay |
| JD Pay |
| Baidu Wallet |
| LianLian Pay |
| Ping An Pay |
| Tenpay |
| Bestpay |
| Others |
Supply Flow & Price Mechanics
Backward integration into server infrastructure anchors supply positioning for fintech platforms confronting MIIT data-localization mandates, while simultaneously compressing pricing power through elevated fixed-cost intensity. This integration choice forces platforms to absorb provincial node duplication costs that feed directly into merchant acquiring fee structures.
Pricing Analysis
High-volume low-margin QR-code transactions dominate aggregate throughput while digital-wallet services capture premium yields through embedded finance bundling. Pricing stratifies across premium, standard, and economy tiers based on NMPA certification grade and merchant volume scale. Cost compression in tier-three city acquiring is intensifying because SAMR capital-reserve requirements elevate compliance operational overhead. Agricultural cooperatives exhibit highest price sensitivity due to thin harvest-season margins, while Shenzhen super-app ecosystems demonstrate lowest sensitivity through captive consumer bases.
Supply Chain Analysis
Dual-sourcing requirements for biometric authentication chips compel wallet providers to qualify both Hangzhou algorithm developers and Beijing computer-vision specialists simultaneously. Hardware supply concentrates in China, South Korea, and Taiwan for NFC-enabled wearable components. Raw material dependencies span semiconductor wafers, encrypted security modules, and renewable-power infrastructure for MIIT-compliant data centers. Single-source vulnerability persists for NMPA-grade facial-recognition algorithm licensing. Distribution runs through provincial rural credit cooperative networks for agricultural merchant onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's mobile payments sector is navigating a technology-transition phase where PBOC's e-CNY infrastructure replaces legacy private deposit-pool models. This displacement forces stakeholders to recalibrate around state-issued rails while defending residual merchant relationships.
For Market Incumbents: Anchor merchant lock-in through mini-program ecosystem expansion that collapses discovery-to-payment funnels into single-interface completion. Deepen API partnerships with provincial rural credit cooperatives to embed payment triggers into harvest-season inventory financing. Defend against e-CNY deposit displacement by accelerating embedded finance service bundling that state infrastructure cannot replicate.
For New Entrants and Emerging Players: Blockchain-based settlement layers offer technology-first wedge opportunities for B2B procurement workflows in Pearl River Delta manufacturing clusters. Target Gansu and Qinghai provinces where sub-40% digital-wallet adoption among rural merchants creates first-mover expansion potential. Pursue wearable-transit convergence partnerships with Shenzhen hardware manufacturers seeking subscription-based commuter revenue streams.
For Investors and Strategic Acquirers: Exit pathways concentrate in supply-chain finance specialists with agricultural cooperative API integration and MIIT-compliant server infrastructure. Long-term viability favors platforms with backward integration into renewable-powered data centers and NMPA-grade biometric authentication capabilities. Watch PBOC e-CNY wallet adoption velocity as the critical inflection signal for private deposit-pool displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| MIIT-Compliant Server Expansion | Provincial node duplication satisfies data-localization mandates while elevating fixed-cost intensity for acquirers. |
| NMPA Biometric Certification Investment | Encrypted facial-recognition algorithms reduce fraud friction for high-value peer-to-peer transfers in rural markets. |
| Agricultural Supply-Chain API Integration | Payment triggers embedded into harvest-season inventory financing lock in cooperative merchant relationships. |
| Wearable-Transit Hardware Partnership | Shenzhen manufacturer collaboration opens subscription-based commuter revenue streams for urban rail networks. |
| Embedded Finance Service Bundling | Loyalty programs and credit extension defend merchant relationships against PBOC e-CNY deposit displacement. |
Methodological Framework
Document review covered PBOC regulatory circulars, SAMR licensing databases, and MIIT infrastructure disclosures, complemented by interviews with fintech platform executives, provincial rural credit cooperative managers, merchant acquirer operations leads, and biometric algorithm engineering directors. Secondary validation drew from PBOC payment system statistics, NMPA data-security protocol filings, and MIIT green data center certification records. Bottom-up transaction volume modeling and top-down regulatory impact assessment were triangulated to cross-verify segment sizing.
Cross-reference approaches combined historical transaction growth patterns against expert panel input on e-CNY adoption trajectories. The analytical framework modeled payment method, end user, device type, and transaction type dimensions across the projection horizon. CAGRs were derived from regression analysis of provincial adoption curves and infrastructure investment cycles. Forecast inputs included MIIT server-residency capex schedules and NMPA encryption standard implementation timelines.
Several conditions sit outside the modeled scope, including abrupt PBOC policy shifts on e-CNY merchant fee structures and unforeseen NMPA biometric protocol revisions. Forecasts reflect assumptions around gradual rural e-commerce merchant onboarding and stable SAMR capital-reserve requirements. Deviation in PBOC digital currency substitution velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
In-Vehicle Payment Services Market
Payments
Digital Payment in Healthcare Market
Payments
Ireland POS Terminals Market
Payments
Global Mobile Payment Technology Market
Payments
Global Point of Sale Terminals Market
Payments
Global Prepaid Cards Market
Payments
Argentina Mobile Wallet Market
Payments
Belgium POS Terminals Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
China POS Terminals Market
Payments
Germany Real Time Payments Market
Payments
Face-Swiping Payment Market
Payments
Japan Retail Cash Management Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Latin America Payment Gateway Market
Payments
Italy POS Terminals Market