
 Brightwood Tray Market | 2026-2036
Brightwood Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Brightwood Tray Market Outlook
The capital-intensity divergence between automated veneer-press operators and hand-finish workshops is collapsing as digital cutting and UV-curing equipment becomes accessible at mid-scale price points. Smurfit Kappa Group plc leverages its integrated pulp-to-packaging infrastructure to control raw material costs across European tray production. JohnsByrne anchors its position through specialized high-end decorative finishing for hospitality brands. PakFactory competes on rapid-turn customization for boutique restaurant chains seeking short-run branded serveware.
Brightwood trays are rigid serving platforms manufactured from laminated wood veneers, bamboo composites, or engineered fiberboard, typically finished with food-safe coatings and precision-molded to depths of one to three inches for containment of plated items or beverages. Production employs rotary die-cutting, hot-press lamination, and automated edge-banding to achieve dimensional tolerances suited to commercial dishwasher cycles. The material dimension shows bamboo gaining share against traditional hardwoods as supply chains prioritize rapidly renewable feedstocks with lower moisture-absorption coefficients. Within end users, restaurants dominate volume while catering services represent the fastest-expanding application as event planners specify sustainable serveware for corporate and wedding contracts. Serving trays command the largest product-type volume, though decorative trays carry higher per-unit margins through artisanal finishing and limited-edition collaborations.
The US FDA maintains food-contact substance regulations governing coatings and adhesives in wooden foodware, while the EU REACH framework restricts certain preservative treatments previously common in mass-market tray production. California's Proposition 65 labeling requirements create additional compliance thresholds for products entering the West Coast hospitality supply chain. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances in food-contact materials, as these compound coating selections and supplier qualification protocols across North American distribution channels.
Market Dynamics
The Brightwood Tray Market pivots on the EU Packaging and Packaging Waste Regulation's mandate to phase out single-use plastics, which forces hospitality procurement teams to certify wooden serveware for commercial dishwasher cycles and food-contact compliance.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory reduction targets for disposable plastics push restaurant chains across Germany, France, and Italy to specify certified Brightwood trays for dine-in service.
- Bamboo-composite molding:Rapidly renewable feedstocks with lower moisture-absorption coefficients enable manufacturers to meet commercial durability standards while satisfying sustainability procurement scorecards.
- Catering services:Event planners for corporate and wedding contracts specify reusable wooden serveware as brand-differentiation elements, expanding volume beyond traditional restaurant channels.
Market Restraints
- Hardwood veneer price volatility:Baltic birch and beech supply concentrates in Eastern European forestry operations, exposing converters to input cost swings from weather-related harvest disruptions.
- Food-contact coating qualification:US FDA substance regulations and California Proposition 65 labeling requirements extend supplier onboarding timelines by 8-14 months for North American market entry.
- Melamine-resin substitutes:Lower-cost molded serveware retains share in QSR and institutional cafeteria segments where capital budgets prioritize unit economics over sustainability metrics.
Strategic Opportunities
- Airline premium cabin service:Carriers redesigning long-haul dining experiences seek lightweight, branded wooden trays to replace plastic-lined meal carts and support net-zero commitments.
- EU Green Deal circular economy incentives:Member-state recovery funds subsidize manufacturing equipment upgrades for SMEs producing reusable food-contact articles from certified renewable sources.
- Direct-to-restaurant digital platforms:Specialized B2B marketplaces bypass traditional foodservice distribution tiers, enabling tray fabricators to capture margin from customization services and short-run production.
Industry Challenges
- Precision mold-making talent:Rotary die-cutting and hot-press lamination require skilled technicians familiar with veneer moisture-content management, a competence pool concentrated in legacy furniture-manufacturing regions.
- Multi-jurisdiction coating compliance:Reconciling EU REACH restrictions on preservative treatments with US FDA adhesive approvals forces dual-formulation inventories and complicates cross-border supply chains.
- Automated edge-banding capex:Mid-scale workshops face equipment investment thresholds to achieve dimensional tolerances required by commercial dishwasher specifications, compressing margins during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brightwood Tray Market |
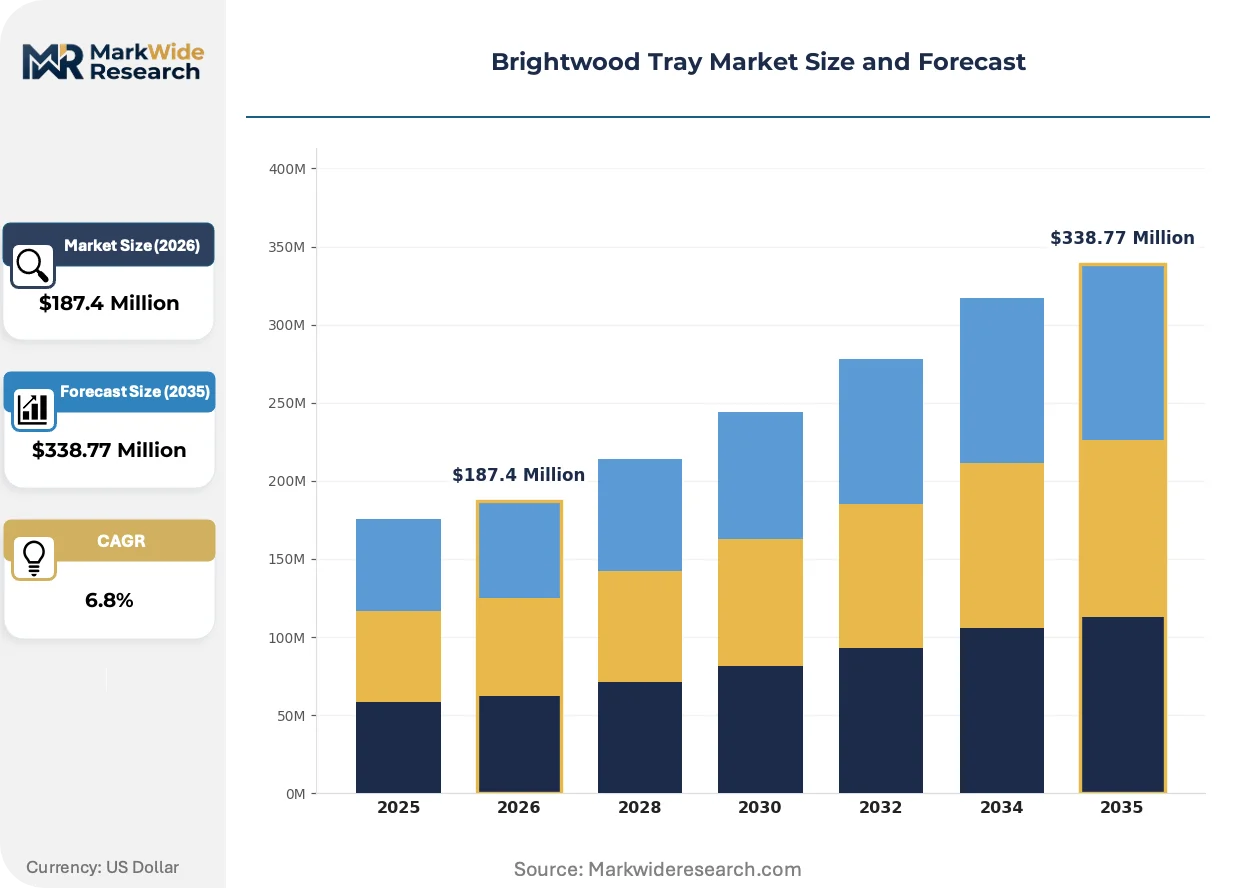
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serving Tray, Decorative Tray, Multi-purpose Tray, Food Tray Material: Wood, Plastic, Metal, Bamboo End User: Households, Restaurants, Cafes, Catering Services Shape: Rectangular, Round, Square, Oval |
| Companies Covered | Cartoncraft Incorporated, New York Label & Box Works, JohnsByrne, Packaging Logic, Inc., PakFactory, Online Print & Pack Private Limited, Quality Box and Package, Smurfit Kappa Group plc, Multi-Color Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brightwood Tray Market Strategic Shifts
Digital cutting and UV-curing equipment democratizes precision manufacturing, collapsing the capability gap between automated veneer-press operators and hand-finish workshops while enabling new entrants to compete on customization speed.
UV-curable acrylate coatings is displacing traditional solvent-based lacquers in Brightwood tray finishing. Premium casual dining chains in Germany and the United States specify these coatings for accelerated production cycles and enhanced scratch resistance. The technology is displacing batch-process finishing houses that cannot justify capital upgrades, concentrating supply among integrated manufacturers with in-house curing lines.
EU REACH framework restrictions on formaldehyde-releasing preservatives and certain biocide treatments reshape material qualification protocols. Manufacturers reformulate adhesive systems and heat-treat veneers to achieve compliance without performance degradation. German hospitality suppliers face the tightest enforcement timelines, driving early adoption of alternative bonding chemistry that will propagate across European production networks.
Certification-driven procurement now governs serveware selection for corporate catering contracts. Sustainability officers at event-planning firms require chain-of-custody documentation for bamboo and hardwood inputs, replacing price-first vendor selection. This pattern concentrates demand among fabricators with FSC or PEFC certification, visible most acutely in California and New York metropolitan markets where client ESG reporting obligations are most stringent.
Brightwood Tray Market Segmentation
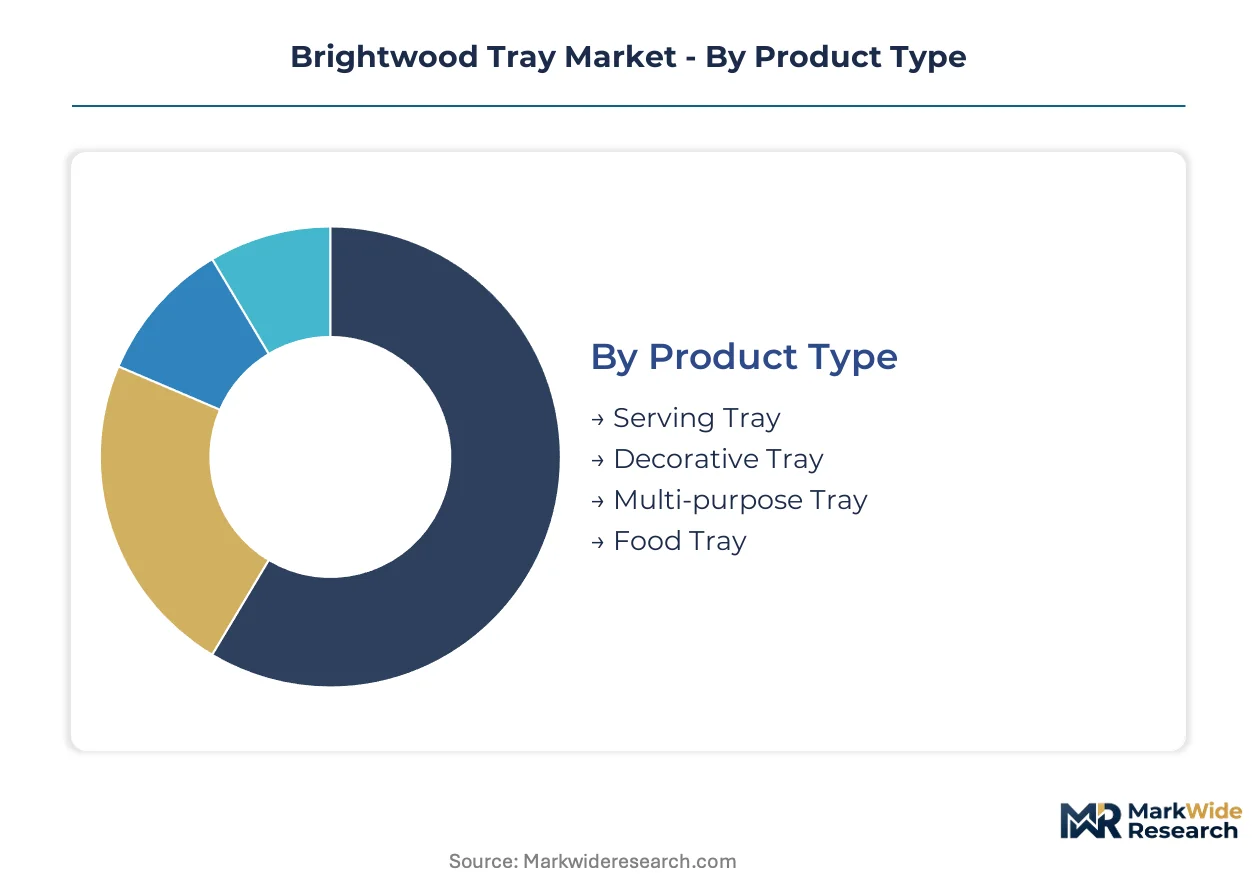
Tray fabricators configure production lines around four distinct segmentation axes. Product type determines finishing complexity and margin structure. Material selection governs compliance pathways and sustainability positioning. End-user concentration shapes volume forecasting and channel strategy. Shape specifications influence mold investment and customization economics.
Product Type:
Melamine-resin and injection-molded plastic substitutes exert the strongest displacement pressure on commodity tray segments where unit economics override sustainability procurement mandates.
- Serving Tray:Rigid platforms with one to three inch containment depths, engineered for commercial dishwasher cycles and high-frequency restaurant turnover. Demand concentrates in Germany and the United States where premium casual dining chains specify certified wooden serveware for brand differentiation against plastic alternatives.
- Decorative Tray:Artisanal finishing and limited-edition collaborations command elevated per-unit margins through specialized high-end decorative techniques. Wedding planners and corporate event coordinators in California and New York metropolitan markets drive procurement, requiring chain-of-custody documentation for ESG reporting obligations.
- Multi-purpose Tray:Modular designs adaptable across serving, display, and storage functions for residential and light commercial environments.
- Food Tray:Shallow-profile platforms optimized for cafeteria and QSR line service where speed of service dominates material selection criteria.
Serving Tray retains volume leadership; Decorative Tray holds the steepest expansion curve.
Material:
Cost tier stratification separates premium certified feedstocks from commodity inputs, with mid-market positioning increasingly contested by engineered composites.
- Wood:Laminated hardwood veneers from Baltic birch and beech supply chains, finished with UV-curable acrylate coatings for scratch resistance. Eastern European forestry operations concentrate raw material sourcing, exposing converters to weather-related harvest disruptions and price volatility.
- Bamboo:Rapidly renewable feedstocks with lower moisture-absorption coefficients enable compliance with commercial durability standards while satisfying sustainability procurement scorecards. German hospitality suppliers face the tightest EU REACH enforcement timelines, accelerating adoption across European production networks.
- Plastic:Virgin and recycled polymer formulations retain share in QSR and institutional cafeteria segments where capital budgets prioritize unit economics.
- Metal:Stainless steel and aluminum alternatives for industrial foodservice environments requiring extreme durability and thermal stability.
Wood dominates current production volumes; Bamboo is climbing the fastest as certification-driven procurement reshapes vendor selection.
End User:
Application concentration determines whether procurement flows through institutional distributors, direct-to-restaurant digital platforms, or event-planning intermediaries.
- Restaurants:Primary volume channel across North American and European markets where sustainability mandates tighten and disposable serving ware replacement accelerates. EU Packaging and Packaging Waste Regulation phase-out targets for single-use plastics force procurement teams to certify wooden serveware for commercial dishwasher cycles.
- Catering Services:Event planners for corporate and wedding contracts specify reusable wooden serveware as brand-differentiation elements. This segment expands volume beyond traditional restaurant channels with sustainability officers requiring FSC or PEFC certification documentation.
- Households:Residential consumption through retail and e-commerce channels, sensitive to price-positioning against ceramic and glass alternatives.
- Cafes:Specialty coffee and tea service environments where aesthetic presentation drives material selection alongside functional durability.
Restaurants anchor current demand; Catering Services is gaining share fastest as event-planning procurement professionalizes.
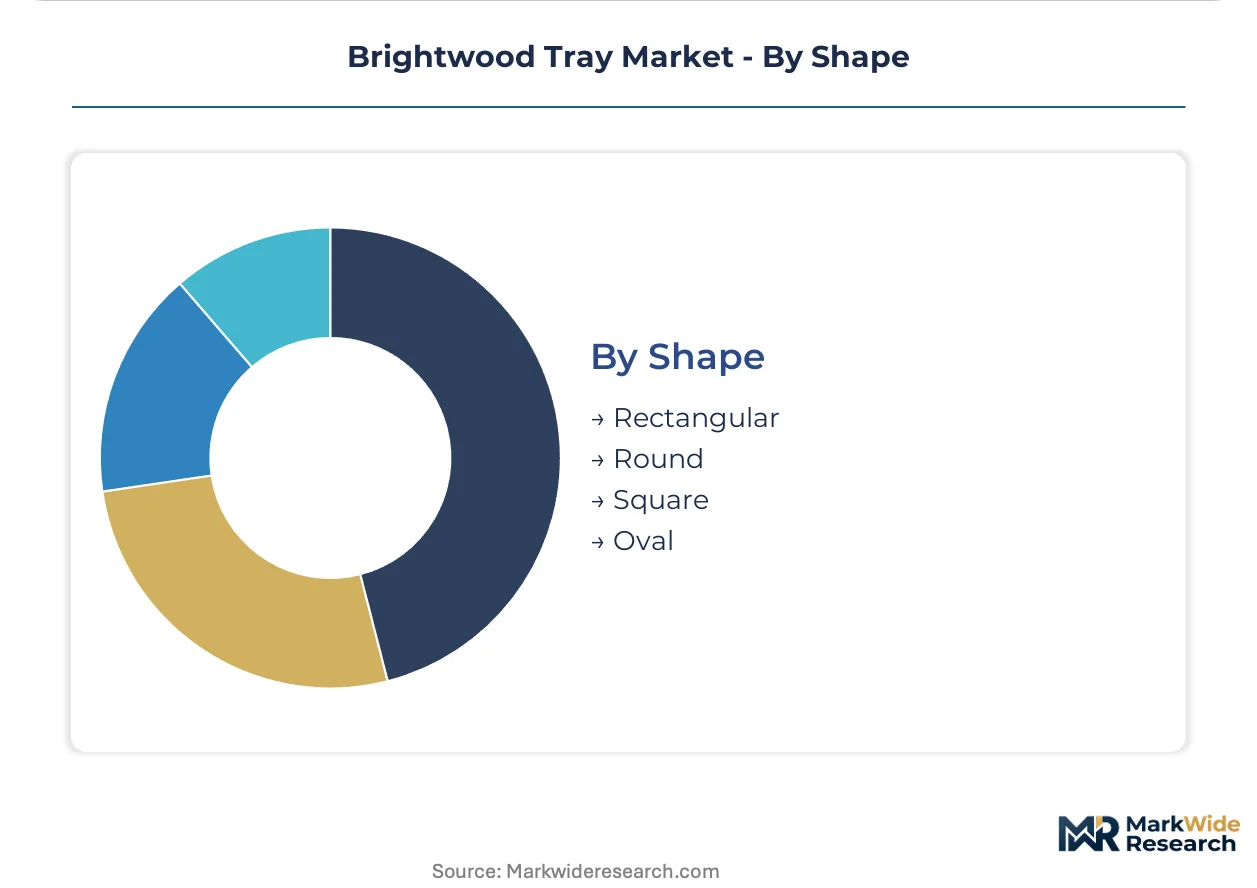
Shape:
Geography of manufacturing legacy influences regional shape preferences, with mold-making talent pools concentrated in former furniture-manufacturing clusters.
- Rectangular:Standardized dimensions optimized for commercial dishwasher racks and airline meal cart compatibility. Long-haul carriers redesigning premium cabin service seek lightweight branded configurations to replace plastic-lined alternatives and support net-zero commitments.
- Round:Traditional presentation formats for hospitality environments emphasizing artisanal craft positioning and tablescape aesthetics.
- Square:Contemporary styling for modern casual dining concepts and architectural interior design schemes.
- Oval:Elongated profiles for banquet service and family-style presentation formats in upscale catering applications.
Rectangular configurations command production volume; Round formats are expanding most quickly in premium positioning strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in institutional foodservice segments contrasts sharply with premium hospitality procurement, where sustainability certification commands substantial margin premiums across major demand centers.
Germany
Premium casual dining chains and corporate catering services drive certified wooden serveware procurement. EU REACH framework restrictions on formaldehyde-releasing preservatives accelerate adhesive reformulation timelines. Bavarian hospitality suppliers lead early adoption of alternative bonding chemistry, propagating compliance standards across European production networks.
United States
West Coast and Northeast metropolitan markets concentrate ESG-driven procurement from event-planning firms and restaurant groups. FDA food-contact substance regulations and California Proposition 65 labeling requirements extend supplier onboarding timelines. New York and California clusters demonstrate the tightest enforcement of chain-of-custody documentation for bamboo and hardwood inputs.
France
Wedding planners and corporate event coordinators specify reusable wooden serveware for brand differentiation. EU Packaging and Packaging Waste Regulation phase-out targets for single-use plastics force procurement certification for commercial dishwasher compatibility. Paris and Lyon hospitality supply chains professionalize sustainability officer roles, concentrating demand among FSC-certified fabricators.
United Kingdom
Boutique restaurant chains seek short-run branded serveware through direct digital procurement platforms. CSRD reporting obligations tighten vendor qualification for corporate catering contracts. London and Southeast England clusters concentrate demand for artisanal finishing and limited-edition collaborations in premium positioning strategies.
Italy
Family-style dining concepts and upscale catering applications favor traditional presentation formats. EU Green Deal circular economy incentives subsidize manufacturing equipment upgrades for SME tray producers. Milan and Emilia-Romagna industrial districts retain mold-making talent pools from legacy furniture-manufacturing heritage.
Brightwood Tray Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers controlling precision finishing capabilities while mid-scale workshops compete on customization velocity. The vendor base stratifies across three tiers: multinational packaging conglomerates with captive pulp supply, specialized decorative finishers serving hospitality brands, and digital-native fabricators targeting short-run restaurant contracts. Consolidation pressure concentrates among automated veneer-press operators acquiring UV-curing capacity, while strategic partnerships proliferate between raw material certifiers and regional distributors.
Within the integrated infrastructure tier, Smurfit Kappa Group plc exemplifies backward control over pulp-to-packaging cost structures. JohnsByrne occupies a position representing specialized high-end decorative finishing archetypes. PakFactory anchors the rapid-turn customization segment for boutique restaurant chains. These three fabricators collectively illustrate the competitive vectors defining procurement segmentation across North American and European markets.
| Leading Market Players |
|---|
| Cartoncraft Incorporated |
| New York Label & Box Works |
| JohnsByrne |
| Packaging Logic, Inc. |
| PakFactory |
| Online Print & Pack Private Limited |
| Quality Box and Package |
| Smurfit Kappa Group plc |
| Multi-Color Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at automated veneer-press operations in Germany and Poland sets price floors for mid-scale European producers, compressing margins for hand-finish workshops that cannot amortize digital cutting equipment across commercial dishwasher-certified output volumes.
Pricing Analysis
After-sales coating refurbishment contracts now drive lifetime value for integrated manufacturers with in-house UV-curing lines. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified bamboo composite trays from Baltic birch veneer products and untreated fiberboard alternatives. Cost compression in economy tiers is intensifying because melamine-resin substitutes retain institutional cafeteria share. QSR procurement teams exhibit highest price sensitivity; premium casual dining chains in California and New York metropolitan markets show least.
Supply Chain Analysis
Inventory lead times for Baltic birch and beech veneers stretch eight to fourteen months when North American market entry requires dual-formulation coating inventories. Raw material sourcing draws from Eastern European forestry operations, Chinese bamboo plantations, and German adhesive chemical suppliers. Single-source vulnerability concentrates in rotary die-cutting mold fabrication, where skilled technicians cluster in legacy Italian furniture-manufacturing districts. Distribution runs through institutional foodservice distributors, direct-to-restaurant digital platforms, and event-planning intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against lower-cost molded melamine-resin serveware that retains institutional cafeteria share where capital budgets override sustainability procurement mandates.
For Market Incumbents: Fortify UV-curing capacity and FSC certification depth to defend margin position against mid-scale workshops acquiring digital cutting equipment. Backward integration into bamboo composite feedstock secures supply continuity as EU REACH restrictions accelerate adhesive reformulation timelines. Channel control through direct-to-restaurant digital platforms captures customization margin from boutique chains.
For New Entrants and Emerging Players: Lead with airline premium cabin service as the most penetrable segment, where long-haul carriers redesign dining experiences and net-zero commitments create specification windows absent entrenched vendor relationships. California and New York metropolitan catering markets offer secondary white-space for certified decorative trays with chain-of-custody documentation. Go-to-market positioning should emphasize rapid-turn customization velocity against incumbent production schedules.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated manufacturers with captive coating refurbishment programs and multi-year hospitality brand contracts. Five-to-ten year viability favors fabricators with in-house UV-curing lines and FSC or PEFC certification infrastructure over equipment-dependent workshops facing technology transition capex. Watch EU Packaging and Packaging Waste Regulation enforcement timelines as inflection indicator for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| UV-Curing Capacity Expansion | Enables compliance with commercial dishwasher specifications while displacing solvent-based finishing houses. |
| Bamboo Composite Feedstock Integration | Secures rapidly renewable supply chains as EU REACH restrictions accelerate material substitution timelines. |
| Direct-to-Restaurant Digital Platform Launch | Bypasses traditional foodservice distribution tiers to capture margin from short-run customization services. |
| FSC Certification Investment | Qualifies fabricators for ESG-driven procurement from California and New York event-planning firms. |
| Airline Premium Cabin Partnership | Positions lightweight branded trays to replace plastic-lined meal carts under carrier net-zero commitments. |
Study Parameters
Desk research of EU regulatory filings, FDA food-contact substance databases, and hospitality procurement contract documentation preceded structured interviews with tray fabrication plant managers, restaurant procurement directors, event-planning sustainability officers, and coating chemistry technical leads. Secondary validation drew from FSC chain-of-custody registries, commercial dishwasher certification records, and trade customs data for laminated wood veneer imports. Bottom-up volume modeling triangulated against top-down spending estimates from premium casual dining chains.
Variance decomposition across product type, material certification tier, end-user channel, and geographic demand cluster shaped analytical framework development over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by per-unit value assumptions. Industry-specific forecast inputs included EU Packaging and Packaging Waste Regulation phase-out timelines and commercial dishwasher cycle durability standards.
Forecasts assume regulatory continuity in EU REACH and US FDA regimes; material policy shifts would require re-modeling. Outputs reflect assumptions about sustainability procurement mandate adoption rates and coating chemistry qualification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Saudi Arabia Kitchen Hoods Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Latin America Kitchen Furniture Market
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Outdoor Kitchen Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
Asia-Pacific Kitchen Furniture Market