
 Skillets and Frying Pans Market | 2026-2036
Skillets and Frying Pans Market Size, Share, and Industry Trends Forecast 2026-2036
Skillets and Frying Pans Market Analytics
Commercial foodservice buyers is bifurcating from traditional household purchasers as the primary volume driver in the Skillets and Frying Pans Market. Tramontina leverages its Brazilian manufacturing scale to dominate Latin American distribution channels for carbon steel and cast iron lines. Lodge anchors North American supply through its Tennessee foundry operations and seasoned cast iron specialization. Merten & Storck differentiates via German-engineered tri-ply construction and premium positioning across European specialty retailers.
Skillets and frying pans are flat-bottomed cooking vessels with sloped or vertical sidewalls, typically manufactured through sand casting, spinning, or deep drawing processes with wall thicknesses ranging from 2.5 mm to 6 mm depending on material and thermal mass requirements. Their primary commercial purpose centers on dry-heat cooking methods including sautéing, searing, and shallow frying across residential and professional food preparation environments. Cast iron product lines retain dominant position in heat retention applications and outdoor cooking segments, while non-stick formulations face structural pressure from fluoropolymer regulatory restrictions despite continued household preference for low-fat cooking convenience. Stainless steel variants command premium margin pools in restaurant and catering channels where durability and dishwasher compatibility justify higher replacement cycles.
The US FDA oversees food contact substance safety for non-stick coatings under 21 CFR regulations, while California's Proposition 65 mandates disclosure requirements for per- and polyfluoroalkyl substances that manufacturers must address through reformulation or labeling compliance. The EU REACH regulation and F-Gas framework constrain certain coating chemistries and manufacturing processes exported into European markets. Stakeholders must monitor evolving state-level chemical restrictions and induction compatibility standards as purchase criteria continue shifting across both household and commercial buyer segments.
Market Dynamics
Commercial foodservice recovery is bifurcating volume flows away from residential channels, while fluoropolymer regulatory pressure under FDA and REACH frameworks forces coating reformulation across manufacturing bases.
Growth Catalysts
- Foodservice Rebound:Restaurant kitchen fleet upgrades concentrate demand in stainless steel and carbon steel categories compatible with high-heat professional environments.
- REACH Compliance Innovation:European ceramic and silicone-based coating alternatives gain technical viability as fluoropolymer restrictions tighten across EU member states.
- Induction Infrastructure:Ferromagnetic base compatibility requirements spread through urban Chinese and South Korean household appliance adoption curves.
Market Restraints
- Raw Material Concentration:Nickel and chromium supply volatility from Indonesian and Philippine mining jurisdictions compress stainless steel margin stability.
- Coating Transition Costs:Per- and polyfluoroalkyl substance phase-out timelines under California Proposition 65 force dual-inventory carrying costs during reformulation periods.
- Cast Iron Weight Logistics:E-commerce fulfillment cost structures disadvantage heavy cast iron products against lighter aluminum and tri-ply alternatives in direct-to-consumer channels.
Strategic Opportunities
- Outdoor Cooking Expansion:Campfire-compatible cast iron and carbon steel designs penetrate North American recreational vehicle and overlanding equipment markets.
- Repair and Resurfacing Services:Premium cookware subscription maintenance models emerge in German and Japanese metropolitan markets extending replacement cycles through professional re-seasoning.
- Induction-Ready Retrofit Bases:Aftermarket magnetic disc attachments open addressable market for legacy aluminum and copper cookware incompatible with glass-ceramic cooktops.
Industry Challenges
- Foundry Labor Availability:Seasoned cast iron production requires specialized mold-making and finishing skills concentrated in aging Tennessee and Pennsylvania workforce pools.
- Coating Certification Timelines:FDA food contact substance notification reviews extend new non-stick formulation launch windows by twelve to eighteen months.
- Multi-Channel Inventory Complexity:Divergent induction compatibility, handle attachment, and packaging specifications fragment stock-keeping units across retail, commercial, and direct-to-consumer fulfillment paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skillets and Frying Pans Market |
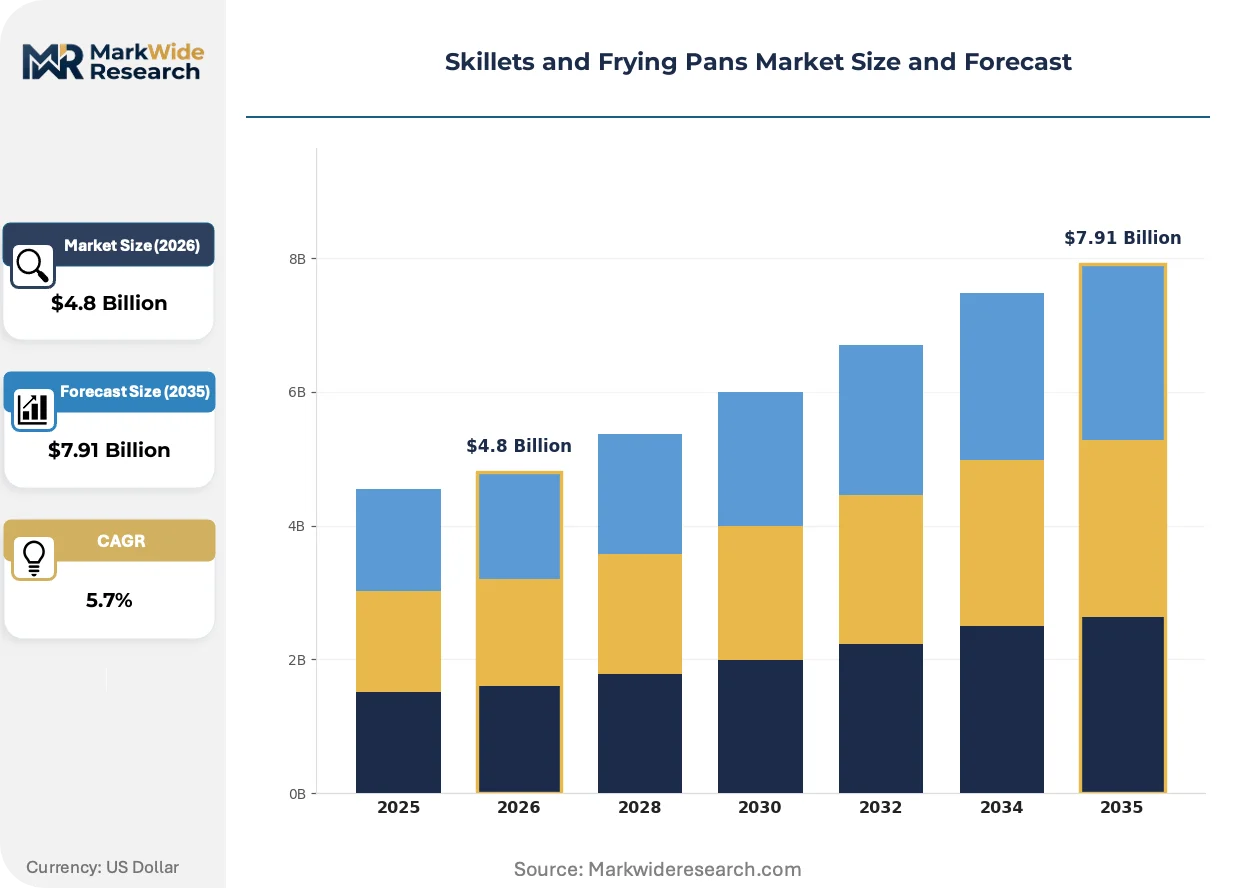
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Iron, Non-Stick, Stainless Steel, Copper End User: Households, Restaurants, Catering Services, Food Trucks Feature: Induction Compatible, Oven Safe, Dishwasher Safe, Scratch Resistant Material: Aluminum, Carbon Steel, Enamel Coated, Others |
| Companies Covered | Tramontina, Merten & Storck, Lodge, Caraway, Sardel, Matfer Bourgeat, Calphalon, Fredericksburg Cast Iron Co., OXO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skillets and Frying Pans Market Evolving Landscape
Material science advances and regulatory chemistry constraints are actively restructuring competitive advantage away from coating performance toward thermal engineering and substrate durability.
Ceramic-reinforced sol-gel coatings are decomposing the traditional fluoropolymer-non-stick duopoly by delivering comparable release properties without perfluorinated compound exposure liabilities. Professional kitchen operators in France and Japan pilot these formulations for high-cycle sauté applications. The technology is decomposing incumbent coating suppliers' intellectual property moats as open-source ceramic matrix recipes proliferate through Asian manufacturing technology transfer.
EU F-Gas Regulation phase-down schedules now constrain hydrofluorocarbon propellant use in spray-applied coating processes exported into European Economic Area markets. German and Italian cookware manufacturers accelerate water-based and powder coating line conversions to maintain CE marking compliance. Cast iron and bare carbon steel producers capture residual demand from buyers preemptively abandoning coated alternatives ahead of 2027 restriction escalations.
Direct-to-consumer subscription models now displace traditional retail assortment purchasing for premium cookware categories in US and UK metropolitan markets. Buyers commit to multi-year replacement cycles with bundled maintenance services rather than single-transaction retail acquisition. This pattern concentrates most visibly among millennial household formations in Seattle, Austin, and London seeking curated kitchen equipment collections over episodic discount-driven purchases.
Skillets and Frying Pans Market Segmentation
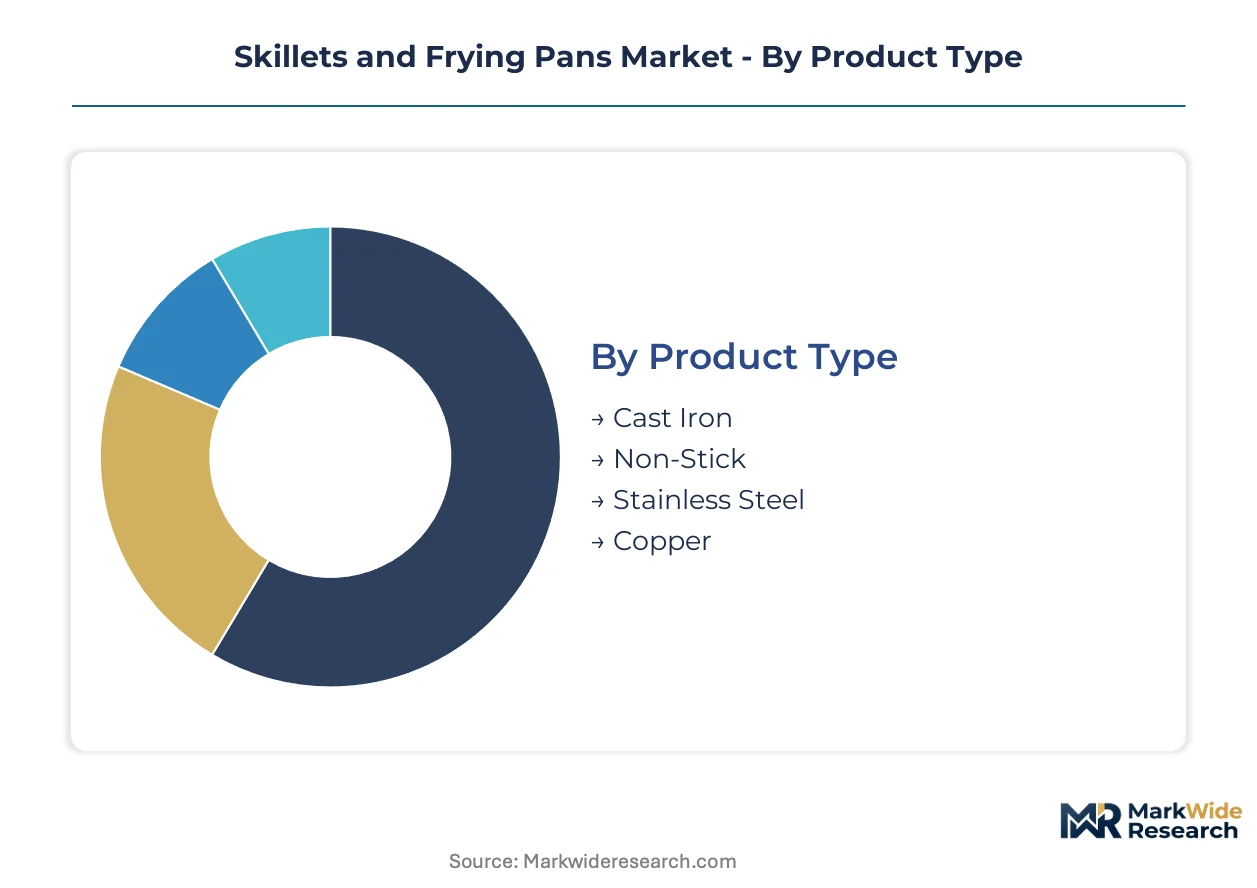
Product architecture and buyer requirements fragment the Skillets and Frying Pans Market into distinct competitive arenas. Regulatory pressure on coatings and appliance infrastructure shifts reshape which segments capture margin versus volume.
Product Type:
FDA food contact substance rules and EU REACH chemical restrictions differentiate coating-dependent lines from bare-metal alternatives.
- Cast Iron:Sand-cast ferrous construction delivers superior thermal mass for searing and outdoor cooking applications. Lodge Manufacturing's Tennessee foundry anchors North American supply. Lodge's seasoned surface technology and campfire compatibility drive demand concentration among recreational vehicle owners and barbecue enthusiasts across Texas, Colorado, and the Pacific Northwest.
- Non-Stick:Fluoropolymer or ceramic-reinforced sol-gel coatings enable low-fat cooking with minimal food adhesion. California Proposition 65 disclosure mandates and EPA perfluorinated compound scrutiny force reformulation timelines. Household buyers in coastal US metropolitan markets preemptively shift toward ceramic alternatives ahead of regulatory escalations.
- Stainless Steel:Chromium-nickel austenitic alloys provide dishwasher compatibility and professional kitchen durability. Tramontina's Brazilian production scales serve Latin American restaurant channels.
- Copper:Unparalleled thermal conductivity supports precision temperature control for sauce-making and confectionery. French and Italian specialty retailers concentrate remaining demand.
Established volume favors cast iron; emerging adoption favors ceramic-reinforced non-stick formulations.
End User:
Procurement authority and replacement cycle economics separate institutional buyers from household decision-makers.
- Restaurants:High-heat compatibility and rapid thermal recovery dominate specification requirements. Stainless steel and carbon steel lines command premium positioning. Merten & Storck's German-engineered tri-ply construction penetrates Michelin-starred kitchens in France, Germany, and Japan where durability justifies replacement cycles exceeding five years.
- Households:Convenience, aesthetics, and price sensitivity drive purchase behavior across urban Chinese and South Korean markets. Induction infrastructure expansion reshapes compatibility requirements.
- Catering Services:Volume procurement and standardization needs favor mid-tier stainless steel assortments with uniform replacement schedules.
- Food Trucks:Space constraints and mobility requirements concentrate demand in lightweight aluminum and compact-dimension carbon steel formats.
Margin concentration sits with restaurant channels; steepest expansion trajectory runs through urban household formations.
Feature:
Appliance technology diffusion and labor cost structures determine which functional attributes command price premiums.
- Induction Compatible:Ferromagnetic base materials or bonded steel plates enable glass-ceramic cooktop operation. China's urban appliance upgrade cycles and South Korea's near-universal induction adoption concentrate demand. MEE dual carbon goals accelerate magnetic-base requirements across Chinese manufacturing standards.
- Oven Safe:Metal or high-temperature silicone handle attachments extend functional temperature ranges. Professional kitchen operators in France and Japan prioritize seamless stovetop-to-oven workflows.
- Dishwasher Safe:Unsealed cast iron exclusion and coating durability concerns segment this attribute toward stainless steel and anodized aluminum lines.
- Scratch Resistant:Hard-anodized aluminum and reinforced ceramic coatings address utensil abrasion in high-frequency household environments.
Technical premium attaches to induction compatibility; convenience premium attaches to dishwasher-safe construction.
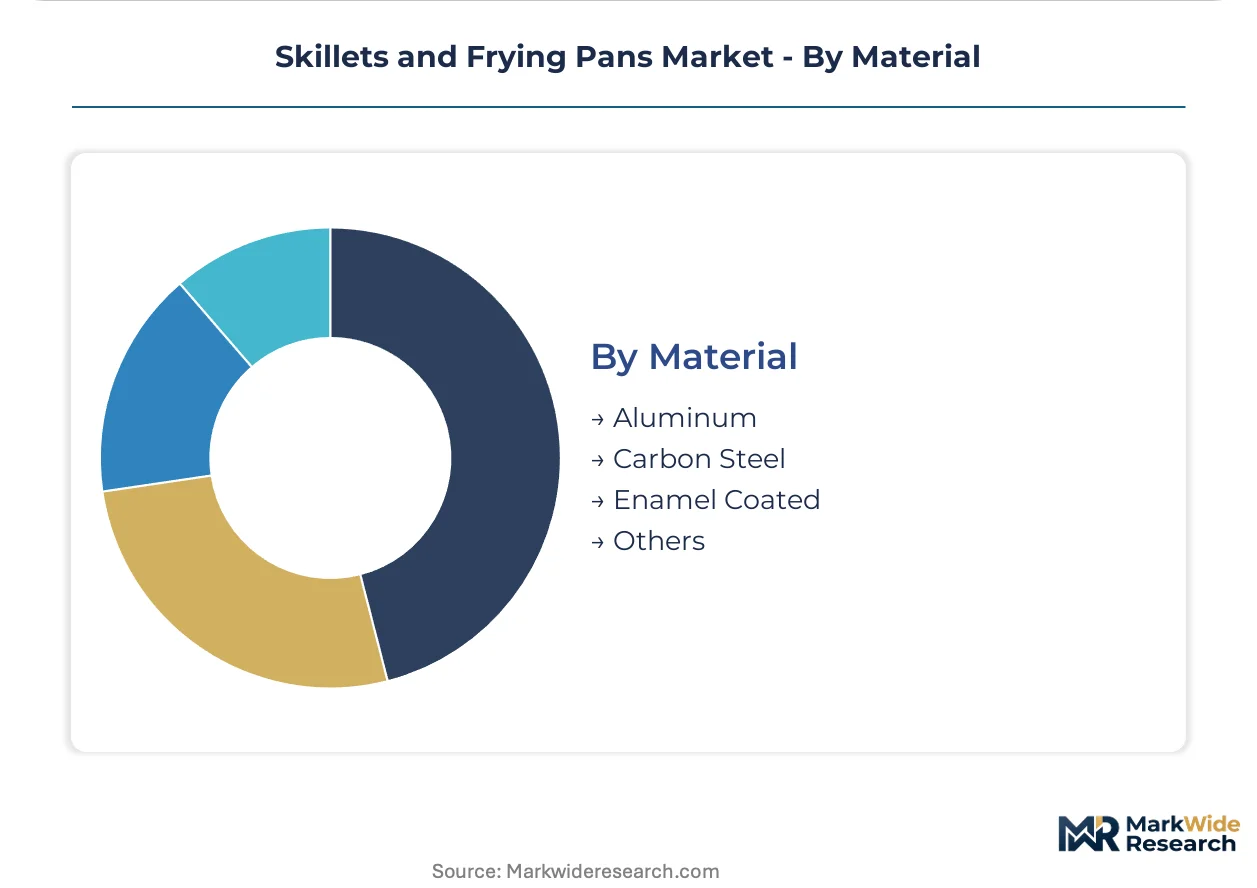
Material:
Supply chain geography and processing energy intensity differentiate substrate economics.
- Aluminum:Lightweight, thermally responsive, and cost-efficient for volume production. Indonesian and Philippine bauxite supply volatility compress margin stability. Spin-formed and deep-drawn manufacturing dominates Southeast Asian production bases serving North American retail channels.
- Carbon Steel:Rapid heat response and seasoning-compatible surfaces bridge professional and outdoor cooking applications. Tramontina's Latin American foundry network scales regional supply.
- Enamel Coated:Vitreous enamel fusion eliminates seasoning requirements while preserving cast iron thermal mass. European specialty retailers concentrate demand for color-finish aesthetics.
- Others:Titanium-reinforced composites and hybrid multi-ply laminates serve niche premium positioning.
Volume manufacturing gravitates toward aluminum; performance differentiation favors carbon steel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Ningbo-Zhoushan's container throughput underwrites China's dominance in cookware export logistics, with dedicated reefer and breakbulk terminals handling ferrous raw materials inbound and finished aluminum and carbon steel vessels outbound to North American and European distribution networks.
United States
Restaurant kitchen fleet upgrades and recreational vehicle ownership expansion drive stainless steel and cast iron procurement. FDA food contact substance rules under 21 CFR constrain non-stick coating formulations. Lodge Manufacturing's Tennessee foundry operations concentrate seasoned cast iron production for barbecue enthusiasts across Texas and the Pacific Northwest.
China
Urban household appliance upgrade cycles and MEE dual carbon goals accelerate induction-compatible cookware demand. GB standards and SAMR market supervision regulate ferromagnetic base material specifications. Yangtze River Delta manufacturing clusters in Zhejiang and Jiangsu provinces scale deep-drawn aluminum and tri-ply stainless steel production for domestic and export markets.
Germany
Michelin-starred kitchen procurement and premium retail channel concentration sustain tri-ply construction demand. ECHA REACH chemical restrictions and EU F-Gas Regulation phase-down schedules force coating line conversions. Solingen and Remscheid industrial heritage centers anchor specialized carbon steel and enameled cast iron fabrication for European specialty retailers.
Brazil
Latin American foodservice recovery and churrasco culture sustain carbon steel skillet demand. ANVISA sanitary surveillance regulates food contact surface compliance for imported and domestic products. Tramontina's Rio Grande do Sul manufacturing base leverages regional foundry networks to serve restaurant and household channels across Mercosur trade zones.
Japan
Precision temperature control requirements in traditional cuisine and compact urban kitchen formats favor multi-ply and copper-core constructions. METI energy efficiency standards promote induction-compatible base designs. Osaka and Nagoya industrial districts concentrate specialized spinning and metalworking capabilities for premium cookware export and domestic specialty retail.
Skillets and Frying Pans Market Competitive Landscape
Concentration sits with heritage foundry operators and regional manufacturing specialists rather than consolidated multinational portfolios. The vendor base spans Brazilian carbon steel scale players, German precision engineering workshops, and North American cast iron heritage brands. Two strategic archetypes dominate: vertically integrated foundry-to-retail operators controlling raw material through distribution, and design-forward direct-to-consumer brands capturing premium household segments through subscription and curated assortment models. Competitive moves center on coating reformulation R&D partnerships addressing fluoropolymer regulatory phase-outs, and foundry capacity expansion into Southeast Asian export platforms.
Among heritage foundry operators, Lodge, Tramontina, and Merten & Storck exemplify distinct geographic and material specializations. Lodge occupies a position within North American seasoned cast iron heritage, Tramontina represents Latin American carbon steel scale manufacturing, and Merten & Storck sits within German-engineered tri-ply premium positioning. These three anchors demonstrate how regional manufacturing traditions translate into defensible market positions against Asian aluminum volume competitors and direct-to-consumer ceramic-coated challengers.
| Leading Market Players |
|---|
| Tramontina |
| Merten & Storck |
| Lodge |
| Caraway |
| Sardel |
| Matfer Bourgeat |
| Calphalon |
| Fredericksburg Cast Iron Co. |
| OXO |
| Others |
Value Network & Pricing Analysis
Ceramic-reinforced sol-gel coating substitution for fluoropolymer formulations simultaneously shifts manufacturing geography toward Southeast Asian chemical processing hubs and compresses premium pricing power as open-source recipes proliferate. This input transition rewards foundry operators with captive seasoning capabilities while eroding margin pools for coating-dependent product lines facing dual-inventory carrying costs during reformulation periods.
Pricing Analysis
Volume-discount tiering structures separate Michelin-starred kitchen procurement from mass retail channels, with restaurant buyers capturing scale advantages through multi-year fleet replacement contracts. Price differentiation hinges on induction compatibility certification and NSF food equipment sanitation standards, with premium tiers commanding substantial markups for ferromagnetic base validation. Pricing pressure stems from nickel and chromium supply volatility originating in Indonesian mining jurisdictions. Household buyers in urban Chinese markets exhibit highest price sensitivity, while professional foodservice operators prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Strait of Malacca transit chokepoints concentrate bauxite and nickel ore flows toward Yangtze River Delta manufacturing clusters, exposing aluminum and stainless steel production to maritime logistics disruption. Raw material dependencies center on Indonesian nickel laterite, Philippine chromite, and Australian bauxite extraction. Single-source vulnerability characterizes seasoned cast iron supply, with Tennessee and Pennsylvania foundry capacity concentrated in aging workforce pools. Distribution runs through Port of Ningbo-Zhoushan breakbulk terminals serving North American big-box retail and European specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
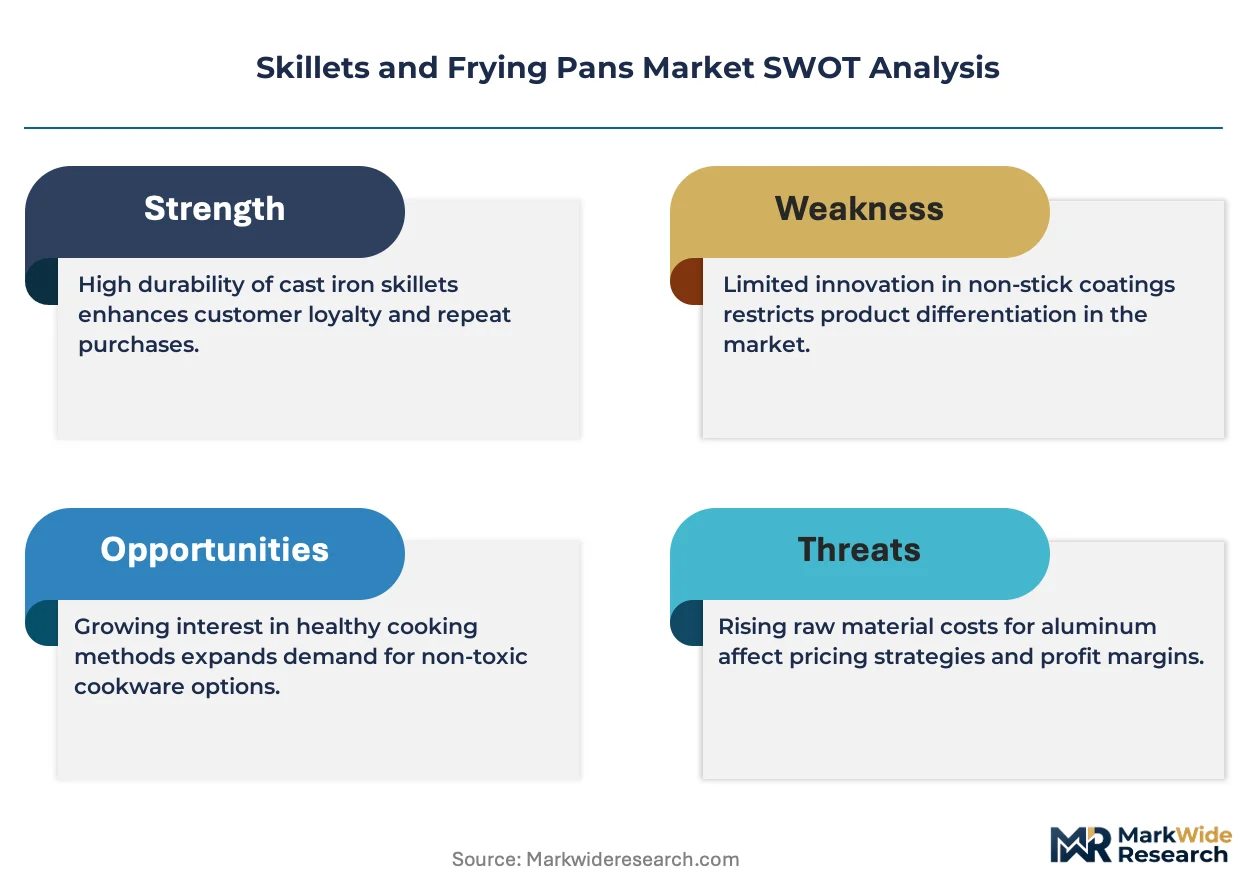
This market constitutes a defensive-moat opportunity anchored in regulatory entrenchment: FDA food contact substance notification timelines and foundry labor scarcity create twelve-to-eighteen-month barriers against coating reformulation competitors.
For Market Incumbents: Consolidate through backward integration into ferromagnetic base material supply and captive seasoning chemistry production. Lodge Manufacturing's Tennessee foundry network exemplifies geographic concentration that emerging ceramic-coated challengers cannot replicate without ECHA REACH compliance investment. Channel control through direct-to-consumer subscription models defends margin pools against aluminum volume competitors. For New Entrants and Emerging Players: Aftermarket magnetic disc retrofit services for legacy aluminum cookware represent an underserved white-space where incumbents under-serve induction-incompatible household formations. German and Japanese metropolitan markets offer penetrable entry points for repair and resurfacing subscription models. Go-to-market execution should prioritize professional re-seasoning certification partnerships with established foundry operators. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors vertically integrated heritage foundry operators with coating reformulation R&D partnerships. Long-term viability across a five-to-ten year horizon rests on induction infrastructure penetration curves and fluoropolymer phase-out completion. The signal to watch is FDA notification approval velocity for ceramic-reinforced sol-gel formulations as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Reformulation R&D Partnership | FDA notification timelines favor early movers in ceramic-sol-gel validation against REACH restrictions. |
| Foundry Capacity Expansion | Tennessee and Pennsylvania labor pools constrain seasoned cast iron supply scalability for outdoor cooking demand. |
| Direct-to-Consumer Subscription Launch | Seattle and Austin millennial formations shift procurement from episodic retail toward curated replacement cycles. |
| Induction Compatibility Certification Investment | China GB standards and South Korean appliance adoption validate ferromagnetic base requirements as purchase criteria. |
| Repair and Resurfacing Service Development | German metropolitan markets demonstrate professional re-seasoning extends replacement cycles and captures recurring revenue. |
Research Methodology
A standing panel of foundry operations directors, restaurant procurement managers, retail category buyers, and ceramic coating R&D leads provided ongoing calibration against secondary validation from customs records, SEC 10-K filings, and ECHA REACH substance restriction updates. Primary interviews with foodservice equipment distributors and household appliance manufacturers combined with bottom-up and top-down triangulation across aluminum trade flow data and stainless steel production statistics.
Consistency checks validated volume and value outputs against Yangtze River Delta export statistics and North American retail audit data across the projection horizon. Segmentation modeling incorporated product architecture, end-user procurement authority, induction compatibility requirements, and regional appliance infrastructure penetration. CAGRs derived from fitted growth curves applied to foundry capacity utilization and coating formulation adoption rates, with nickel price volatility and FDA notification timelines as industry-specific sensitivity inputs.
Forecasts assume regulatory continuity in FDA 21 CFR frameworks and ECHA REACH phase-down schedules; material policy shifts would require re-modeling of coating transition timelines and import restriction scenarios. Practitioners should keep alternative scenarios live as Indonesian mining export regulations and California Proposition 65 enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
Oman Kitchen Hood Market
Kitchen and Dining
Latin America Kitchen Furniture Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
North America Tabletop Kitchen Products Market
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
United States Modular Kitchen Market