
 Endpoint Security Market | 2026-2036
Endpoint Security Market Size, Share, and Industry Trends Forecast 2026-2036
Endpoint Security Market Analysis
Cybersecurity talent scarcity is unwinding traditional on-premises deployment timelines as enterprises struggle to staff Security Operations Centers. CrowdStrike leverages its cloud-native architecture to capture organizations abandoning legacy agent-heavy stacks. Palo Alto Networks anchors enterprise trust through integrated platform consolidation spanning network and endpoint layers. Fortinet competes on price-performance by bundling endpoint modules within its broader security fabric licensing.
Endpoint security encompasses software agents, behavioral analytics engines, and policy enforcement mechanisms deployed on laptops, servers, mobile devices, and IoT endpoints to prevent, detect, and respond to malicious activity. Modern platforms integrate machine-learning classifiers that process telemetry streams exceeding one million events per endpoint daily, enabling real-time threat containment without human intervention. The Endpoint Detection and Response segment leads solution-type revenue as organizations prioritize proactive threat hunting over signature-based antivirus. Cloud-based deployment is expanding fastest among mid-market buyers seeking reduced infrastructure overhead, while on-premises stacks retain dominance in classified government and air-gapped industrial environments where data sovereignty requirements prevail.
The Securities and Exchange Commission mandates incident disclosure within four business days, compelling publicly traded firms to invest in detection capabilities that accelerate breach validation. The European Union Agency for Cybersecurity enforces certification schemes under the Cybersecurity Act that gate market access for endpoint vendors serving critical sectors. Stakeholders must weigh platform consolidation against best-of-breed specialization as vendor sprawl costs increasingly exceed the risk reduction from point-solution diversity.
Market Dynamics
Zero-trust architecture mandates from the US federal government are compressing enterprise refresh cycles and forcing platform consolidation decisions across endpoint security procurement teams.
Growth Catalysts
- EU AI Act compliance deadlines:European critical infrastructure operators must deploy automated threat detection by 2025, accelerating replacement of signature-based tools with behavioral analytics engines.
- Financial services ransomware exposure:Banking and insurance sectors face quadrupled extortion demands, expanding budgets for endpoint detection and response platforms with real-time containment capabilities.
- Extended detection and response convergence:XDR platforms unify telemetry across email, identity, and cloud workloads, reducing mean-time-to-response for resource-constrained security operations centers.
Market Restraints
- Agent sprawl and performance degradation:Multiple endpoint agents from different vendors consume CPU and memory resources, triggering user resistance and IT helpdesk escalation volumes.
- Cloud sovereignty requirements:German and French classified environments mandate data residency within national borders, blocking pure SaaS deployment models for sensitive government endpoints.
- Managed detection and response substitution:Mid-market buyers increasingly outsource threat hunting to MDR providers rather than building in-house EDR expertise, capping direct license growth.
Strategic Opportunities
- Operational technology convergence:Manufacturing and energy sectors seek unified agent platforms covering both IT laptops and industrial control system endpoints, collapsing separate procurement silos.
- India's Digital Personal Data Protection Act:Data breach notification requirements create compliance-driven demand for endpoint monitoring among Indian IT services exporters and domestic enterprises.
- Autonomous response automation:Machine-learning models that isolate compromised endpoints without human approval address talent scarcity in Japan's aging cybersecurity workforce.
Industry Challenges
- Security operations center staffing gaps:Alert fatigue and burnout drive analyst turnover above thirty percent annually, degrading the value of detection tools that generate high false-positive volumes.
- Legacy Windows Server migration friction:Industrial environments running unsupported operating systems cannot host modern endpoint agents, creating persistent visibility gaps in critical infrastructure networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endpoint Security Market |
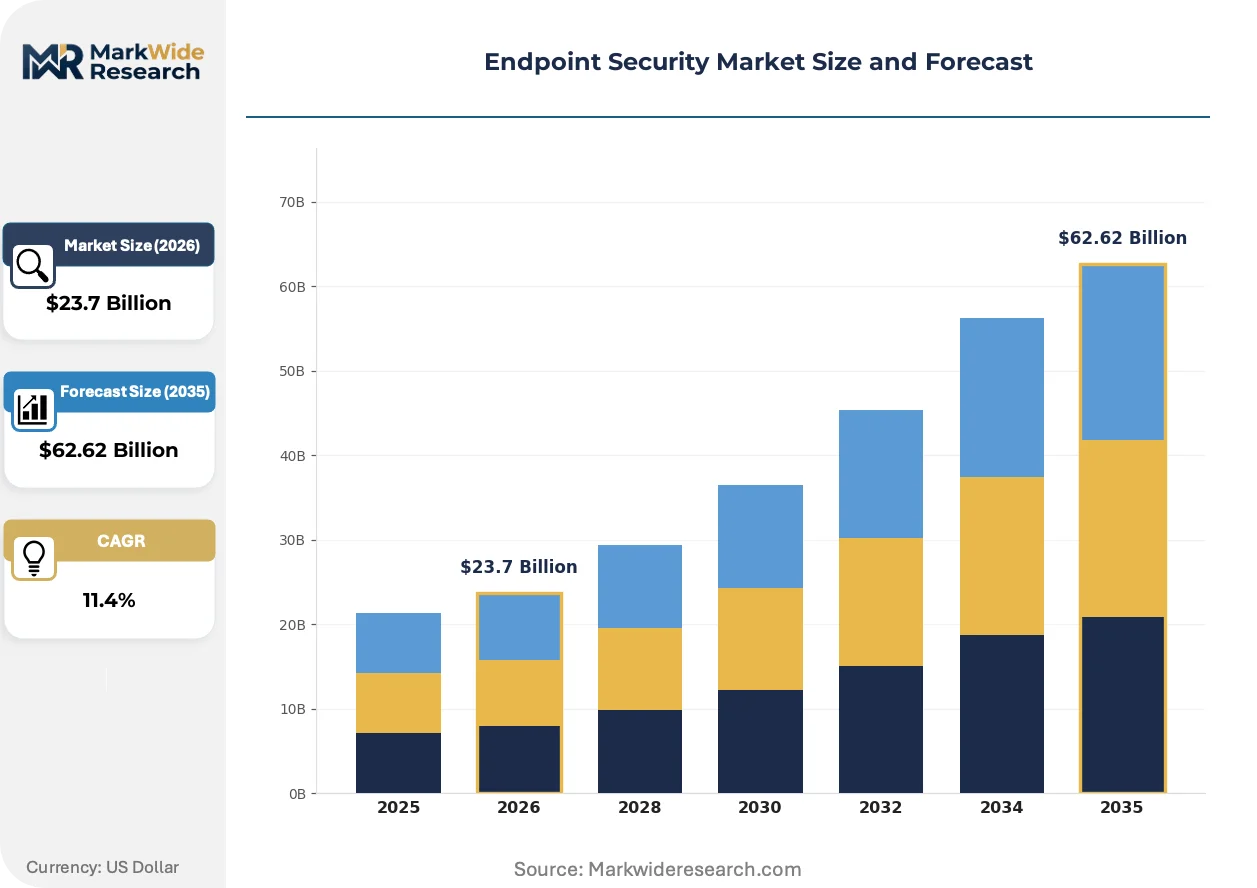
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
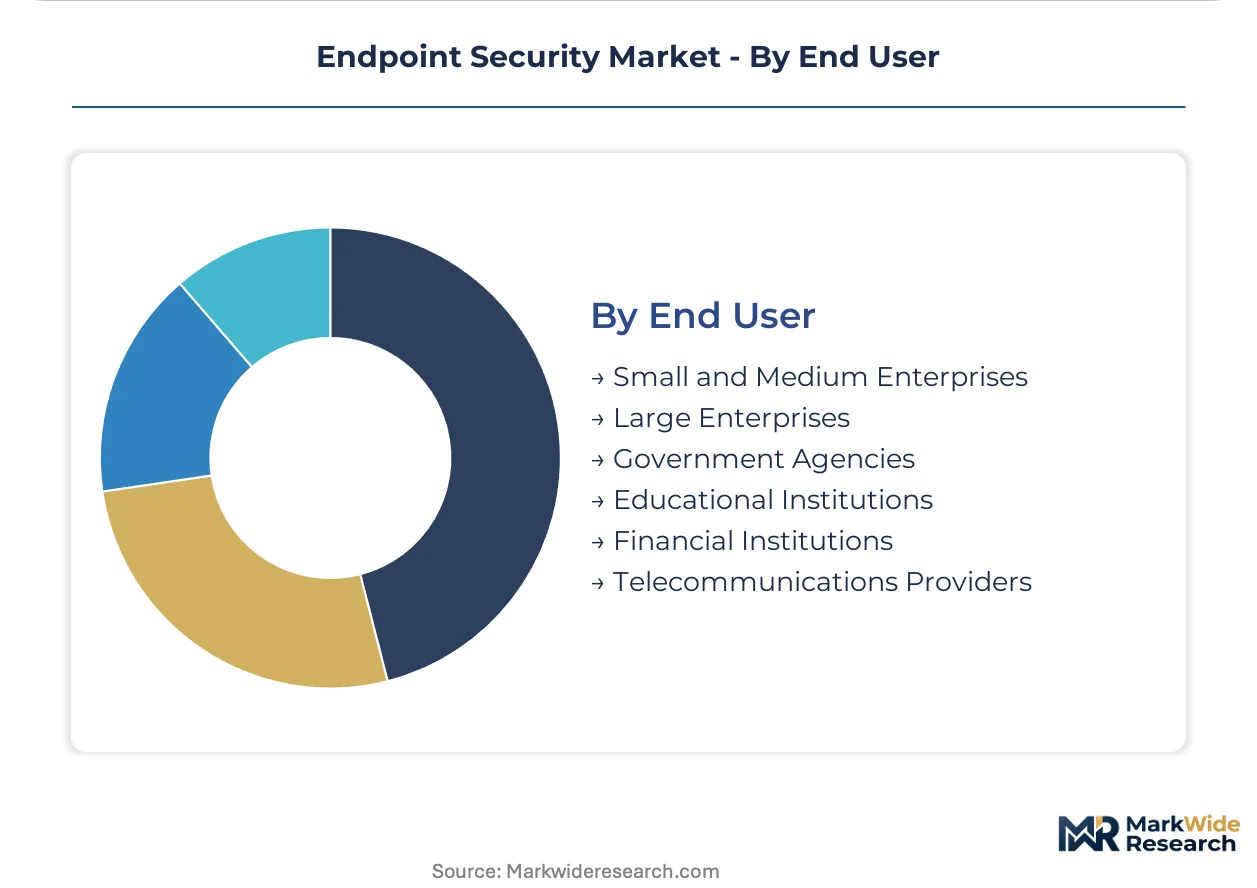
| Segmentation | Solution Type: Antivirus, Endpoint Detection and Response, Firewall, Data Loss Prevention, Encryption, Intrusion Prevention Deployment Mode: On-Premises, Cloud-Based, Hybrid, Hosted, Managed Security Service Application: Threat Hunting, Malware Protection, Access Control, Remote Monitoring, Compliance Management, Incident Response End User: Small and Medium Enterprises, Large Enterprises, Government Agencies, Educational Institutions, Financial Institutions, Telecommunications Providers |
| Companies Covered | Broadcom Symantec, Fortinet, CrowdStrike, Sophos, Trellix, SentinelOne, Palo Alto Networks, Trend Micro, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endpoint Security Market Emerging Trajectories
Endpoint security architecture is bifurcating between lightweight cloud-native agents and heavy on-premises stacks, with buyer choice increasingly determined by data sovereignty requirements rather than feature parity.
Extended detection and response platforms are bifurcating the competitive landscape. XDR correlates telemetry across identity, email, and cloud workloads to reduce alert noise. Large enterprises with mature security operations centers adopt these platforms fastest. The technology is bifurcating vendor strategies between integrated-suite players and best-of-breed specialists.
The EU NIS2 Directive expands cybersecurity obligations to postal services, waste management, and food supply chains previously outside critical infrastructure scope. Member states must transpose the directive into national law by October 2024. Manufacturing and logistics sectors in Germany and France face the steepest compliance ramps as they build first-time security programs.
Consumption-based licensing models are displacing perpetual endpoint agent purchases. Mid-market buyers prefer monthly billing tied to active endpoint counts rather than upfront enterprise agreements. Channel partners in the United Kingdom and Netherlands report accelerated migration toward subscription economics, compressing implementation timelines and reducing procurement committee involvement.
Endpoint Security Market Segmentation
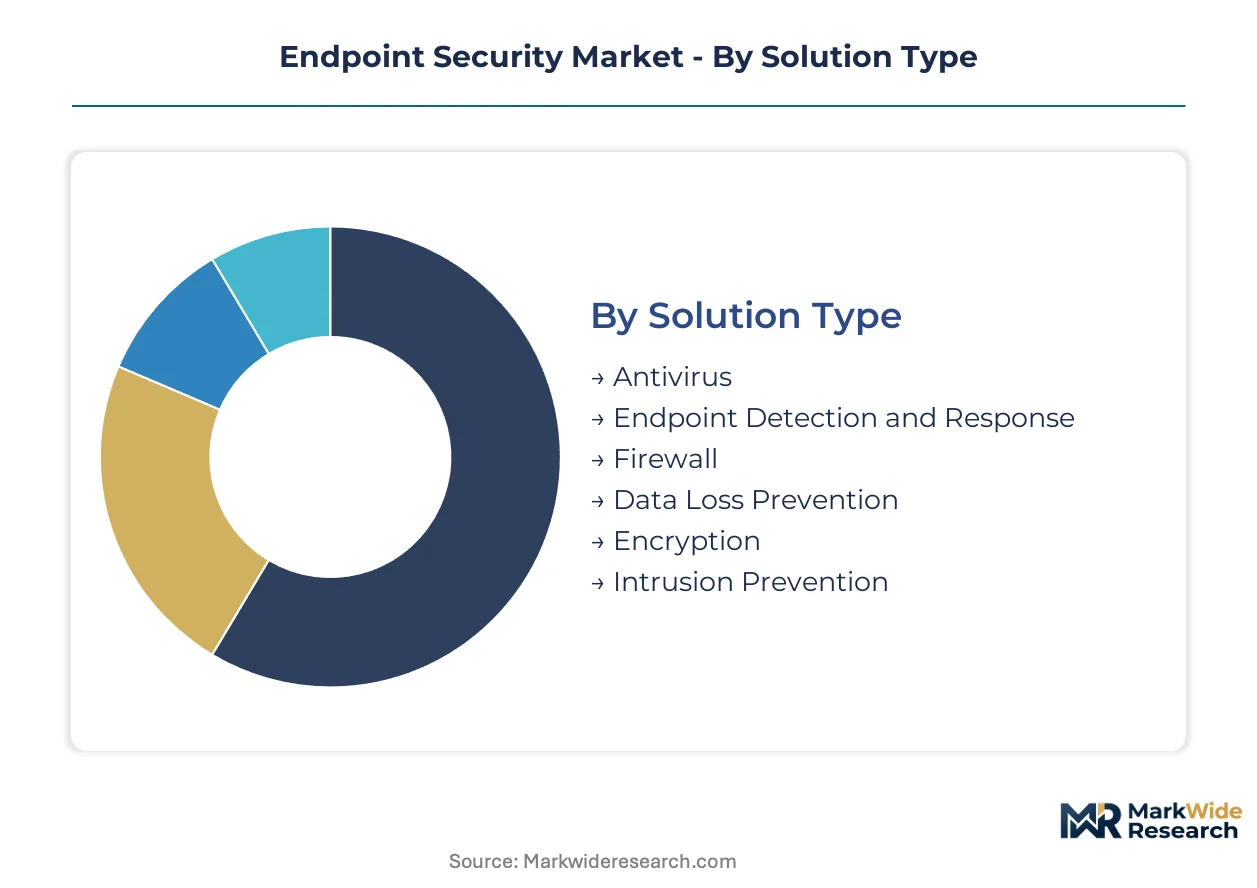
Endpoint security procurement patterns diverge sharply across organizational scale and operational constraints. Buyers select solution architectures based on data sovereignty mandates, security operations maturity, and legacy infrastructure footprints rather than feature checklists alone.
Solution Type:
Channel mix varies by solution complexity—behavioral analytics platforms flow through specialized security VARs, while signature-based tools distribute through broad IT resellers.
- Antivirus:Signature-based engines detect known malware patterns through periodic definition updates. Demand concentrates among cost-constrained educational institutions and legacy-dependent industrial operators seeking baseline protection without behavioral analytics overhead.
- Endpoint Detection and Response:Telemetry-intensive platforms capture process execution, network connections, and file system events for threat hunting. Financial institutions in Frankfurt and Singapore prioritize EDR for SEC disclosure compliance and MAS technology risk management requirements.
- Firewall:Host-based packet filtering controls inbound and outbound network traffic at the endpoint level. Government agencies with air-gapped networks favor integrated firewall modules over standalone appliances.
- Data Loss Prevention:Content inspection engines classify and block sensitive data exfiltration. Healthcare providers deploy DLP agents to satisfy HIPAA breach notification mandates.
- Encryption:Full-disk and file-level cryptographic protection secures data at rest. Legal and professional services firms in London and New York adopt encryption for client confidentiality compliance.
- Intrusion Prevention:Behavioral heuristics block exploit attempts and memory-resident attacks. Energy sector operators integrate IPS with industrial control system monitoring.
By volume, Antivirus leads legacy refresh cycles. By growth pace, Endpoint Detection and Response is expanding most quickly among regulated enterprises.
Deployment Mode:
Cost tier segmentation separates premium fully-managed offerings from self-operated infrastructure investments.
- On-Premises:Dedicated hardware and software stacks within customer-controlled data centers. German and French classified environments mandate on-premises deployment for data residency under national cybersecurity certification schemes.
- Cloud-Based:SaaS-delivered agents with centralized policy management and threat intelligence feeds. Mid-market buyers in the United Kingdom and Netherlands prefer cloud deployment for reduced capital expenditure and faster implementation.
- Hybrid:Mixed architecture combining cloud management planes with local enforcement nodes. Large enterprises with multi-jurisdiction operations adopt hybrid models to satisfy varying sovereignty requirements.
- Hosted:Single-tenant infrastructure operated by third-party providers in designated facilities. Japanese financial institutions select hosted deployment for FISC compliance with domestic data localization.
- Managed Security Service:Outsourced endpoint monitoring and response delivered by specialized providers. Australian and Canadian mid-market organizations substitute MSSP engagement for in-house security operations center construction.
By commercial footprint, Cloud-Based deployment captures the broadest buyer base. By expansion trajectory, Managed Security Service is climbing the fastest as talent scarcity drives outsourcing preference.
Application:
Volume concentration tracks security operations maturity—advanced functions cluster in financial services and government, while foundational protection dominates education and small business.
- Threat Hunting:Proactive adversary detection through hypothesis-driven telemetry analysis. Mature security operations centers at US federal agencies and major banks staff dedicated threat hunting teams.
- Malware Protection:Prevention-focused blocking of malicious executables and scripts. Universal deployment across all end-user segments with highest agent density in uncontrolled endpoint environments.
- Access Control:Identity verification and privilege enforcement at device login. Healthcare systems implement access control for FDA-regulated medical device networks.
- Remote Monitoring:Continuous visibility into off-network endpoint status and compliance posture. Post-pandemic distributed workforces in technology and professional services drive remote monitoring adoption.
- Compliance Management:Automated evidence collection and control validation for audit readiness. EU NIS2 Directive implementation accelerates compliance management procurement among newly regulated sectors.
- Incident Response:Orchestrated containment and remediation workflows for confirmed breaches. Cyber insurance carriers mandate incident response capabilities for policy renewal.
By deployment scale, Malware Protection maintains the largest installed base. By strategic priority, Threat Hunting is gaining share fastest among enterprises with advanced security operations.
End User:
Customer type determines procurement authority structure—centralized IT procurement dominates large enterprises, while departmental buyers influence educational and small business decisions.
- Small and Medium Enterprises:Resource-constrained organizations prioritizing turnkey solutions with minimal configuration. Indian IT services exporters and domestic enterprises invest in endpoint security following Digital Personal Data Protection Act notification requirements.
- Large Enterprises:Complex multi-site organizations with dedicated cybersecurity teams. Platform consolidation initiatives at Fortune 500 companies reduce vendor sprawl through integrated suite procurement.
- Government Agencies:Public sector entities with classified and unclassified network segments. US federal zero-trust mandates compress refresh cycles across civilian and defense agencies.
- Educational Institutions:Universities and K-12 districts with heterogeneous device populations and limited security staffing. Ransomware targeting student records accelerates endpoint protection investment.
- Financial Institutions:Banks, insurers, and payment processors facing quadrupled extortion demands. Real-time containment capabilities differentiate procurement evaluations for trading floor and branch networks.
- Telecommunications Providers:Network operators with subscriber-facing infrastructure and internal corporate systems. Critical infrastructure protection rules apply to core network equipment alongside standard endpoint coverage.
By license volume, Large Enterprises dominate direct procurement. By growth momentum, Government Agencies are expanding fastest under regulatory compliance deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SEC mandates four-day incident disclosure for publicly traded firms, compressing procurement timelines across the United States as enterprises race to deploy detection capabilities that accelerate breach validation.
United States
Federal zero-trust architecture mandates drive platform consolidation across civilian and defense agencies. The Cybersecurity and Infrastructure Security Agency enforces critical infrastructure protection rules that accelerate enterprise refresh cycles. Financial institutions in New York and Chicago prioritize real-time containment capabilities for trading floor networks.
Germany
Industrial manufacturers seek unified agent platforms covering both IT laptops and industrial control system endpoints. The national cybersecurity certification scheme under EU NIS2 mandates data residency for classified environments, blocking pure SaaS deployment models. Automotive clusters in Bavaria and Baden-Württemberg collapse separate procurement silos for operational technology convergence.
United Kingdom
Mid-market buyers prefer cloud-based deployment for reduced capital expenditure and faster implementation. Channel partners report accelerated migration toward subscription economics, compressing procurement committee involvement. London-based financial services firms face quadrupled extortion demands, expanding budgets for endpoint detection and response platforms.
Japan
Machine-learning models that isolate compromised endpoints without human approval address talent scarcity in the aging cybersecurity workforce. The Financial Services Agency's FISC compliance requirements drive domestic data localization preferences among financial institutions. Tokyo and Osaka anchors host concentrated demand for autonomous response automation.
India
IT services exporters and domestic enterprises invest in endpoint monitoring following Digital Personal Data Protection Act breach notification requirements. Mid-market organizations substitute managed security service provider engagement for in-house security operations center construction. Bengaluru and Hyderabad technology corridors generate compliance-driven procurement volume.
Endpoint Security Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where integrated-suite vendors compete against best-of-breed specialists. Cloud-native architectures displace legacy agent-heavy stacks as enterprises abandon on-premises deployment timelines. Three archetypes dominate: platform consolidators bundling network and endpoint layers, cloud-native specialists capturing mid-market migration, and price-performance competitors licensing endpoint modules within broader security fabrics. Strategic moves center on portfolio diversification through extended detection and response convergence and geographic expansion into data sovereignty-constrained markets.
Within the cloud-native specialist tier, CrowdStrike and SentinelOne exemplify architecture-driven competitive positioning. Palo Alto Networks anchors enterprise trust through integrated platform consolidation spanning network and endpoint layers. Fortinet occupies a position as the price-performance alternative, bundling endpoint modules within its broader security fabric licensing to capture cost-constrained buyers.
| Leading Market Players |
|---|
| Broadcom Symantec |
| Fortinet |
| CrowdStrike |
| Sophos |
| Trellix |
| SentinelOne |
| Palo Alto Networks |
| Trend Micro |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
Subscription-based capacity reservation contracts lock in multi-year endpoint agent deployments while stabilizing vendor revenue visibility against churn volatility. US federal zero-trust mandates and EU NIS2 compliance deadlines compress procurement timelines, forcing buyers toward predictable SaaS billing rather than perpetual licensing negotiations.
Pricing Analysis
Geographic price spreads widen substantially between North American enterprise deployments and Asia-Pacific mid-market subscriptions, reflecting divergent security operations maturity and data sovereignty requirements. Three-tier pricing structure across premium, standard, and economy levels segments buyers by managed detection inclusion and response automation depth. Cost compression in the economy tier intensifies because Indian IT services exporters and educational institutions prioritize baseline malware protection over behavioral analytics. Government agencies exhibit the lowest price sensitivity due to classified environment mandates, while small and medium enterprises in unregulated sectors drive hardest bargain hunting.
Supply Chain Analysis
Israel and the United States anchor threat intelligence feed generation and machine-learning model development for behavioral analytics engines. Taiwan and South Korea manufacture the semiconductor substrates powering endpoint agent processing hardware. The supply chain draws from specialized cybersecurity talent pools, cloud infrastructure provisioning, and cryptographic certification services. Single-source vulnerability concentrates in elite threat research teams whose expertise cannot be rapidly replicated. Distribution runs through security-focused value-added resellers and hyperscaler marketplaces for cloud-native deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Endpoint security penetration remains below saturation across operational technology networks and mid-market managed service channels, creating expansion headroom as regulatory deadlines force first-time procurement.
For Market Incumbents: Shield platform consolidation gains by embedding extended detection and response telemetry correlation deeper into network security fabrics. Counter cloud-native specialist erosion through certification investment in German and French data residency schemes. Vertical integration into managed detection and response service delivery captures mid-market buyers abandoning in-house security operations center construction.
For New Entrants and Emerging Players: Lead with autonomous response automation targeting Japanese financial institutions facing acute cybersecurity workforce aging. India's Digital Personal Data Protection Act compliance rush offers the most penetrable geography for breach notification tooling. Channel partnership with British and Dutch managed security service providers accelerates subscription economics adoption without direct enterprise sales investment.
For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors cloud-native architecture specialists over legacy agent-heavy stack vendors. Long-term viability over the next decade hinges on extended detection and response convergence capabilities spanning identity and cloud workload telemetry. Watch for inflection signals in operational technology security procurement as manufacturing and energy sectors collapse separate IT and industrial control system procurement silos.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying network and endpoint layers satisfies US federal zero-trust architecture mandates. |
| Geographic Expansion | Establishing German and French data centers satisfies EU NIS2 data residency requirements. |
| Acquisition of Specialist Firm | Absorbing operational technology security vendors collapses procurement silos for manufacturing buyers. |
| Strategic Partnership | Aligning with managed security service providers captures mid-market outsourcing preference. |
| Product Launch | Introducing autonomous response automation addresses Japan's cybersecurity talent scarcity. |
Methodological Framework
Cross-validation between primary fieldwork and secondary data repositories anchors the qualitative findings in observable procurement patterns. Interviews with chief information security officers, managed security service provider executives, channel partner technical leads, and regulatory compliance officers generated demand-side intelligence. Secondary sources include SEC cybersecurity disclosure filings, EU Agency for Cybersecurity certification databases, hyperscaler security marketplace transaction data, and national critical infrastructure protection directives. Bottom-up endpoint deployment estimates triangulate against top-down security software spending forecasts.
Sensitivity analysis across deployment mode, organization size, vertical sector, integration complexity, and regional regulatory cluster dimensions stress-tests projection robustness. Compound annual growth rates derive from segment-level adoption curves weighted by compliance deadline proximity and security operations maturity indicators. Threat intelligence feed quality scores and mean-time-to-response benchmarks serve as industry-specific forecast inputs throughout the modeling period.
Forecasts assume regulatory continuity in US federal zero-trust mandates and EU NIS2 transposition timelines; material policy shifts would require re-modeling. Cybersecurity talent availability, cloud infrastructure cost trajectories, and operational technology convergence pace constitute specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Finland Cybersecurity Market
Cybersecurity
Turkey Cybersecurity Market
Cybersecurity
Europe Data Exfiltration Market
Cybersecurity
Global Mobile Application Security Market
Cybersecurity
Global Automated Breach and Attack Simulation (BAS) Market
Cybersecurity
Application Programming Interface Security Market
Cybersecurity
Data Security Market
Cybersecurity
Cloud Security in Banking Market
Cybersecurity
Global Digital Forensic Laboratory As a Service Market
Cybersecurity
Cloud Network Security Market
Cybersecurity
Global Patch Management Market
Cybersecurity
Industrial Cybersecurity Market
Cybersecurity
Next-Generation Firewall Market
Cybersecurity
SOC As a Service Market
Cybersecurity
Global Content Disarm and Reconstruction Market
Cybersecurity
Global Bug Bounty Platforms Market