
 Hypermarket Market | 2026-2036
Hypermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Hypermarket Market Foresight
REACH compliance is repositioning European hypermarket operators toward stricter supplier vetting and chemical disclosure protocols. Walmart leverages its North American distribution density to absorb traceability costs without margin erosion. Carrefour anchors its competitive stance through private-label expansion across fresh and packaged categories. Schwarz Group dominates Central European procurement networks through backward integration into dairy and baked goods.
A hypermarket denotes a large-format retail establishment exceeding typical supermarket scale, combining grocery assortments with general merchandise under one roof, typically requiring floor plates above standard retail thresholds to achieve inventory breadth and traffic economics. The format serves primary commercial purposes of maximizing basket size through trip consolidation while capturing economies of scale in logistics and labor deployment. Food and Beverage segments sustain the highest traffic frequency and margin stability, whereas Electronics commands premium positioning within supercenter formats. Warehouse Club configurations concentrate affluent family spending through membership lock-in, while Click & Collect channels capture professional segments seeking time efficiency without aisle traversal.
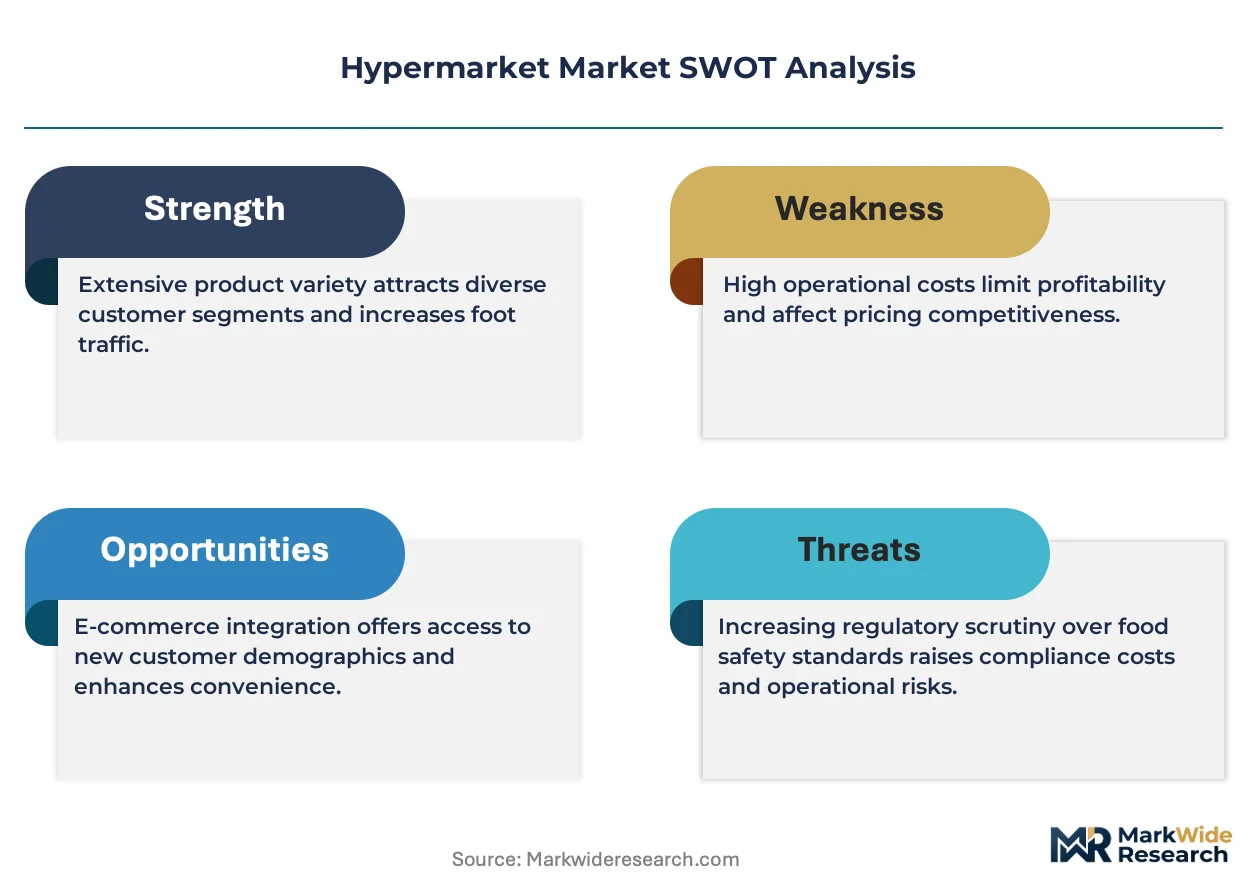
EU Green Deal frameworks and F-Gas Regulation standards constrain refrigeration infrastructure choices across European hypermarket estates, elevating capital requirements for new entrants. India's FSSAI mandates reshape cold-chain compliance for fresh produce sections, while China's SAMR enforces pricing transparency rules that limit promotional complexity. Stakeholders must weigh regulatory compliance costs against format scalability when evaluating entry or expansion commitments.
Market Dynamics
Urban consolidation of household shopping trips is compressing format economics across hypermarket estates, forcing operators to rebalance square footage between fresh food traffic drivers and general merchandise margin pools.
Growth Catalysts
- Digital payment infrastructure:China's SAMR pricing transparency rules and India's UPI network expansion are accelerating checkout velocity and reducing cash-handling labor costs across tier-one metropolitan stores.
- Cold-chain logistics upgrades:FSSAI mandates in India and EU Green Deal refrigeration standards are professionalizing fresh produce handling, extending shelf life and reducing shrinkage in high-traffic perishable sections.
- Membership lock-in models:Warehouse club configurations are capturing affluent family spending through annual fee structures that subsidize lower merchandise margins and deepen purchase frequency.
Market Restraints
- Refrigeration capex inflation:F-Gas Regulation compliance in Europe and dual carbon goals in China are elevating capital requirements for new store builds by mandating low-GWP refrigeration systems with shorter replacement cycles.
- Last-mile labor density:Click & Collect fulfillment requires 3-4x picker headcount per square meter versus traditional floor staffing, compressing labor productivity metrics in markets with rising minimum wages.
- Supermarket format substitution:Compact neighborhood formats with curated assortments are siphoning convenience-driven trips from large-footprint stores in dense urban corridors.
Strategic Opportunities
- Private-label fresh expansion:Backward integration into dairy and baked goods categories offers margin capture and differentiation in markets where branded CPG pricing faces regulatory scrutiny.
- India metropolitan corridor penetration:FSSAI cold-chain compliance investments create barriers to entry that favor established operators with capital reserves in Bangalore, Mumbai, and Delhi NCR.
- AI-driven demand forecasting:Convergence of computer vision shelf monitoring and machine learning replenishment algorithms is reducing out-of-stock rates in high-velocity produce and bakery sections.
Industry Challenges
- Refrigeration technician scarcity:F-Gas certification requirements in Europe and MEE environmental standards in China are outstripping qualified service technician supply, extending equipment downtime during peak summer loads.
- Legacy POS integration friction:Real-time inventory visibility across general merchandise and grocery divisions requires middleware layers that introduce latency and reconciliation errors during promotional events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypermarket Market |
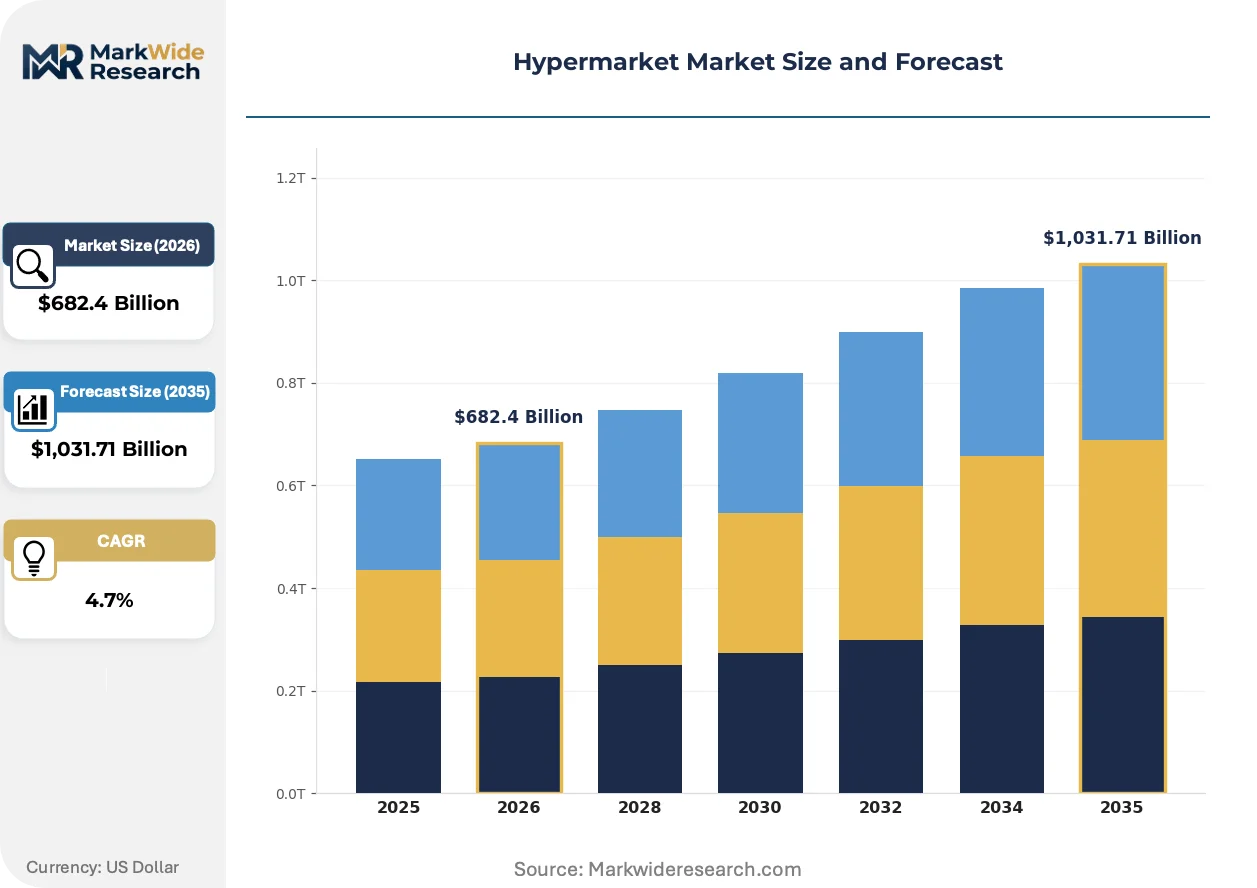
| Market Size in 2026 | $682.4 Billion |
| Market Size in 2035 | $1,031.71 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Beverage, Electronics, Clothing Store Format: Supercenter, Discount Store, Warehouse Club, Neighborhood Market Customer Type: Families, Singles, Professionals, Students Sales Channel: In-Store, Online, Mobile App, Click & Collect |
| Companies Covered | Kroger, ALDI, Walmart, Aldi Nord Group, Costco, Carrefour, Schwarz Group, REWE Group, Tesco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypermarket Market Shifts & Advancements
Automation of in-store fulfillment and predictive replenishment is compressing the gap between hypermarket scale and convenience-store responsiveness, reshaping capital allocation across the format.
Computer vision shelf-monitoring systems paired with edge-computing inference engines are electrifying real-time inventory tracking in fresh departments. Tier-one Chinese operators are deploying these systems at scale in Shanghai and Shenzhen stores. The technology is electrifying labor redeployment from manual stock checks to customer-facing service roles.
REACH chemical disclosure protocols are mandating granular supplier vetting across European hypermarket private-label supply chains. ECHA substance restrictions are propagating through textile, toy, and household chemical categories. Fresh and packaged food segments face the steepest compliance cost escalations as they source from fragmented agricultural upstreams.
Time-compressed professional households are consolidating weekly shopping into single hypermarket trips while delegating interim replenishment to quick-commerce platforms. This bifurcation is fragmenting basket composition between bulk pantry loading and immediate consumption needs. India's metropolitan corridors exhibit the most pronounced trip-splitting behavior between formats.
Hypermarket Market Segmentation
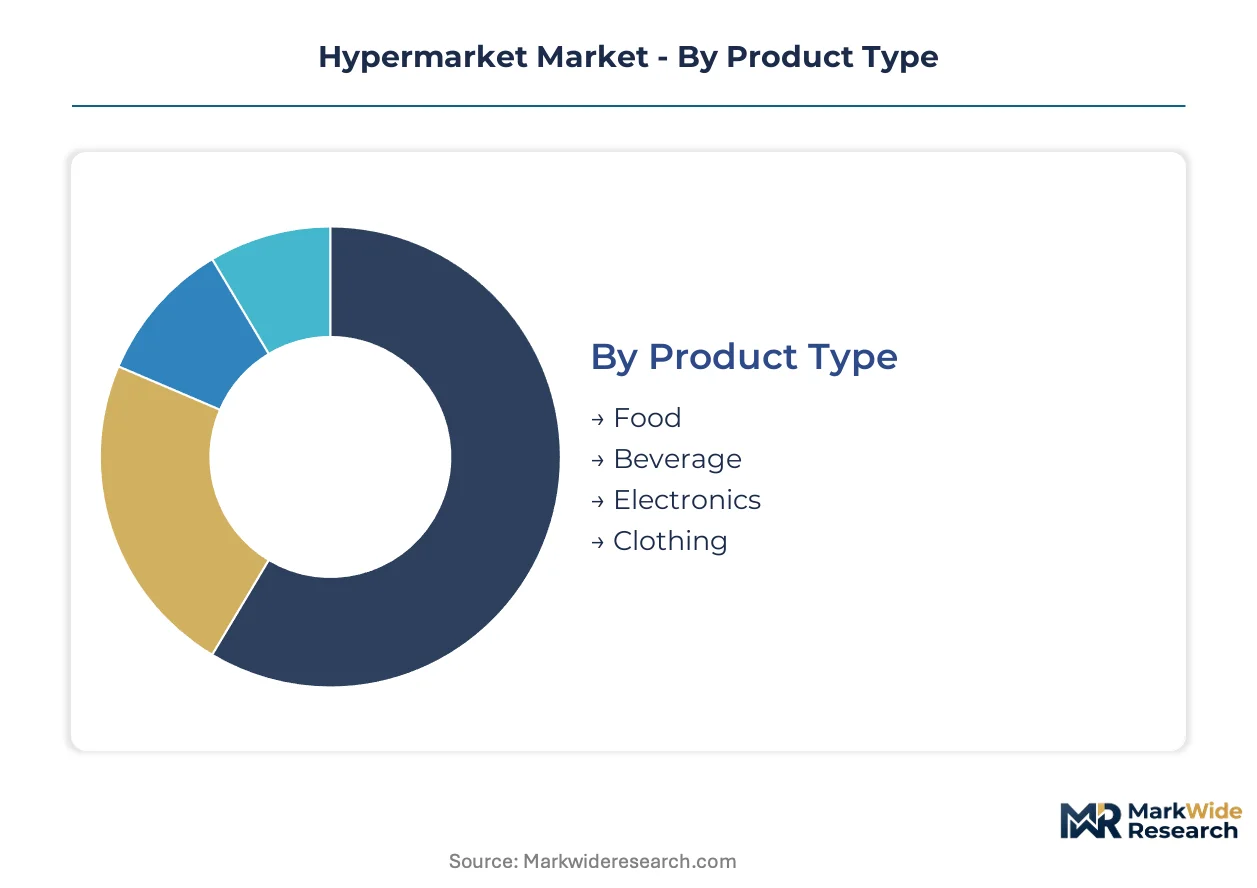
Hypermarket operators allocate capital unevenly across segment boundaries, with refrigeration-intensive categories and large-format real estate commanding disproportionate upfront investment. Format selection and channel architecture determine payback periods more than geographic positioning alone.
Product Type:
Fresh categories absorb the heaviest capital deployment through cold-chain infrastructure, while electronics and apparel require lower per-square-meter equipment outlays but higher working capital cycles.
- Food:Perishable assortments drive traffic frequency and mandate multi-temperature refrigeration zones. China's tier-one cities and India's metropolitan corridors concentrate demand as FSSAI and SAMR regulations professionalize cold-chain compliance.
- Beverage:High-velocity SKUs with seasonal demand spikes require modular cooler banks and rapid replenishment systems. EU Green Deal refrigeration standards are elevating capital requirements for new European beverage infrastructure.
- Electronics:Premium-margin category with extended replacement cycles and theft-sensitive inventory. Demand clusters in urban professional segments seeking one-stop convenience.
- Clothing:General merchandise anchor with lower equipment intensity but higher SKU proliferation and seasonal markdown risk. REACH compliance adds supplier vetting costs across European private-label programs.
Most installed capacity flows through Food. Expansion is steepest in Beverage.
Store Format:
Real estate footprint and membership mechanics create distinct capital structures, with warehouse clubs and supercenters locking up the largest balance-sheet commitments.
- Supercenter:Combines full grocery assortment with general merchandise under single roof, typically exceeding standard retail floor plates. China's SAMR pricing transparency rules and India's UPI infrastructure are compressing checkout friction in these high-traffic formats.
- Warehouse Club:Membership-fee model subsidizes lower merchandise margins while capturing affluent family spending through annual lock-in. Cold-chain investments concentrate in fresh and frozen sections to differentiate against online competitors.
- Discount Store:Curated assortment with reduced service levels and streamlined SKU counts. Capital efficiency attracts operators in markets with constrained real estate availability.
- Neighborhood Market:Compact format siphoning convenience trips from large-footprint competitors. Lower refrigeration capex per door but compressed labor productivity in high-rent urban corridors.
Supercenter deployments dominate existing square footage. Warehouse Club configurations are climbing the fastest.
Customer Type:
Basket composition and trip frequency vary sharply across household structures, with family units consolidating volume and professionals prioritizing time efficiency.
- Families:Primary volume driver consolidating weekly pantry loading into single trips. Bulk purchasing patterns justify large-format real estate economics.
- Singles:Smaller basket sizes with higher trip frequency, often delegating replenishment to quick-commerce platforms rather than hypermarket visits.
- Professionals:Time-compressed households splitting purchases between hypermarket bulk trips and interim digital channels. Click & Collect penetration is highest in this segment.
- Students:Price-sensitive with limited storage capacity, favoring discount formats and smaller pack sizes over warehouse club memberships.
Families account for the majority of transaction volume. Professionals are gaining share fastest through channel-splitting behavior.
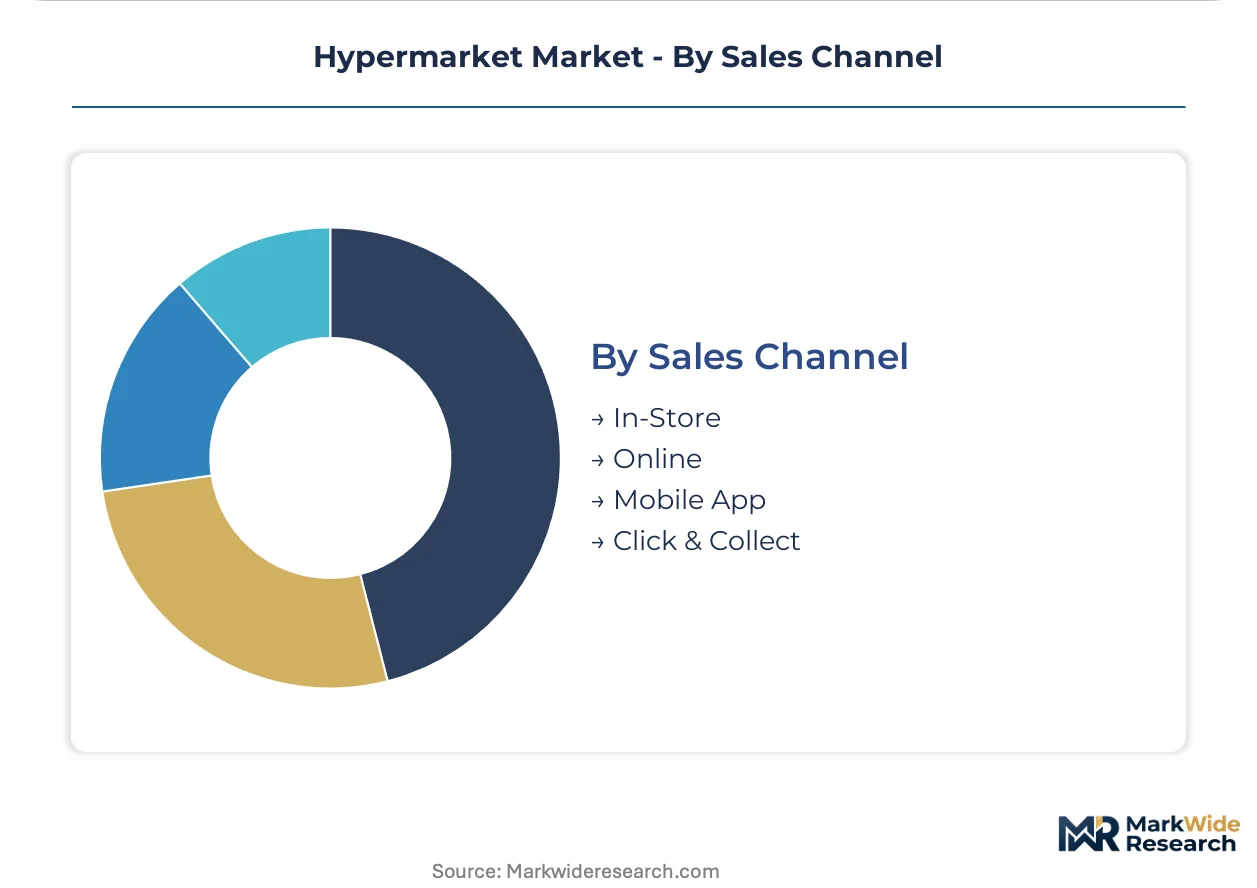
Sales Channel:
Digital integration intensity determines labor model and inventory visibility requirements, with pure online fulfillment demanding the most complex backend systems.
- In-Store:Traditional floor-staffing model with fixed checkout infrastructure. India's UPI network and China's digital payment density are reducing cash-handling headcount.
- Online:Home delivery fulfillment requiring dedicated picking infrastructure and last-mile partnerships. Labor density runs 3-4x higher per square meter than traditional formats.
- Mobile App:Loyalty-integrated ordering layer with personalized promotion delivery. Real-time inventory synchronization remains technically challenging across general merchandise and grocery divisions.
- Click & Collect:Hybrid model capturing professional segments seeking time efficiency without aisle traversal. Fulfilled from store inventory with dedicated staging areas.
In-Store retains the largest transaction share. Click & Collect is expanding most quickly among metropolitan professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban retail talent pools concentrate in Asia-Pacific metropolitan corridors and European logistics hubs, anchoring format innovation and cold-chain expertise.
China
SAMR pricing transparency rules compress promotional complexity while tier-one cities absorb supercenter expansion. MEE environmental standards mandate low-GWP refrigeration retrofits across Shanghai and Shenzhen estates. Yangtze River Delta clusters deploy computer vision shelf-monitoring at scale, electrifying labor redeployment to customer-facing roles.
United States
Warehouse club membership density and UPI-equivalent digital payment penetration sustain format economics. OSHA workplace safety protocols and FDA food safety mandates elevate operational compliance costs. Texas and Florida metropolitan corridors concentrate new supercenter groundbreakings, absorbing last-mile labor inflation through automation investments.
India
FSSAI cold-chain compliance investments professionalize fresh produce handling across Bangalore, Mumbai, and Delhi NCR. UPI network expansion accelerates checkout velocity, reducing cash-handling headcount. Metropolitan corridor penetration favors established operators with capital reserves to absorb refrigeration capex barriers.
Germany
REACH chemical disclosure protocols and EU Green Deal refrigeration standards constrain estate expansion. ECHA substance restrictions propagate through private-label supply chains, elevating supplier vetting costs. Bavaria and North Rhine-Westphalia anchor Schwarz Group procurement networks through backward integration into dairy and baked goods.
Brazil
Neighborhood format substitution pressures large-footprint economics in São Paulo and Rio de Janeiro dense urban cores. ANVISA food safety mandates reshape cold-chain compliance for fresh sections. Discount format capital efficiency attracts operators confronting constrained real estate availability in metropolitan corridors.
Hypermarket Market Competitive Landscape
The competitive structure tilts toward diversified retail conglomerates with multi-format portfolios. Consolidation concentrates among North American warehouse clubs and European private-label specialists. Three archetypes dominate: scale-driven supercenter operators, membership-fee warehouse clubs, and vertically integrated discount specialists. M&A activity and cold-chain infrastructure partnerships constitute the primary competitive vectors reshaping market positioning.
Within the scale-driven tier, Walmart anchors North American distribution density, while Carrefour occupies a position exemplifying European private-label expansion. Schwarz Group sits within the vertically integrated archetype, representing backward integration strategies into fresh categories. These three entities collectively illustrate the strategic divergence between geographic market penetration and supply-chain control.
| Leading Market Players |
|---|
| Kroger |
| ALDI |
| Walmart |
| Aldi Nord Group |
| Costco |
| Carrefour |
| Schwarz Group |
| REWE Group |
| Tesco |
| Others |
Supply & Pricing Matrix
Global food commodity indices and energy benchmarks cascade through hypermarket supply chains into three distinct pricing tiers. Cold-chain logistics costs and private-label procurement scale determine margin allocation between premium fresh formats and economy-oriented discount channels.
Pricing Analysis
The bundled-vs-unbundled service split separates membership-fee warehouse clubs from transactional supercenter formats. Three-tier pricing structure across premium, standard, and economy levels tracks cold-chain investment intensity and SKU breadth. Price differentiation hinges on after-sales service bundling and geographic delivery density. Cost compression in economy tiers intensifies because neighborhood format substitution erodes traffic. Students exhibit highest price sensitivity; affluent families locked into warehouse memberships show lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for perishable returns and packaging refurbishment reshape inventory velocity in fresh departments. Supply concentrates in China for electronics and general merchandise, India for agricultural produce and textiles, and Germany for precision refrigeration equipment. Raw material dependencies center on steel for shelving infrastructure, aluminum for beverage cans, and specialty gases for cooling systems. Single-source vulnerability in compressor manufacturing elevates downtime risk during peak summer loads. Distribution runs through regional distribution centers feeding last-mile store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Urban household consolidation toward premium fresh specifications and cold-chain reliability rewards operators with backward-integrated supply control.
For Market Incumbents: Deepen cold-chain infrastructure ownership in India's metropolitan corridors to preempt FSSAI compliance barriers. Expand private-label dairy and baked goods capacity to capture margin pools threatened by branded CPG pricing scrutiny. Lock in refrigeration technician training pipelines before MEE and F-Gas certification shortages intensify.
For New Entrants and Emerging Players: Enter via compact neighborhood formats in Brazil's São Paulo and Rio de Janeiro cores where real estate constraints favor capital-efficient footprints. Target India's Bangalore and Delhi NCR corridors with click-and-collect specialization for time-compressed professionals. Deploy AI-driven demand forecasting as differentiated service layer.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated discount specialists controlling upstream fresh categories. Five-to-ten year viability favors operators with captive dairy, baked goods, and produce supply chains. Monitor FSSAI and EU Green Deal refrigeration capex inflation as consolidation trigger signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fresh Categories | Captures margin pools in dairy and baked goods while differentiating against online competitors. |
| Cold-Chain Infrastructure Expansion | Builds FSSAI and EU Green Deal compliance moats in India's metropolitan corridors. |
| AI-Driven Demand Forecasting Deployment | Reduces out-of-stock rates in high-velocity produce sections through computer vision integration. |
| Click-and-Collect Channel Buildout | Captures professional segments seeking time efficiency without aisle traversal in tier-one cities. |
| Private-Label Assortment Deepening | Offsets branded CPG pricing pressure under SAMR transparency rules and REACH disclosure protocols. |
Research Methodology
Bottom-up store-format modeling reconciled against top-down cold-chain infrastructure tracking forms the analytical core. Primary interviews with hypermarket operations directors, category buyers, refrigeration equipment suppliers, and FSSAI compliance officers combined with secondary validation. Customs records, SAMR pricing filings, EU ECHA substance databases, and Nielsen retail audit data anchored supply-side and demand-side estimates. Triangulation across stakeholder inputs and documentary sources calibrated segment-level projections.
Input-output matrices mapped capital deployment across refrigeration equipment, real estate, and labor categories against traffic and basket-size outputs. Segmentation dimensions modeled include product type, store format, customer archetype, and sales channel across the projection horizon. CAGRs derived from logistic diffusion curves for digital payment penetration and cold-chain compliance adoption. Forecast inputs incorporated UPI network expansion velocity and F-Gas Regulation retrofit timelines.
Inputs from regulatory filings and equipment supplier disclosures were available through the study window; gaps in private-label margin data introduce uncertainty bands. Forecasts reflect documented assumptions about urban household consolidation and refrigeration technician supply elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Security Bottles Market
Others
UAE Location-Based Services Market
Others
Automotive Smart Lighting Market
Others
Solar Animal Repeller Market
Others
Digital Media Adaptor (DMA) Market
Others
Profiling Floats Market
Others
Europe Astrology Market
Others
Tunnel Lighting Market
Others
Diamond Mining Market
Others
Global Automotive LED Lighting Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Interference Mitigation Filters Market
Others
US Cat Food Market
Others
Mobile Computing Devices Market
Others
Shisha Tobacco Market
Others
Radiation Detection Monitoring and Safety Market