
 Automotive Predictive Technology Market | 2026-2036
Automotive Predictive Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Predictive Technology Market Outlook
Multi-source procurement of AI training datasets and sensor fusion modules is shifting toward captive data collection pipelines. Robert Bosch GmbH leverages its manufacturing scale to anchor in-house predictive algorithm development for braking and steering systems. NVIDIA Corporation competes through specialized GPU architectures optimized for real-time inference at the vehicle edge. Continental AG sustains R&D intensity across neural network validation labs in Germany and the United States.
Automotive predictive technology encompasses machine learning models, sensor fusion architectures, and edge computing frameworks that process real-time vehicle telemetry to forecast component failures, driver behavior patterns, and collision risks before occurrence. These systems typically operate with sub-100-millisecond latency requirements and integrate CAN bus data streams with cloud-based fleet analytics to enable preemptive maintenance scheduling and dynamic insurance underwriting. Machine learning and predictive maintenance segments lead current deployment volumes, while neural networks and edge computing represent the fastest-growing solution categories as OEMs prioritize localized inference over cloud dependency. Fleet management and accident prevention applications command the deepest margin pools due to their direct linkage with commercial fleet operating costs and liability reduction.
FDA oversight of software-as-medical-device classifications, NHTSA automated vehicle guidance, and ISO 26262 functional safety standards collectively shape product validation timelines and algorithmic transparency requirements for predictive systems deployed in production vehicles. The EU AI Act adds conformity assessment obligations for high-risk AI applications in mobility, compelling suppliers to maintain auditable training datasets and bias mitigation documentation. Stakeholders must monitor evolving regulatory divergence between jurisdictions to determine whether to architect unified global platforms or regionally differentiated compliance stacks.
Market Dynamics
The EU AI Act and ISO 26262 functional safety standards are compressing product validation timelines while forcing suppliers to maintain auditable training datasets and bias mitigation documentation. Fleet operators now demand sub-100-millisecond latency guarantees for predictive maintenance platforms, creating technical barriers for cloud-dependent architectures.
Growth Catalysts
- Fleet operator demand:Commercial vehicle operators are mandating predictive maintenance integration to minimize downtime and reduce liability exposure across heavy-duty trucking and logistics fleets.
- EU AI Act conformity requirements:The regulation's high-risk AI application classification for mobility systems is accelerating supplier investment in transparent algorithmic architectures and documented bias testing protocols.
- Sensor fusion advancement:Multi-source data pipelines combining CAN bus telemetry with lidar and radar inputs are enabling more accurate component failure forecasting for braking and steering systems.
Market Restraints
- GPU supply concentration:Specialized inference accelerators for vehicle-edge deployment face supply bottlenecks concentrated among NVIDIA and limited alternative fabricators, constraining OEM scaling timelines.
- ISO 26262 certification costs:Functional safety validation for ASIL-D rated predictive systems requires 18-36 month development cycles and specialized engineering talent pools that remain geographically concentrated in Germany and the United States.
- Edge-to-cloud latency tradeoffs:Real-time inference requirements at the vehicle edge necessitate hardware architectures that sacrifice model complexity, limiting predictive accuracy for rare failure modes.
Strategic Opportunities
- India commercial vehicle penetration:The country's fragmented fleet operator base and emerging telematics infrastructure present first-mover advantages for predictive platform providers targeting BharatBenz and Tata Motors integration.
- Dynamic insurance underwriting:Usage-based insurance models leveraging real-time driver behavior prediction are creating new revenue streams for platforms that integrate with AXA and Allianz risk pricing systems.
- Neural network validation automation:Convergence of formal verification methods with machine learning testing is reducing ISO 26262 compliance costs and opening mid-tier supplier participation.
Industry Challenges
- Functional safety engineer scarcity:ASIL-D certification expertise remains concentrated among Bosch, Continental, and a handful of specialized consultancies, inflating talent acquisition costs for new entrants.
- Legacy CAN bus integration:Predictive systems must interface with heterogeneous vehicle communication protocols spanning 20+ years of production models, complicating software architecture standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Predictive Technology Market |
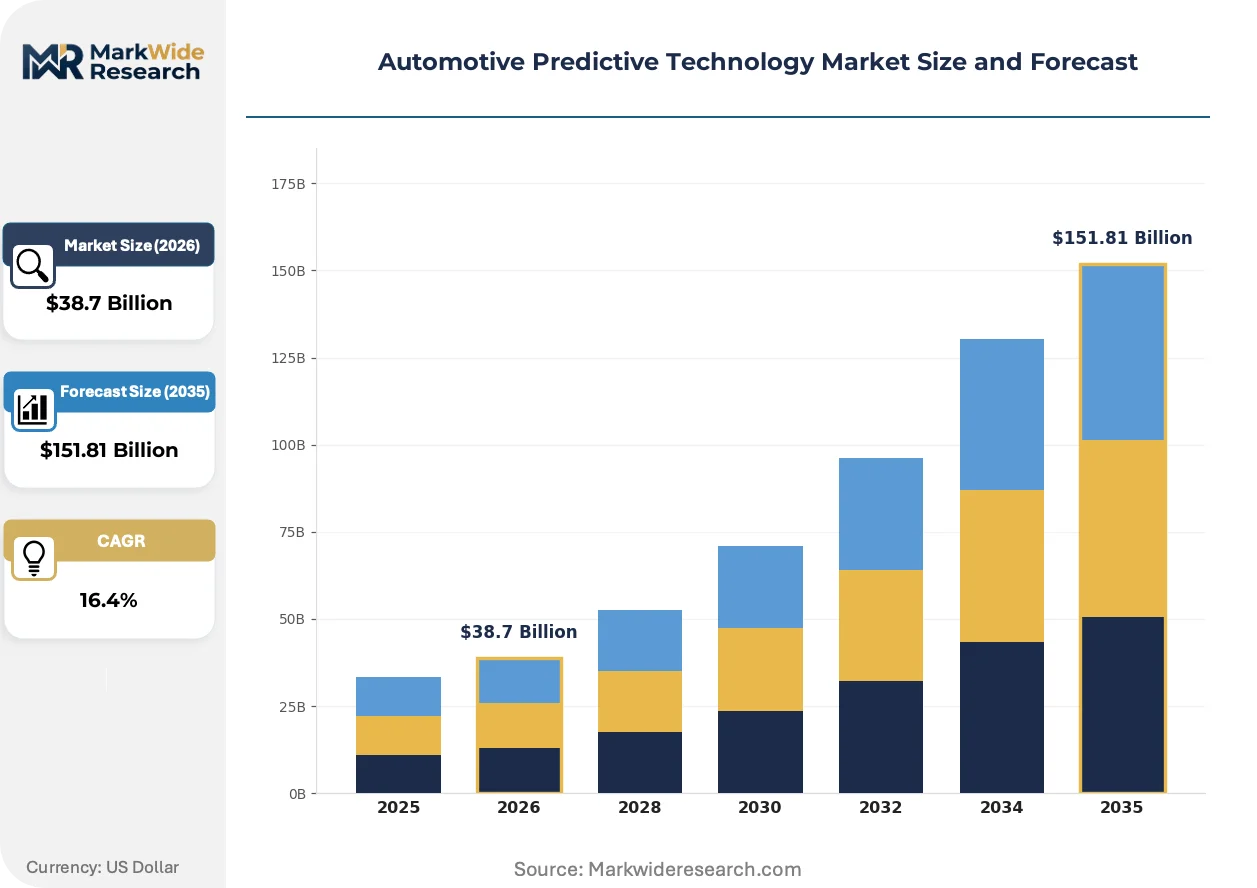
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Neural Networks, Data Analytics, Predictive Maintenance Application: Fleet Management, Driver Behavior Prediction, Vehicle Diagnostics, Accident Prevention End User: OEMs, Aftermarket Providers, Insurance Companies, Fleet Operators Solution: Software Solutions, Hardware Integration, Cloud Services, Edge Computing |
| Companies Covered | Aptiv PLC, Valeo SA, Robert Bosch GmbH, Intel Corporation, NVIDIA Corporation, Continental AG, ZF Friedrichshafen AG, Cerence, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Predictive Technology Market Strategic Shifts
Edge computing architectures are displacing cloud-dependent inference models as OEMs prioritize data sovereignty and latency guarantees. Neural network compression techniques and specialized accelerators are enabling complex predictive models to run on vehicle-mounted hardware with minimal power consumption penalties.
Transformer-based neural architectures is overtaking recurrent neural networks for time-series prediction of component degradation patterns. Tier-1 suppliers including braking system manufacturers are adopting these models for real-time thermal load forecasting. The shift is overtaking traditional physics-based simulation approaches and compressing algorithm development cycles from months to weeks.
The EU AI Act's high-risk AI conformity assessment obligations are reshaping supplier documentation requirements for algorithmic decision-making in vehicles. OEMs must now maintain version-controlled training datasets and explainability logs for predictive systems affecting vehicle control. German manufacturers around Stuttgart and Munich are responding fastest, establishing dedicated AI governance offices to manage regulatory submissions.
Fleet procurement teams are consolidating vendor relationships around platforms offering integrated maintenance scheduling and insurance underwriting APIs. The shift is compressing supplier margins for standalone predictive maintenance modules while rewarding end-to-end solution providers. This concentration is most visible in Germany's commercial vehicle sector, where Daimler Truck and MAN are mandating unified telematics platforms across their leasing subsidiaries.
Automotive Predictive Technology Market Segmentation
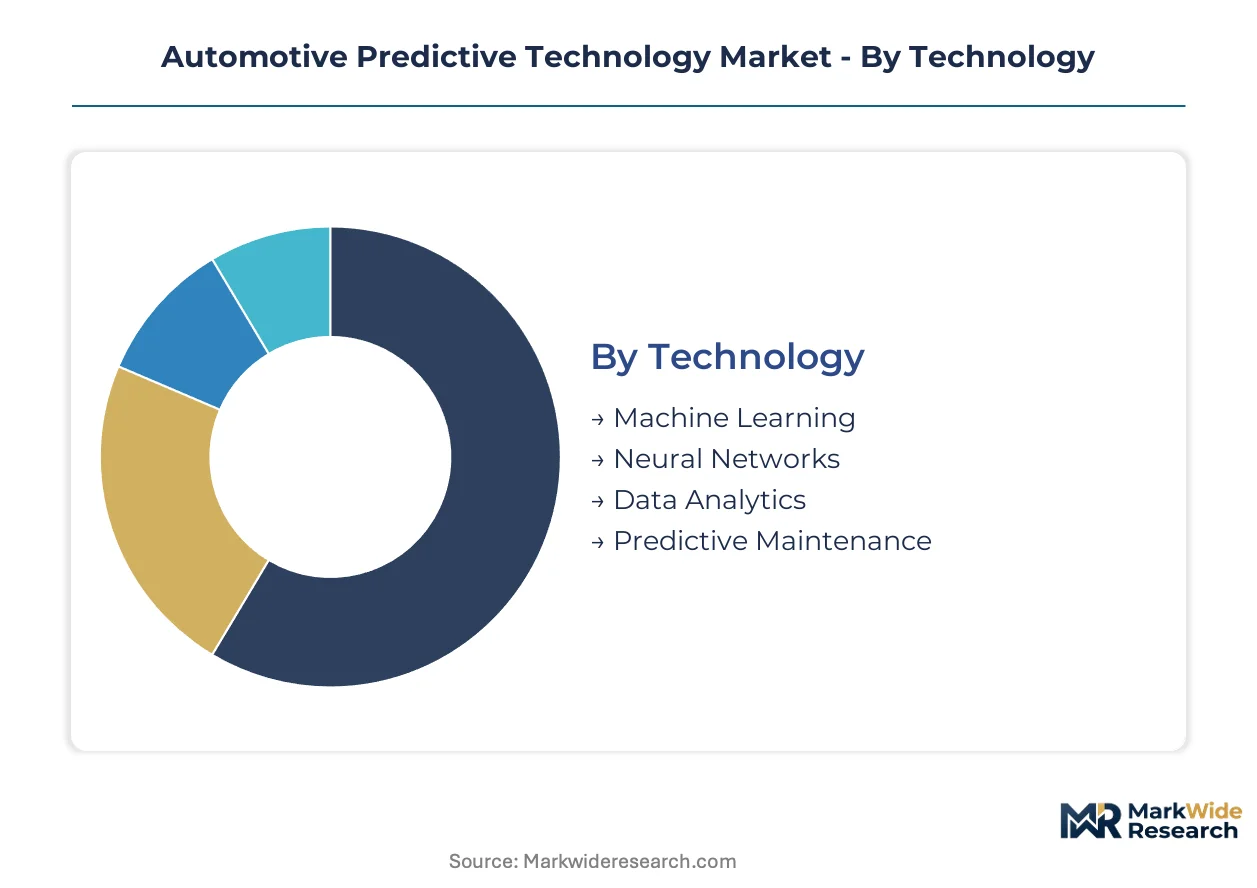
Technology choices in automotive predictive systems determine latency budgets, certification pathways, and hardware procurement strategies. Fleet operators and OEMs prioritize segments that align with ISO 26262 ASIL ratings and EU AI Act documentation requirements.
Technology:
Upgrade cycles for predictive algorithms accelerate as transformer architectures displace legacy recurrent neural networks in braking and steering system forecasting.
- Machine Learning:Supervised learning models process CAN bus telemetry to classify component degradation states. Demand concentrates in Germany's Stuttgart automotive cluster where Bosch and Continental anchor R&D for thermal load prediction in brake systems.
- Neural Networks:Deep learning architectures enable end-to-end prediction of driver behavior patterns from multi-sensor fusion inputs. Fleet operators in commercial trucking mandate these systems for insurance underwriting integration with AXA and Allianz risk pricing platforms.
- Data Analytics:Statistical process control methods aggregate historical failure data for pattern recognition in warranty claims.
- Predictive Maintenance:Time-series forecasting models schedule component replacement before failure occurrence.
Volume placements concentrate in Machine Learning; the faster expansion belongs to Neural Networks.
Application:
Cost tier differentiation separates premium integrated platforms from standalone modules, with bundled maintenance-insurance APIs commanding margin premiums.
- Fleet Management:Unified telematics platforms consolidate vehicle tracking, predictive maintenance scheduling, and fuel optimization. Daimler Truck and MAN mandate these systems across German leasing subsidiaries to minimize downtime liability.
- Accident Prevention:Real-time collision risk forecasting integrates lidar, radar, and camera inputs with sub-100-millisecond inference latency. NHTSA automated vehicle guidance shapes validation requirements for US deployments.
- Driver Behavior Prediction:Pattern recognition models score risk profiles for dynamic insurance premium adjustment.
- Vehicle Diagnostics:Onboard health monitoring systems flag anomalies in powertrain and chassis components.
Revenue concentration sits with Fleet Management; the steepest expansion trajectory belongs to Accident Prevention.
End User:
Customer type determines procurement scale, with OEM integration requiring 18-36 month ASIL-D certification cycles that aftermarket providers bypass.
- OEMs:Vehicle manufacturers embed predictive systems at design phase with hardware-software co-validation. Robert Bosch GmbH supplies braking and steering prediction modules requiring ISO 26262 ASIL-D documentation.
- Fleet Operators:Commercial vehicle owners mandate predictive maintenance to reduce liability exposure and operating costs. Fragmented operator bases in India present first-mover opportunities for BharatBenz and Tata Motors integration.
- Aftermarket Providers:Retrofit solution vendors target legacy vehicle fleets with telematics hardware upgrades.
- Insurance Companies:Underwriters leverage real-time behavior data for usage-based risk pricing models.
Procurement volume clusters with OEMs; the fastest share gain belongs to Fleet Operators.
Solution:
Supply concentration in GPU fabrication constrains scaling timelines for edge-dependent architectures, favoring hybrid cloud-edge deployments.
- Edge Computing:Vehicle-mounted inference processors execute predictive models with localized data sovereignty. NVIDIA specialized GPU architectures dominate real-time thermal forecasting for Tier-1 braking system suppliers.
- Cloud Services:Centralized model training and fleet-wide analytics platforms aggregate telemetry across distributed vehicle populations. EU AI Act conformity assessment obligations compel German manufacturers to maintain auditable training datasets in Munich and Stuttgart governance offices.
- Software Solutions:Licensed algorithm stacks deploy across heterogeneous hardware configurations.
- Hardware Integration:Custom silicon and sensor fusion modules combine for dedicated predictive processing.
Deployment volume favors Cloud Services; the most rapid scaling belongs to Edge Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive engineering clusters supply the silicon carbide substrates and precision sensor modules that anchor predictive system manufacturing across three continents.
United States
NHTSA automated vehicle guidance and commercial fleet liability pressures drive predictive platform procurement from heavy-duty trucking operators. The IRA clean vehicle tax credits accelerate edge computing hardware deployment in Michigan and Ohio assembly plants. Detroit-Warren-Dearborn anchors Tier-1 supplier R&D for thermal load forecasting in brake systems.
Germany
EU AI Act conformity assessments and ISO 26262 ASIL-D certification requirements compress supplier validation timelines for algorithmic transparency. KBA type approval processes mandate auditable training datasets for high-risk AI mobility applications. Stuttgart and Munich host dedicated AI governance offices managing regulatory submissions for Bosch and Continental neural network validation labs.
China
MIIT intelligent vehicle standards and dual carbon goals propel domestic OEM adoption of predictive maintenance for electric commercial fleets. GB standards for functional safety shape local certification pathways distinct from ISO 26262. Yangtze River Delta clusters around Shanghai concentrate lidar fusion module manufacturing for real-time collision risk systems.
India
Fragmented commercial vehicle operator bases and emerging telematics infrastructure create first-mover opportunities for BharatBenz and Tata Motors integration. PLI scheme incentives for automotive electronics attract edge computing hardware assembly to Tamil Nadu and Gujarat. Pune and Chennai host expanding validation facilities serving domestic fleet management platform deployment.
Japan
METI mobility-as-a-service initiatives and aging commercial driver demographics accelerate predictive behavior scoring for insurance underwriting integration. JIS standards for vehicle communication protocols influence CAN bus data architecture choices. Nagoya-Toyota City corridors concentrate Tier-1 supplier R&D for sensor fusion modules in steering and braking systems.
Automotive Predictive Technology Market Competitive Environment
Global majors compete with regional champions across certification depth and sensor fusion specialization. Market structure tilts toward consolidated Tier-1 supply with ASIL-D documentation capabilities, though mid-tier algorithm vendors fragment around specific fleet management applications. Three archetypes dominate: integrated automotive electronics conglomerates with captive silicon design, specialized GPU architecture suppliers for edge inference, and telematics platform operators bundling maintenance scheduling with insurance APIs. Competitive moves concentrate on strategic partnerships for sensor fusion data pipelines and geographic expansion into underpenetrated commercial vehicle markets.
Within the integrated electronics tier, Robert Bosch GmbH and Continental AG exemplify the full-stack validation capabilities required for EU AI Act compliance. NVIDIA Corporation occupies a distinct position supplying specialized inference accelerators where real-time thermal forecasting demands exceed general-purpose processor limits. These three anchors represent the certification-heavy, hardware-software co-validation archetype that OEM procurement teams increasingly mandate for braking and steering system integration.
| Leading Market Players |
|---|
| Aptiv PLC |
| Valeo SA |
| Robert Bosch GmbH |
| Intel Corporation |
| NVIDIA Corporation |
| Continental AG |
| ZF Friedrichshafen AG |
| Cerence |
| DENSO Corporation |
| Others |
Value Chain & Pricing Dynamics
EU AI Act conformity requirements gate both qualified supply and premium-tier pricing access for predictive algorithm vendors, compressing margins for uncertified competitors while rewarding ASIL-D documentation capabilities with service-bundled premiums.
Pricing Analysis
Warranty and predictive maintenance service bundling separates premium integrated platforms from standalone software licenses. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 certification grade and after-sales support depth. Price differentiation hinges on ASIL-D validation documentation and real-time latency guarantees below 100 milliseconds. Fleet operators in commercial trucking exhibit highest price sensitivity, while OEM procurement teams prioritize certification depth over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Shanghai anchor hub-and-spoke fulfillment patterns for edge computing hardware and sensor fusion modules. GPU accelerator supply concentrates in Taiwan, South Korea, and the United States, drawing from silicon carbide substrates and precision lidar components. Single-source vulnerability in NVIDIA specialized inference chips creates procurement risk for Tier-1 braking system suppliers. Distribution runs through captive OEM logistics networks and Tier-1 supplier direct fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transformer-based neural architectures are displacing recurrent neural networks for time-series component degradation forecasting, compressing algorithm development cycles and reshaping competitive entry barriers.
For Market Incumbents: To counter GPU supply concentration bottlenecks, Robert Bosch GmbH and Continental AG should deepen backward integration into specialized inference silicon design while expanding neural network validation lab capacity in Germany. Certification investment in EU AI Act documentation capabilities remains the critical defensive lever against mid-tier algorithm vendors. For New Entrants and Emerging Players: Capture fragmented fleet operator bases in India through BharatBenz and Tata Motors integration partnerships, targeting telematics platform white space with bundled maintenance-insurance API offerings. Dynamic insurance underwriting integration with AXA and Allianz risk pricing systems offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: First-mover establishment of dedicated AI governance offices by German manufacturers is the leading indicator that regulatory compliance capabilities will determine acquisition premiums. Long-term viability favors vertically integrated automotive electronics conglomerates with captive silicon design and ASIL-D certification depth. Watch for neural network validation automation convergence with formal verification methods as the inflection signal for mid-tier supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Unified telematics architectures reduce OEM integration costs for Daimler Truck and MAN leasing subsidiaries. |
| Battery Supply Agreement | Edge computing hardware deployment accelerates with IRA clean vehicle tax credits in Michigan assembly plants. |
| Software-Defined Vehicle Investment | Real-time inference localization prioritizes data sovereignty over cloud-dependent architectures. |
| Geographic Manufacturing Footprint | PLI scheme incentives attract predictive hardware assembly to Tamil Nadu and Gujarat for Indian fleet penetration. |
| Charging Infrastructure Partnership | MIIT intelligent vehicle standards propel predictive maintenance adoption across Yangtze River Delta electric commercial fleets. |
Study Parameters
SEC filings, IHS Markit vehicle production databases, and EU regulatory submission records formed the secondary backbone, supplemented by primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet management operators. Bottom-up unit economics triangulated against top-down market sizing across technology, application, end user, and solution dimensions.
Historical trendline analysis of predictive algorithm deployment volumes and edge computing hardware shipments established baseline growth patterns across the projection horizon. Segmentation modeling incorporated machine learning versus neural network technology splits, fleet management versus accident prevention application tiers, and OEM versus fleet operator end user categories. CAGRs derived from weighted average of technology diffusion curves and regulatory compliance timeline compression.
The model holds under stable EU AI Act implementation timelines and continued GPU supply concentration; deviation in ISO 26262 certification cost trajectories or alternative inference accelerator commercialization would shift competitive dynamics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
India Autonomous Navigation Market
Autonomous Vehicles
Blind Spot Detection Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Europe IoT Connected Cars Market