
 Soft Signage Market | 2026-2036
Soft Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Signage Market Outlook
Polyester is expanding its share in soft signage substrates as PVC-free alternatives gain commercial traction among environmentally constrained buyers. HP leverages vertical integration across ink and printhead technology to sustain margin capture in high-speed dye-sub segments. Epson anchors its position in precision piezoelectric systems that dominate photographic-quality backdrop production. Mimaki competes through specialized textile printer configurations tailored to short-run event marketing workflows.
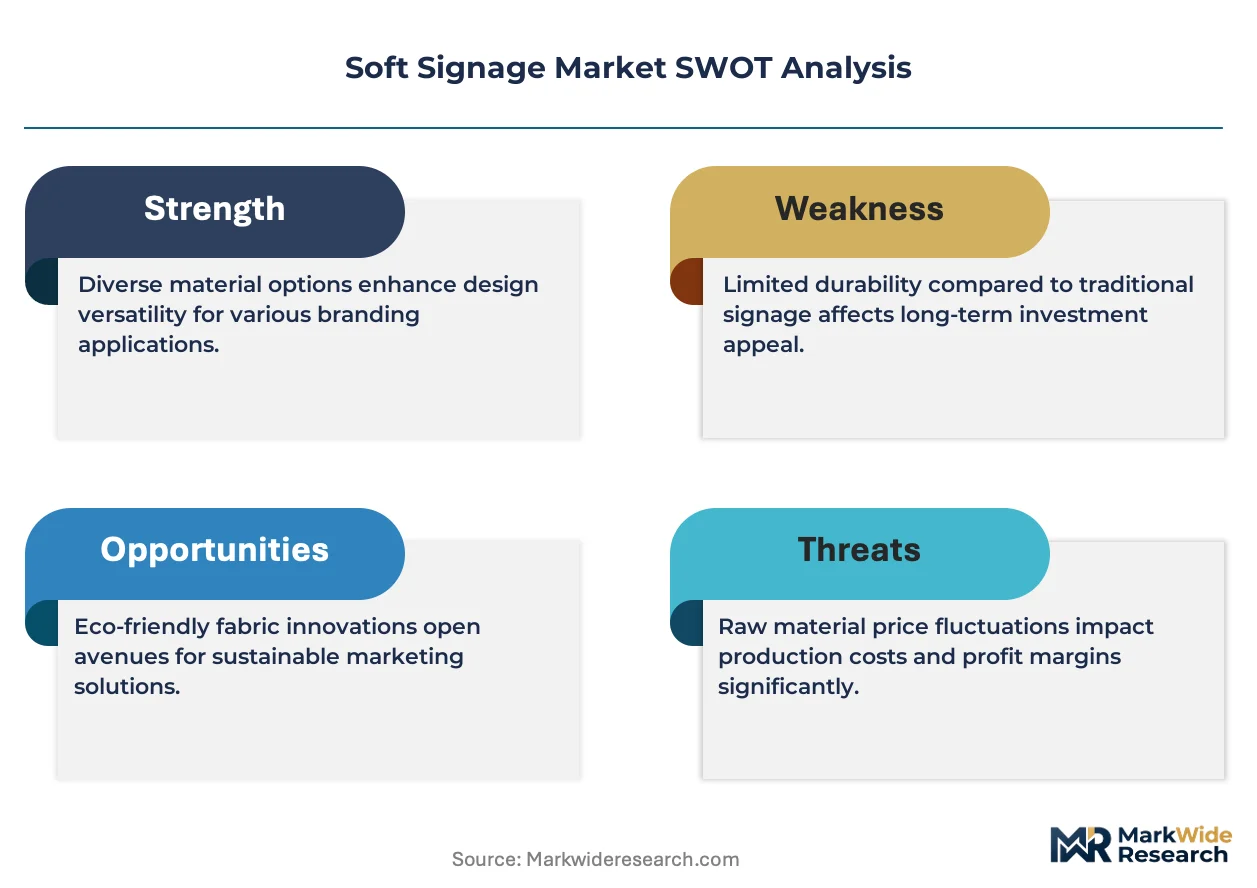
Soft signage comprises flexible, fabric-based visual communication substrates engineered for dye-sublimation, UV, or latex ink reception, typically constructed from woven polyester or knit textiles with weights ranging from 90 to 300 gsm for dimensional stability during tensioning. Its primary commercial purpose spans temporary and semi-permanent promotional display, trade show architecture, and retail environment graphics where portability and storage efficiency outweigh rigid panel requirements. Fabric-based banners command the largest volume share within product type segmentation, though POS displays generate superior per-unit margins through customized finishing and rapid turnaround demands. Event marketing represents the fastest-expanding application channel as experiential budgets recover and brands prioritize reusable, collapsible display systems over single-use vinyl.
EPA regulations governing volatile organic compound emissions from wide-format printing operations directly constrain solvent-based ink formulations and push conversion toward latex and UV-curable alternatives. REACH restrictions on phthalate plasticizers and persistent organic pollutants in Europe restrict PVC-coated substrate imports while accelerating certified polyester and recycled nylon qualification programs. California's Air Resources Board maintains the most stringent state-level VOC thresholds in the United States, creating a de facto national compliance benchmark for domestic manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks for textile waste, as these policies will determine which material-recovery partnerships and substrate circularity investments yield durable competitive advantage.
Market Dynamics
Retail chains are systematically replacing rigid substrates with fabric-based displays, compressing traditional wide-format vinyl demand while expanding dye-sublimation printer utilization rates across commercial print service providers.
Growth Catalysts
- REACH compliance deadlines:European phthalate restrictions on PVC-coated imports are accelerating certified polyester qualification programs among brand owners.
- Experiential marketing budgets:Event production houses are prioritizing reusable, collapsible fabric systems over single-use vinyl for trade show architecture.
- Guangdong Province cluster density:Proximity between dye-sub printer OEMs and textile finishing houses in southern China compresses lead times for export orders.
Market Restraints
- Petrochemical input volatility:Purified terephthalic acid and ethylene glycol price swings destabilize polyester substrate cost structures.
- EPA VOC thresholds:California Air Resources Board emission limits constrain solvent-based ink formulation options for domestic converters.
- Rigid substrate substitution:Aluminum composite panels and acrylic sheets retain cost advantages for permanent retail installations.
Strategic Opportunities
- Extended producer responsibility frameworks:EU textile waste directives will reward material-recovery partnerships with durable procurement advantages.
- UV-curable latex convergence:Hybrid ink technologies are opening short-run textile applications previously reserved for dye-sublimation.
- India retail modernization:Organized retail expansion in tier-two cities is generating first-time demand for portable fabric display systems.
Industry Challenges
- Color management expertise scarcity:Dye-sub profile calibration for polyester knits requires specialized operators that print shops struggle to recruit.
- Finishing equipment capex:Automated cutting and sewing lines for soft signage demand capital commitments that mid-size converters defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Signage Market |
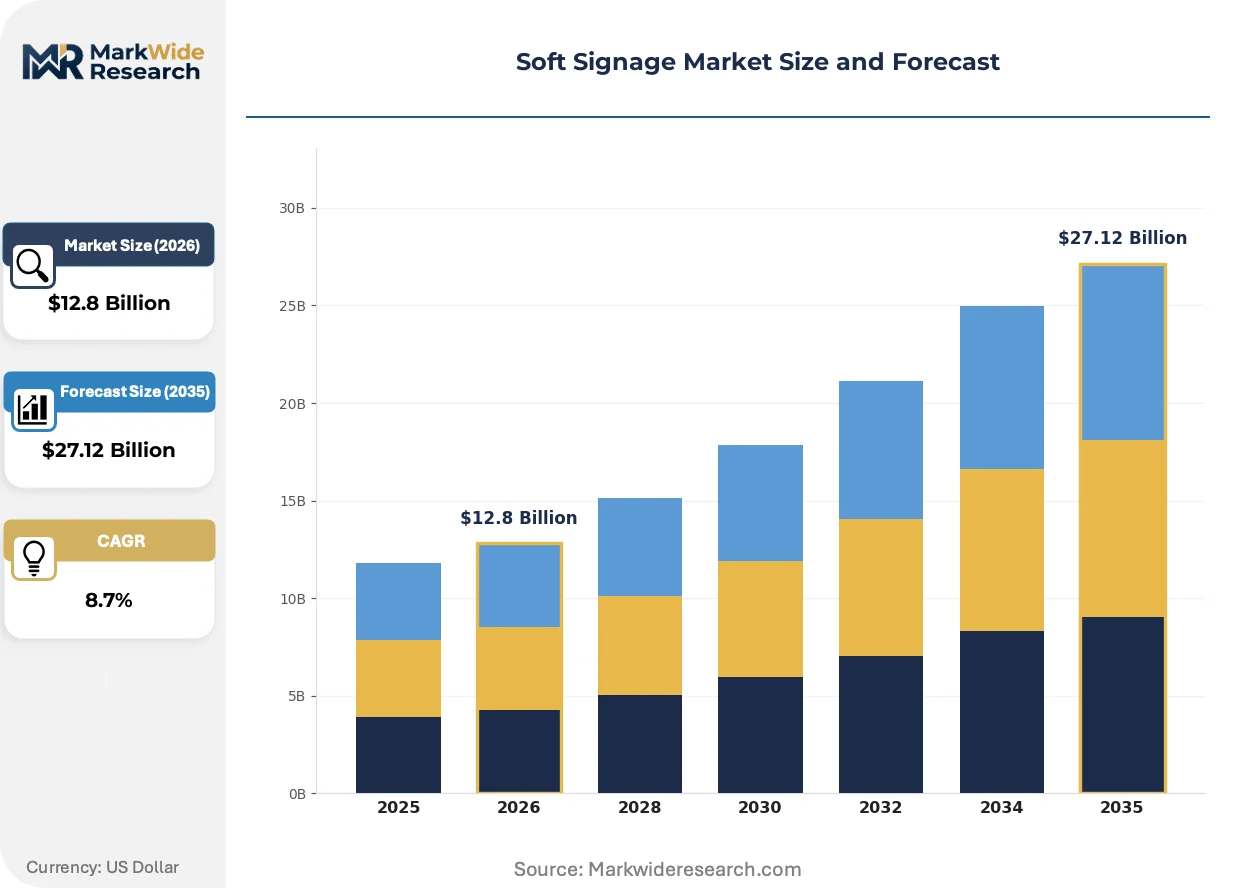
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Banners, POS Displays, Table Cloths, Backdrops Material: Fabric, Polyester, Canvas, Nylon Application: Event Marketing, Retail Promotion, Trade Shows, Indoor Displays Distribution Channel: Direct Sales, Online Retail, Distributors, Print Shops |
| Companies Covered | HP, Epson, Mimaki, Roland, Durst, Canon, Agfa-Gevaert, Kornit Digital, Gandi Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Signage Market Strategic Shifts
Hardware architecture and ink chemistry are converging to compress job turnaround times while regulatory pressure on substrate composition accelerates material substitution cycles across commercial print channels.
Single-pass inkjet printheads are modularizing production workflows for high-volume soft signage. Event marketing agencies are adopting these systems for same-day backdrop fulfillment. The technology is modularizing what were previously discrete pre-press, printing, and finishing operations into continuous production lines.
REACH restrictions on persistent organic pollutants are reshaping import qualification protocols for coated textiles. European converters now face documentation burdens that delay PVC-based substrate clearance. Photographic-quality backdrop producers are responding by accelerating woven polyester certification timelines.
Brand procurement teams are consolidating print vendor relationships around circularity credentials. Retail environment graphics buyers now bundle fabric recycling commitments with volume contracts. This preference shift is most visible in Germany, where extended producer responsibility frameworks penalize non-recoverable display materials.
Soft Signage Market Segmentation
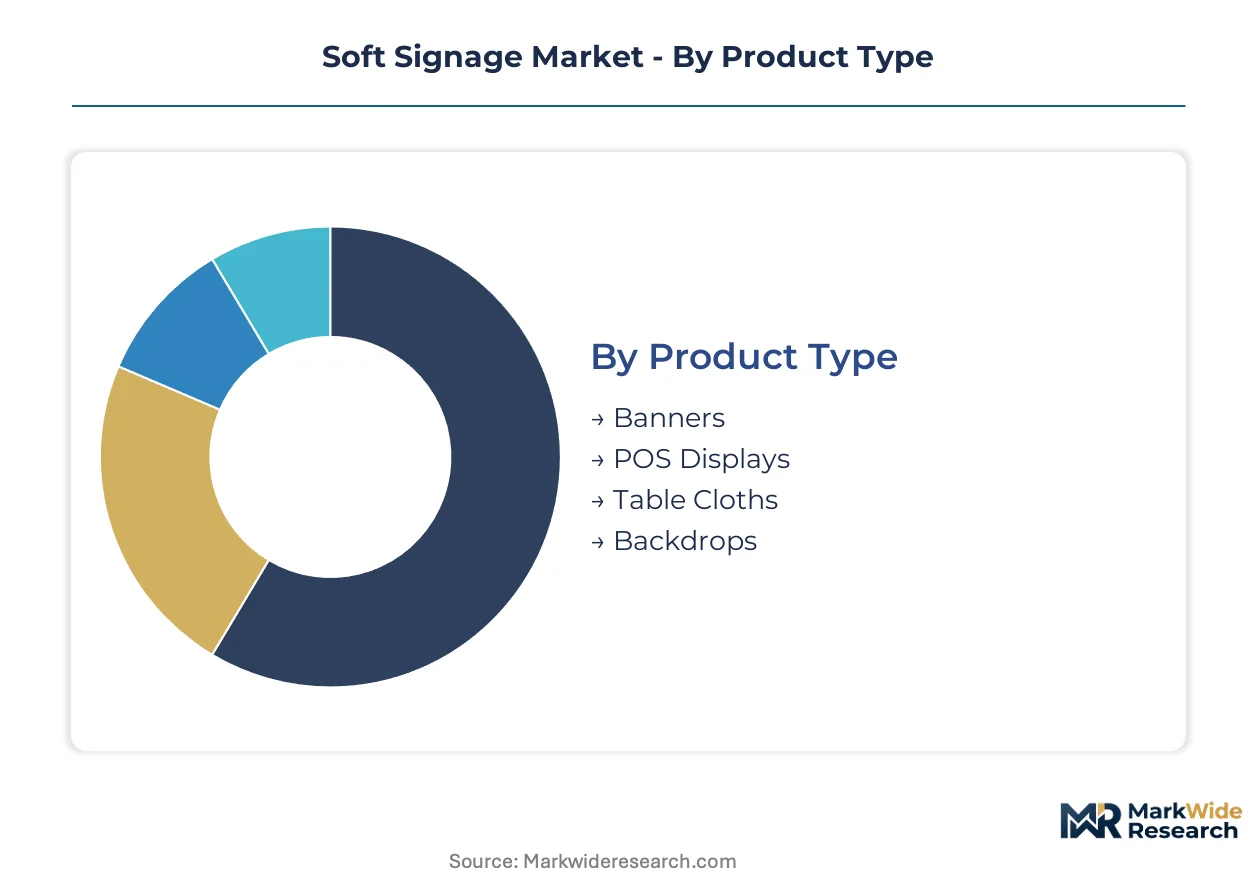
Soft signage procurement decisions hinge on display duration, transport frequency, and regulatory compliance requirements. Buyers segment demand across material durability, installation complexity, and end-use environment constraints.
Product Type:
Buyers prioritize portability and storage efficiency when selecting display formats for temporary installations.
- Banners:Woven polyester or knit textiles ranging from 90 to 300 gsm with reinforced edges and grommet finishing. Retail chains and event agencies in Germany are displacing rigid vinyl with fabric alternatives as REACH phthalate restrictions tighten import clearance timelines.
- POS Displays:Custom-finished fabric structures with tensioning hardware for shelf-edge and counter-top placement. Quick-service restaurants and cosmetics brands in tier-two Indian cities are generating first-time demand for collapsible point-of-sale systems.
- Table Cloths:Wrinkle-resistant knit polyester with dye-sub receptive coatings for hospitality and catering applications.
- Backdrops:Large-format tension fabric systems for stage and exhibition architecture requiring photographic print resolution.
Banners lead on scale; POS displays lead on momentum.
Material:
Substrate selection tracks regulatory pressure on plasticizers and recyclability certification requirements.
- Fabric:General category encompassing woven and knit textile constructions with weights calibrated to frame tension specifications.
- Polyester:Purified terephthalic acid and ethylene glycol polymerization yielding dye-sub receptive surfaces. Guangdong Province textile finishing houses are compressing lead times for export-grade woven polyester as PVC-free alternatives gain procurement preference.
- Canvas:Heavy cotton or cotton-blend substrates with matte surfaces suited to UV and latex ink reception for fine art reproduction.
- Nylon:Recycled nylon qualification programs are accelerating in Europe as extended producer responsibility frameworks penalize non-recoverable display materials.
Polyester leads on scale; recycled nylon leads on momentum.
Application:
End-use environment determines durability specifications and finishing complexity.
- Event Marketing:Reusable, collapsible fabric systems for experiential activations and temporary brand installations. Event production houses in California are prioritizing fabric over single-use vinyl as Air Resources Board VOC thresholds constrain solvent-based alternatives.
- Retail Promotion:Seasonal and campaign-based displays requiring rapid turnaround and modular hardware compatibility.
- Trade Shows:Large-format tension fabric architecture with tool-free assembly for international exhibition circuits.
- Indoor Displays:Controlled-environment graphics with lower durability requirements and premium print resolution demands.
Retail promotion leads on scale; event marketing leads on momentum.
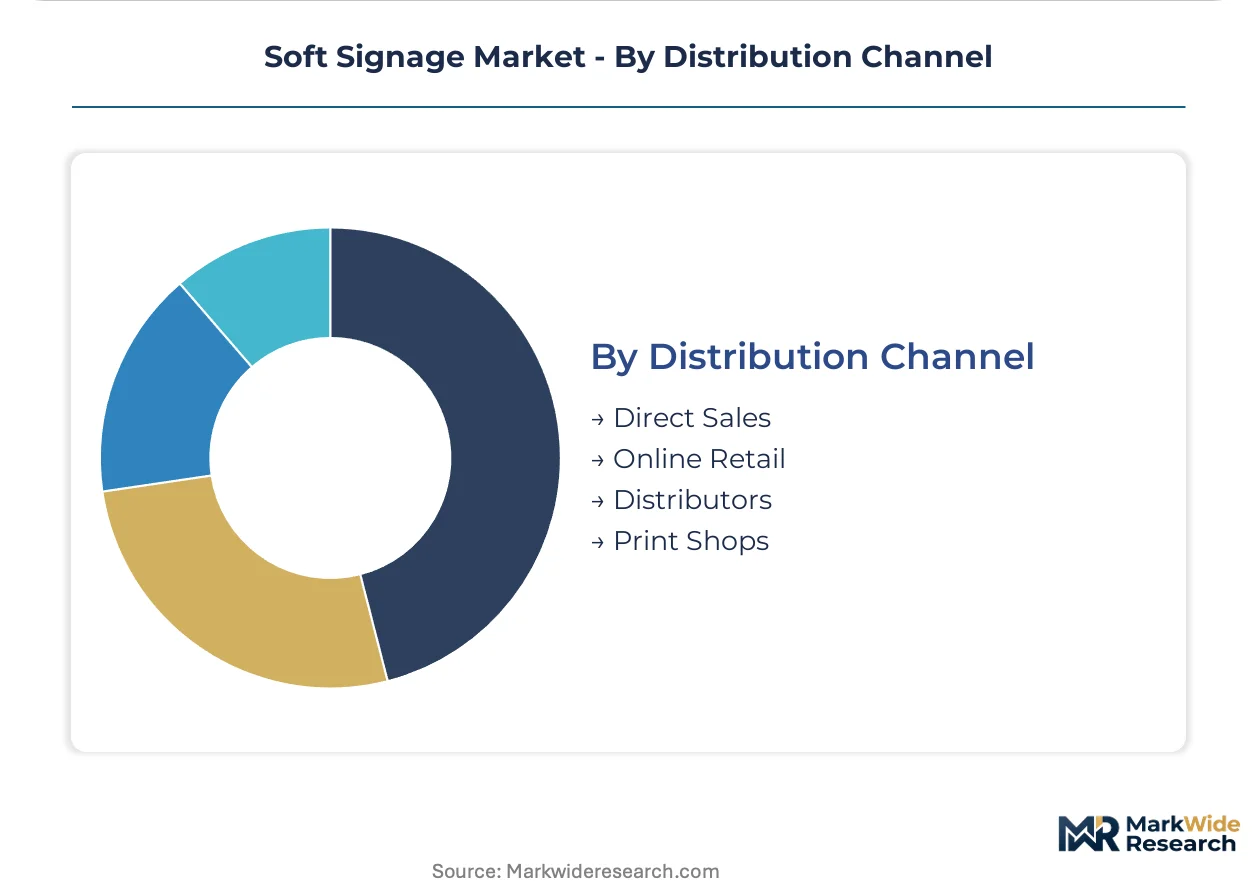
Distribution Channel:
Channel selection reflects job size, customization depth, and buyer technical sophistication.
- Direct Sales:Manufacturer-to-brand relationships for high-volume recurring programs with dedicated color management protocols.
- Online Retail:Template-driven ordering platforms serving small businesses and individual event organizers with standardized specifications.
- Distributors:Inventory-holding intermediaries providing substrate samples and hardware bundling for commercial print shops.
- Print Shops:Local service providers offering design-to-installation workflows with same-day fulfillment capabilities for urgent event marketing needs.
Print shops lead on scale; direct sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province anchors soft signage manufacturing density through its concentration of dye-sub printer OEMs and textile finishing houses that compress export lead times for global buyers.
United States
California's Air Resources Board enforces the nation's most stringent VOC emission thresholds for wide-format printing operations. EPA standards constrain solvent-based ink formulations while pushing commercial converters toward latex and UV-curable alternatives. Los Angeles and Orange County host dense clusters of event marketing agencies prioritizing fabric systems for experiential activations.
Germany
REACH phthalate restrictions on PVC-coated imports are accelerating certified polyester qualification programs among brand procurement teams. Extended producer responsibility frameworks penalize non-recoverable display materials while rewarding circularity credentials. The Rhine-Ruhr corridor concentrates textile finishing capacity serving retail environment graphics buyers across Western Europe.
China
Guangdong Province's Pearl River Delta hosts vertically integrated supply chains spanning dye-sub printer manufacturing and woven polyester finishing. MEE enforcement of dual carbon goals is reshaping energy-intensive textile production economics. Shenzhen and Dongguan export clusters dominate global supply for fabric-based banner substrates.
India
Organized retail expansion in tier-two cities is generating first-time demand for portable fabric display systems. BIS certification requirements for imported printing equipment create compliance barriers for foreign OEM market entry. Maharashtra and Gujarat host emerging print service provider networks serving quick-service restaurant and cosmetics brand customers.
United Kingdom
Event production houses in London and the Southeast are displacing rigid vinyl with reusable fabric systems for trade show architecture. CSRD disclosure requirements are pressuring corporate procurement teams to document display material circularity. The Midlands corridor concentrates dye-sub conversion capacity for European export markets.
Soft Signage Market Competitive Environment
Global majors compete with regional champions across printhead technology and ink chemistry integration. Market structure tilts toward consolidated hardware supply with fragmented downstream conversion services. Three archetypes dominate: vertically integrated ink-and-printer systems specialists, precision piezoelectric equipment manufacturers, and textile-focused workflow configurators. Dominant competitive moves include strategic partnerships for circular material recovery and geographic expansion through distributor network densification.
Within the integrated systems tier, HP exemplifies captive supply chain control spanning ink formulation and printhead architecture. Epson occupies a position emphasizing precision piezoelectric deposition for photographic-quality output requirements. Mimaki represents specialized textile printer configuration for short-run event marketing workflows. These three anchors illustrate divergent strategic postures around speed, resolution, and application specificity.
| Leading Market Players |
|---|
| HP |
| Epson |
| Mimaki |
| Roland |
| Durst |
| Canon |
| Agfa-Gevaert |
| Kornit Digital |
| Gandi Innovations |
| Others |
Value Chain & Pricing Dynamics
REACH phthalate restrictions on PVC-coated imports gate qualified supply access and premium-tier pricing power for certified polyester alternatives in European procurement channels. Brand procurement teams now bundle circularity credentials with volume contracts, compressing margins for non-compliant converters while rewarding certified suppliers with pricing premiums.
Pricing Analysis
Purified terephthalic acid and ethylene glycol cost pass-through destabilizes polyester substrate pricing, with volatility concentrated in woven textile grades. Three-tier pricing structure across REACH-certified premium, standard commercial, and economy import tiers separates qualified European supply from Guangdong export alternatives. Price differentiation hinges on certification tier and geographic delivery cost, with California event marketing agencies least price-sensitive due to Air Resources Board compliance mandates. Cost compression in economy-tier imports is intensifying as Guangdong finishing houses compete on lead time.
Supply Chain Analysis
Dual-sourcing requirements from brand procurement teams mandate multi-supplier qualification across Guangdong Province, Germany, and India for woven polyester substrates. Raw material dependencies draw from purified terephthalic acid, ethylene glycol, and dye-sub receptive coating chemistries. Single-source vulnerability concentrates in Guangdong printer OEM clusters, where MEE dual carbon enforcement reshapes energy-intensive production economics. Distribution runs through inventory-holding distributors providing substrate samples and hardware bundling for commercial print shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with REACH phthalate deadlines accelerating certified polyester qualification programs and compressing PVC-based substrate clearance timelines.
For Market Incumbents: Lock in material-recovery partnerships ahead of extended producer responsibility framework enforcement in Germany and the United Kingdom. HP and Epson should deepen backward integration into textile finishing capacity in Guangdong to defend margin capture against emerging regional challengers. Certification investment in recycled nylon qualification programs represents the priority defensive lever against PVC substitution threats. For New Entrants and Emerging Players: E-commerce template platforms serving tier-two Indian cities offer the most penetrable white-space target, with organized retail expansion generating first-time demand for collapsible POS systems. Quick-service restaurant chains and cosmetics brands in Maharashtra and Gujarat present underserved conversion opportunities. A direct-to-print-shop SaaS ordering interface with same-day fulfillment capabilities unlocks channel access without distributor network investments. For Investors and Strategic Acquirers: Roll-up economics work for regional print service providers with dye-sub profile expertise because color management capability scarcity concentrates in fragmented mid-size converters. Target acquisition archetypes include automated finishing equipment owners in the Rhine-Ruhr corridor and event marketing workflow specialists in California. Watch for Air Resources Board threshold tightening as the inflection signal accelerating latex and UV-curable conversion capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Material Recovery Partnership | Extended producer responsibility frameworks in Germany reward circularity credentials with procurement advantages. |
| Automated Finishing Line Investment | Mid-size converters defer capex commitments, creating acquisition targets for integrated players. |
| REACH Certification Acceleration | European brand procurement teams consolidate vendor relationships around qualified polyester supply. |
| Hybrid UV-Latex Ink Development | Short-run textile applications previously reserved for dye-sublimation open to new technology entrants. |
| Distributor Network Densification | Inventory-holding intermediaries in India provide substrate samples and hardware bundling for emerging print shops. |
Study Parameters
Coverage spans the United States, Germany, China, India, and the United Kingdom, with primary inputs from each regional cluster combining executive interviews with print service provider operators, brand procurement managers, textile finishing house technical directors, and dye-sub printer OEM product strategists. Secondary validation draws from EPA emission filings, ECHA REACH registration databases, China customs trade data, and BIS certification records. Bottom-up demand modeling triangulates against top-down supply capacity assessments across Guangdong Province export clusters.
Granularity-level modeling disaggregates volume and value outputs across product type, material substrate, end-use application, and distribution channel dimensions throughout the forecast period. CAGRs derive from segment-specific growth rate convergence analysis calibrated to printer utilization rate surveys and substrate import volume trajectories. Industry-specific forecast inputs include dye-sub printer shipment data from Shenzhen and Dongguan manufacturing clusters and experiential marketing budget recovery patterns from Los Angeles event production agencies.
The model assumes a particular technology adoption path; alternative pathways for single-pass inkjet modularization would alter the outlook for same-day fulfillment economics. Forecasts reflect documented assumptions regarding REACH enforcement timelines and MEE dual carbon implementation intensity. Deviation in California Air Resources Board threshold tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Asia-Pacific Digital Printing Packaging Market
Packaging Printing
Stamping Foils Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
Thermal Transfer Overprinter Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
LAMEA Label Printing Software Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Global Thermal Transfer Ribbon Market