
 Global Beneficial Insects Market | 2026-2036
Global Beneficial Insects Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beneficial Insects Market Analysis
REACH is consolidating the cost-of-entry calculus for European biocontrol suppliers, forcing smaller breeders to invest in comprehensive toxicology dossiers or exit the market entirely. Koppert leverages its Dutch greenhouse infrastructure to sustain year-round production of predatory mites and parasitoid wasps. Biobest Group NV anchors its competitive position through specialized bumblebee pollination services that dominate protected-crop systems across Belgium and Spain. Andermatt Group AG differentiates via nematode and macrobial R&D intensity, competing against chemical alternatives in Swiss and German vineyard applications.
Beneficial insects are live arthropods reared under controlled temperature, humidity, and diet protocols, typically shipped at densities of 500 to 50,000 individuals per container depending on species and application scale, deployed primarily to suppress agricultural pests or pollinate crops without synthetic chemical residues. Predatory insects occupy the largest product category due to established use in greenhouse vegetable production, while parasitoids represent the fastest-expanding segment as row-crop growers adopt precision-release protocols for lepidopteran pest management. Pollinators command premium pricing in high-value fruit and nut orchards where colony collapse disorder has intensified reliance on managed bumblebee and solitary bee species.
The EPA in the United States regulates beneficial insects as biological pesticides under FIFRA, requiring efficacy data and non-target organism assessments that lengthen registration timelines but create defensible market positions for compliant suppliers. The EU Green Deal and Farm to Fork Strategy mandate pesticide reduction targets that directly expand procurement budgets for biocontrol agents across member state agricultural ministries. China's MEE and Ministry of Agriculture are implementing dual carbon goals that favor biological inputs over synthetic chemistry in provincial pilot programs. Stakeholders must monitor how divergent regulatory timelines between North American and European approval pathways affect cross-border product portfolio decisions.
Market Dynamics
EU Green Deal pesticide reduction mandates are compressing registration timelines for biocontrol agents while concentrating production among dossier-capable breeders, reshaping competitive entry economics across the beneficial insects supply base.
Growth Catalysts
- Farm to Fork Strategy:EU member state agricultural ministries are expanding dedicated procurement budgets for biological pest control agents, directly funding grower adoption programs.
- Greenhouse vegetable production:Netherlands-based controlled-environment agriculture clusters are scaling precision-release protocols for predatory mites, creating sustained demand pull.
- Dual carbon goals:China's MEE and Ministry of Agriculture are prioritizing biological inputs over synthetic chemistry in provincial pilot programs, redirecting subsidy flows.
Market Restraints
- REACH compliance costs:Comprehensive toxicology dossier requirements are forcing smaller European breeders to exit, concentrating supply among capitalized incumbents.
- Temperature-controlled logistics:Perishable live arthropod shipments require specialized cold-chain infrastructure, limiting distribution radius and raising landed costs.
- Synthetic pheromone substitutes:Chemical mating disruption products compete directly with parasitoid wasps in orchard systems, capping pricing power.
Strategic Opportunities
- India protected cultivation:Polyhouse expansion in Maharashtra and Karnataka is creating first-mover openings for bumblebee pollination services in high-value horticulture.
- Drone-based dispersal:UAV precision-release technology is converging with macrobial biocontrol, enabling row-crop scale deployment previously limited to greenhouse settings.
- US IRA conservation funding:Agricultural climate-smart practice incentives are channeling federal dollars toward integrated pest management adoption.
Industry Challenges
- Entomological expertise scarcity:Skilled rearing technicians for parasitoid wasp colonies command premium wages, constraining production scaling.
- FIFRA registration timelines:EPA efficacy and non-target organism assessments extend multi-year approval cycles, delaying revenue recognition for new species introductions.
- Quality standardization gaps:Absence of unified viability metrics across shipping containers creates buyer uncertainty and dispute friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beneficial Insects Market |
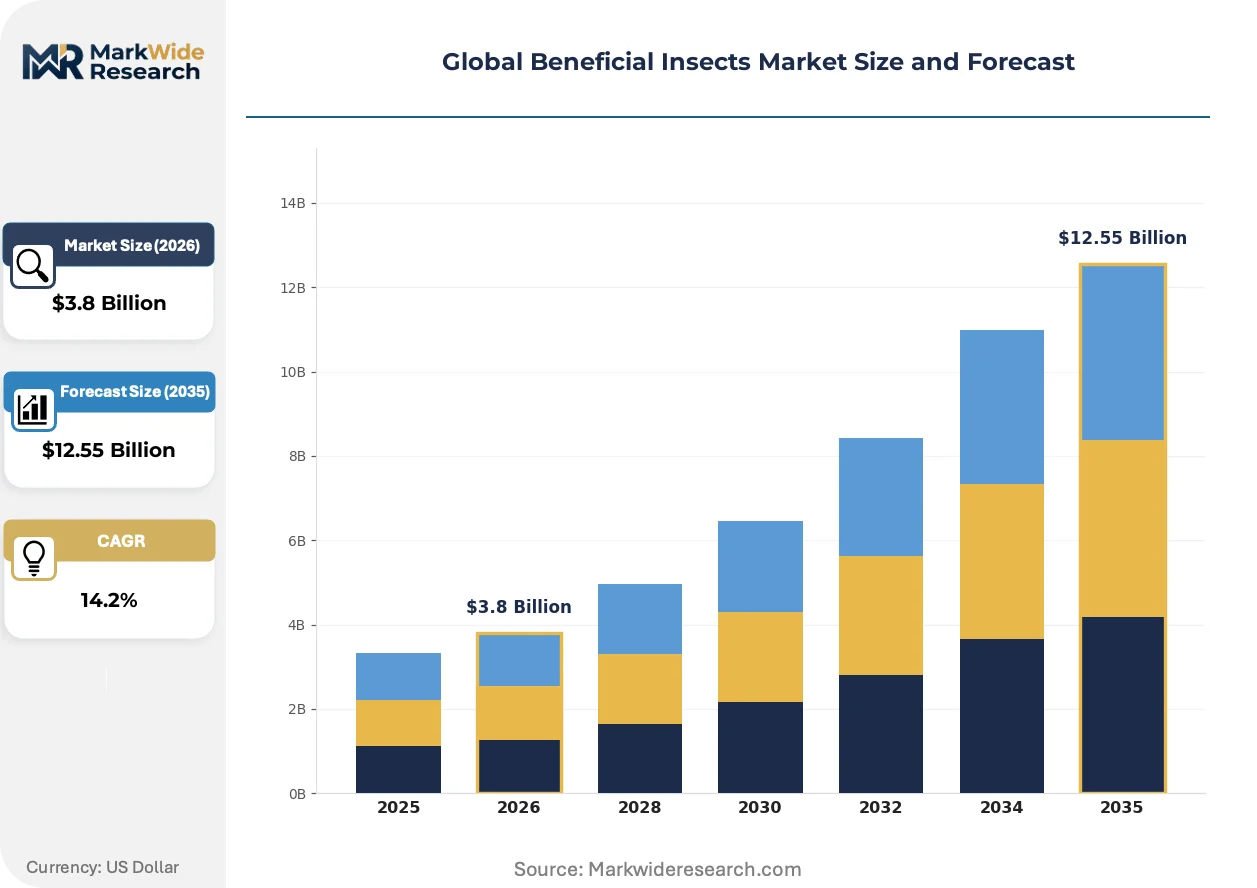
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predatory Insects, Parasitoids, Pollinators, Detrivores Application: Agricultural Pest Control, Soil Health Improvement, Crop Pollination, Ecosystem Restoration End User: Farmers, Agricultural Cooperatives, Gardeners, Researchers Distribution Channel: Online Retail, Agricultural Supply Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Bioline AgroSciences Ltd, Andermatt Group AG, Biobest Group NV, BioBee Ltd, ARBICO Organics, Koppert, Fargro Limited, BIONEMA, Applied Bionomics Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beneficial Insects Market Emerging Trajectories
Precision agriculture hardware and biological control agents are fusing into integrated systems, with automation reshaping how live beneficial insects are stored, distributed, and released at scale.
Drone-mounted dispersal systems for predatory mites and parasitoid wasps are expanding into row-crop applications previously inaccessible to beneficial insects. Corn and soybean growers in Iowa and Illinois are piloting UAV release protocols for lepidopteran pest suppression. This hardware-biocontrol convergence is expanding into broadacre agriculture, compressing the historical greenhouse-only addressable market boundary.
REACH dossier harmonization across EU member states is compressing registration friction for cross-border biocontrol trade. ECHA streamlined assessment pathways are reducing redundant toxicology submissions for predatory mites and nematode species. Specialized breeders in Belgium and Spain are responding by consolidating multi-country approval strategies, prioritizing species with transferable efficacy data packages.
Direct-to-grower digital platforms are displacing traditional agricultural distributor networks for beneficial insect procurement. Specialty crop producers in California's Central Valley are contracting straight from Dutch and Israeli breeding facilities, bypassing regional input suppliers. This channel disintermediation is most visible in high-value nut and vine crops where shipment traceability and viability guarantees dominate purchasing criteria.
Global Beneficial Insects Market Segmentation
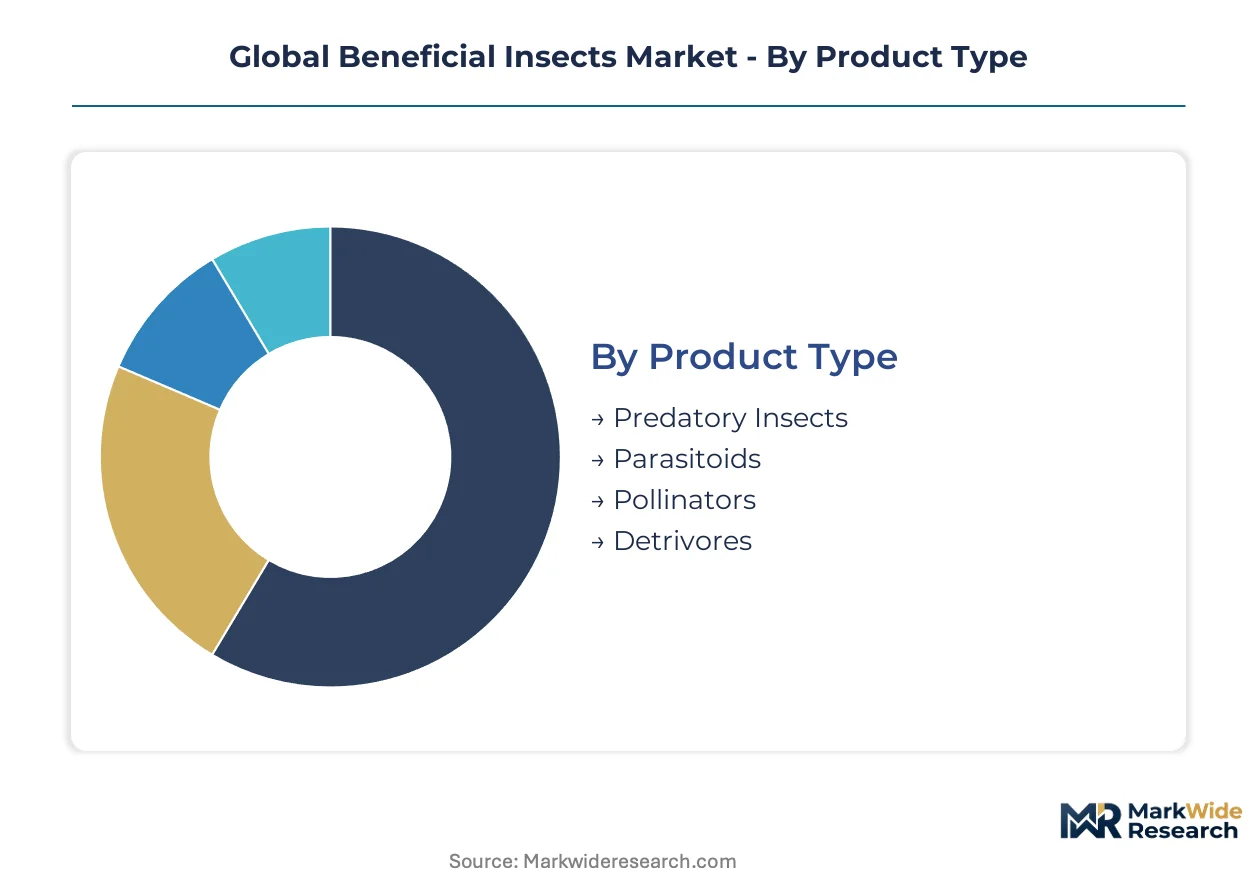
Segmentation in beneficial insects reflects divergent biological capabilities, temperature-controlled logistics requirements, and regulatory compliance burdens that shape supplier specialization and buyer procurement patterns across agricultural value chains.
Product Type:
Buyers differentiate by functional mechanism—predation versus parasitism versus pollination—each demanding distinct rearing infrastructure, shipment densities, and field deployment protocols.
- Predatory Insects:These arthropods consume pest organisms directly, with species like predatory mites reared at densities of 500 to 50,000 individuals per container depending on application scale. Demand concentrates in Netherlands greenhouse vegetable clusters where Koppert sustains year-round production using Dutch controlled-environment infrastructure.
- Parasitoids:Organisms that develop within or on host pests, requiring precise synchronization with target pest life cycles. Iowa and Illinois corn and soybean growers are piloting UAV release protocols for lepidopteran pest suppression, compressing the historical greenhouse-only market boundary.
- Pollinators:Managed bumblebee and solitary bee species command premium pricing in high-value fruit and nut orchards where colony collapse disorder has intensified reliance on biological pollination services.
- Detrivores:Decomposer organisms that break down organic matter, deployed primarily in soil health improvement applications within Swiss and German vineyard systems.
Volume sits with Predatory Insects; growth tilts toward Parasitoids.
Application:
Application scope determines shipment viability windows, with perishable live arthropod logistics favoring high-frequency, short-radius deployments over bulk long-haul distribution.
- Agricultural Pest Control:The dominant deployment mode, encompassing greenhouse and row-crop suppression of herbivorous pests through precision-release protocols. California Central Valley specialty crop growers are expanding biological pest control programs, bypassing regional distributors to contract directly from Dutch breeding facilities.
- Crop Pollination:High-value protected-crop systems across Belgium and Spain rely on Biobest Group NV's specialized bumblebee services, with managed colonies shipped to orchards during critical flowering windows.
- Soil Health Improvement:Nematode and macrobial applications in vineyard and orchard soils, where Andermatt Group AG competes against chemical alternatives through R&D intensity in nematode strain development.
- Ecosystem Restoration:Reintroduction of native beneficial species for habitat rehabilitation, requiring extended field establishment monitoring and lower shipment densities than agricultural applications.
Revenue concentrates in Agricultural Pest Control; margin expansion favors Crop Pollination.
End User:
End user scale dictates procurement channel preference, with large-volume buyers demanding viability guarantees and shipment traceability that smaller purchasers trade for convenience and lower minimum order quantities.
- Farmers:Individual growers managing diverse crop portfolios, increasingly accessing direct-to-grower digital platforms that displace traditional agricultural distributor networks for beneficial insect procurement.
- Agricultural Cooperatives:Consolidated purchasing entities that leverage volume to negotiate specialized cold-chain logistics and extended viability warranties from breeding facilities.
- Gardeners:Small-scale residential and commercial horticulture operators with low-volume, high-frequency purchase patterns suited to online retail channels.
- Researchers:Academic and government institutions conducting efficacy trials and non-target organism assessments required under EPA FIFRA and EU REACH registration pathways.
Procurement volume clusters with Agricultural Cooperatives; digital adoption spreads fastest among Farmers.
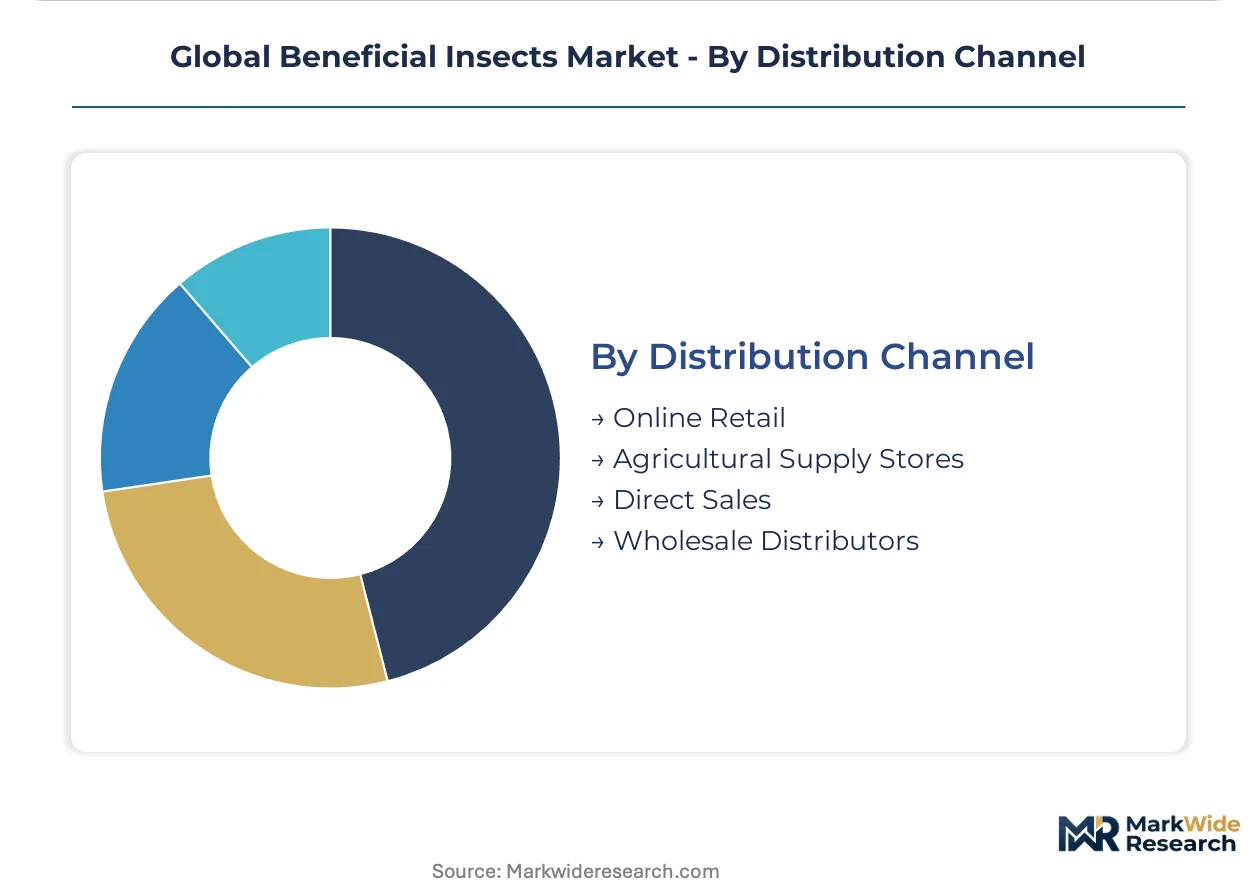
Distribution Channel:
Channel selection reflects the tension between perishability constraints requiring speed and the traceability demands of high-value crop producers.
- Direct Sales:Breeding facilities contract straight with specialty crop producers, dominating high-value nut and vine crops where shipment traceability and viability guarantees override price sensitivity. California Central Valley growers exemplify this channel shift.
- Wholesale Distributors:Traditional agricultural input suppliers losing share in beneficial insects as live arthropod specialization requirements exceed their cold-chain capabilities.
- Online Retail:Emerging channel for standardized predatory mite and nematode products with established shelf stability, serving gardeners and small farmers.
- Agricultural Supply Stores:Regional brick-and-mortar outlets with limited live inventory, primarily handling dormant or refrigerated beneficial insect formulations.
Direct Sales captures premium value; Online Retail expands addressable reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands' greenhouse corridor around Westland and North Brabant functions as the primary tax-advantaged concentration zone for beneficial insect production, with specialized economic zones offering R&D credits that anchor European supply.
United States
California Central Valley specialty crop growers expand biological pest control programs for nut and vine crops. EPA FIFRA registration requirements extend multi-year approval cycles for new biocontrol species. Direct-to-grower digital platforms enable Dutch breeding facility contracts that bypass traditional agricultural distributors.
Netherlands
Controlled-environment agriculture clusters in Westland sustain year-round predatory mite and parasitoid wasp production. EU Green Deal Farm to Fork Strategy pesticide reduction mandates expand procurement budgets for biological agents. Koppert leverages Dutch greenhouse infrastructure to maintain continuous breeding cycles.
China
Provincial pilot programs in Yangtze River Delta prioritize biological inputs over synthetic chemistry. MEE dual carbon goals redirect subsidy flows toward biocontrol adoption. Shanghai and Jiangsu greenhouse operators scale precision-release protocols for vegetable pest management.
Germany
Swiss and German vineyard applications drive nematode and macrobial demand for chemical alternative suppression. ECHA REACH dossier requirements concentrate supply among capitalized breeders capable of comprehensive toxicology submissions. Baden-Württemberg wine regions anchor specialized biocontrol procurement.
India
Polyhouse expansion in Maharashtra and Karnataka creates first-mover openings for bumblebee pollination services in high-value horticulture. National horticulture mission programs subsidize protected cultivation infrastructure. Pune and Bangalore metropolitan greenhouse clusters import managed pollinator colonies.
Global Beneficial Insects Market Vendor Landscape
Dutch producers anchor the integrated breeding tier; Israeli and Belgian specialists hold positions in parasitoid and pollination niches. Market structure concentrates among dossier-capable incumbents as REACH compliance costs force smaller European breeders to exit. Three archetypes dominate: vertically integrated greenhouse operators, R&D-intensive nematode developers, and pollination service specialists. Competitive moves center on geographic expansion into emerging protected cultivation markets and drone-based dispersal technology partnerships.
Within the integrated breeding tier, Koppert and Biobest Group NV exemplify scale-driven positions, while Andermatt Group AG occupies the specialized nematode development niche. These entities represent divergent strategic postures across the beneficial insects value chain, with geographic origins and organizational structures reflecting distinct competitive approaches to regulated agricultural input markets.
| Leading Market Players |
|---|
| Bioline AgroSciences Ltd |
| Andermatt Group AG |
| Biobest Group NV |
| BioBee Ltd |
| ARBICO Organics |
| Koppert |
| Fargro Limited |
| BIONEMA |
| Applied Bionomics Ltd |
| Others |
Supply Flow & Price Mechanics
Certification-tier divergence between REACH-compliant dossier holders and non-compliant regional breeders splits both pricing power and supply chain access across European biocontrol markets. Premium pricing attaches to suppliers with ECHA-validated toxicology packages, while spot-market arthropod traders face margin compression from restricted distribution radius and quality disputes.
Pricing Analysis
Short lead-time premiums dominate beneficial insect procurement, with Dutch greenhouse operators commanding price multiples over spot-market inventory from peripheral breeders. Three-tier pricing structure across certified-dossier, established-breeder, and spot-trader levels reflects REACH compliance status and cold-chain reliability. Cost compression in the spot tier intensifies because temperature-controlled logistics failures erode viability guarantees. Agricultural cooperatives exhibit highest price sensitivity due to volume consolidation leverage, while specialty nut and vine growers in California's Central Valley prioritize traceability over unit cost.
Supply Chain Analysis
Regional distribution centers in the Netherlands, Israel, and Belgium anchor hub-and-spoke patterns for live arthropod fulfillment, with Westland greenhouse clusters feeding satellite cold-chain nodes across EU member states. Production draws from controlled-environment facilities in the Netherlands, specialized parasitoid breeders in Israel, and emerging nematode developers in Switzerland. Single-source vulnerability concentrates in Dutch predatory mite strains that propagate year-round under artificial light protocols. Distribution runs through direct-to-grower digital platforms displacing traditional agricultural wholesalers in high-value crop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH dossier requirements is forcing smaller European breeders to exit, concentrating supply among capitalized incumbents with cross-border regulatory capabilities.
For Market Incumbents: Cement market position by deepening captive supply of temperature-controlled logistics infrastructure and accelerating ECHA dossier harmonization across parasitoid species portfolios. Synthetic pheromone substitutes in orchard systems threaten pricing power, requiring incumbents to defend through precision-release technology partnerships that chemical disruptors cannot replicate. For New Entrants and Emerging Players: Polyhouse operators in Maharashtra and Karnataka represent the most penetrable buyer archetype, with national horticulture mission subsidies creating procurement budget availability absent entrenched supplier relationships. Drone-based dispersal technology partnerships offer a specific go-to-market angle for row-crop scale deployment previously inaccessible to greenhouse-native breeding operations. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated breeding facilities possessing both REACH dossier capabilities and direct-to-grower digital platforms, given EU Green Deal procurement budget expansion as a named catalyst. Long-term viability hinges on regulatory compliance moats widening over five-to-ten year horizons. Watch for EPA FIFRA registration timeline acceleration as an inflection indicator for US market entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Harmonization | ECHA streamlined assessments reduce redundant toxicology costs for cross-border EU trade. |
| Drone-Based Dispersal Partnership | UAV precision-release technology enables Iowa corn growers to adopt parasitoid wasp protocols. |
| Direct-to-Grower Platform Launch | Digital procurement channels bypass traditional agricultural distributors in California Central Valley. |
| Cold-Chain Infrastructure Expansion | Regional distribution centers extend viable shipment radius for perishable live arthropod products. |
| Protected Cultivation Joint Venture | Polyhouse operators in Karnataka create first-mover pollination service openings for managed bumblebee colonies. |
Methodological Framework
Trade databases, regulatory filing repositories, and controlled-environment agriculture industry publications formed the secondary backbone, supplemented by primary interviews with breeding facility technical directors, agricultural cooperative procurement managers, greenhouse operations specialists, and EPA regulatory affairs consultants. Bottom-up shipment volume estimates from Dutch, Israeli, and Belgian production facilities were triangulated against top-down EU Green Deal procurement budget allocations and US IRA conservation funding flows.
Historical trendline analysis of predatory mite and parasitoid wasp shipment densities informed projection modeling across the analysis window, with segmentation dimensions including functional mechanism, application scope, end-user scale, and distribution channel type. CAGRs were derived from growth rate convergence analysis incorporating greenhouse vegetable production expansion rates, row-crop precision agriculture adoption curves, and provincial pilot program subsidy trajectories in China.
Revisions become necessary when EPA FIFRA registration timelines compress or extend beyond modeled assumptions, when REACH dossier requirements shift toxicology burden thresholds, or when temperature-controlled logistics infrastructure investments alter viable distribution radius calculations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Sustainable Air Filter Market
Environment & Sustainability
Bio Filter Market
Environment & Sustainability
Carbon Capture and Sequestration Market
Environment & Sustainability
AI in Environmental Sustainability Market
Environment & Sustainability
Green Concrete Market
Environment & Sustainability
Javelle Water Market
Environment & Sustainability
Solar Trash Compactors Market
Environment & Sustainability
Air Pollution Control Systems Market
Environment & Sustainability
ISO Certification Market
Environment & Sustainability
Middle East and Africa Water Sink Market
Environment & Sustainability
Green Building Market
Environment & Sustainability
Home Water Softener System Market
Environment & Sustainability
Carbon Capture and Utilization Market
Environment & Sustainability
Packaging Waste Recycling Market
Environment & Sustainability
Smart Water Network Market
Environment & Sustainability
Global SCADA in Water and Wastewater Management Market