
 Retail Media Platform Market | 2026-2036
Retail Media Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Media Platform Market Insights
US-based retail networks is expanding their on-site and off-site inventory pools to capture brand budgets migrating from traditional digital channels. Amazon Advertising leverages its first-party shopper graph to sustain premium CPM rates across sponsored and display formats. Walmart Connect anchors its growth through in-store digital touchpoints and connected TV extensions. Kroger Precision Marketing differentiates through loyalty-card-linked attribution that ties ad exposure to actual basket data.
A retail media platform is a technology infrastructure that enables retailers to monetize their digital properties and customer data by selling advertising inventory to brand marketers, typically integrating demand-side platforms, data management layers, and real-time bidding protocols to serve targeted ads based on purchase intent signals. The system processes billions of transaction events to build anonymized audience segments for programmatic activation. Sponsored products and display ads command the largest share of inventory value due to their direct placement at the point of purchase decision. Video ads represent the fastest-expanding format as retailers build streaming and connected TV capabilities. Self-service delivery models are gaining traction among mid-market brands seeking direct control over campaign pacing and audience selection without managed-service fees.
The US Federal Trade Commission scrutinizes data practices in retail media, while the European Union's GDPR and Digital Services Act impose consent and transparency obligations on audience targeting across the continent. China's Personal Information Protection Law restricts cross-border data flows that underpin multinational platform operations. Retailers must monitor evolving enforcement patterns and decide whether to build compliant data architectures in-house or rely on certified vendor partnerships.
Market Dynamics
Retail media platforms face a structural inflection as third-party cookie deprecation forces advertisers to reallocate budgets toward first-party data environments, concentrating demand on retailers with authenticated shopper graphs and closed-loop measurement capabilities.
Growth Catalysts
- GDPR and state-level privacy statutes:Regulatory pressure on cross-site tracking elevates retailer-owned identifiers as compliant alternatives, accelerating brand migration to on-site retail inventory.
- Connected TV integration:Retailers extending shopper data into streaming television formats capture video budgets previously reserved for broadcast and cable networks.
- Grocery retail digitization:Supermarket chains deploying in-store digital screens and app-based promotions create net-new ad inventory at the point of purchase.
Market Restraints
- Data localization mandates:China's Personal Information Protection Law restricts cross-border data flows, fragmenting multinational platform architectures and raising compliance costs.
- Attribution standardization gaps:Inconsistent measurement methodologies across retailer networks prevent unified campaign planning and budget allocation.
- Supply-side concentration:Dominant cloud infrastructure providers create vendor lock-in risks for mid-market retailers building proprietary ad stacks.
Strategic Opportunities
- Off-site programmatic expansion:Retailers activating shopper segments across the open web through clean-room integrations capture brand budgets beyond owned properties.
- Self-service platform adoption:Mid-market advertisers demand direct campaign control, creating white space for simplified interfaces without managed-service overhead.
- Commerce media convergence:Integration of retail media with payment networks and financial services unlocks closed-loop attribution across online and offline transactions.
Industry Challenges
- Data science talent scarcity:Shortage of engineers skilled in privacy-preserving machine learning slows deployment of differential privacy and federated learning systems.
- Legacy ERP integration:Retailers with decades-old inventory and customer databases face protracted timelines to connect real-time transaction feeds to ad-serving infrastructure.
- Consent management complexity:Evolving interpretations of GDPR and Digital Services Act requirements create uncertainty in audience segmentation practices across European operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Media Platform Market |
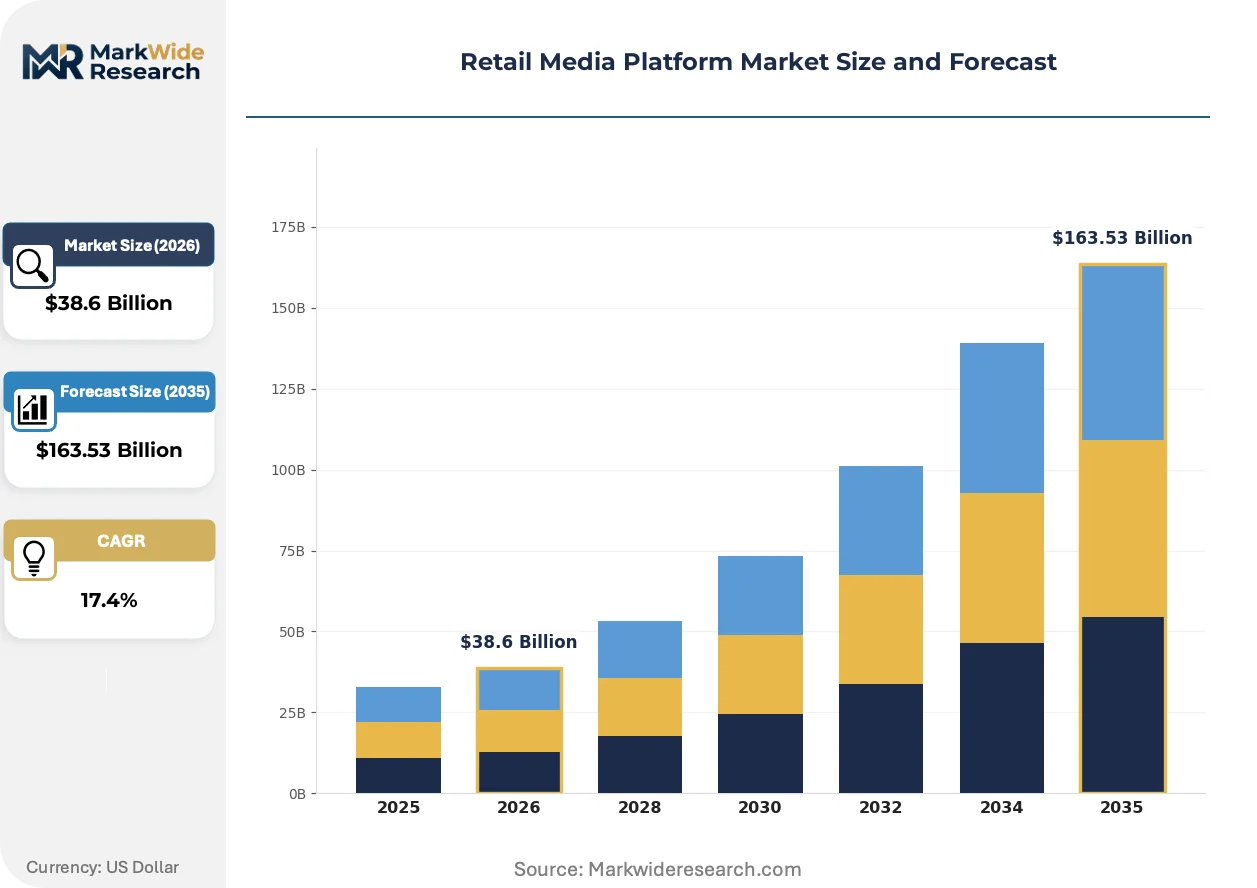
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $163.53 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Ads, Video Ads, Sponsored Products, Affiliate Marketing Technology: Programmatic Advertising, Data Management Platforms, Analytics Tools, Demand-Side Platforms End User: Brand Marketers, Retailers, Ad Agencies, E-commerce Platforms Delivery Model: Self-Service, Managed Service, Hybrid Model, Subscription-Based |
| Companies Covered | Amazon Advertising, Walmart Connect, Target Roundel, Criteo Retail Media, Instacart Ads, Kroger Precision Marketing, Albertsons Media Collective, eBay Advertising, The Trade Desk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Media Platform Market Trends and Innovations
Retail media infrastructure is undergoing rapid reconfiguration as artificial intelligence, regulatory mandates, and advertiser procurement preferences reshape how inventory is priced, targeted, and measured across digital touchpoints.
Artificial intelligence is rewriting campaign optimization workflows across retail media platforms. Machine learning models now predict purchase intent from browse patterns and basket composition in milliseconds. Mid-market brands adopting these automated bidding tools reduce manual audience segmentation labor. This compression of optimization cycles is narrowing the performance gap between self-service and managed-service delivery models.
The European Union's Digital Services Act imposes transparency obligations on algorithmic content ranking and ad targeting. Platform operators must disclose parameters governing ad auction mechanics and audience segmentation logic. Retailers with significant European traffic are restructuring data governance frameworks to satisfy audit requirements. This regulatory friction is favoring retailers with pre-existing clean-room architectures and documented data lineage.
Advertiser buying patterns are consolidating around outcome-based guarantees rather than impression-based commitments. Brand marketers now demand sales lift verification tied directly to loyalty card transactions and payment data. Retailers with closed-loop measurement capabilities command premium inventory rates. This preference shift is most pronounced in the United States and United Kingdom, where grocery and mass merchant networks have invested in attributable sales data infrastructure.
Retail Media Platform Market Segmentation
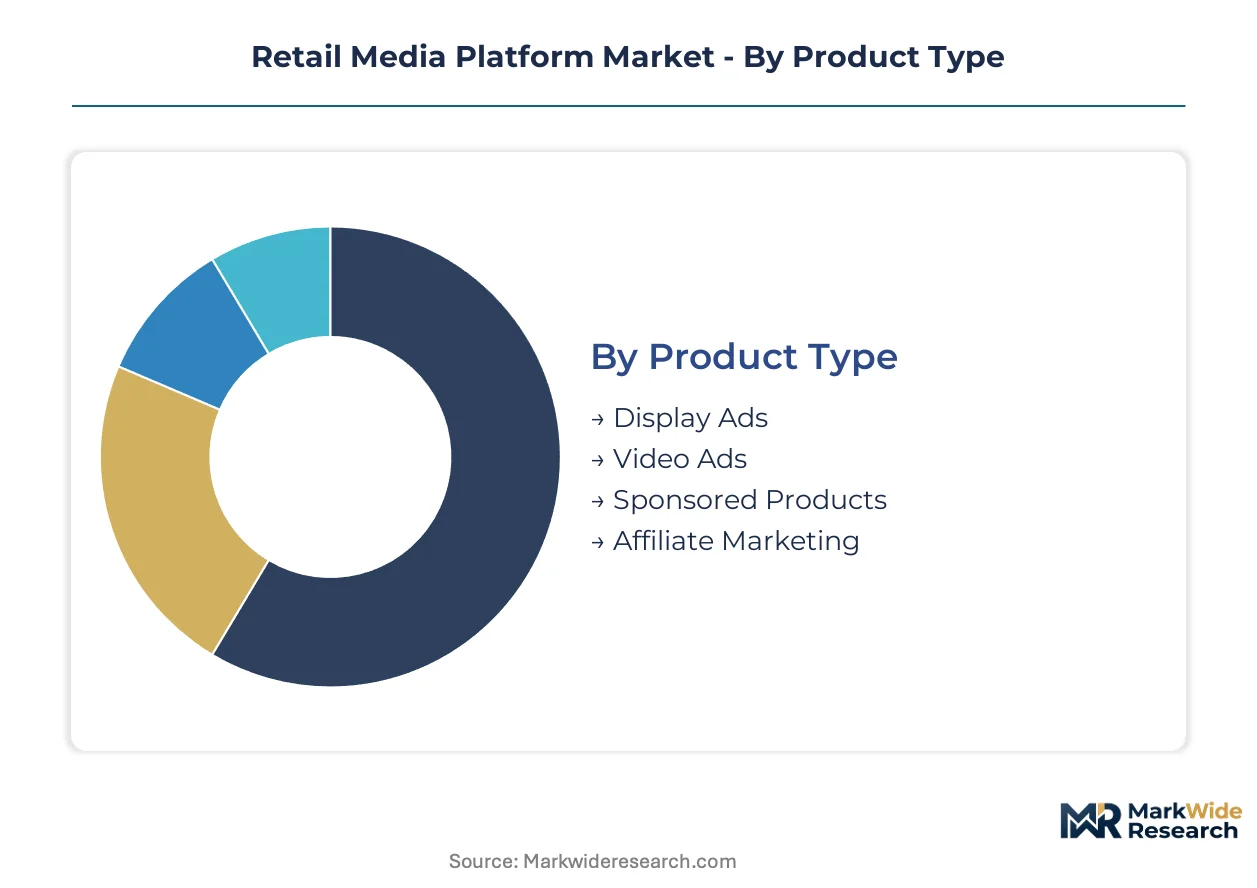
Retail media platforms segment across four critical dimensions that determine capital deployment, technical architecture, and customer acquisition strategy. Each category reflects distinct investment thresholds and margin structures that shape vendor positioning and buyer procurement patterns.
Product Type:
Capital intensity varies sharply across formats, with video infrastructure demanding the heaviest upfront outlay for encoding, streaming, and connected TV integrations.
- Sponsored Products:Keyword-triggered placements within search results and product detail pages. Retailers in the United States and United Kingdom monetize these units through auction-based pricing tied to purchase intent signals. Grocery chains leverage loyalty-linked attribution to justify premium rates.
- Video Ads:In-stream and connected TV inventory requiring substantial encoding infrastructure and publisher partnerships. Demand concentrates among mass merchants extending shopper data into streaming television formats previously reserved for broadcast networks. Supply-side investment in ad servers and content delivery networks runs highest here.
- Display Ads:Banner and native placements across retailer-owned properties.
- Affiliate Marketing:Performance-based partnerships with third-party publishers.
Most installed capacity flows through Sponsored Products. Expansion is steepest in Video Ads.
Technology:
Architecture choices divide vendors between those building proprietary stacks and those licensing modular components, with implications for data sovereignty and integration timelines.
- Programmatic Advertising:Real-time bidding infrastructure processing billions of impression auctions daily. Retailers in China face fragmentation under Personal Information Protection Law restrictions on cross-border data flows, forcing localized stack deployments.
- Data Management Platforms:Customer data unification layers segmenting audiences from transaction histories and browse patterns. European deployments require GDPR-compliant consent frameworks and documented data lineage for Digital Services Act audits.
- Demand-Side Platforms:Buyer-facing interfaces for campaign planning and budget allocation.
- Analytics Tools:Measurement and attribution dashboards closing the loop between ad exposure and sales outcomes.
Programmatic Advertising absorbs the largest share of R&D expenditure. Data Management Platforms are climbing the fastest as privacy regulations harden.
End User:
Procurement sophistication and budget scale diverge substantially across buyer types, shaping platform feature roadmaps and service model design.
- Brand Marketers:Consumer packaged goods advertisers migrating budgets from traditional digital channels to first-party retail environments. United States-based brands prioritize closed-loop measurement tying ad exposure to loyalty card transactions and actual basket data.
- Retailers:Grocery chains and mass merchants building in-house monetization capabilities. Kroger and Walmart anchor North American investment in on-site and off-site inventory expansion.
- Ad Agencies:Intermediaries managing cross-retailer campaign orchestration.
- E-commerce Platforms:Pure-play marketplaces integrating advertising into transaction flows.
Brand Marketers command the largest aggregate spending. Retailers are gaining share fastest as vertical integration accelerates.
Delivery Model:
Service architecture determines customer acquisition costs and lifetime value profiles, with self-service models promising scale at lower marginal expense.
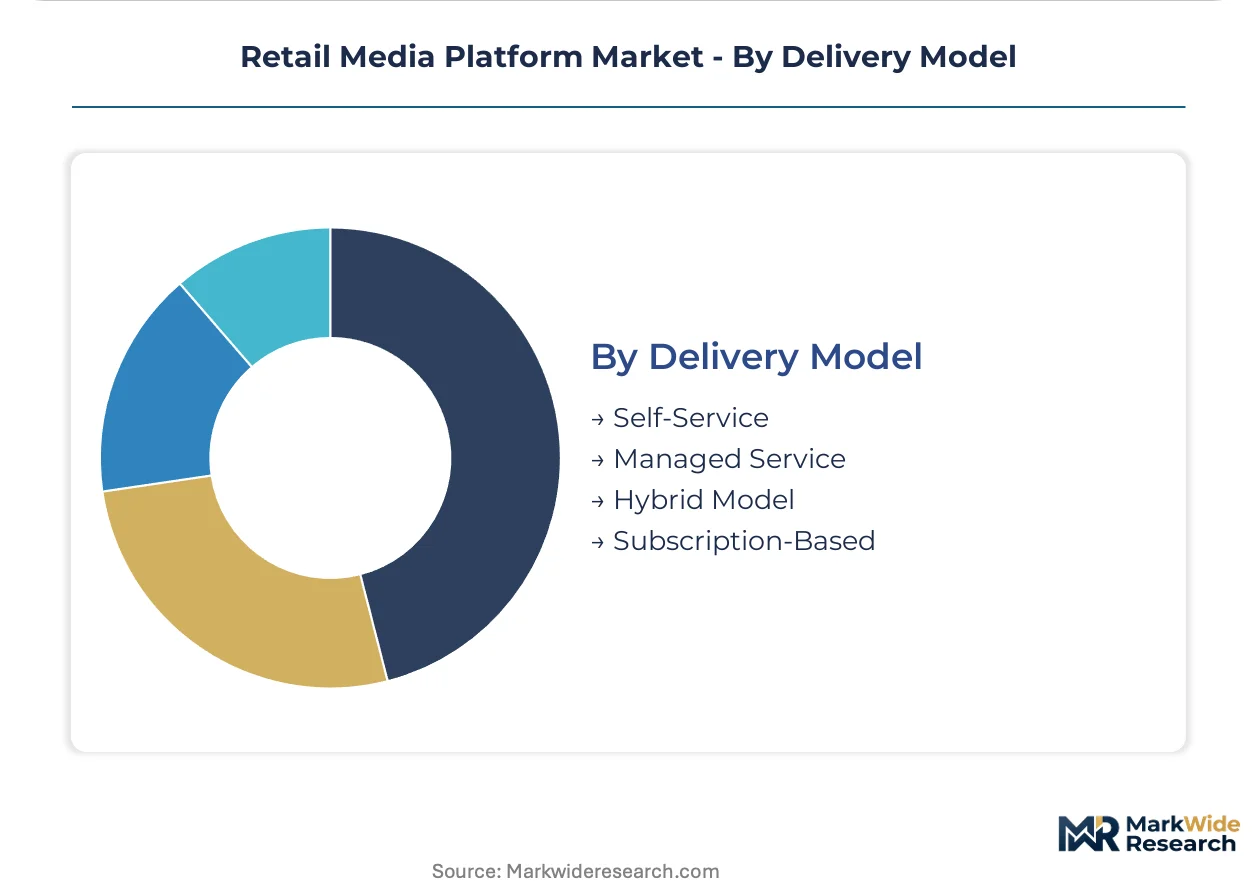
- Self-Service:Direct advertiser access to campaign building, audience selection, and pacing controls. Mid-market brands in the United States and United Kingdom adopt these interfaces to eliminate managed-service fees and compress optimization cycles through automated bidding tools.
- Managed Service:White-glove campaign execution by platform operator teams.
- Hybrid Model:Tiered support combining self-service tooling with strategic consulting.
- Subscription-Based:Fixed-fee access to platform capabilities decoupled from media spend.
Managed Service still processes the majority of transaction value. Self-Service is expanding most quickly as procurement preferences shift toward direct control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium CPM rates through authenticated shopper graphs, while China fragments under data localization mandates that force multinational platforms into costly parallel architectures.
United States
Walmart Connect and Kroger Precision Marketing anchor North American investment through in-store digital touchpoints and loyalty-linked attribution systems. The FTC scrutinizes data practices under Section 5 of the FTC Act, creating compliance friction for audience targeting methodologies. Chicago and Bentonville host concentrated engineering talent pools building real-time bidding infrastructure for grocery and mass merchant networks.
China
Domestic e-commerce platforms monetize transaction flows through closed-loop ecosystems insulated from cross-border data restrictions. The Personal Information Protection Law mandates localized storage of consumer behavior data, compelling multinational retailers to deploy separate technology stacks. Alibaba and JD.com anchor platform development in Hangzhou and Beijing, where regulatory sandboxes test compliance frameworks for programmatic advertising.
United Kingdom
Tesco and Sainsbury's retail media networks capture brand budgets migrating from deprecating third-party cookie environments. The Information Commissioner's Office enforces GDPR consent requirements through binding corporate rules and documented data lineage audits. London's ad-tech cluster concentrates demand-side platform engineering and clean-room architecture development for European market entry.
Germany
Retailers with dense brick-and-mortar footprints digitize in-store screens and app-based promotions to create attributable ad inventory at purchase points. The Federal Data Protection Act transposes GDPR requirements into national enforcement frameworks with strict interpretation of legitimate interest bases for processing. Berlin and Munich host data management platform vendors specializing in privacy-preserving audience segmentation for automotive and electronics advertisers.
Japan
Convenience store chains and department store operators build first-party data assets from loyalty programs and mobile payment integration. METI guidelines on data portability and consumer protection shape platform architecture decisions for cross-retailer audience activation. Tokyo's Roppongi and Shibuya districts concentrate ad-tech engineering talent developing machine learning models for predictive purchase intent scoring.
Retail Media Platform Market Competitive Landscape
United States producers anchor the premium tier through closed-loop measurement capabilities; European specialists hold compliance-driven positioning through pre-audited data governance frameworks. The vendor base stratifies across three tiers: dominant cloud-backed retail networks, mid-market self-service platforms, and regional grocery cooperative systems. Strategic archetypes include authenticated-data aggregators, in-store digitization specialists, and off-site programmatic extenders. Competitive moves concentrate on M&A for loyalty data assets and strategic partnerships for connected TV inventory access.
Within the dominant retail network tier, Amazon Advertising exemplifies the authenticated-data aggregator archetype through its first-party shopper graph infrastructure. Walmart Connect occupies a position bridging in-store digitization with off-site programmatic extension into streaming television formats. Criteo Retail Media represents the independent technology vendor archetype, sitting within mid-market retailer enablement through modular demand-side and data management platform licensing.
| Leading Market Players |
|---|
| Amazon Advertising |
| Walmart Connect |
| Target Roundel |
| Criteo Retail Media |
| Instacart Ads |
| Kroger Precision Marketing |
| Albertsons Media Collective |
| eBay Advertising |
| The Trade Desk |
| Others |
Pricing and Supply Chain Analysis
Authenticated-data premium tiers diverge sharply from commodity programmatic inventory, with closed-loop measurement capabilities commanding substantial rate premiums while undifferentiated display placements face compression. This bifurcation concentrates supply chain investment in first-party data infrastructure and clean-room architectures that justify higher CPMs, while marginal inventory relies on outsourced ad-serving and third-party verification layers.
Pricing Analysis
Distributor margin layers in retail media compress as self-service interfaces disintermediate agency markups and direct advertiser access becomes standard. Auction-based pricing for sponsored products dominates, with rate differentiation driven by loyalty-linked attribution depth and off-site programmatic extension capabilities. Pricing pressure stems from mid-market retailer platform proliferation expanding inventory supply faster than brand budget migration. Brand marketers with closed-loop sales verification exhibit lowest price sensitivity, while performance advertisers without first-party data assets drive commodity-tier competition.
Supply Chain Analysis
Regional distribution center patterns for cloud infrastructure concentrate supply in the United States, Ireland, and Singapore, where hyperscaler data centers anchor real-time bidding latency requirements. Platform technology draws from specialized ad-serving hardware, privacy-preserving machine learning frameworks, and connected TV encoding pipelines. Single-source vulnerability runs through dominant cloud providers, creating lock-in risk for mid-market retailers building proprietary stacks. Distribution runs through API-first integrations with demand-side platforms and direct publisher partnerships for off-site inventory extension.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail media platforms offer margin expansion through automated campaign optimization compressing service delivery costs, while outcome-based pricing models capture premium rates from verification-hungry brand marketers.
For Market Incumbents: Extend closed-loop measurement capabilities into streaming television and payment network partnerships before challenger retailers replicate Kroger's loyalty-card-linked attribution. Defend position by deepening clean-room architectures that satisfy Digital Services Act audit requirements in European operations. Prioritize engineering talent acquisition in privacy-preserving machine learning to maintain differential privacy deployment lead. For New Entrants and Emerging Players: Self-service platform interfaces represent the most penetrable entry vector, as mid-market brands seek direct campaign control without managed-service overhead. Target grocery cooperative systems and regional pharmacy chains lacking in-house ad-tech engineering. Accelerate market entry through white-label licensing of modular demand-side platforms rather than full-stack development. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented mid-market retailers lack capital to build proprietary first-party data infrastructure. Long-term viability favors platforms with authenticated shopper graphs and documented data lineage for regulatory audit. Acquisition target archetypes include loyalty data aggregators and in-store digital screen networks. Watch for inflection when outcome-based guarantees displace impression-based commitments as standard procurement terms.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Room Architecture Deployment | Enables GDPR-compliant audience activation for European brand budgets. |
| Connected TV Inventory Partnership | Captures video advertising spend migrating from broadcast networks. |
| Self-Service Platform Launch | Reduces customer acquisition costs for mid-market advertiser segments. |
| Loyalty Data Asset Acquisition | Closes attribution loops between ad exposure and actual basket transactions. |
| Payment Network Integration | Unlocks offline transaction attribution for comprehensive sales lift verification. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with retail media platform executives, brand marketer procurement leads, ad-tech engineering directors, and grocery chain monetization officers. Secondary validation draws from SEC filings of retail networks, hyperscaler infrastructure disclosure reports, GDPR enforcement bulletins, and programmatic advertising trade data. Bottom-up segment sizing triangulates against top-down market aggregation.
Granularity-level modeling deploys product type, technology architecture, end-user procurement sophistication, and delivery model service intensity as core segmentation dimensions. CAGRs derive from fitted growth curves calibrated to historical platform adoption rates and privacy regulation enforcement timelines. Forecast inputs incorporate retail digitization capex cycles and third-party cookie deprecation schedules.
The model assumes a particular technology adoption path; alternative pathways for privacy-preserving federated learning would alter the outlook if deployment timelines accelerate. Forecasts reflect stated assumptions on regulatory enforcement intensity and cloud infrastructure concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Reinforcement Geosynthetics Market
Others
Manometers Market
Others
US Quantum Computing Market
Others
Air Purification Systems Market
Others
Italy Smart Home Market
Others
Agitation System Market
Others
Europe Battery Packaging Market
Others
Canada Feed Additives Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
North America Video Conferencing Hardware Market
Others
Military Sensors Market
Others
Bird Food Market
Others
Storage Dewar and Dry Shipper Market
Others
Global Molded Plastics Market
Others
ASEAN Smart Homes Market
Others
Metaverse Market