
 Dew Point Apparatus Market | 2026-2036
Dew Point Apparatus Market Size, Share, and Industry Trends Forecast 2026-2036
Dew Point Apparatus Market Outlook
Direct-to-plant technical service channels is tilting toward integrated sensor vendors with embedded calibration networks. Vaisala leverages its Helsinki-based metrology heritage to sustain premium positioning in pharmaceutical-grade installations. Michell Instruments anchors European process industries through specialized chilled-mirror reference systems. AMETEK competes across North American utility and pipeline sectors with ruggedized field-deployable units.
A dew point apparatus measures the temperature at which air becomes saturated with water vapor, typically employing chilled-mirror, capacitive polymer, or optical absorption techniques achieving detection thresholds of −80°C frost point in critical applications. Portable units lead volume shipments for facility audits and spot-check compliance, while online installations capture the fastest growth as continuous monitoring replaces manual sampling in semiconductor and battery dry rooms. Capacitive technology dominates mid-range industrial applications for its balance of drift stability and cost, though optical methods gain ground where non-contact measurement eliminates sensor contamination risks in aggressive chemical environments.
FDA's process analytical technology guidelines and EMA Annex 1 revisions compel pharmaceutical manufacturers to validate environmental monitoring with traceable dew point documentation, directly expanding demand for laboratory-grade reference instruments. EPA emissions compliance and OSHA workplace exposure limits further shape industrial procurement specifications across manufacturing and environmental monitoring end uses. Stakeholders must weigh calibration traceability against total cost of ownership as regulatory bodies tighten audit frequencies and data-integrity requirements.
Market Dynamics
Continuous monitoring mandates from pharmaceutical regulators are compressing replacement cycles for manual dew point sampling equipment, forcing facility operators to validate sensor networks with traceable calibration documentation.
Growth Catalysts
- EMA Annex 1 Revision:Pharmaceutical cleanroom operators in Germany and Switzerland face expanded environmental monitoring requirements. Calibrated dew point sensors now require documented traceability for sterile manufacturing compliance.
- Petrochemical corridor concentration:US Gulf Coast process operators protect billion-dollar streams from corrosion damage. Humidity control failures trigger catastrophic contamination losses.
- Semiconductor dry room expansion:Battery manufacturing facilities deploy online monitoring systems. Continuous measurement replaces manual spot-checking for moisture-sensitive electrode production.
Market Restraints
- Calibration infrastructure scarcity:National metrology institutes maintain limited frost-point generation capacity. Lead times for ISO 17025-traceable certificates extend operational downtime.
- Chilled-mirror consumables concentration:Precision mirror coatings and platinum resistance thermometers depend on specialized European suppliers. Input cost volatility pressures reference instrument margins.
- Capacitive polymer drift limitations:Mid-range industrial sensors require annual recalibration against primary standards. Long-term stability gaps restrict deployment in unmanned remote installations.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO alignment with PIC/S guidelines drives cleanroom instrumentation upgrades. Domestic vaccine production facilities represent underpenetrated demand.
- Optical absorption convergence:Non-contact measurement eliminates sensor contamination in aggressive chemical environments. TDLAS techniques penetrate chlorine and acid gas processing.
- Embedded calibration networks:Sensor vendors integrate automated drift correction through cloud-connected reference loops. Service revenue models displace transactional hardware sales.
Industry Challenges
- Metrology technician scarcity:Frost-point calibration requires specialized thermometry expertise. Workforce gaps constrain service network expansion for field-deployable units.
- Legacy system integration friction:Existing SCADA architectures lack digital interfaces for smart sensor protocols. Retrofit costs delay continuous monitoring adoption in brownfield facilities.
- Data integrity audit preparation:FDA 21 CFR Part 11 compliance demands electronic record validation. Documentation burden extends procurement cycles for laboratory-grade instruments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dew Point Apparatus Market |
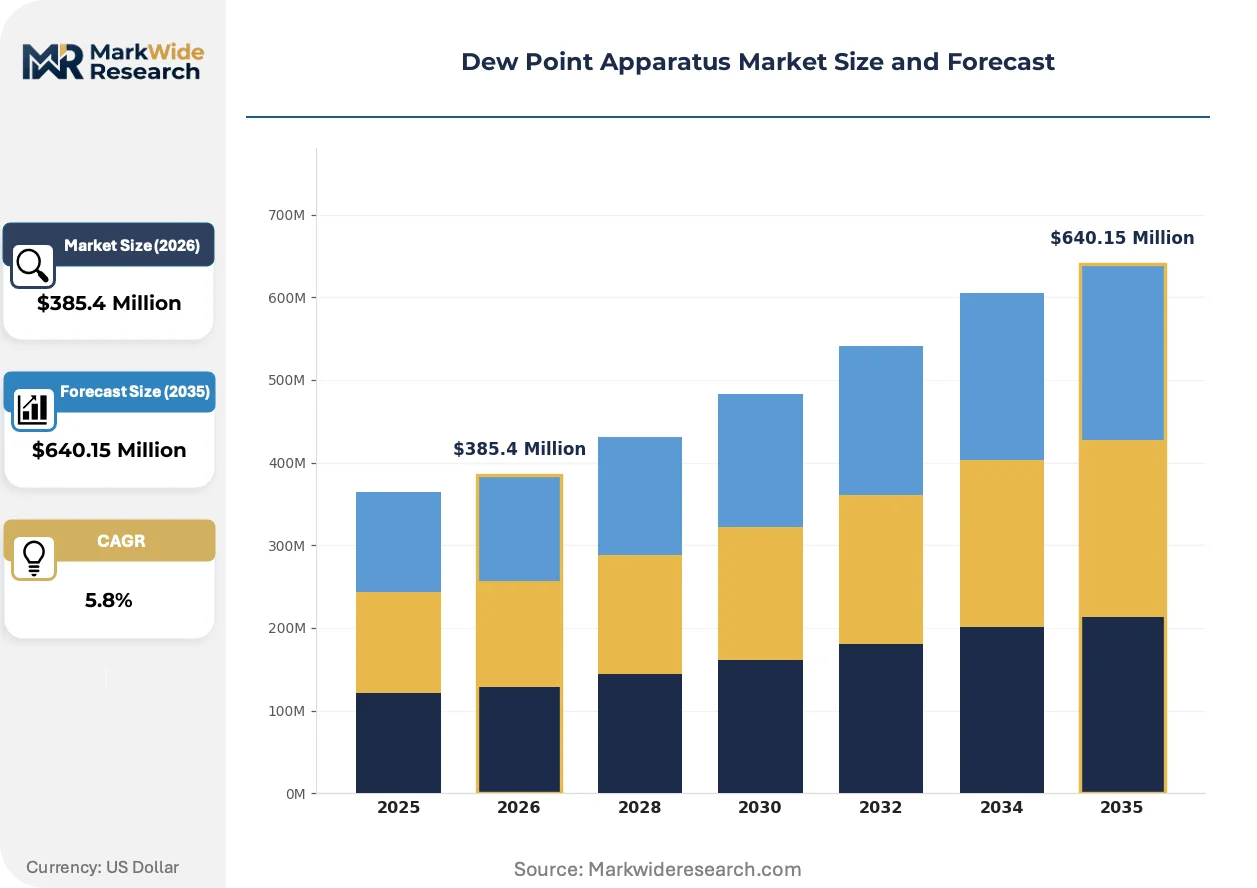
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Benchtop, Online, Laboratory Technology: Capacitive, Resistive, Optical, Thermoelectric End User: Manufacturing, Pharmaceuticals, Food & Beverage, Environmental Monitoring Application: Indoor Air Quality, Industrial Processes, HVAC Systems, Research |
| Companies Covered | Vaisala, Edgetech Instruments, Michell Instruments, AMETEK, COSA Xentaur, CS Instruments, Testo, E+E Elektronik, LI-COR Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dew Point Apparatus Market Strategic Shifts
Measurement modality convergence and regulatory data-integrity mandates are restructuring how dew point instrumentation is specified, deployed, and monetized across process industries.
Optical absorption spectroscopy is collapsing the performance gap between contact and non-contact measurement in corrosive chemical processing. Chlor-alkali and acid gas facilities adopt tunable diode laser absorption spectroscopy to eliminate sensor degradation. Maintenance intervals extend from quarterly to annual cycles, compressing total cost of ownership for aggressive environment applications.
REACH restrictions on perfluorinated compounds are forcing refrigerant transitions in chilled-mirror reference systems. European process industries face compressed timelines to validate alternative cooling fluids in primary standards. German calibration laboratories accelerate qualification programs for hydrofluoroolefin-based frost-point generators ahead of F-Gas Regulation phase-down deadlines.
Service unbundling is fragmenting traditional vendor-customer relationships in North American utility sectors. Pipeline operators separate hardware procurement from calibration contracts, soliciting third-party metrology providers. Competitive bidding for ISO 17025-traceable certificates intensifies price pressure on integrated sensor vendors.
Dew Point Apparatus Market Segmentation
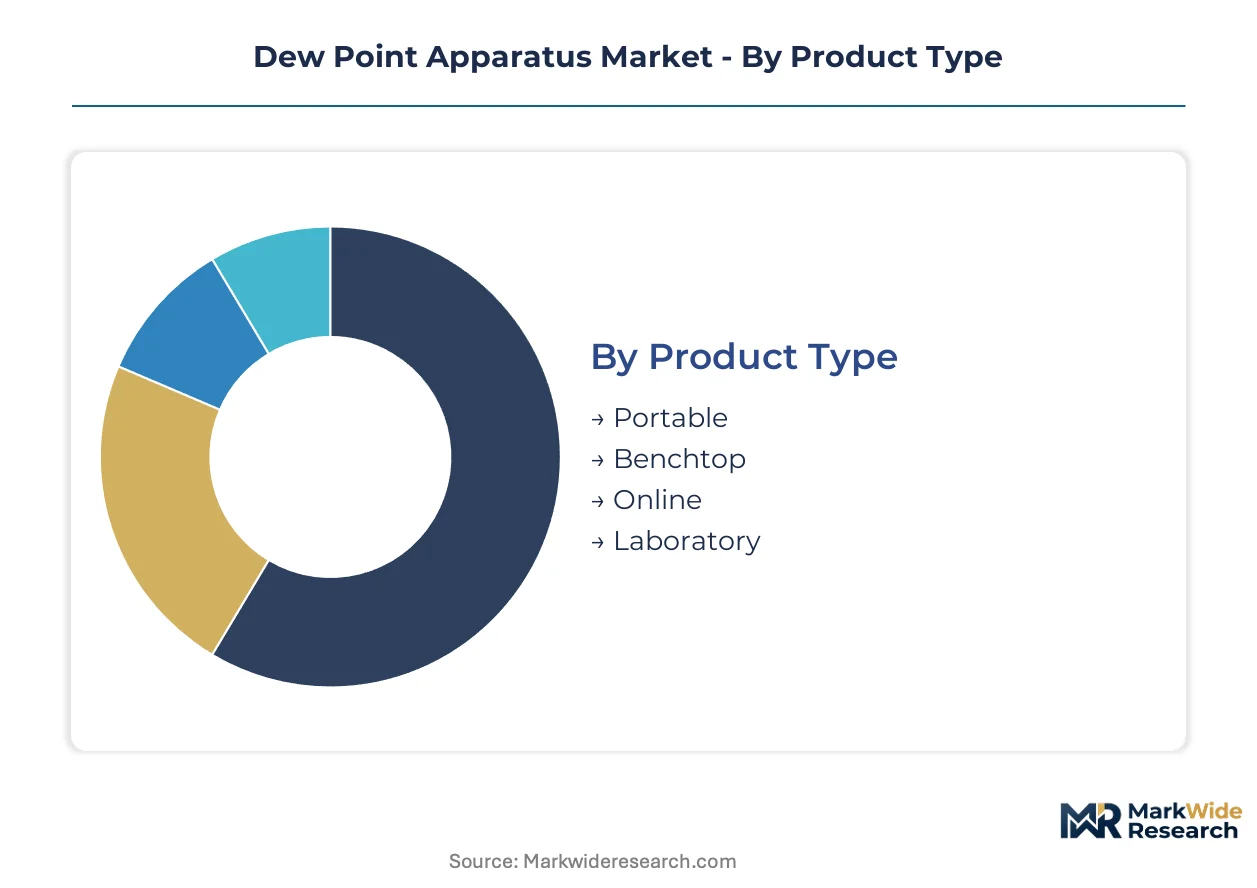
Segmentation in dew point instrumentation reflects divergent equipment lifecycles and calibration burdens across deployment contexts. Procurement patterns split sharply between mobile audit tools and permanently installed process sensors with distinct replacement economics.
Product Type:
Portable units turn over fastest with 3-5 year replacement cycles driven by field wear, while laboratory reference systems operate 10-15 years with periodic recertification.
- Portable:Handheld battery-powered units deliver spot-check capability for facility audits and compliance verification. Pharmaceutical cleanroom operators in Germany deploy these for EMA Annex 1 documentation gaps between fixed sensor networks.
- Online:Permanently installed transmitters enable continuous moisture monitoring in process streams. Battery electrode dry rooms and semiconductor fabrication facilities drive fastest expansion as manual sampling phases out.
- Benchtop:Laboratory-grade instruments serve quality control laboratories with moderate throughput requirements.
- Laboratory:Primary reference standards anchor calibration chains for national metrology traceability.
Portable units dominate installed base across industrial maintenance departments. Online systems represent where expansion concentrates for regulatory-driven continuous monitoring mandates.
Technology:
Cost tiers stratify sharply between commodity polymer sensors and precision primary standards with order-of-magnitude price spreads.
- Capacitive:Polymer-based sensors balance drift stability against unit economics for mid-range industrial applications. Petrochemical corridor operators on the US Gulf Coast specify these for billion-dollar stream protection where annual recalibration is operationally acceptable.
- Optical:Tunable diode laser absorption spectroscopy eliminates sensor contact with process media. Chlor-alkali and acid gas processors adopt these to extend maintenance intervals from quarterly to annual cycles in corrosive environments.
- Resistive:Aluminum oxide sensors serve compressed air and dryer applications with moderate accuracy requirements.
- Thermoelectric:Chilled-mirror systems provide fundamental frost-point measurement traceable to SI units.
Capacitive technology commands volume shipments through manufacturing and HVAC sectors. Optical methods are climbing the fastest as chemical processors seek contamination-immune measurement.
End User:
Customer type determines specification rigor and documentation burden, with pharmaceutical and environmental regulators imposing divergent data-integrity requirements.
- Manufacturing:Process industries deploy dew point control to prevent corrosion, contamination, and product quality degradation. Automotive paint lines and plastics extrusion facilities drive consistent replacement demand for production-critical humidity management.
- Pharmaceuticals:Sterile manufacturing mandates under EMA Annex 1 and FDA process analytical technology guidelines require validated environmental monitoring with traceable calibration documentation. Swiss and German cleanroom operators face compressed procurement cycles for documented sensor networks.
- Food & Beverage:Packaging atmosphere control and cold chain monitoring specify moisture measurement for shelf-life optimization.
- Environmental Monitoring:Atmospheric research and emissions compliance applications demand laboratory-grade reference instruments with national metrology traceability.
Manufacturing holds the broadest installed base across process sectors. Pharmaceuticals is gaining share fastest as Annex 1 revisions force instrumentation upgrades.
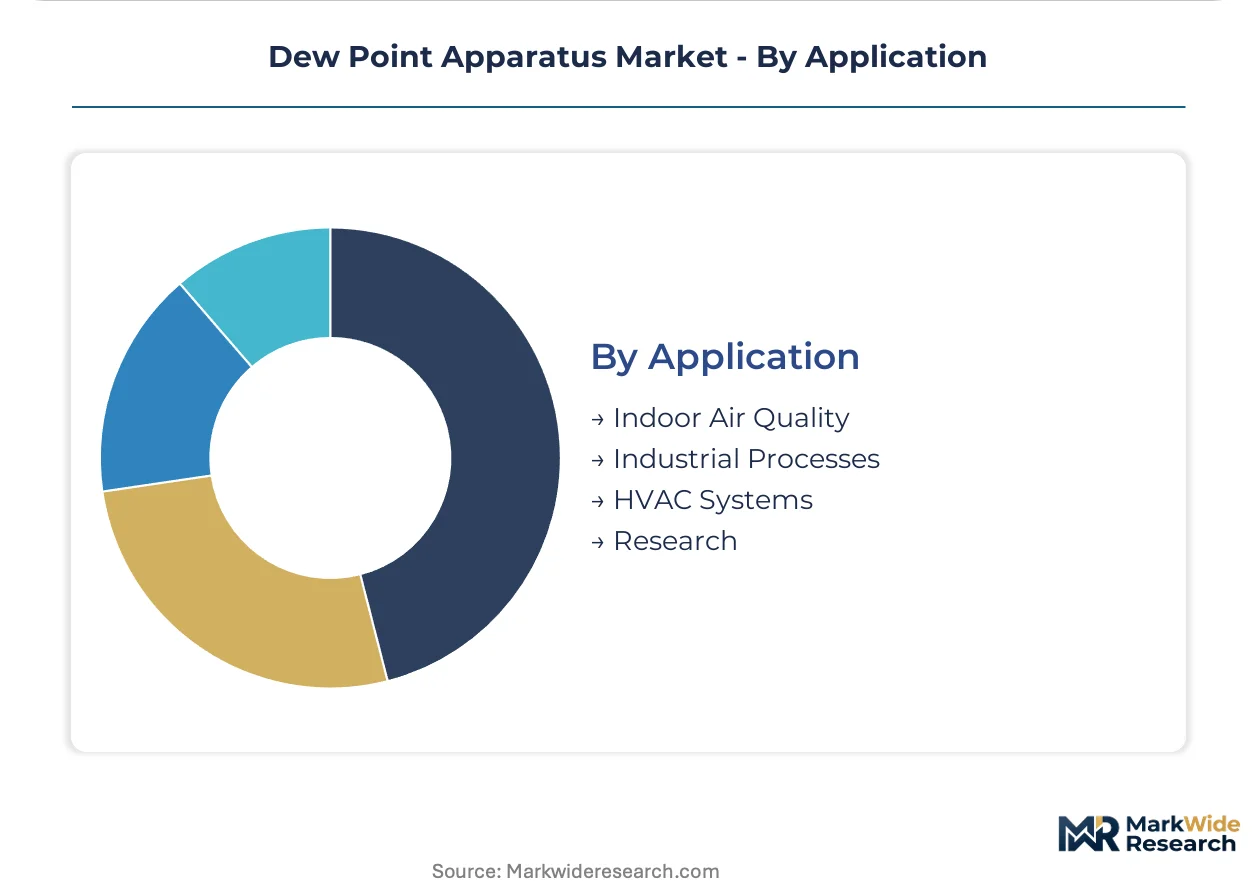
Application:
Volume concentrates in building automation while margin pools in process-critical industrial installations with failure-cost exposure.
- Industrial Processes:Petrochemical, chemical, and battery manufacturing operations protect billion-dollar assets from moisture-induced corrosion and contamination. Pipeline operators across North American utility sectors specify ruggedized field-deployable units for custody transfer measurement.
- Research:National metrology institutes and calibration laboratories maintain primary frost-point standards for ISO 17025-traceable certificate generation. Limited NMI capacity creates extended lead times that constrain service network expansion.
- Indoor Air Quality:Commercial building commissioning and comfort control specify lower-accuracy instruments with reduced calibration frequency.
- HVAC Systems:Building automation integration drives volume shipments for energy optimization and condensation prevention.
HVAC systems anchor volume demand through construction and retrofit cycles. Industrial processes is where value expansion concentrates given catastrophic failure costs and regulatory documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA's Annex 1 revision and FDA process analytical technology guidelines are accelerating calibrated sensor procurement across pharmaceutical manufacturing clusters worldwide.
United States
Petrochemical operators along the Gulf Coast corridor deploy ruggedized field units to protect billion-dollar process streams from moisture-induced corrosion. EPA emissions compliance and OSHA workplace exposure limits shape procurement specifications for industrial facilities. Houston and Baton Rouge anchor concentrated demand from pipeline custody transfer and refinery operations.
Germany
Pharmaceutical cleanroom operators in Baden-Württemberg and Bavaria face compressed upgrade cycles for EMA-mandated environmental monitoring. The F-Gas Regulation drives refrigerant transitions in chilled-mirror reference systems ahead of phase-down deadlines. Frankfurt-Rhine-Main calibration laboratories accelerate qualification programs for alternative cooling fluids.
Switzerland
Swissmedic sterile manufacturing mandates expand documented traceability requirements for dew point sensor networks. Basel's pharmaceutical cluster leads instrumentation upgrades for vaccine and biologics production. Alpine metrology heritage sustains premium positioning for precision reference standards.
China
Battery manufacturing facilities in the Yangtze River Delta and Pearl River Delta deploy online monitoring for moisture-sensitive electrode production. NMPA alignment with international GMP standards drives cleanroom instrumentation investments. Domestic vaccine production expansion creates underpenetrated demand for calibrated sensor networks.
India
CDSCO alignment with PIC/S guidelines compels cleanroom upgrades at domestic vaccine production facilities. Maharashtra and Gujarat pharmaceutical clusters represent emerging procurement centers. Hyderabad and Bangalore biotech corridors drive spot-check audit tool demand between fixed sensor installations.
Dew Point Apparatus Market Competitive Environment
On the supply side, the industry is moderately consolidated around metrology-specialist incumbents and diversified instrumentation conglomerates with overlapping territory claims. Three strategic archetypes dominate: Helsinki-based precision sensor houses with embedded calibration networks, European chilled-mirror reference specialists, and North American field-deployable ruggedization experts. Competitive moves concentrate on service unbundling to capture recurring calibration revenue and embedded cloud connectivity for automated drift correction.
Among precision sensor houses, Vaisala represents the metrology-heritage archetype with Helsinki-based positioning. Michell Instruments exemplifies European reference-system specialization. AMETEK occupies the diversified conglomerate position with North American utility sector anchoring. These three illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Vaisala |
| Edgetech Instruments |
| Michell Instruments |
| AMETEK |
| COSA Xentaur |
| CS Instruments |
| Testo |
| E+E Elektronik |
| LI-COR Biotechnology |
| Others |
Value Chain & Pricing Dynamics
REACH restrictions on perfluorinated compounds and F-Gas Regulation phase-down timelines determine both tier spreads between chilled-mirror reference systems and capacitive polymer units and the geographic reconfiguration of calibration laboratory networks. Buyers face extended lead times for ISO 17025-traceable certificates as European suppliers qualify alternative refrigerants, compressing margins on mid-range instruments while sustaining premium positioning for metrology-grade installations.
Pricing Analysis
Certification level creates the primary spread between laboratory-grade reference instruments and field-deployable units. Three-tier pricing structure separates SI-traceable primary standards from ISO 17025-calibrated process sensors and uncertified maintenance-grade devices. Cost compression in the mid-range capacitive segment is intensifying because annual recalibration requirements expose total cost-of-ownership gaps against optical alternatives. Pharmaceutical cleanroom operators in Germany and Switzerland show least price sensitivity given EMA Annex 1 compliance failure costs, while HVAC contractors in building automation drive hardest bargaining for economy-tier volume shipments.
Supply Chain Analysis
Export controls on precision thermometry components and chilled-mirror refrigerants limit flows from German and Swiss calibration equipment manufacturers to Indian and Chinese pharmaceutical facilities. Platinum resistance thermometers and specialized mirror coatings draw from concentrated European suppliers, while capacitive polymer sensing elements source from Japanese and South Korean semiconductor fabs. Single-source vulnerability around frost-point generation capacity at national metrology institutes constrains service network expansion. Distribution runs through direct-to-plant technical service channels for pharmaceutical and petrochemical end users, with distributor networks handling lower-specification HVAC and compressed air applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dew point apparatus market builds defensive moats through regulatory entrenchment: EMA Annex 1 and FDA process analytical technology guidelines impose switching costs that lock validated sensor networks into incumbent calibration ecosystems.
For Market Incumbents: Pre-empt optical absorption convergence by embedding tunable diode laser reference loops within cloud-connected sensor networks before TDLAS costs drop to capacitive parity. Secure exclusive service contracts with US Gulf Coast petrochemical operators facing billion-dollar contamination exposure. Vertical integration into automated drift correction software displaces third-party metrology providers capturing calibration revenue. For New Entrants and Emerging Players: Build out embedded calibration networks targeting Indian vaccine production facilities where CDSCO alignment with PIC/S guidelines forces instrumentation upgrades but domestic metrology infrastructure remains underdeveloped. Partner with regional distributors for spot-check audit tools in Hyderabad and Bangalore biotech corridors. License optical absorption technology from atmospheric research instrument specialists to bypass chilled-mirror patent thickets. For Investors and Strategic Acquirers: The market sits at a regulatory-upgrade phase that favors metrology-heritage specialists with embedded service revenue models over transactional hardware vendors. Five-to-ten year viability hinges on cloud-connected calibration network density. Target acquisition archetypes combine precision sensor manufacturing with ISO 17025-accredited laboratory assets. Watch for FDA 21 CFR Part 11 enforcement intensity as inflection indicator for documentation-burden expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Calibration Network Expansion | Cloud-connected reference loops automate drift correction for pharmaceutical cleanroom compliance under EMA Annex 1. |
| Optical Absorption Technology Licensing | TDLAS acquisition eliminates sensor contamination risks in chlor-alkali and acid gas processing environments. |
| Indian Pharmaceutical Cluster Partnership | CDSCO alignment with PIC/S guidelines drives cleanroom instrumentation upgrades at domestic vaccine facilities. |
| Alternative Refrigerant Qualification | Hydrofluoroolefin-based frost-point generators sustain European calibration laboratory operations ahead of F-Gas deadlines. |
| Service Revenue Model Transition | Subscription-based calibration contracts displace transactional hardware sales in North American utility sectors. |
Study Parameters
Cross-validation between primary interviews with calibration laboratory directors, pharmaceutical quality assurance managers, and petrochemical maintenance engineers and secondary sources including EMA regulatory filings, FDA guidance documents, and customs trade data anchors the qualitative findings. Plant-level procurement patterns at US Gulf Coast refineries and German sterile manufacturing facilities were reconciled against national metrology institute capacity disclosures. Bottom-up unit shipment estimates by technology type were triangulated with top-down spending analysis across end-use segments.
Calibration against historical replacement cycle data and regulatory implementation timelines refined the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, measurement technology, end-user industry, and application criticality, with regional regulatory cluster as an additional industry-specific layer. CAGRs were derived from installed base turnover rates and continuous monitoring mandate penetration curves, incorporating battery dry room expansion and pharmaceutical cleanroom upgrade pipelines as sector-specific demand inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by optical technology specialists or cloud-platform entrants would shift outcomes. Material shifts in FDA 21 CFR Part 11 enforcement intensity, REACH refrigerant restriction timelines, or national metrology institute capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Battery CT Inspection Market
Test and Measurement
Automatic Impact Testing Machine Market
Test and Measurement
Global Conductivity Meters Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
Semiconductor Test Socket Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
Stress Test Chamber Market
Test and Measurement
Temperature Humidity Chambers Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
One-Box Testers Market
Test and Measurement
Fluorometers Market
Test and Measurement
Scuff Tester Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Europe Electronic Test and Measurement Market