
 Europe Electronic Test and Measurement Market | 2026-2036
Europe Electronic Test and Measurement Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electronic Test and Measurement Market Insights
Capability gaps in high-frequency RF calibration and in-house probe manufacturing is bifurcating the competitive landscape between capital-heavy incumbents and specialized challengers. Keysight Technologies leverages its vertically integrated semiconductor test portfolio to dominate 5G mmWave validation workflows. Rohde & Schwarz GmbH & Co. KG anchors its position through deep backward integration into precision oscillator fabrication. Tektronix Inc. competes aggressively on price-performance in the mid-band oscilloscope tier.
Electronic test and measurement encompasses instruments that characterize electrical signals across frequency, amplitude, and time domains, with modern systems achieving bandwidths exceeding 100 GHz and sample rates above 200 GS/s for semiconductor device validation. These tools serve as critical quality gates in product development cycles, ensuring electromagnetic compliance and functional reliability before mass production release. Oscilloscope demand concentrates in the premium segment where 12-bit resolution and software-defined architectures command durable margin pools. Spectrum analyzers for RF interference testing represent the fastest-expanding product category, driven by 6G research pre-standardization activity. Hybrid technology instruments bridging analog front-ends with digital signal processing are displacing pure analog architectures in automotive validation labs.
The EU AI Act and CE marking requirements under the Radio Equipment Directive are tightening electromagnetic compatibility thresholds for connected test instruments sold across member states. ECHA's REACH restrictions on lead-based solders and cadmium plating are forcing redesigns of probe assemblies and chassis components. Germany's national metrology institute PTB maintains traceability standards that shape procurement specifications for calibration laboratories. Stakeholders must monitor how the CSRD disclosure regime alters capital allocation toward circular-design instrument platforms.
Market Dynamics
Semiconductor fabs across Germany and the Netherlands are expanding test capacity for automotive ECU validation, creating a structural pull for high-bandwidth instrumentation that outpaces legacy replacement cycles. This demand concentration is reshaping supplier allocation priorities and calibration service footprints across the continent.
Growth Catalysts
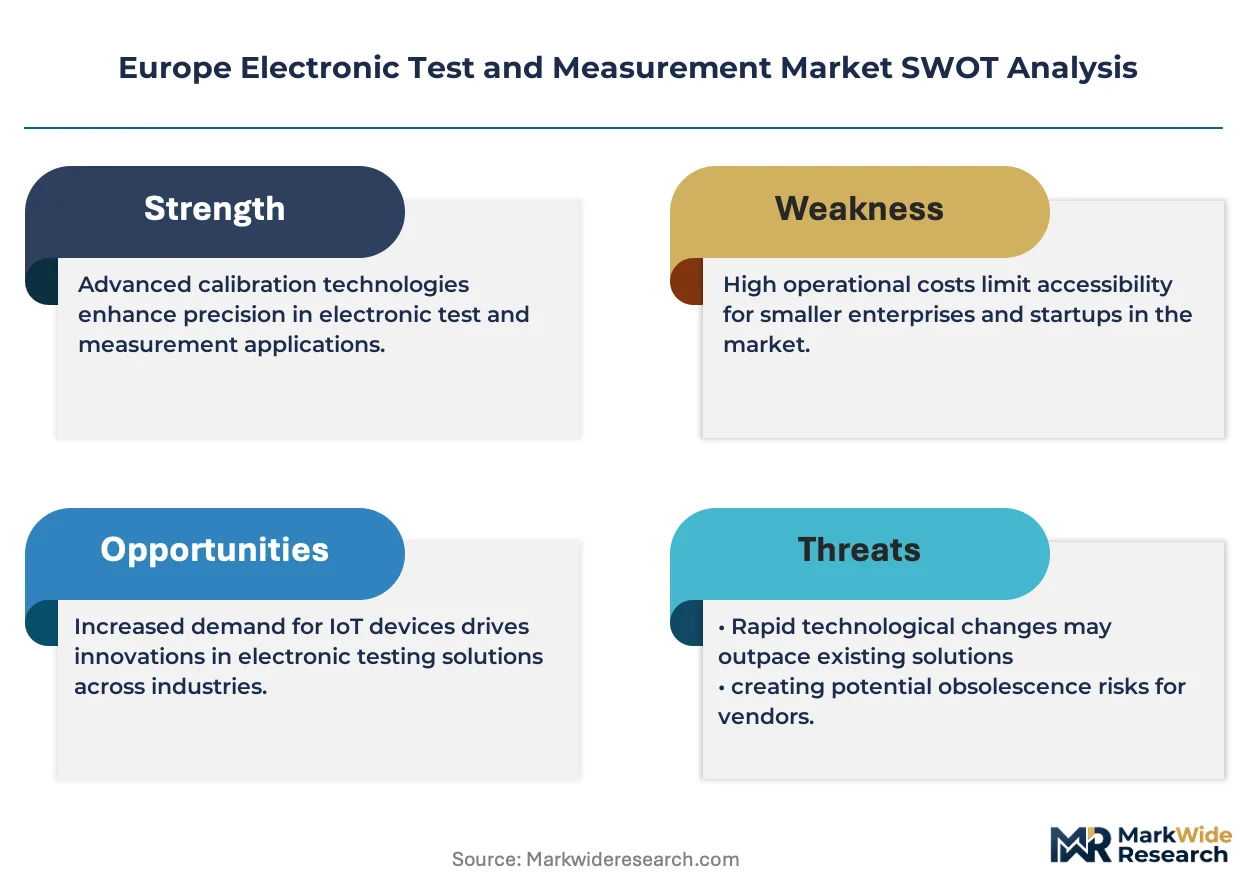
- EU Green Deal compliance:Manufacturers are retooling instrument designs to meet energy-efficiency mandates, opening procurement windows for next-generation thermal management and power-optimized architectures.
- 6G research pre-standardization:Academic consortia and national laboratories from Finland to Spain are acquiring sub-THz characterization equipment, extending addressable demand beyond traditional telecom vendor bases.
- Automotive ECU complexity:Domain controller integration in electric vehicles requires multi-domain signal validation, pulling oscilloscope and protocol analyzer demand into Munich-Stuttgart industrial corridors.
Market Restraints
- Precision oscillator supply concentration:German and Swiss suppliers control critical frequency reference components, exposing instrument makers to single-source risk and extended lead times.
- ECHA REACH substance restrictions:Lead-free solder mandates and cadmium plating bans are forcing probe assembly redesigns, adding qualification cycles and material substitution costs.
- High-frequency calibration scarcity:PTB-traceable standards above 50 GHz remain limited to three national metrology institutes, constraining field service expansion for mmWave instrument portfolios.
Strategic Opportunities
- Poland and Czech Republic industrial zones:Automotive tier-one supplier clusters in these markets currently rely on German calibration services, creating white space for localized test-as-a-service platforms.
- EU AI Act electromagnetic compliance:Connected instrument categories face new conformity assessment pathways, advantaging vendors with pre-certified modular architectures.
- Software-defined instrument convergence:FPGA-based signal processing is merging oscilloscope and spectrum analyzer functions, enabling single-platform substitution of multiple legacy boxes in validation labs.
Industry Challenges
- RF microwave engineering talent scarcity:mmWave circuit design and probe characterization expertise concentrates in aging workforce pools across Bavaria and Baden-Württemberg, constraining R&D velocity.
- CE marking timeline compression:Radio Equipment Directive amendments are shortening conformity assessment windows, pressuring documentation and notified body coordination workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electronic Test and Measurement Market |
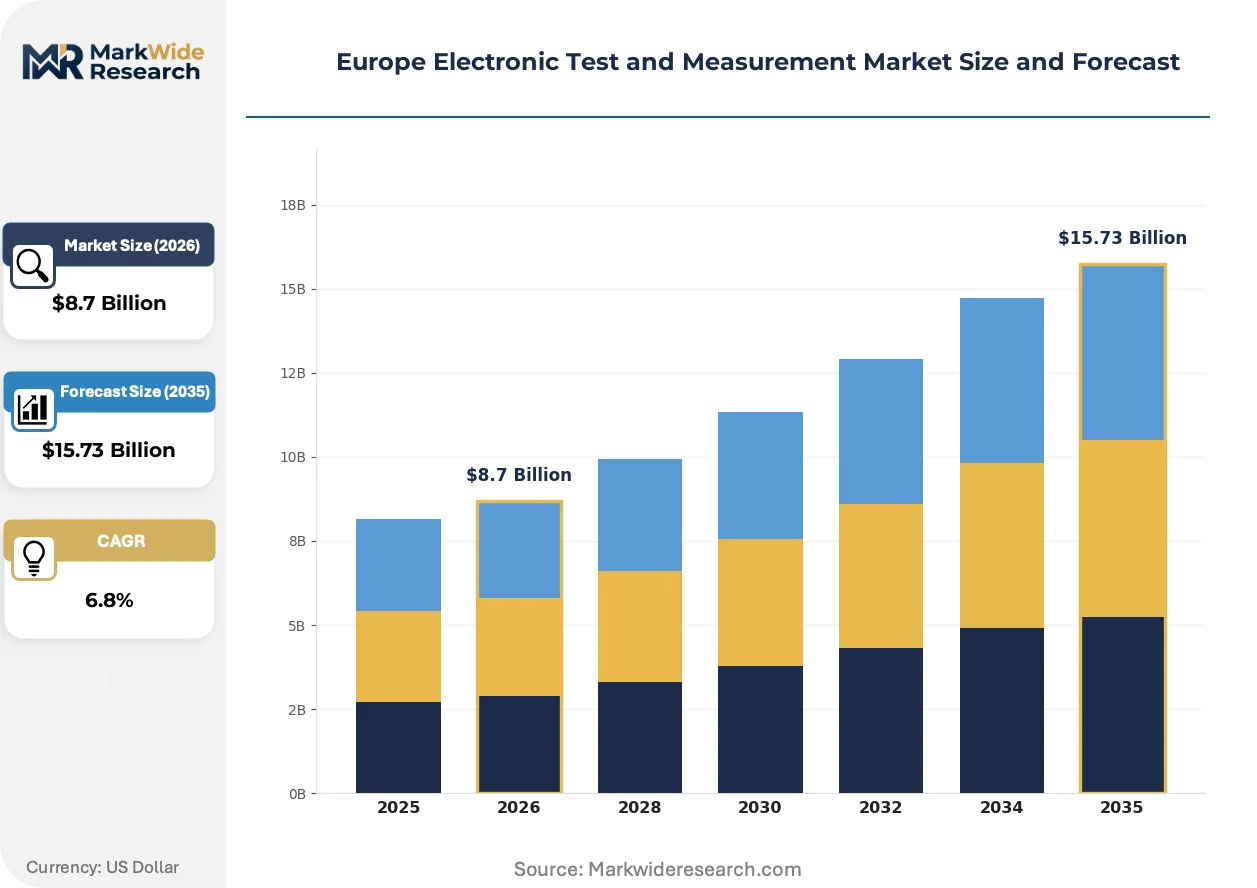
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oscilloscope, Multimeter, Signal Generator, Spectrum Analyzer Technology: Digital, Analog, Hybrid, RF End User: Aerospace, Automotive, Consumer Electronics, Telecommunications Application: Testing, Calibration, Measurement, Quality Assurance |
| Companies Covered | Keysight Technologies, Rohde & Schwarz GmbH & Co. KG, Tektronix Inc., National Instruments Corporation, Fluke Corporation, Yokogawa Electric Corporation, Advantest Corporation, Anritsu Corporation, Viavi Solutions, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electronic Test and Measurement Market Trends and Innovations
Hybrid architectures combining analog front-ends with digital signal processing are redefining instrument performance benchmarks. Three developments are compressing traditional product category boundaries and reshaping buyer-seller relationships.
Modular PXIe and AXIe chassis configurations are supplanting standalone box instruments in automotive validation environments. Tier-one suppliers in Stuttgart and Ingolstadt are standardizing on software-defined platforms that reconfigure via firmware loads rather than hardware swaps. This shift is collapsing the traditional three-year instrument replacement cycle into continuous capability upgrades through module insertion.
F-Gas Regulation phase-down schedules are accelerating refrigerant substitution in thermal test chambers and environmental stress screening equipment. Manufacturers serving Netherlands semiconductor fabs must now qualify alternative cooling chemistries that maintain temperature stability margins. The regulation is compressing supplier qualification timelines and favoring vendors with in-house thermal engineering capabilities.
Service unbundling is fragmenting traditional instrument sales models. Calibration and repair contracts are separating from hardware procurement in German industrial accounts, with PTB-traceable labs competing directly with OEM service organizations. This pattern is most pronounced in Berlin-Brandenburg research institutes, where budget autonomy allows piecemeal supplier selection.
Europe Electronic Test and Measurement Market Segmentation
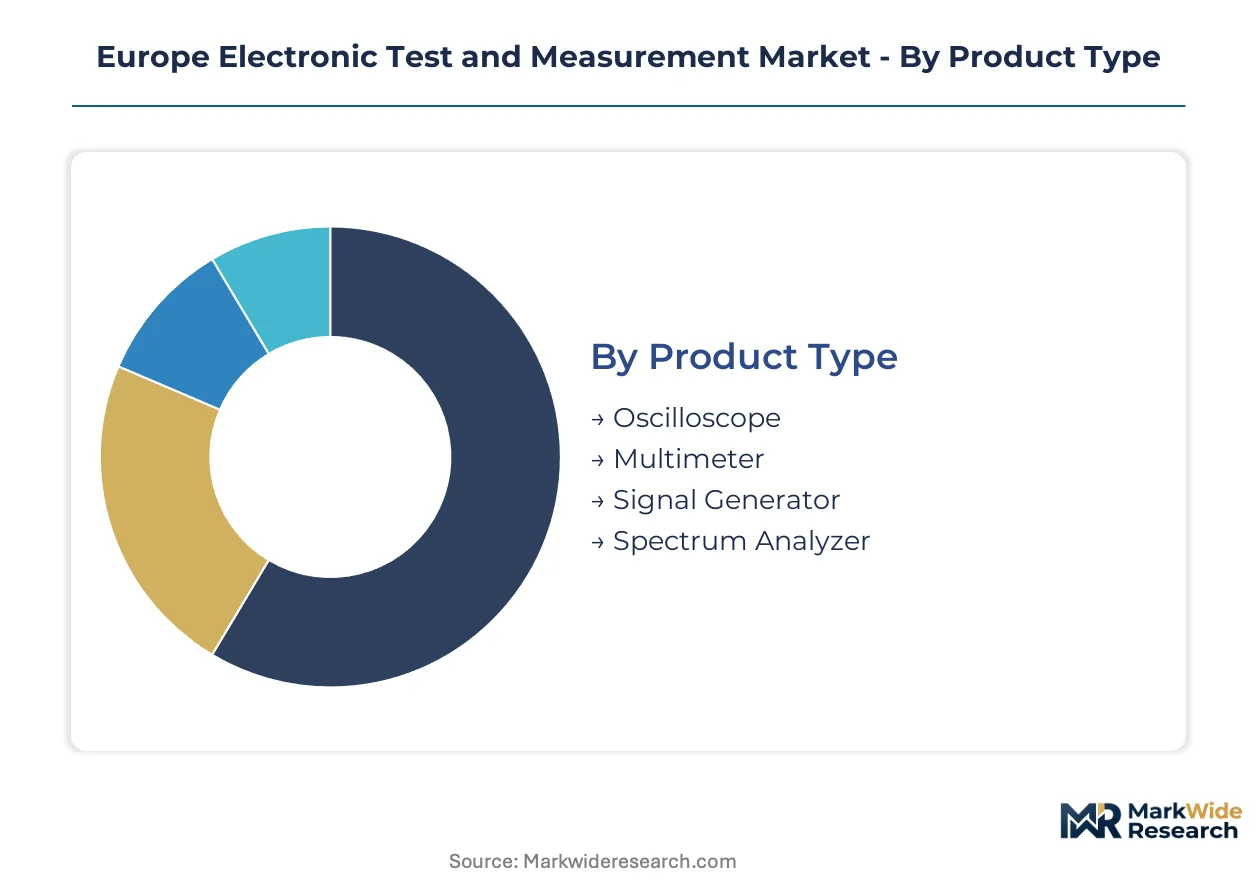
Electronic test and measurement vendors configure product portfolios around four intersecting dimensions. Each segmentation layer reveals distinct margin structures, procurement patterns, and technical qualification barriers that shape competitive positioning across European industrial corridors.
Product Type:
Premium margin pools concentrate in instruments serving sub-THz characterization and multi-domain synchronization workflows.
- Oscilloscope:These instruments capture voltage waveforms across time domains with bandwidths exceeding 100 GHz for semiconductor validation. Demand clusters in Stuttgart automotive labs and Munich research institutes where 12-bit resolution and software-defined architectures command durable pricing power. Keysight and Rohde & Schwarz dominate premium configurations through proprietary ADC architectures.
- Spectrum Analyzer:RF interference testing equipment measures signal power distribution across frequency bands for electromagnetic compliance verification. Netherlands semiconductor fabs and Finland 6G research consortia are pulling sub-THz configurations faster than legacy replacement cycles, extending addressable demand beyond traditional telecom vendor bases.
- Multimeter:Precision voltage, current, and resistance measurement devices serve baseline electrical verification in manufacturing floor environments.
- Signal Generator:Arbitrary waveform and vector signal sources provide stimulus signals for device characterization in protocol validation labs.
Oscilloscope holds installed capacity. Spectrum Analyzer is rotating up the share rankings.
Technology:
Architecture choices determine thermal budgets, calibration intervals, and firmware upgrade pathways that lock in recurring service revenue.
- Digital:FPGA-based signal processing architectures merge oscilloscope and spectrum analyzer functions through software reconfiguration. Stuttgart tier-one automotive suppliers are standardizing on these platforms, collapsing traditional three-year replacement cycles into continuous capability upgrades via module insertion.
- Hybrid:Analog front-end precision combined with digital back-end flexibility bridges legacy metrology requirements and modern automation protocols. German PTB-traceable calibration labs favor these configurations for maintaining measurement uncertainty budgets across 50 GHz+ characterization tasks.
- Analog:Pure analog signal paths persist in niche high-linearity applications where digital quantization noise compromises measurement fidelity.
- RF:Dedicated radio frequency architectures serve mmWave and sub-THz characterization with specialized local oscillator chains.
Digital holds installed capacity. Hybrid is rotating up the share rankings.
End User:
Customer concentration patterns diverge sharply between capital-intensive validation environments and high-volume production screening.
- Automotive:Electric vehicle domain controller integration requires multi-domain signal validation across power electronics, sensor fusion, and communication protocols. ECU complexity is pulling oscilloscope and protocol analyzer demand into Munich-Stuttgart industrial corridors where tier-one suppliers operate centralized test facilities.
- Telecommunications:5G mmWave and pre-standardization 6G research drives sub-THz equipment procurement. Academic consortia from Finland to Spain are acquiring characterization equipment that extends addressable demand beyond traditional vendor bases.
- Aerospace:Defense and satellite communication applications impose stringent environmental qualification and traceability documentation requirements.
- Consumer Electronics:High-volume manufacturing environments prioritize throughput-optimized screening with compressed test times and minimal operator intervention.
Automotive holds installed capacity. Telecommunications is rotating up the share rankings.
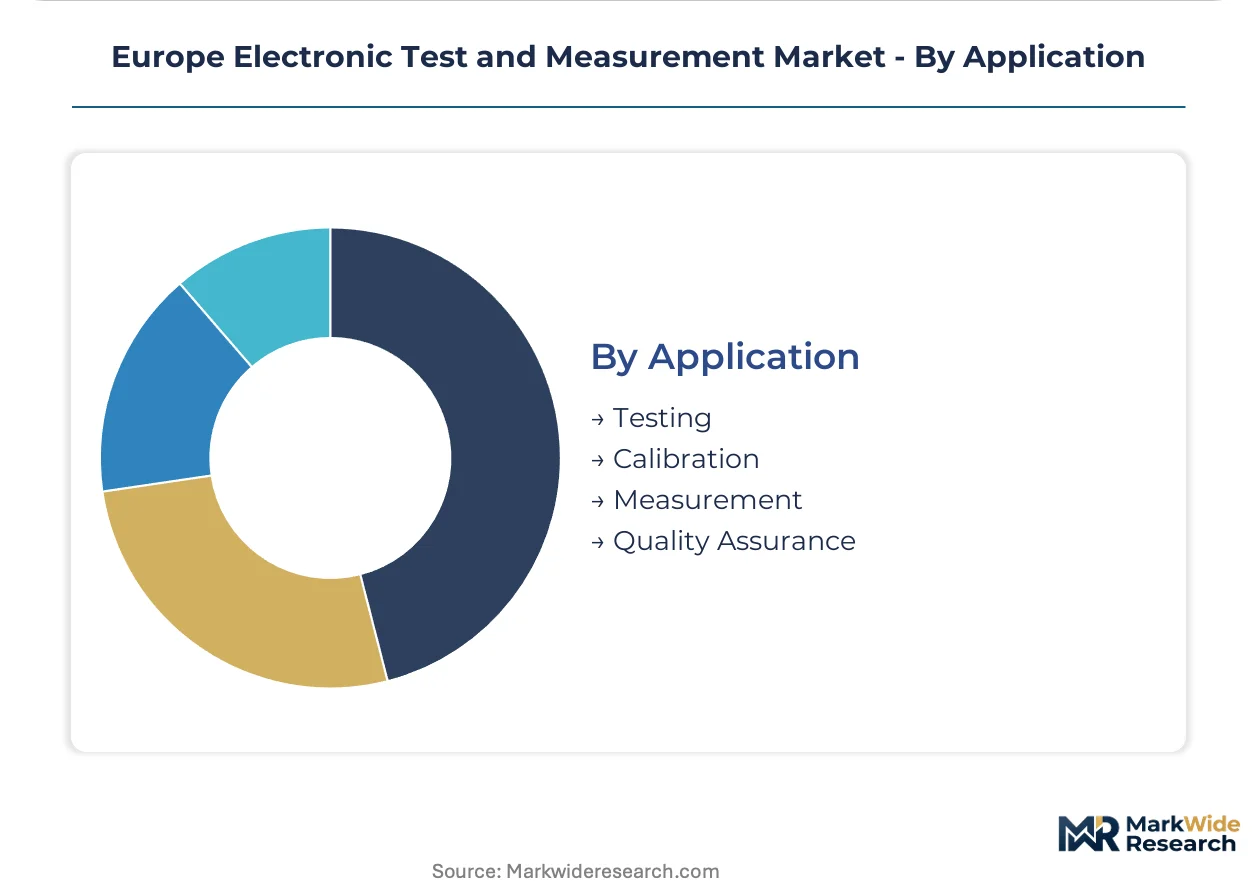
Application:
Workflow positioning determines whether instruments generate one-time hardware revenue or recurring service attachment.
- Calibration:PTB-traceable metrology services maintain measurement uncertainty chains for regulatory compliance and quality system certification. Berlin-Brandenburg research institutes are unbundling calibration contracts from hardware procurement, with independent labs competing directly against OEM service organizations.
- Testing:Functional verification and stress screening workflows dominate semiconductor fab and automotive ECU validation environments.
- Measurement:Parametric characterization tasks support R&D iteration and design optimization cycles.
- Quality Assurance:Production-line pass-fail determination with statistical process control integration.
Testing holds installed capacity. Calibration is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor from Munich to Berlin consumes electronic test equipment differently than peripheral markets, emphasizing precision metrology and automotive validation over high-volume production screening. Netherlands semiconductor fabs prioritize sub-THz characterization for EUV lithography process control. Nordic research consortia concentrate spending on pre-standardization 6G equipment rather than established telecom test protocols.
Germany
Automotive ECU validation and power electronics testing dominate procurement across Bavaria and Baden-Württemberg. PTB traceability requirements shape specifications for calibration laboratories serving Stuttgart tier-one suppliers. Munich-Stuttgart industrial corridors host centralized test facilities where domain controller integration pulls multi-domain signal validation demand.
Netherlands
Semiconductor fabs near Eindhoven expand test capacity for EUV process control and wafer-level characterization. F-Gas Regulation phase-down schedules accelerate refrigerant substitution in thermal test chambers serving ASML supplier ecosystems. Brabant region equipment purchases concentrate on sub-THz spectrum analyzers for lithography metrology.
France
Aerospace and defense applications in Île-de-France impose stringent environmental qualification requirements on instrument procurement. ANSM electromagnetic compliance oversight extends to connected test equipment categories under Radio Equipment Directive amendments. Paris-Saclay research cluster acquisitions focus on hybrid analog-digital architectures for satellite communication validation.
United Kingdom
London-Southeast financial and research institutions unbundle calibration contracts from hardware procurement, with independent PTB-traceable labs competing against OEM service organizations. CE marking timeline compression under post-Brexit UKCA arrangements pressures conformity assessment workflows. Cambridge-Tokyo research partnerships drive 6G pre-standardization equipment demand.
Finland
Oulu and Espoo academic consortia lead European 6G research pre-standardization activity, acquiring sub-THz characterization equipment ahead of traditional telecom vendor bases. National research funding programs extend addressable demand beyond commercial procurement cycles. Arctic climate test facilities require specialized environmental stress screening instrumentation.
Europe Electronic Test and Measurement Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in European electronic test and measurement. Capital-heavy incumbents control precision oscillator fabrication and high-frequency RF calibration chains, while specialized challengers compete on price-performance in mid-band instrument categories. Three archetypes define positioning: vertically integrated semiconductor test portfolios, precision metrology specialists with backward integration into frequency references, and modular software-defined platform vendors. Competitive moves concentrate on strategic partnerships for mmWave probe manufacturing and geographic expansion into Poland-Czech industrial zones.
Within the integrated leader tier, Keysight Technologies and Rohde & Schwarz GmbH & Co. KG exemplify divergent approaches to market dominance. Keysight represents the vertically integrated semiconductor test archetype, while Rohde & Schwarz occupies a position anchored in precision oscillator fabrication. Tektronix Inc. sits within the aggressive price-performance specialist tier. These three entities collectively illustrate how capability concentration in high-frequency calibration and in-house probe manufacturing bifurcates competitive positioning across the continent.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz GmbH & Co. KG |
| Tektronix Inc. |
| National Instruments Corporation |
| Fluke Corporation |
| Yokogawa Electric Corporation |
| Advantest Corporation |
| Anritsu Corporation |
| Viavi Solutions, Inc. |
| Others |
Pricing and Supply Chain Analysis
CE marking requirements under the Radio Equipment Directive gate both instrument qualification timelines and price differentiation between certified and uncertified equipment categories. This regulatory threshold simultaneously constrains supplier entry and enables premium positioning for vendors with pre-certified modular architectures serving German automotive labs.
Pricing Analysis
Long-term service contracts dominate procurement in Stuttgart tier-one automotive facilities, while spot purchases persist in research institute environments. Three-tier pricing structure across premium, standard, and economy levels separates PTB-traceable calibration tiers from basic functional verification units. Cost compression in the mid-band oscilloscope tier is intensifying because Tektronix and specialized challengers compete aggressively on price-performance. German industrial accounts show lowest price sensitivity for calibration services, whereas Poland-Czech tier-one suppliers exhibit highest sensitivity to hardware acquisition costs.
Supply Chain Analysis
Strategic stockpiling of precision oscillator components characterizes German and Swiss instrument makers facing extended lead times from single-source frequency reference suppliers. Manufacturing concentration in Germany, Switzerland, and the United States shapes component availability for EUV lithography metrology equipment. Critical dependencies include indium phosphide substrates, precision machined chassis, and specialized RF connectors. Single-source vulnerability in 50 GHz+ calibration standards constrains field service expansion. Distribution runs through authorized channel partners serving Munich-Berlin industrial corridors and direct OEM relationships with Netherlands semiconductor fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards mastery of mmWave probe characterization and PTB-traceable calibration chains, capabilities concentrated in aging workforce pools across Bavaria. Firms lacking these assets face structural barriers to premium positioning regardless of capital deployment.
For Market Incumbents: Consolidate control over precision oscillator fabrication through captive supply arrangements with Swiss and German frequency reference specialists. Lock in multi-year calibration service contracts with Stuttgart automotive labs before independent PTB-traceable labs expand field presence. Defend against modular software-defined platform substitution by embedding proprietary ADC architectures into firmware-upgradeable chassis configurations. For New Entrants and Emerging Players: CE marking fast-track pathways for connected instrument categories offer entry advantages against legacy vendors with documentation backlogs. White space concentrates in Poland and Czech Republic automotive supplier zones currently dependent on German calibration services. Target test-as-a-service platforms with localized probe characterization capabilities rather than hardware resale. Lead with software-defined architectures that collapse multiple instrument functions into single reconfigurable platforms. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized precision metrology divisions lacking standalone scale. Long-term viability hinges on positioning within 6G pre-standardization research funding flows and automotive ECU validation consolidation. Favor acquisition candidates with in-house mmWave probe manufacturing and established PTB traceability chains. Watch for inflection when EU AI Act electromagnetic compliance deadlines compress conformity assessment windows beyond notified body capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Oscillator Backward Integration | Captive supply of frequency references from Swiss suppliers insulates against lead time volatility. |
| Software-Defined Platform Convergence | FPGA-based architectures merge oscilloscope and spectrum analyzer functions for Stuttgart automotive labs. |
| PTB-Traceable Calibration Service Expansion | Berlin-Brandenburg research institutes unbundle calibration from hardware procurement. |
| Poland-Czech Test-as-a-Service Localization | Automotive tier-one clusters in these markets currently rely on German calibration infrastructure. |
| 6G Pre-Standardization Equipment Positioning | Finland and Spain academic consortia acquire sub-THz characterization ahead of commercial vendor bases. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with instrument R&D directors, calibration laboratory managers, automotive tier-one procurement leads, and semiconductor fab metrology engineers; and secondary validation through ECHA REACH substance restriction filings, PTB traceability standard documentation, EU AI Act electromagnetic compliance drafts, and SEC filings of listed test equipment vendors. Bottom-up segmentation modeling triangulated against top-down market sizing from customs trade data and national research funding disclosures.
Across the projection horizon, the analytical framework modeled demand across product type, technology architecture, end-use industry, and application workflow dimensions. CAGRs derived from instrument replacement cycle compression rates, 6G research funding trajectories, and automotive ECU validation capacity expansion plans. Specific inputs included F-Gas Regulation phase-down schedules affecting thermal test chamber demand and EU Green Deal energy-efficiency mandates reshaping procurement specifications.
Decision-makers should treat outputs as directional under assumptions of continued semiconductor fab expansion in the Netherlands and sustained 6G research funding across Nordic consortia; material deviation would warrant model refresh. Specific risk factors include precision oscillator supply disruption from Swiss-German frequency reference concentration and CE marking timeline compression under Radio Equipment Directive amendments. Revision becomes warranted when PTB-traceable calibration capacity constraints cross thresholds that bottleneck mmWave instrument field service expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Manufacturing Test Systems Market
Test and Measurement
Automated Optical Inspection (AOI) System Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Ground Resistance Testers Market
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
Water Leakage Tester Market
Test and Measurement
Ultrasonic Pulse Velocity Tester Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Receptacle Tester Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Hardness Testing Machine Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
High Rate Discharge Test Machine Market