
 United States Electric Insulator Market | 2026-2036
United States Electric Insulator Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Insulator Market Intelligence
Utility procurement channels is tilting toward direct manufacturer relationships and away from traditional distributor intermediaries. TE Connectivity leverages its polymer expertise to sustain long-term supply agreements with major utilities. Hubbell Incorporated anchors its position through integrated manufacturing and field service capabilities. MacLean Power Systems competes aggressively on transmission-class hardware bundles that include insulator assemblies.
United States Electric Insulators are non-conductive devices engineered from porcelain, glass, polymer composites, or silicone rubber, designed to mechanically support and electrically isolate conductors while withstanding voltage stresses from 15 kV to 765 kV and environmental loads including UV, pollution, and thermal cycling. Their primary purpose is preventing current leakage to ground structures in overhead lines, substations, and electrified rail systems. Porcelain insulators still occupy the largest installed base across legacy transmission corridors, though polymer and composite materials are displacing glass in new construction due to lighter weight and superior vandalism resistance. Renewable energy applications represent the fastest-expanding demand pool, driven by solar farm collector systems and wind turbine step-up transformers requiring specialized creepage distance designs.
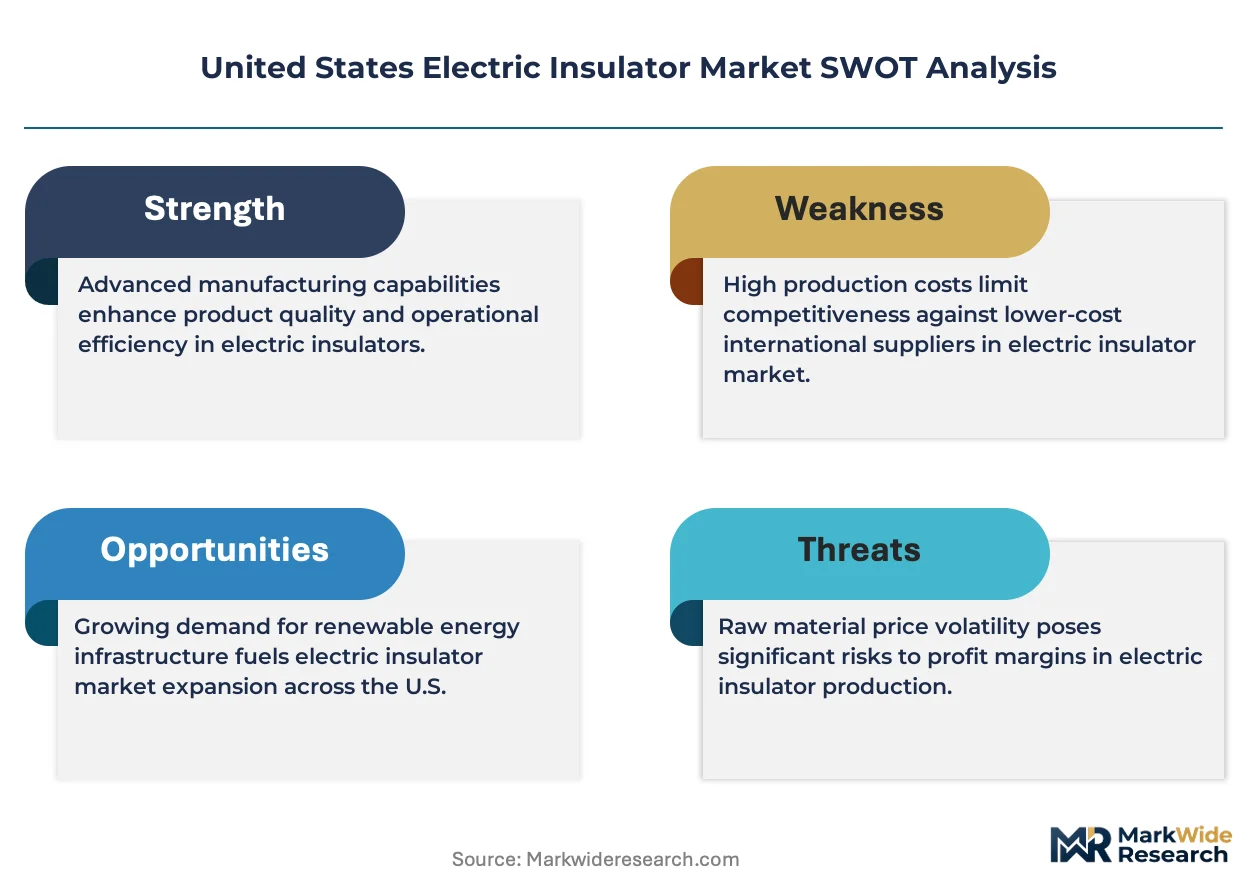
FERC Order 1000 compliance deadlines and NERC CIP reliability standards are forcing utilities to accelerate inspection and replacement schedules for aging ceramic installations. OSHA 1910.269 live-line work rules and IEEE 1527 testing protocols shape product certification requirements and limit market access for uncertified imports. State public utility commissions in California, Texas, and New York are embedding resilience metrics into rate-case approvals that favor upgraded insulator specifications. Stakeholders must monitor evolving material qualification timelines and build flexible polymer compounding capacity to capture shifting specification trends.
Market Dynamics
Grid modernization mandates from FERC Order 1000 and state renewable portfolio standards are compressing replacement cycles while tilting specifications toward composite materials that withstand coastal corrosion and desert thermal cycling.
Growth Catalysts
- Transmission hardening mandates:NERC reliability standards require utilities in hurricane-prone Gulf Coast and wildfire-vulnerable California corridors to upgrade ceramic installations with polymer alternatives rated for extreme weather resilience.
- Offshore wind interconnection buildout:Atlantic seaboard lease auctions from Massachusetts to North Carolina are creating dedicated demand for silicone rubber insulators engineered for salt-fog environments and subsea cable terminations.
- Solar farm collector system expansion:Utility-scale photovoltaic installations in Texas and Arizona require specialized creepage distance designs for DC-to-AC step-up transformers, expanding the addressable market beyond traditional AC transmission.
Market Restraints
- Silicone rubber feedstock volatility:Polymer insulator manufacturers face margin pressure from petrochemical price swings tied to ethylene and silicone monomer supply disruptions concentrated in Gulf Coast refining clusters.
- Porcelain installed base lock-in:Legacy ceramic insulators across Midwest transmission corridors impose switching costs that delay composite adoption despite superior vandalism resistance and lighter structural loads.
- Import certification friction:Uncertified Asian manufacturers face exclusion from utility procurement lists due to IEEE 1527 testing protocol requirements and OSHA 1910.269 live-line work rule compliance verification.
Strategic Opportunities
- Rail electrification retrofit programs:Amtrak and regional commuter authorities in the Northeast Corridor are replacing aging catenary insulators with hybrid designs that reduce electromagnetic interference for high-speed rolling stock.
- Texas ERCOT resilience carve-outs:State public utility commission rate-case approvals now embed storm-hardening metrics that favor upgraded insulator specifications for critical nodes in the independent grid operator's territory.
- Digital twin integration:Sensor-embedded intelligent insulators that feed real-time leakage current data into predictive maintenance platforms represent an emerging premium segment for transmission asset managers.
Industry Challenges
- Polymer compounding qualification timelines:Material formulation approvals from IEEE working groups stretch 18-24 months, compressing product development windows for manufacturers targeting specific utility specification cycles.
- Field service technician scarcity:Specialized live-line replacement crews certified for 345 kV and above operations face retirement waves that outpace training pipeline capacity across rural transmission territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Insulator Market |
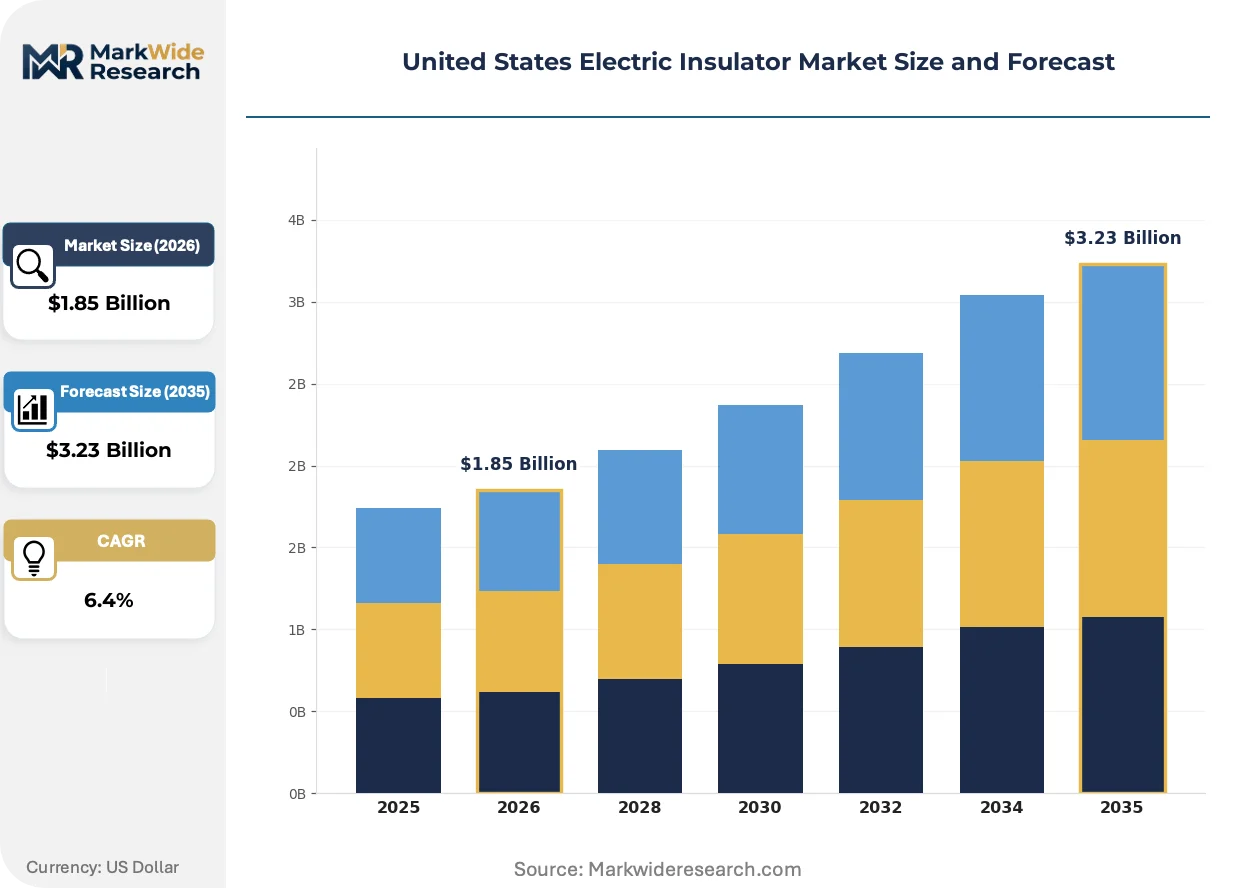
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Glass, Composite, Polymer Application: Power Transmission, Distribution Networks, Renewable Energy, Manufacturing Installation Type: Overhead Lines, Underground Systems, Substations, Railways End User: Utilities, Industrial, Commercial, Construction |
| Companies Covered | Peak Demand Incorporated, Newell Porcelain, TE Connectivity, Meister International, MacLean Power Systems, Hubbell Incorporated, Gamma Insulators, Norplex-Micarta, Victor Insulators, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Insulator Market Strategic Shifts & Innovations
Material science advances and procurement digitization are converging to reshape how utilities specify, source, and deploy insulation hardware across voltage classes and environmental zones.
Silicone rubber composite housing technology is collapsing the traditional weight-performance tradeoff that favored porcelain for high-voltage applications. Transmission utilities in Florida and California are specifying hollow-core polymer designs for 230 kV and 345 kV lines at accelerating rates. This shift is collapsing freight and installation cost structures that previously constrained composite penetration above 138 kV.
FERC Order 1000 compliance deadlines are forcing regional transmission organizations to consolidate procurement specifications across multi-state planning regions. The industrial consequence is standardization of creepage distance and mechanical load ratings that previously varied by utility. Midwest ISO and Southwest Power Pool territories are most affected, with procurement departments rewriting master service agreements to accommodate unified technical standards.
Direct manufacturer relationships are displacing traditional electrical distributor intermediaries for transmission-class hardware bundles. Utility procurement departments in Texas and New York are negotiating long-term supply agreements that embed field service capabilities and inventory consignment. This channel restructuring is most visible in PJM Interconnection territory, where integrated manufacturing-service providers capture premium positioning through outage response guarantees.
United States Electric Insulator Market Segmentation
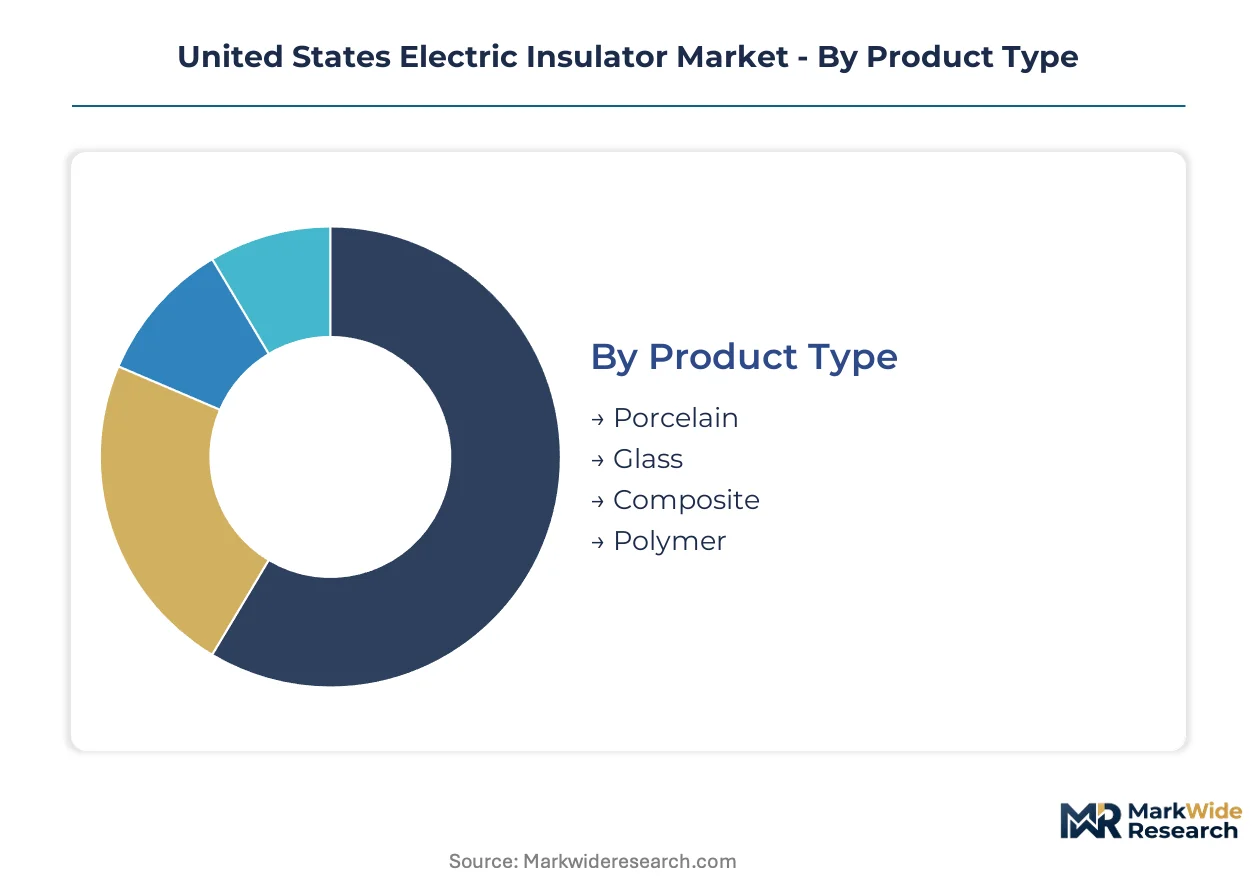
Segmentation reveals how material specifications, voltage requirements, and end-use environments fragment procurement patterns across the United States electric insulator market. Utility buyers prioritize different performance tradeoffs than industrial or commercial purchasers, creating distinct competitive arenas.
Product Type:
Material composition determines weight, vandalism resistance, and thermal cycling performance across voltage classes from 15 kV to 765 kV.
- Porcelain:Alumina-based ceramic formulations dominate legacy transmission corridors throughout the Midwest and Southeast. Aging installed bases across Tennessee Valley Authority and Entergy territories impose switching costs that delay replacement despite structural weight penalties.
- Composite:Fiberglass-reinforced polymer cores with silicone rubber housings are displacing glass above 138 kV. Florida Power and Light specifications for hurricane-rated 230 kV lines demonstrate accelerating acceptance of hollow-core designs.
- Glass:Tempered borosilicate constructions retain niche positioning in European-influenced utility standards. Northeast Corridor commuter rail electrification maintains steady demand for traditional cap-and-pin assemblies.
- Polymer:Silicone rubber formulations engineered for salt-fog environments serve Atlantic offshore wind interconnection projects. Salt spray testing protocols per IEEE 1527 constrain supplier qualification timelines.
Porcelain holds installed capacity. Composite is rotating up the share rankings.
Application:
Voltage class and system function dictate creepage distance requirements, mechanical load ratings, and environmental sealing specifications.
- Power Transmission:Bulk power transfer corridors at 345 kV and 765 kV require suspension and tension assemblies with specified tensile strengths exceeding 60,000 pounds. ERCOT and PJM interconnection hardening mandates accelerate procurement cycles.
- Renewable Energy:Solar farm collector systems and wind turbine step-up transformers demand specialized DC-rated designs with extended creepage distances. Texas and Arizona utility-scale photovoltaic expansions drive specification innovation.
- Distribution Networks:15 kV to 69 kV radial feeders prioritize cost efficiency and vandalism resistance over extreme weather ratings. Municipal utilities in California and Texas dominate volume procurement.
- Manufacturing:Industrial plant substations and captive generation interconnections require compact phase-to-ground clearances. Petrochemical complexes along the Gulf Coast specify explosion-resistant housings.
Power Transmission anchors revenue concentration. Renewable Energy is climbing the fastest.
Installation Type:
Physical deployment environment shapes contamination exposure, accessibility for live-line maintenance, and seismic or wind loading calculations.
- Overhead Lines:Suspension, tension, and post-type assemblies exposed to UV, pollution, and mechanical vibration. California wildfire corridors and Gulf Coast hurricane zones drive polymer adoption for resilience.
- Substations:Station post and bus support insulators for switchyard equipment with standardized bolt-circle patterns. FERC Order 1000 consolidation of procurement specifications reduces catalog complexity.
- Underground Systems:Cable termination and GIS (gas-insulated switchgear) applications requiring gas-tight sealing. Urban density in New York and Chicago constrains overhead routing.
- Railways:Catenary suspension and section insulators for electrified passenger and freight corridors. Amtrak Northeast Corridor replacement programs specify electromagnetic interference reduction.
Overhead Lines commands volume leadership. Substations is gaining specification priority.
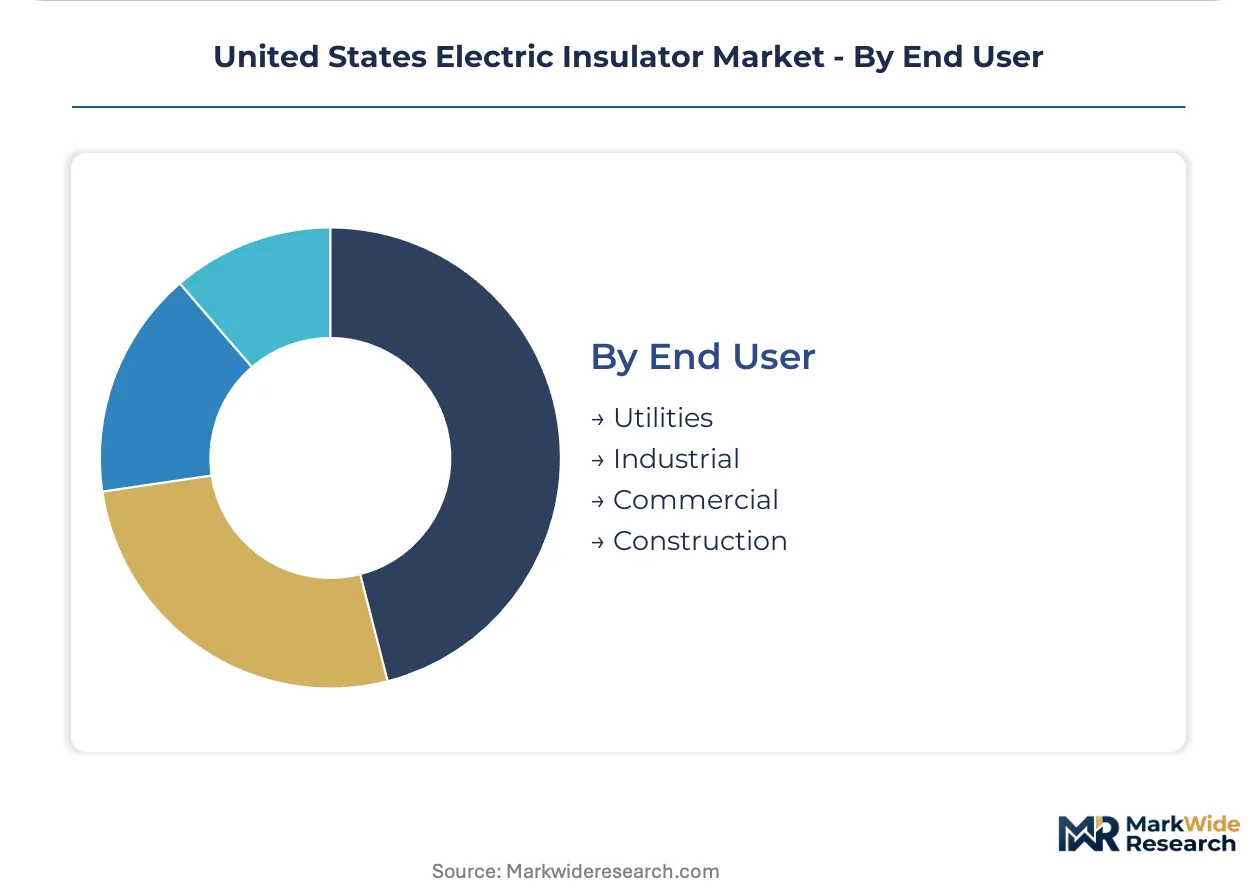
End User:
Procurement sophistication, specification authority, and field service requirements vary sharply across customer categories.
- Utilities:Investor-owned and public power entities with centralized engineering standards and long-term supply agreements. Texas and California rate-case approvals embed storm-hardening metrics that favor upgraded specifications.
- Industrial:Heavy manufacturing, mining, and petrochemical operations with captive substations and reliability-critical processes. Gulf Coast refining clusters specify corrosion-resistant polymer housings.
- Commercial:Data centers, hospitals, and large retail distribution facilities with medium-voltage service entrances. Backup power interconnection requirements drive demand for compact indoor designs.
- Construction:Greenfield infrastructure developers and EPC contractors bidding on transmission and renewable projects. Lump-sum contract structures prioritize freight cost minimization through lightweight composite selection.
Utilities dominates procurement value. Industrial is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas ERCOT interconnection anchors regional demand through storm-hardening mandates and renewable integration pressures. California's wildfire corridors and Atlantic offshore wind lease zones concentrate procurement activity across three distinct climatic stress regimes.
Texas
ERCOT's isolated grid drives transmission hardening investments across the Gulf Coast and Permian Basin renewable zones. State public utility commission rate-case approvals embed resilience metrics that favor upgraded insulator specifications for critical nodes. Houston and Dallas-Fort Worth clusters concentrate utility engineering headquarters and manufacturer field service operations.
California
Wildfire-vulnerable transmission corridors accelerate ceramic-to-polymer replacement cycles mandated by CPUC safety regulations. Investor-owned utilities in Sacramento and San Francisco Bay Area procurement offices consolidate specifications under FERC Order 1000 compliance timelines. Central Valley solar farm expansions create specialized DC-rated demand for step-up transformer installations.
Midwest
Aging porcelain installed bases across TVA and Entergy territories impose switching costs that delay composite adoption despite structural weight penalties. MISO procurement consolidation rewrites master service agreements to accommodate unified technical standards. Chicago and St. Louis serve as distribution logistics hubs for transmission-class hardware bundles.
Northeast Corridor
Offshore wind interconnection projects from Massachusetts to North Carolina drive salt-fog-rated silicone rubber specifications. PJM Interconnection territory favors integrated manufacturing-service providers through outage response guarantees. Boston and New York City procurement departments negotiate long-term supply agreements with embedded inventory consignment.
Southeast
Hurricane-rated polymer designs gain specification share across Florida Power and Light and Duke Energy territories. NERC reliability standards require extreme weather resilience upgrades in Gulf Coast corridors. Atlanta and Charlotte clusters concentrate regional utility engineering and distributor consolidation activity.
United States Electric Insulator Market Key Industry Players
On the supply side, the industry is tiered between integrated manufacturing-service providers, specialized polymer compounders, and regional hardware fabricators. Three strategic archetypes dominate: transmission-class bundle suppliers with field service capabilities, polymer specialists leveraging material science differentiation, and legacy porcelain manufacturers defending installed base replacement cycles. Competitive moves center on direct utility relationship cultivation and long-term supply agreement negotiation.
Within the integrated manufacturing-service tier, TE Connectivity and Hubbell Incorporated exemplify the archetype of polymer expertise combined with outage response guarantees. MacLean Power Systems occupies a position representing aggressive transmission-class hardware bundling. These three anchors illustrate how procurement channel restructuring toward direct manufacturer relationships rewards vertical capability integration.
| Leading Market Players |
|---|
| Peak Demand Incorporated |
| Newell Porcelain |
| TE Connectivity |
| Meister International |
| MacLean Power Systems |
| Hubbell Incorporated |
| Gamma Insulators |
| Norplex-Micarta |
| Victor Insulators |
| Others |
Cost & Logistics Intelligence
Gulf Coast petrochemical corridors anchor freight cost dynamics for silicone rubber feedstock, concentrating polymer insulator manufacturing in Texas and Louisiana while compressing margins for distant competitors and enabling volume-based price stratification across utility procurement tiers.
Pricing Analysis
Volume-discount tiering structures separate transmission-class bundled hardware from distribution-grade commodity units, with FERC Order 1000 compliance deadlines compressing negotiation windows for integrated manufacturing-service providers. Certification under IEEE 1527 and OSHA 1910.269 standards commands premium positioning against uncertified imports. Pricing pressure stems from ethylene and silicone monomer volatility tied to Gulf Coast refining disruptions. Municipal utilities in California and Texas exhibit highest price sensitivity, while investor-owned transmission operators prioritize outage response guarantees over unit cost.
Supply Chain Analysis
Upstream feedstock dependence on Gulf Coast petrochemical clusters and Chinese silicone monomer production concentrates polymer compounding capacity in Texas and Ohio. Raw material inputs encompass alumina for porcelain, fiberglass roving for composite cores, and silicone rubber for housings. Single-source vulnerability in silicone monomer supply chains exposes manufacturers to force majeure disruptions. Distribution runs through direct manufacturer-utility relationships for transmission-class hardware, bypassing traditional electrical distributor intermediaries in PJM and ERCOT territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FERC Order 1000 compliance deadlines and NERC reliability standard upgrades constitute a regulatory inflection compressing replacement cycles and tilting procurement toward composite materials, creating a high-growth disruption window for positioned suppliers.
For Market Incumbents: Pre-empt ceramic-to-polymer substitution acceleration by embedding field service capabilities into long-term supply agreements before IEEE qualification timelines lock out competitors. Defend against emerging polymer specialists through backward integration into silicone rubber compounding capacity in Texas. Prioritize outage response guarantees in PJM and ERCOT territories where procurement departments consolidate vendor lists. For New Entrants and Emerging Players: Pursue digital twin integration for sensor-embedded intelligent insulators as a white-space target underserved by legacy manufacturers. Target solar farm collector systems in Arizona and Texas where DC-rated creepage distance designs lack established supply relationships. Enter through EPC contractor partnerships on lump-sum renewable interconnection projects where freight cost minimization favors lightweight composite sourcing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electrical equipment conglomerates with underutilized polymer compounding assets and dormant utility relationships. Long-term viability hinges on positioning ahead of Atlantic offshore wind interconnection buildout completion. Monitor IEEE working group material formulation approval timelines as inflection indicators for supplier qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Captures margin from petrochemical volatility while accelerating IEEE 1527 qualification timelines for Gulf Coast manufacturers. |
| Long-term Supply Agreement with Outage Guarantees | Secures premium positioning in PJM Interconnection territories where procurement departments prioritize response speed over unit pricing. |
| Joint Venture for Offshore Wind Interconnection Hardware | Accesses salt-fog-rated silicone rubber specifications demanded by Massachusetts-to-North Carolina lease auctions. |
| Digital Twin Platform Integration | Opens predictive maintenance revenue streams through sensor-embedded intelligent insulators for transmission asset managers. |
| Capacity Expansion in Texas ERCOT Corridor | Aligns manufacturing footprint with state PUC rate-case resilience carve-outs and Permian Basin renewable zones. |
Research Approach
A spread of perspectives from utility procurement directors, transmission planning engineers, polymer compounding specialists, and live-line service contractors converged on the working assumptions. Primary fieldwork combined structured interviews with IEEE working group participants and FERC compliance officers. Secondary validation drew from EIA grid investment databases, NERC reliability standard filings, state PUC rate-case documentation, and customs records tracking insulator hardware imports. Bottom-up unit economics triangulated against top-down transmission investment forecasts.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions encompassed material composition, voltage class, installation environment, and end-user procurement sophistication. CAGRs derived from utility capital expenditure trajectories and renewable interconnection queue data. Industry-specific inputs included NERC CIP compliance cost estimates and silicone rubber feedstock price indices.
Sensitivities concentrate around IEEE material qualification timeline delays, Gulf Coast petrochemical disruption frequency, and state-level renewable portfolio standard acceleration or relaxation. Cross-checking against EIA Annual Energy Outlook transmission investment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
North America Thermal Protector Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
Global Panelboards Market