
 Middle East and Africa Busbar Market | 2026-2036
Middle East and Africa Busbar Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Busbar Market Foresight
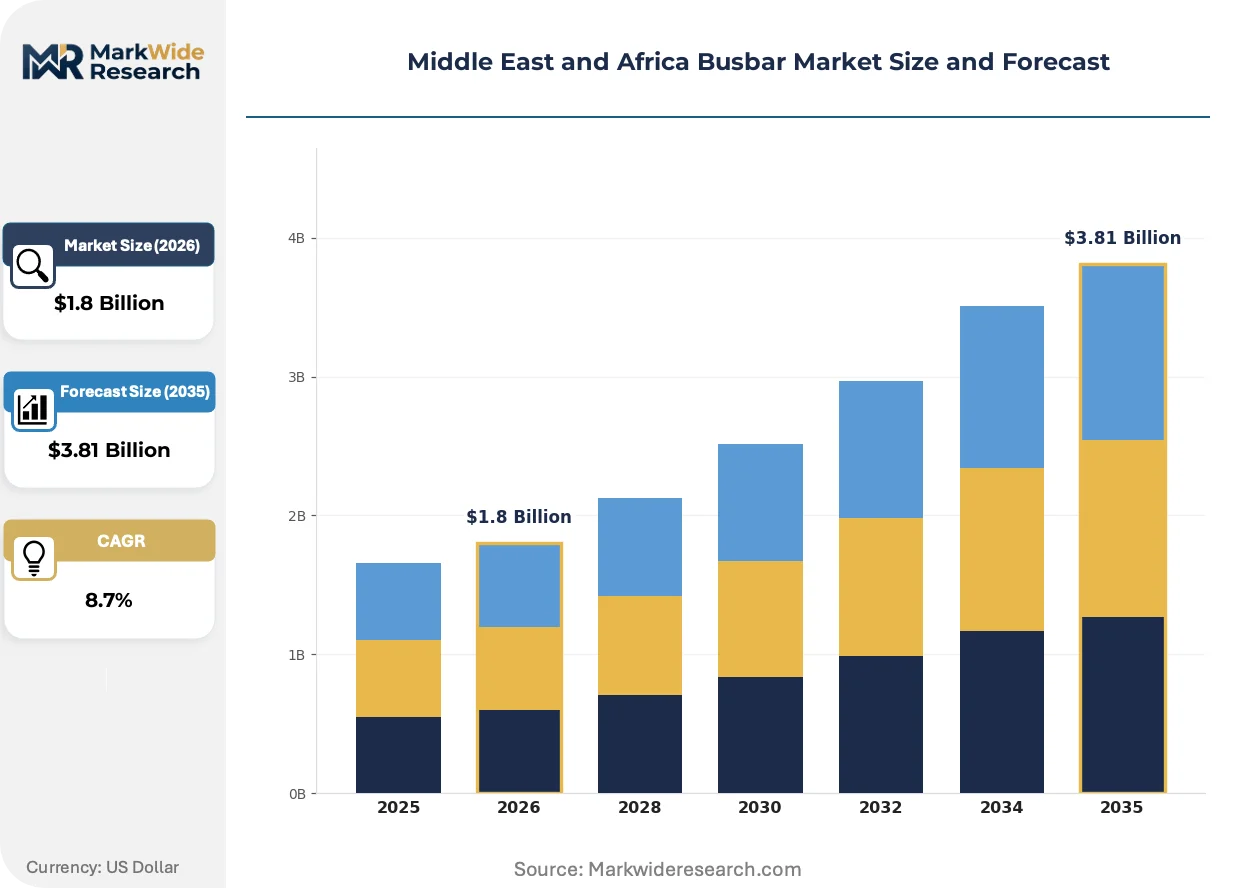
Copper smelter expansions in Zambia and the Democratic Republic of Congo are rebalancing raw material availability for regional busbar fabricators. Schneider Electric SE leverages its Gulf distribution network to anchor medium-voltage projects across Saudi Arabia and the UAE. ABB Ltd sustains technology leadership in gas-insulated busbar systems for desert climate installations. Siemens AG competes on digital busbar monitoring integration with substation automation platforms.
A busbar is a metallic strip or bar, typically copper or aluminum, engineered to conduct substantial electrical current within switchgear, distribution boards, and substations; manufacturers often extrude or roll-form these conductors to precise conductivity and thermal tolerance specifications. The primary purpose is to consolidate power distribution paths, reducing connection complexity while managing heat dissipation in high-amperage environments. Insulated busbars command premium positioning in data center and healthcare applications where arc-fault containment is non-negotiable, while aluminum material grades gain share in utility-scale solar installations across North Africa where weight and cost efficiency outweigh conductivity optimization. Copper still dominates industrial end-user specifications in South Africa's mining and petrochemical corridors.
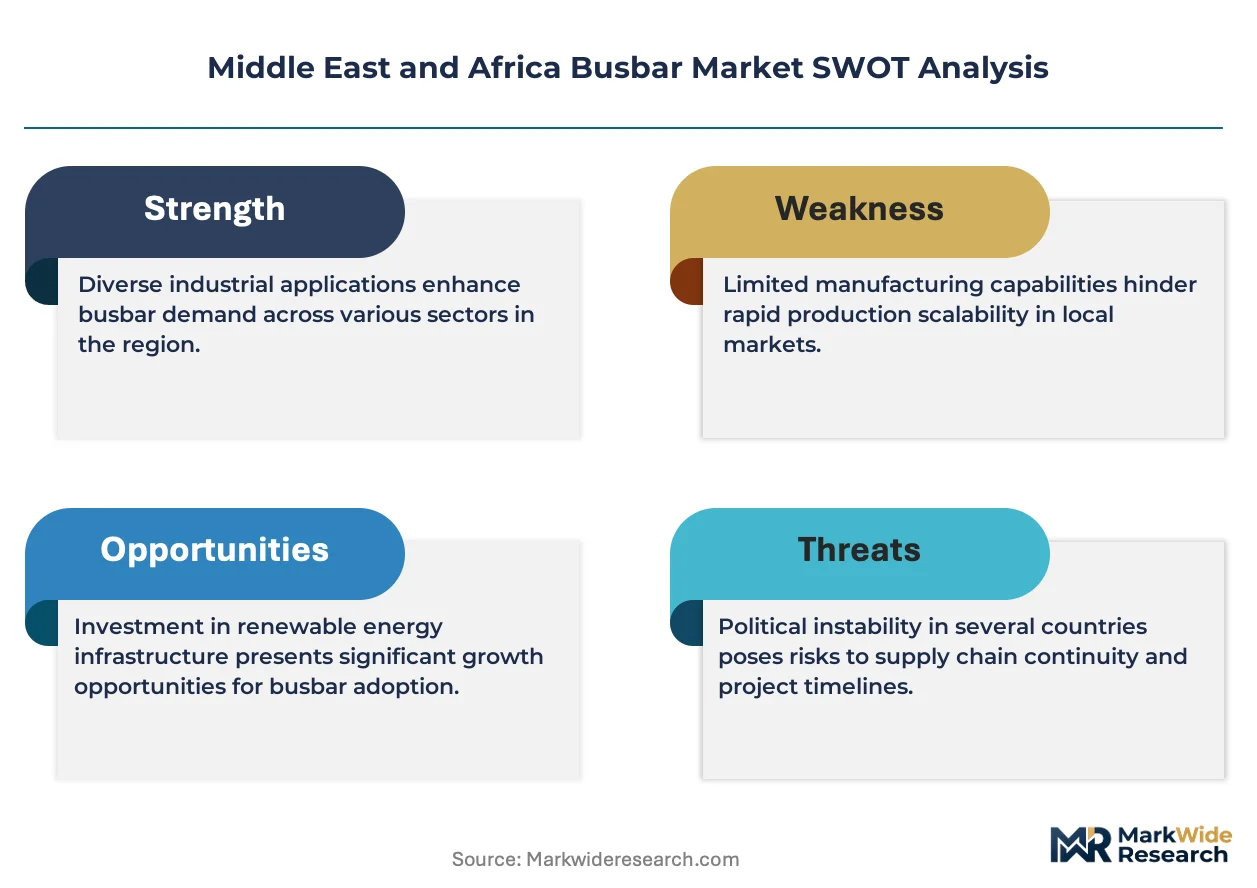
Saudi Arabia's Saudi Standards, Metrology and Quality Organization mandates busbar thermal cycling tests for grid-connected renewable projects, effectively filtering out uncertified imports. The UAE's Emirates Authority for Standardization and Metrology enforces IEC-equivalent short-circuit withstand ratings for Dubai's megaproject electrical infrastructure. South Africa's National Regulator for Compulsory Specifications maintains compulsory safety marks for low-voltage busbar assemblies used in mining operations. Stakeholders must monitor how Gulf sovereign wealth fund commitments to domestic manufacturing reshape supplier qualification criteria and local content thresholds.
Market Dynamics
Data center power density thresholds across the Gulf Cooperation Council are forcing copper-intensive busbar specifications into procurement contracts, compressing supplier qualification timelines and rewiring competitive positioning toward thermal performance guarantees.
Growth Catalysts
- Renewable energy mandates:Saudi Arabia's national regulator enforces copper busbar specifications for grid-connected solar projects, accelerating thermal cycling certification requirements for all imported assemblies.
- Data center clustering:Dubai South logistics corridor and Abu Dhabi's Masdar City are aggregating hyperscale facility construction, concentrating medium-voltage busbar demand across three concurrent megaprojects.
- Copper smelter expansion:Zambia and the Democratic Republic of Congo are expanding raw material availability, shortening lead times for regional fabricators serving East African utility-scale solar installations.
Market Restraints
- Input cost volatility:Copper concentrate supply disruptions from Central African copperbelt operations create margin compression for extrusion-dependent fabricators lacking long-term offtake agreements.
- Technical limitation:Aluminum conductivity gaps persist in high-amperage industrial specifications, locking South African mining and petrochemical corridors into copper-only procurement despite weight penalties.
- Regulatory friction:Saudi Standards, Metrology and Quality Organization thermal cycling test mandates filter uncertified imports, extending supplier qualification timelines by 8-14 months for new market entrants.
Strategic Opportunities
- Underpenetrated geography:Egypt's New Administrative Capital smart grid deployment represents uncontracted medium-voltage busbar volume for IEC-certified suppliers with desert climate installation experience.
- Regulatory tailwind:UAE Emirates Authority for Standardization and Metrology short-circuit withstand rating enforcement is compressing procurement toward pre-certified suppliers with established Gulf distribution networks.
- Technology convergence:Gas-insulated busbar systems are integrating digital monitoring platforms, creating bundled offering potential for substation automation providers targeting Saudi Aramco infrastructure upgrades.
Industry Challenges
- Certification timeline compression:South Africa's National Regulator for Compulsory Specifications compulsory safety mark requirements for mining-sector low-voltage assemblies extend product launch cycles by 10-16 months.
- Capex intensity:Extrusion press capacity expansion for copper alloy busbar production requires $12-18 million per production line, concentrating fabrication capability among sovereign wealth fund-backed domestic manufacturing initiatives.
- Integration complexity:Legacy switchgear retrofit specifications across UAE federal infrastructure projects demand custom busbar bending and coating protocols that fragment production runs and elevate tooling costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Busbar Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Busbars, Bare Busbars, Modular Busbars, Hybrid Busbars Installation Type: Indoor, Outdoor, Rail-mounted, Free-standing End User: Industrial Sector, Commercial Sector, Utilities, Residential Sector Material: Copper, Aluminum, Steel, Others |
| Companies Covered | Schneider Electric SE, ABB Ltd, Siemens AG, Eaton Corporation PLC, Mersen SA, Rittal GmbH & Co. KG, Nexans S.A., Legrand SA, TE Connectivity, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Busbar Market Shifts & Advancements
Digital monitoring integration is compressing the traditional separation between power distribution hardware and substation automation software, forcing busbar manufacturers toward embedded sensor partnerships.
Cast resin insulated busbar systems are unifying arc-fault containment with reduced footprint requirements. Data center operators across the UAE and Saudi Arabia are specifying these assemblies for hyperscale facilities where space constraints intersect with zero-tolerance reliability mandates. The technology is unifying what were previously separate procurement streams for busbar and switchgear into single-vendor accountability structures.
Saudi Standards, Metrology and Quality Organization thermal cycling test mandates for grid-connected renewable projects are compressing supplier pools to pre-certified manufacturers. Industrial consequence includes accelerated qualification investment by regional distributors seeking to maintain project eligibility. Medium-voltage specifications for Saudi Aramco solar procurement are most affected, with respondents consolidating toward suppliers with established in-country testing partnerships.
Consolidated procurement frameworks are displacing fragmented project-by-project purchasing across Gulf sovereign wealth fund infrastructure mandates. Engineering-procurement-construction contractors are losing discretion to specify busbar suppliers independently as owner-operators centralize vendor qualification. This pattern is most visible in Abu Dhabi's Masdar City clean energy cluster where single-source agreements now cover multi-project busbar volumes.
Middle East and Africa Busbar Market Segmentation
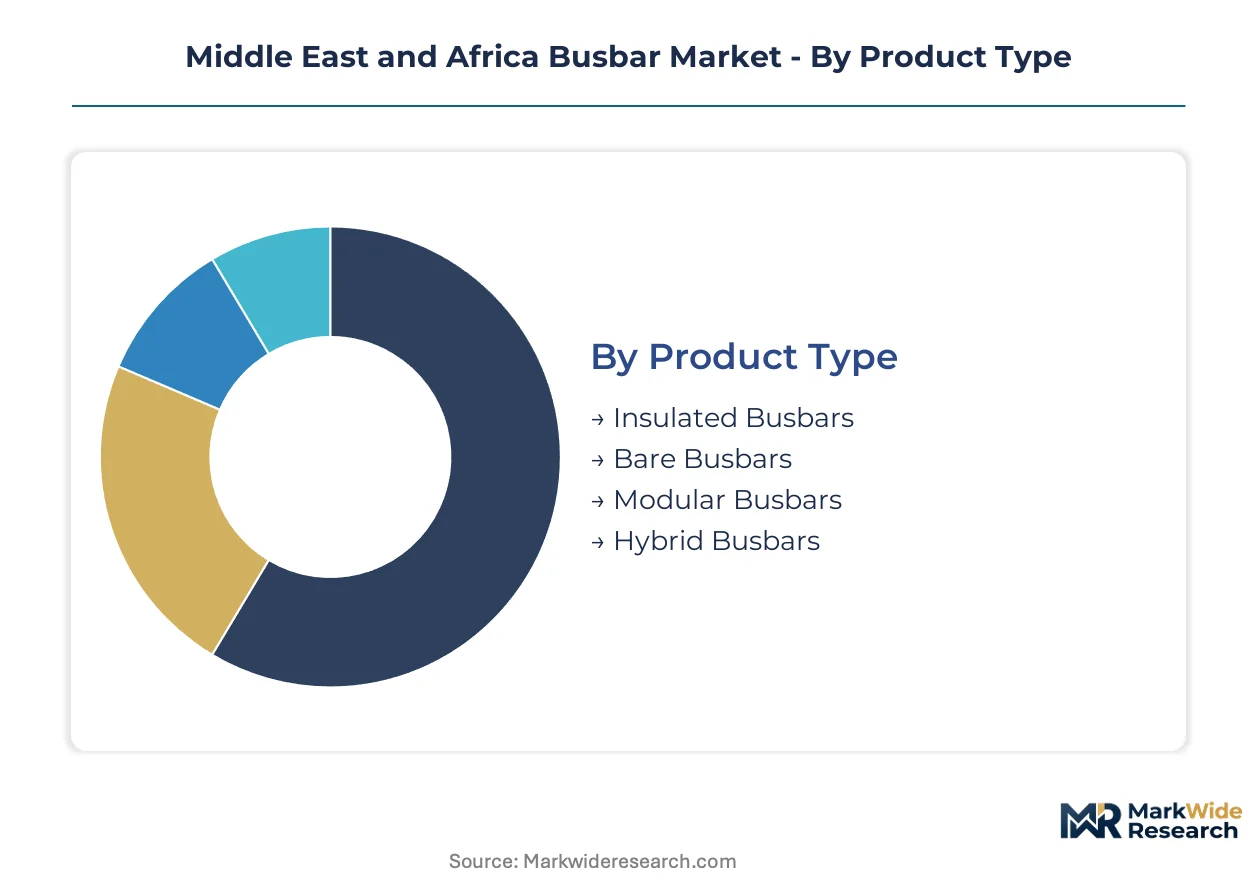
Busbar procurement patterns across the Middle East and Africa diverge sharply by installation environment and end-use criticality. Upgrade cycles in Saudi Aramco infrastructure and Dubai South data centers are compressing specification timelines, forcing suppliers to align product portfolios with distinct thermal and spatial constraints.
Product Type:
Replacement cycles for legacy switchgear across Gulf utilities are accelerating demand for pre-certified insulated and modular configurations that reduce installation downtime.
- Insulated Busbars:Cast resin and epoxy-coated assemblies enclose conductors to prevent arc faults and environmental contamination. Dubai's hyperscale data centers specify these for medium-voltage distribution where space constraints eliminate separate switchgear enclosures. SFDA-equivalent thermal cycling certifications from Saudi Standards, Metrology and Quality Organization filter supplier pools to pre-qualified manufacturers.
- Modular Busbars:Plug-in segment designs enable rapid capacity scaling without full system replacement. Abu Dhabi's Masdar City clean energy cluster deploys these for solar farm interconnection where phased commissioning demands flexible busbar reconfiguration.
- Bare Busbars:Uninsulated copper or aluminum strips serve cost-sensitive utility-scale solar installations across Egypt and Morocco where environmental protection is handled at the enclosure level.
- Hybrid Busbars:Composite aluminum-copper constructions balance conductivity with weight reduction for rooftop commercial installations in South African mining corridors.
Insulated busbars sit at the top of the volume ranking, with modular configurations climbing the fastest as Gulf megaprojects prioritize installation speed.
Installation Type:
Cost tier differentiation separates premium indoor specifications from economy outdoor deployments where environmental sealing determines lifecycle economics.
- Indoor:Climate-controlled switchgear applications dominate Saudi petrochemical and UAE healthcare facilities where dust infiltration risks equipment failure. SFDA mandates specify IP54 minimum ingress protection for grid-connected renewable projects.
- Outdoor:Desert climate installations across North Africa require sand-resistant coatings and expanded thermal cycling ranges. Egyptian New Administrative Capital smart grid deployments specify these for substation yard layouts.
- Rail-mounted:Mobile power distribution for temporary construction camps and mining operations in Zambia and the Democratic Republic of Congo favors standardized rail interfaces.
- Free-standing:Isolated phase busbar configurations serve high-amperage industrial corridors in South Africa where seismic isolation and maintenance access drive specification.
Outdoor installations command the largest project volumes, though rail-mounted systems are expanding most quickly across East African extractive industries.
End User:
Application maturity varies sharply across customer types, with industrial procurement standardizing faster than fragmented residential electrification programs.
- Industrial Sector:Mining and petrochemical operations in South Africa's Northern Cape and Saudi Arabia's Eastern Province specify copper-intensive busbars for continuous high-amperage duty. SFDA compulsory safety marks extend qualification timelines but lock in supplier relationships.
- Utilities:National grid operators across Egypt, Morocco, and the UAE consolidate procurement through sovereign wealth fund frameworks. Medium-voltage specifications for Saudi Aramco solar procurement favor gas-insulated systems with embedded monitoring.
- Commercial Sector:Retail and office developments in Dubai South logistics corridor specify aluminum busbars where weight reduction enables rooftop transformer placement.
- Residential Sector:Low-voltage distribution boards for mass housing in Egypt and Nigeria drive high-volume, low-margin bare busbar demand with minimal customization.
Industrial end users generate the steepest revenue concentration, while utility procurement is gaining share fastest through consolidated megaproject frameworks.
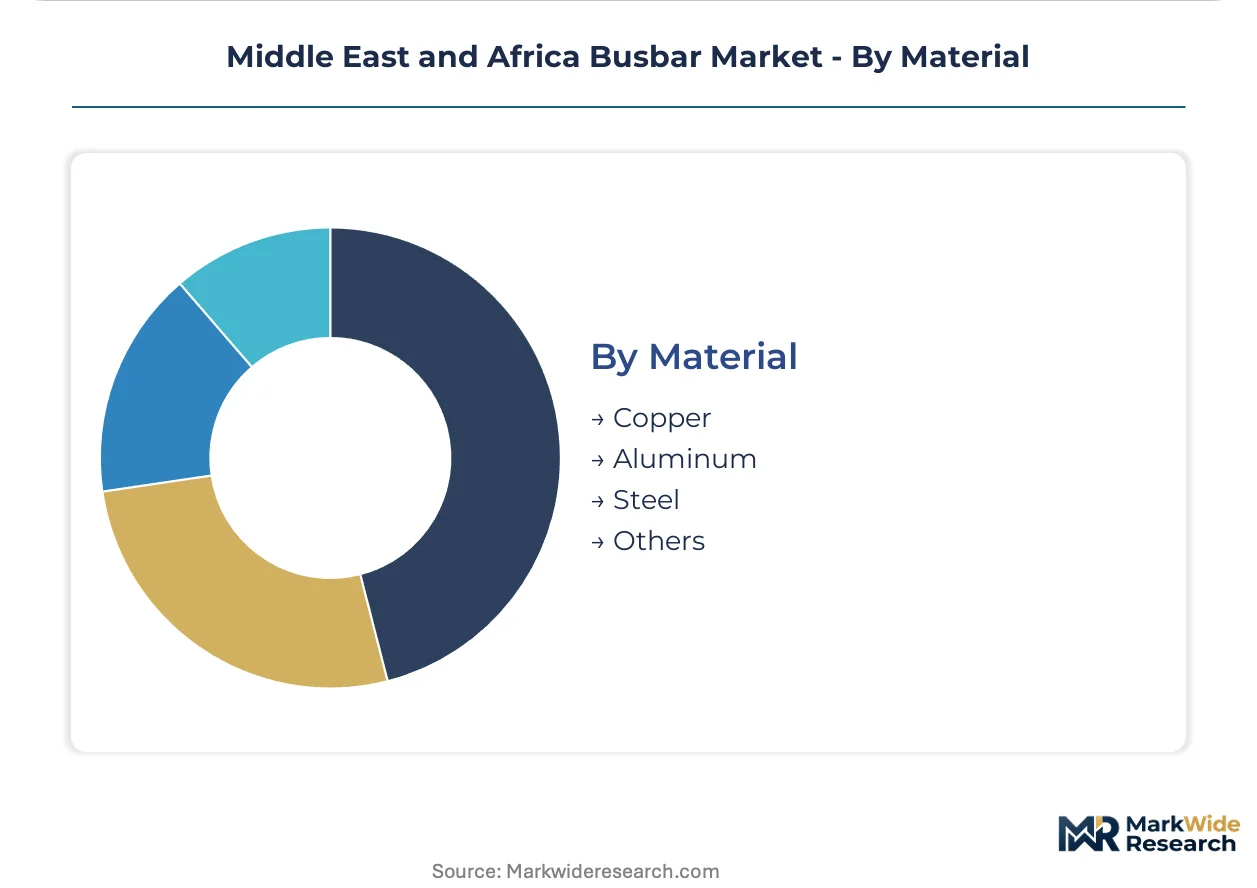
Material:
Supply concentration in Central African copperbelt operations directly shapes regional fabrication economics and procurement lead times.
- Copper:High-conductivity electrolytic grades dominate industrial specifications where thermal tolerance is non-negotiable. Zambia and Democratic Republic of Congo smelter expansions are shortening lead times for regional fabricators serving East African markets.
- Aluminum:Lightweight alloys capture utility-scale solar installations across North Africa where transport costs and structural loading outweigh conductivity penalties. Emirates Authority for Standardization and Metrology short-circuit withstand ratings apply equally regardless of base material.
- Steel:Galvanized structural busbars serve grounding and low-current distribution in rural electrification programs where cost minimization overrides performance optimization.
- Others:Silver-plated and tin-coated specialty conductors address high-frequency switching applications in data center power distribution units.
Copper retains the dominant volume position, with aluminum gaining share fastest as North African solar deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE dominate procurement volumes, while Egypt and South Africa concentrate specialized industrial demand. Copper supply expansions in Central Africa are shortening lead times for East African fabricators.
Saudi Arabia
Riyadh's megaproject pipeline and Eastern Province petrochemical corridors drive copper-intensive busbar specifications. Saudi Standards, Metrology and Quality Organization mandates thermal cycling tests for grid-connected renewable projects. NEOM Northwest and Red Sea Project developments are consolidating procurement through sovereign wealth fund frameworks.
United Arab Emirates
Dubai South logistics corridor and Abu Dhabi's Masdar City cluster aggregate hyperscale data center construction. Emirates Authority for Standardization and Metrology enforces IEC-equivalent short-circuit withstand ratings. Dubai's federal infrastructure retrofit programs demand custom busbar bending protocols for legacy switchgear integration.
South Africa
Northern Cape mining operations and Eastern Cape petrochemical facilities specify copper-only busbars for high-amperage continuous duty. National Regulator for Compulsory Specifications maintains compulsory safety marks for low-voltage mining assemblies. Johannesburg-Pretoria industrial corridor suppliers face 10-16 month certification cycles for new product launches.
Egypt
New Administrative Capital smart grid deployment and utility-scale solar installations across the Western Desert create uncontracted medium-voltage volume. The country's national electrical regulator aligns with IEC standards for desert climate installations. Cairo-Alexandria industrial belt fabricators are expanding extrusion capacity to serve North African solar markets.
Zambia and Democratic Republic of Congo
Copperbelt smelter expansions are rebalancing raw material availability for regional busbar production. National mining regulators in both jurisdictions enforce environmental compliance for concentrate processing operations. Lusaka and Lubumbashi fabrication hubs are shortening lead times for East African utility-scale solar procurement.
Middle East and Africa Busbar Market Competitive Landscape
Gulf-based producers anchor the premium tier; European specialists hold technology leadership in insulated systems. Market structure concentrates around three to five integrated electrical equipment conglomerates with established certification partnerships. Two strategic archetypes dominate: full-suite power distribution providers and copper-intensive fabrication specialists. Competitive moves center on extrusion press capacity expansion and digital monitoring platform integration.
Within the full-suite provider tier, Schneider Electric SE, ABB Ltd, and Siemens AG exemplify divergent positioning strategies. Schneider Electric SE occupies a position anchored in Gulf distribution networks for medium-voltage project execution. ABB Ltd represents technology leadership in gas-insulated systems adapted for desert climate specifications. Siemens AG exemplifies the convergence trajectory between hardware fabrication and substation automation software integration.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Siemens AG |
| Eaton Corporation PLC |
| Mersen SA |
| Rittal GmbH & Co. KG |
| Nexans S.A. |
| Legrand SA |
| TE Connectivity |
| Others |
Supply & Pricing Matrix
Gulf sovereign wealth fund procurement consolidation anchors pricing power toward pre-certified suppliers with established in-country testing partnerships, compressing margin structures for uncertified imports while rewarding thermal performance guarantees.
Pricing Analysis
Capacity additions in Zambia and the Democratic Republic of Congo are reshaping price floors for copper-intensive specifications across East African markets. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-certified insulated assemblies from bare copper strips for utility-scale solar. Price differentiation hinges on thermal cycling certification grade and volume scale of sovereign wealth fund offtake agreements. Cost compression in economy-tier bare aluminum busbars is intensifying because Egyptian and Moroccan solar developers prioritize transport efficiency over conductivity optimization. Industrial mining procurement in South Africa's Northern Cape shows least price sensitivity due to compulsory safety mark requirements that lock in supplier relationships.
Supply Chain Analysis
Refurbishment flows for legacy switchgear across UAE federal infrastructure projects are creating secondary copper recovery channels that supplement primary concentrate supply. Raw material sourcing draws from Zambian and Congolese smelter expansions, Egyptian extrusion capacity buildouts, and South African fabrication hubs serving mining corridors. Copper concentrate supply disruptions from Central African copperbelt operations present single-source vulnerability for regional fabricators lacking long-term offtake agreements. Distribution runs through Schneider Electric's Gulf distribution network, ABB's desert climate installation partnerships, and Siemens' substation automation integration channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily through embedded infrastructure replacement cycles across Gulf megaprojects and Central African copperbelt expansion.
For Market Incumbents: Deploy thermal cycling certification pre-qualification as a competitive moat. Deepen backward integration into Zambian and Congolese copper concentrate offtake to defend margin position against raw material volatility. Accelerate digital monitoring platform partnerships to counter emerging pure-play sensor vendors. Lock in sovereign wealth fund master service agreements before procurement centralization completes. For New Entrants and Emerging Players: Egyptian New Administrative Capital smart grid contractors represent the most penetrable buyer archetype for IEC-certified suppliers with desert climate installation experience. Rail-mounted busbar specifications for Zambian and Congolese mining operations offer white-space entry with lower certification barriers than Gulf megaprojects. Target East African utility-scale solar developers through regional fabricator partnerships rather than direct Gulf market entry. For Investors and Strategic Acquirers: Electrical equipment conglomerates with Gulf distribution networks are the most active acquirer in this space. Acquisition targets should display captive extrusion capacity in copperbelt-adjacent geographies and pre-existing SFDA or ESMA certification partnerships. Watch for Saudi Aramco solar procurement volume announcements as the signal indicating inflection in medium-voltage insulated busbar demand.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Partnership | Pre-qualifies suppliers for Saudi grid-connected renewable procurement mandates. |
| Copperbelt Smelter Integration | Captures raw material cost advantage for East African utility-scale solar fabricators. |
| Digital Monitoring Platform Embedding | Creates bundled hardware-software accountability for Saudi Aramco infrastructure upgrades. |
| Rail-Mounted Product Line Launch | Addresses mobile power distribution demand in Zambian and Congolese extractive industries. |
| Cast Resin Insulation Scale-Up | Meets Dubai hyperscale data center specifications for space-constrained arc-fault containment. |
Research Methodology
Direct dialogue with EPC contractors, utility procurement officers, copper smelter operations managers, and busbar fabrication plant engineers grounded qualitative assessment. Secondary validation drew from Saudi Standards, Metrology and Quality Organization filings, Emirates Authority for Standardization and Metrology technical regulations, South African National Regulator for Compulsory Specifications safety mark databases, and copper concentrate trade flow records. Bottom-up project pipeline enumeration and top-down electrical infrastructure spending analysis triangulated market sizing.
Segment-level projections across product type, installation environment, end-use sector, and base material grade fed into consolidated growth trajectories across the analysis window. CAGRs were derived from weighted average of replacement cycle timing, megaproject commissioning schedules, and raw material supply expansion curves. Forecast inputs included Saudi Aramco renewable procurement timelines, Dubai South data center power density specifications, and Central African copperbelt smelter capacity ramp schedules.
Underlying measurement precision varies by segment; utility and industrial end-use categories carry tighter precision than fragmented residential electrification. Forecasts reflect assumptions around sovereign wealth fund procurement centralization pace and copper concentrate supply continuity. Periodic stress-testing of base assumptions against regulatory timeline slippage and raw material disruption scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Global Busbar Trunking Market
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
Modular Contactor Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
Terminal Block Market
Electrical Equipment
Smart Heater Market