
 3D Technology Market | 2026-2036
3D Technology Market Size, Share, and Industry Trends Forecast 2026-2036
3D Technology Market Analysis
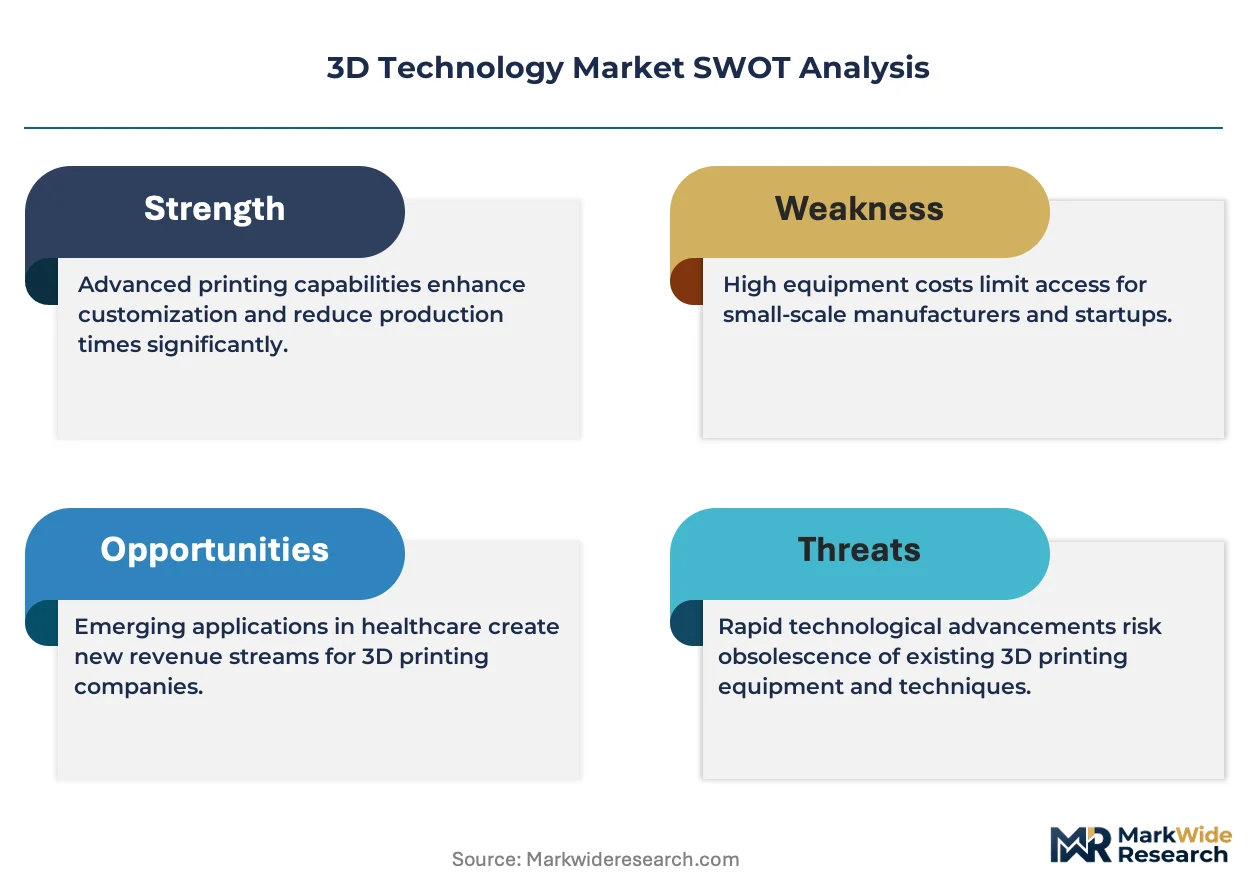
The capability gap between capital-heavy metal sintering specialists and desktop polymer entrants is bifurcating competitive dynamics across the 3D Technology landscape. EOS GmbH leverages its laser-sintering installed base to dominate aerospace qualification programs. HP Inc anchors polymer production-scale systems through its Multi Jet Fusion platform. Materialise NV differentiates via software-to-manufacturing workflow integration across medical and industrial verticals.
3D technology encompasses additive manufacturing hardware, volumetric capture systems, spatial computing software, and stereoscopic display apparatus that construct or render three-dimensional objects from digital models. Fused Deposition Modeling systems process thermoplastic filaments through heated extrusion nozzles at layer resolutions typically ranging from 50 to 400 microns, serving prototyping and short-run production needs across automotive and consumer goods sectors. Stereolithography retains margin concentration in dental and jewelry applications where surface finish precision commands premium pricing. Selective Laser Sintering leads industrial polymer production for functional aerospace ducting and under-hood automotive components.
The FDA's 3D-printed medical device guidance and the EU Medical Device Regulation impose biocompatibility and traceability requirements that filter market access for implant-grade manufacturers. REACH chemical restrictions in Europe constrain powder feedstock formulations, particularly for nylon-12 and TPU materials used in Selective Laser Sintering. China's NMPA and GB standards for custom medical devices are tightening documentation requirements for patient-matched orthopedic implants. Stakeholders must monitor evolving qualification protocols as aviation authorities in the United States and Europe advance certification pathways for flight-critical printed components.
Market Dynamics
Patient-matched orthopedic implants are compressing development timelines from months to weeks, forcing hardware manufacturers to integrate software workflows and biocompatible material certification into unified service offerings.
Growth Catalysts
- EU Medical Device Regulation:Mandatory traceability requirements for implant-grade devices are filtering out non-compliant suppliers and consolidating demand among qualified manufacturers with validated quality systems.
- Titanium lattice structures:Aerospace airframe manufacturers are qualifying topology-optimized brackets and ducting that reduce weight while maintaining load-bearing capacity for flight-critical applications.
- Automotive prototyping clusters:Short-run tooling for electric vehicle battery housings and thermal management components is concentrating demand in Germany's industrial additive manufacturing corridor.
Market Restraints
- Metal powder feedstock volatility:Titanium and nickel-based superalloy powder prices fluctuate with aerospace demand cycles, squeezing margins for contract manufacturers without long-term supply agreements.
- Post-processing bottleneck:Support removal, surface finishing, and heat treatment steps consume 60-70% of total production time, limiting throughput scaling for production-scale metal sintering operations.
- REACH chemical restrictions:European formulations of nylon-12 and TPU powders face compliance-driven reformulation costs that disadvantage smaller material suppliers against integrated chemical conglomerates.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives for custom implants and surgical instruments are attracting technology transfer partnerships from established European and North American equipment suppliers.
- Volumetric capture convergence:Integration of photogrammetry and LiDAR scanning with real-time mesh optimization is opening point-of-care anatomical modeling in hospital radiology departments.
- China's NMPA custom device pathway:Streamlined documentation for patient-matched orthopedic implants is accelerating market access for software-integrated manufacturing platforms with localized regulatory expertise.
Industry Challenges
- Multi-material certification timelines:Aviation authorities in the United States and Europe require extensive fatigue testing data for flight-critical printed components, extending qualification cycles beyond typical product development windows.
- Workflow software integration:Hospitals and contract manufacturers struggle to bridge proprietary CAD formats, build preparation slicers, and quality management systems into seamless digital threads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Technology Market |
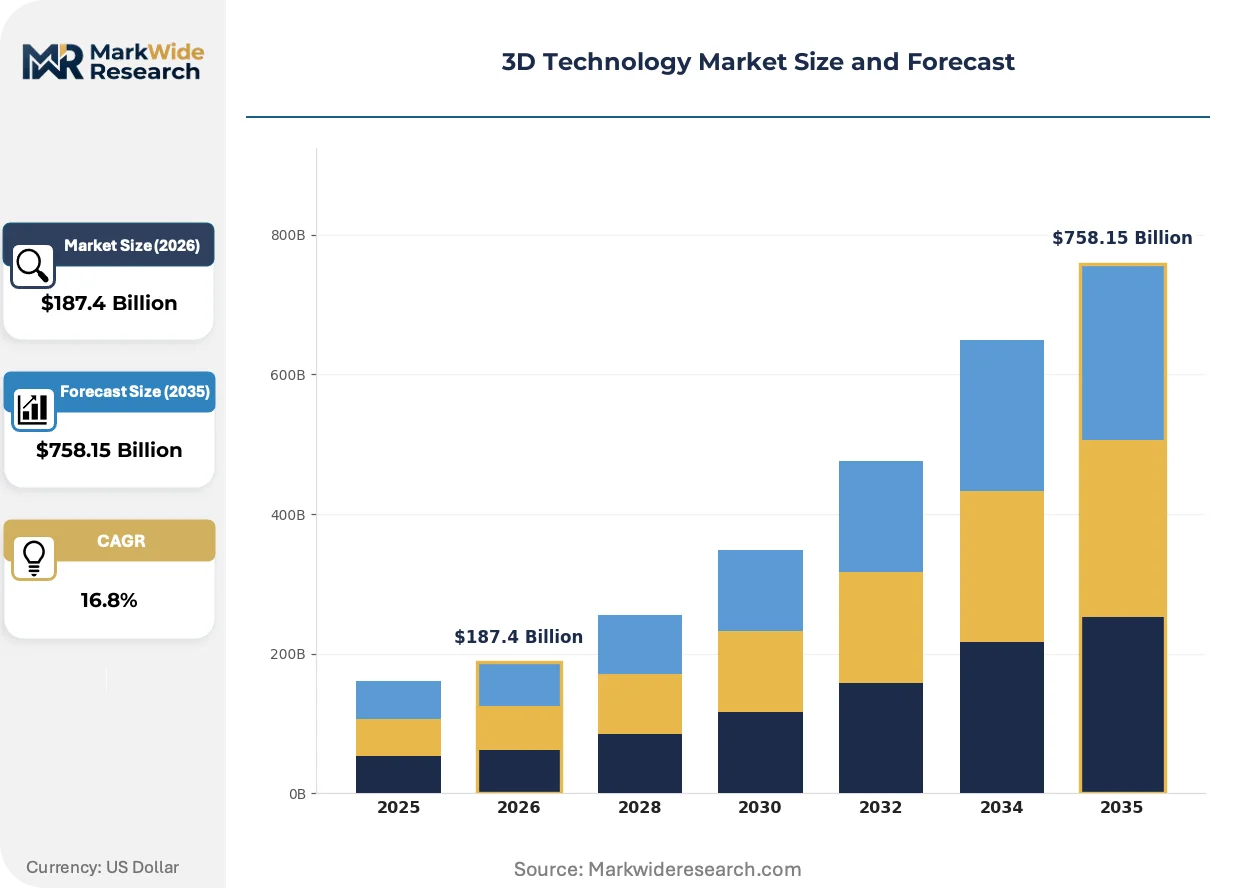
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Printers, 3D Scanners, 3D Software, 3D Glasses Application: Aerospace, Automotive, Healthcare, Education End User: Manufacturers, Designers, Researchers, Retailers Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Multi Jet Fusion |
| Companies Covered | Stratasys Ltd, 3D Systems Inc, Autodesk Inc, HP Inc, Samsung Electronics, Dassault Systèmes, EOS GmbH, Materialise NV, Hexagon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Technology Market Emerging Trajectories
Metal additive manufacturing is splitting into two distinct capability tiers while regulatory frameworks harden quality assurance requirements and buyer procurement models favor integrated solution providers over standalone equipment vendors.
Continuous liquid interface production is bifurcating dental and jewelry manufacturing from conventional vat polymerization. Dental laboratories in the United States and Germany are adopting mask-projection systems that cure entire layers in seconds rather than tracing perimeters with laser spots. This speed advantage is compressing unit economics for clear aligner mold production and enabling same-day crown fabrication that displaces centralized milling operations.
The FDA's 3D-printed medical device guidance framework is formalizing biocompatibility documentation requirements for powder bed fusion implants. Device manufacturers must now submit particle release testing and sterilization validation data alongside mechanical property specifications. Orthopedic implant suppliers with captive powder atomization and in-house testing capabilities are capturing preference from hospitals seeking single-source accountability.
Point-of-care anatomical modeling is restructuring radiology department capital allocation across major hospital networks. Surgeons in Germany and the United States now request patient-specific organ replicas for complex oncology and cardiovascular procedures, displacing traditional two-dimensional imaging review. Medical centers are consolidating procurement through integrated hardware-software-service contracts rather than acquiring standalone printers and contracting external segmentation support.
3D Technology Market Segmentation
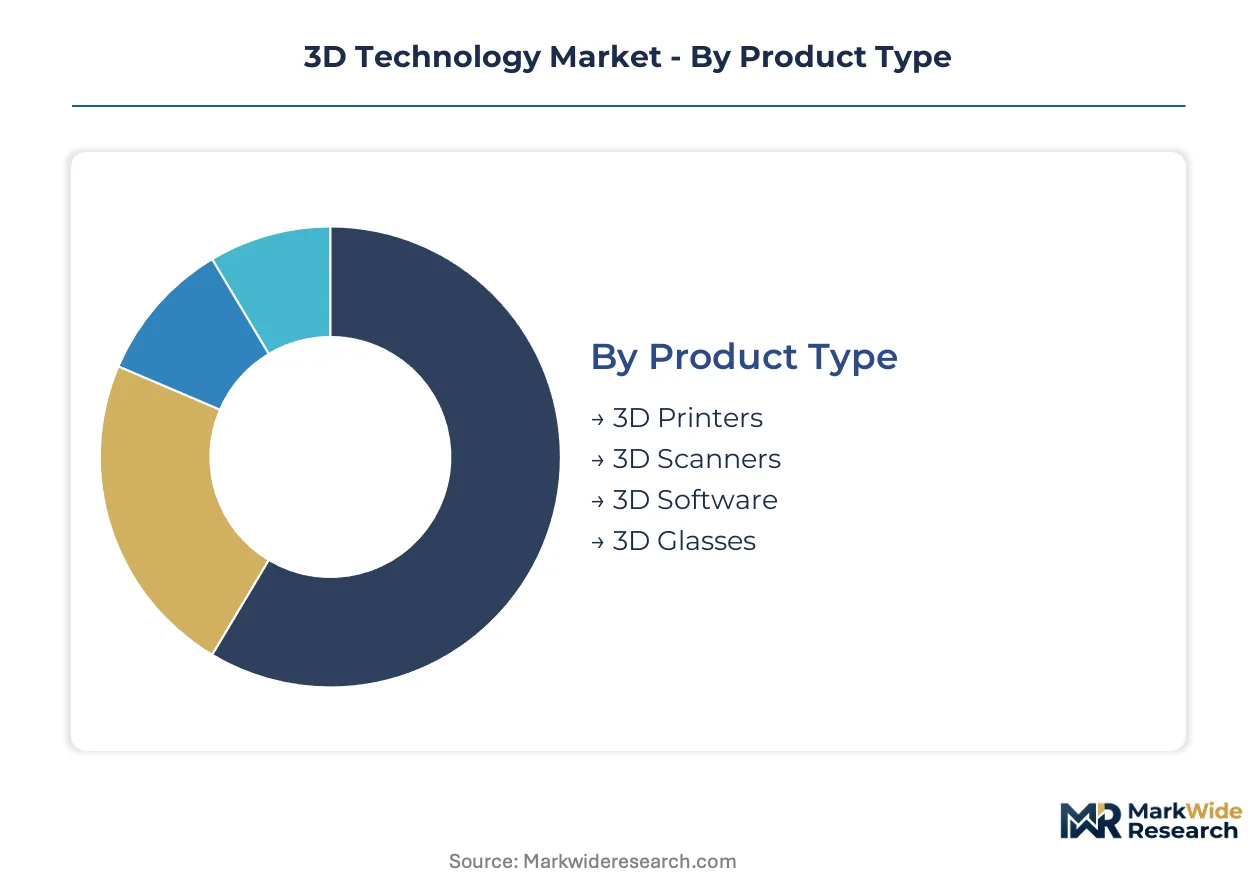
Segmentation in the 3D Technology Market reveals how hardware, software, and service layers command divergent margin profiles. Understanding where value concentrates across product types, applications, and technology tiers enables stakeholders to prioritize capability investments and partnership strategies.
Product Type:
Margin pools concentrate in integrated systems where hardware-software lock-in creates recurring revenue streams rather than one-time equipment sales.
- 3D Printers:Industrial metal and polymer systems process titanium, aluminum, and engineering-grade thermoplastics through powder bed fusion and material extrusion architectures. Demand clusters in Germany's automotive corridor and the United States aerospace manufacturing belt, where production-scale throughput justifies capital expenditure against per-part economics.
- 3D Scanners:Structured light and laser triangulation devices capture sub-millimeter geometric fidelity for reverse engineering and quality assurance workflows. Healthcare networks in the United States and Germany are deploying handheld units for point-of-care anatomical modeling, compressing the digital thread from patient scan to surgical guide.
- 3D Software:Build preparation, topology optimization, and mesh repair platforms license through subscription models that embed deeply into manufacturing workflows.
- 3D Glasses:Active shutter and passive polarized eyewear serves stereoscopic visualization in design review and medical imaging applications.
The dominant share belongs to 3D Printers, while 3D Software is closing the gap fastest through recurring revenue conversion.
Application:
Application-level profitability tracks directly with regulatory barriers and certification timelines that filter supplier pools.
- Aerospace:Topology-optimized brackets, ducting, and fuel nozzles in titanium and nickel-based superalloys undergo exhaustive fatigue testing per FAA and EASA qualification protocols. Boeing and Airbus supply chains in the United States and France are qualifying flight-critical printed components, extending development cycles but securing long-term supplier relationships.
- Healthcare:Patient-matched orthopedic implants and surgical guides require FDA 510(k) or EU MDR conformity assessment for biocompatibility and sterilization validation. German hospital networks are consolidating procurement through integrated hardware-software-service contracts that displace standalone equipment purchases.
- Automotive:Short-run tooling and thermal management prototypes for electric vehicle platforms concentrate demand in prototyping clusters.
- Education:Desktop polymer systems and curriculum licenses serve vocational training and university research programs.
Aerospace commands the premium pricing tier, though Healthcare is expanding most quickly through regulatory pathway maturation.
End User:
End-user economics diverge sharply between capital-intensive production environments and knowledge-work configurations.
- Manufacturers:Tier-1 suppliers and contract manufacturers operate industrial metal and polymer systems under ISO 9001 and AS9100 quality systems. Post-processing automation for support removal and surface finishing determines throughput economics at production scale.
- Designers:Industrial design studios and architectural firms deploy desktop stereolithography and material extrusion systems for form validation and client presentation models.
- Researchers:National laboratories and university engineering departments access multi-material and high-temperature systems through equipment grants and shared facility models.
- Retailers:Consumer-facing 3D printing services and bespoke product configurators operate on distributed manufacturing networks with localized fulfillment.
Manufacturers retain the largest equipment installed base, while Researchers are gaining share fastest through federal funding expansion.
Technology:
Technology-tier margins scale with materials versatility, build envelope size, and process control sophistication.
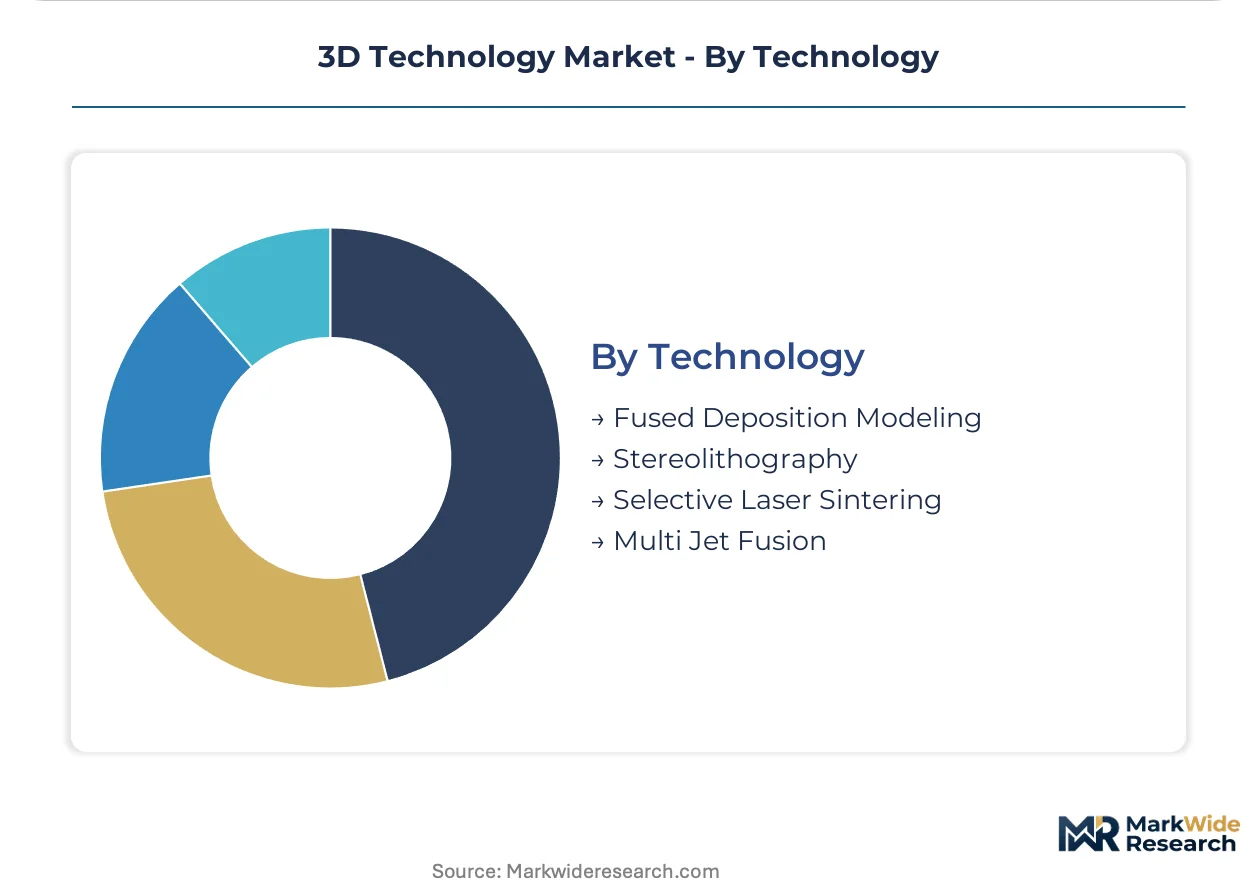
- Selective Laser Sintering:CO2 and fiber lasers fuse nylon-12, TPU, and polypropylene powders into functional ducting, housings, and medical devices without support structures. REACH chemical restrictions in Europe are reformulating powder feedstock compositions, advantaging integrated chemical suppliers over independent material vendors.
- Stereolithography:UV laser and mask-projection systems cure photopolymer resins at layer resolutions below 25 microns for dental crowns, jewelry patterns, and microfluidic devices. Dental laboratories in Germany and the United States are adopting continuous liquid interface production for same-day clear aligner mold fabrication.
- Fused Deposition Modeling:Heated extrusion nozzles deposit ABS, PLA, and engineering thermoplastics for prototyping and jigs at accessible price points.
- Multi Jet Fusion:Thermal inkjet arrays deposit fusing and detailing agents across polymer powder beds, enabling voxel-level control over mechanical properties.
Selective Laser Sintering holds the leading position, though Multi Jet Fusion is climbing the fastest through production-scale throughput gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial additive manufacturing clusters command 40-50% pricing premiums over Chinese contract manufacturers for aerospace-qualified titanium components. United States healthcare networks absorb similar premiums for FDA-validated patient-matched implants. This bifurcation reflects regulatory compliance costs and qualification timeline differentials rather than raw production economics.
United States
FAA qualification pathways for flight-critical printed components and FDA 510(k) medical device clearances concentrate demand among validated suppliers. The FDA's 3D-printed medical device guidance framework mandates particle release testing and sterilization validation data. Boeing and Lockheed Martin supply chains in Washington State and Texas are qualifying topology-optimized brackets for next-generation airframes.
Germany
Automotive prototyping clusters for electric vehicle thermal management components and industrial polymer production anchor demand. REACH chemical restrictions from ECHA reformulate nylon-12 and TPU powder feedstock compositions. EOS GmbH and Materialise NV anchor industrial additive manufacturing clusters in Bavaria and North Rhine-Westphalia, serving aerospace and medical device qualification programs.
China
NMPA streamlined documentation for patient-matched orthopedic implants accelerates market access for software-integrated manufacturing platforms. GB standards for custom medical devices tighten traceability requirements. Yangtze River Delta manufacturing hubs in Shanghai and Jiangsu province concentrate metal powder atomization capacity for domestic aerospace and medical implant supply chains.
India
PLI scheme domestic manufacturing incentives for custom implants and surgical instruments attract technology transfer partnerships. CDSCO medical device regulations align with international quality management system requirements. Maharashtra and Gujarat industrial corridors host emerging contract manufacturing facilities serving European and North American equipment suppliers.
Japan
METI industrial policy supports additive manufacturing adoption for precision components in automotive and electronics supply chains. PMDA quality management system requirements filter market access for implant-grade manufacturers. Nagoya and Osaka industrial zones concentrate metal sintering capacity serving Toyota and Honda prototyping programs.
3D Technology Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the 3D Technology landscape. Metal sintering specialists with aerospace qualification capabilities occupy premium pricing tiers, while polymer system vendors compete on production-scale throughput and unit economics. Three archetypes dominate: integrated hardware-software-service providers, standalone equipment manufacturers, and materials-captive contract manufacturers. Consolidation through strategic partnerships and vertical integration into powder feedstock production represent the dominant competitive vectors.
Among German laser-sintering specialists, EOS GmbH exemplifies the integrated hardware-materials archetype with captive powder atomization capabilities. HP Inc occupies a position at the production-scale polymer vector through its voxel-level control platform. Materialise NV represents the software-to-manufacturing workflow integration archetype, bridging proprietary CAD formats and quality management systems for medical and industrial verticals.
| Leading Market Players |
|---|
| Stratasys Ltd |
| 3D Systems Inc |
| Autodesk Inc |
| HP Inc |
| Samsung Electronics |
| Dassault Systèmes |
| EOS GmbH |
| Materialise NV |
| Hexagon |
| Others |
Supply Flow & Price Mechanics
Long-term powder offtake agreements between aerospace contract manufacturers and titanium atomization facilities in Germany and the United States lock in supply access and price visibility across volatile metal feedstock markets. These contracts insulate qualified suppliers from spot-market titanium powder fluctuations while embedding quality certification costs into multi-year pricing schedules.
Pricing Analysis
The customization-premium spread between patient-matched orthopedic implants and standard catalog devices runs three to five times base hardware pricing. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FDA-validated implant-grade systems commanding substantial premiums over prototyping-tier equipment. Cost compression in desktop polymer systems is intensifying because Chinese manufacturers are scaling production of material extrusion hardware. Contract manufacturers operating under AS9100 quality systems show lowest price sensitivity due to qualification timeline investments, while education and research buyers negotiate aggressively on per-unit hardware costs.
Supply Chain Analysis
Inbound logistics costs for titanium and nickel-based superalloy powders from atomization facilities in Germany and the United States to contract manufacturers in India and China fluctuate with container availability on Asia-Europe trade lanes. Powder feedstock production concentrates in Germany, the United States, and China, with Germany's EOS GmbH and the United States' Carpenter Technology anchoring premium alloy atomization capacity. The supply chain draws from specialized chemical precursors, precision laser optics, and high-purity gas systems. Single-source vulnerability in fiber laser componentry sourced from Germany and Japan creates qualification risk for new market entrants. Distribution runs through authorized reseller networks for industrial systems and direct e-commerce channels for desktop hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in software subscriptions and preventive maintenance contracts are expanding faster than hardware unit sales as hospitals and manufacturers prioritize operational continuity over capital expenditure minimization.
For Market Incumbents: Fortify captive powder atomization capabilities to defend margin position against emerging Chinese material suppliers. Lock in multi-year service contracts with German and United States hospital networks before NMPA-qualified competitors gain procurement preference. Invest in FDA 510(k) pathway expertise as regulatory documentation requirements harden quality system barriers.
For New Entrants and Emerging Players: Differentiate on point-of-care anatomical modeling workflows that compress radiology-to-surgical-guide timelines below incumbent offerings. Target India's PLI scheme corridors for technology transfer partnerships with domestic implant manufacturers. Pursue software-first go-to-market positioning that embeds build preparation and quality management tools before hardware placement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-to-manufacturing workflow integrators with hospital system penetration. Long-term viability across the analysis window favors acquisition targets with captive regulatory expertise in multiple jurisdictions. Watch for inflection signals in FAA qualification timelines for flight-critical printed components as certification pathway maturation accelerates aerospace adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Build preparation platforms from Materialise NV embed deeply into hospital radiology workflows. |
| Hospital System Partnership | Integrated hardware-software-service contracts with German networks displace standalone equipment procurement. |
| Backward Integration | Captive titanium powder atomization insulates EOS GmbH from feedstock price volatility. |
| Regulatory Approval Pathway | FDA 510(k) clearances for patient-matched implants filter supplier pools to qualified manufacturers. |
| Geographic Expansion | Technology transfer partnerships in India's Maharashtra corridor leverage PLI scheme incentives. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR conformity assessment databases, and hospital procurement contract records. Primary interviews engaged additive manufacturing hardware executives, biomedical engineers at German and United States hospital networks, regulatory affairs specialists navigating NMPA pathways, and contract manufacturing procurement leads. Secondary validation incorporated SEC filings from publicly traded equipment suppliers, REACH chemical restriction updates from ECHA, and trade data from German and Chinese customs authorities. Bottom-up unit economics modeling triangulated against top-down market sizing across technology tiers.
Segmentation dimensions modeled span product type, application vertical, end-user archetype, and technology tier across the projection horizon. Aerospace qualification status, healthcare regulatory pathway, and production-scale throughput capacity served as industry-specific forecast inputs. CAGRs derived from installed base expansion rates, replacement cycle analysis, and per-part cost convergence trajectories.
The analysis sits within stated boundaries; outcomes outside current FAA and FDA qualification timelines would require recalibration. Forecasts reflect assumptions about regulatory pathway maturation, powder feedstock price stability, and hospital capital allocation priorities. Practitioners should keep alternative scenarios live as aviation authority certification protocols and REACH chemical restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Global 3D Virtual Platform Market
3D Technology
Glasses Free 3D Tvs Market
3D Technology
3D Printing CAD Software Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
Molecular Modeling Market
3D Technology
Latin America 3D 4D Technology Market
3D Technology
Global 3D Rendering Service Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
Mobile 3D Market
3D Technology
Generative Design Market
3D Technology
3D Geospatial Technologies Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
3D CAD Market
3D Technology
North America 3D 4D Technology Market
3D Technology
Spatial Computing Market
3D Technology
Global 3D Architecture Software Market