
 3D Reconstruction Market | 2026-2036
3D Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
3D Reconstruction Market Analysis
A capital-intensity divergence between photogrammetry-focused software vendors and full-stack hardware integrators is reorganizing competitive dynamics in 3D reconstruction. Autodesk Inc. leverages its cloud-native design platform to embed reconstruction tools within existing AEC workflows. FARO Technologies Inc. sustains premium positioning through captive manufacturing of laser scanner hardware. Hexagon AB anchors its geographic footprint through sensor-to-software integration across surveying and metrology verticals.
3D reconstruction encompasses the computational derivation of three-dimensional geometry from two-dimensional image sequences, depth sensor arrays, or point cloud data, typically outputting mesh surfaces with sub-millimeter accuracy for engineering validation or immersive visualization. Photogrammetry dominates volume deployment due to minimal hardware requirements, while LIDAR commands premium applications demanding millimeter-grade precision in adverse lighting conditions. Services revenue pools concentrate around cultural heritage digitization and industrial asset inspection where specialized operator expertise creates margin protection.
FDA oversight of patient-specific anatomical models shapes healthcare application requirements, while FCC spectrum allocations govern LIDAR and time-of-flight sensor deployments in unmanned aerial systems. ISO standards for dimensional tolerancing and point cloud interoperability further constrain product architecture decisions across vendor ecosystems. Stakeholders must monitor regulatory divergence between medical device classification frameworks and geospatial data sovereignty laws as procurement criteria evolve.
Market Dynamics
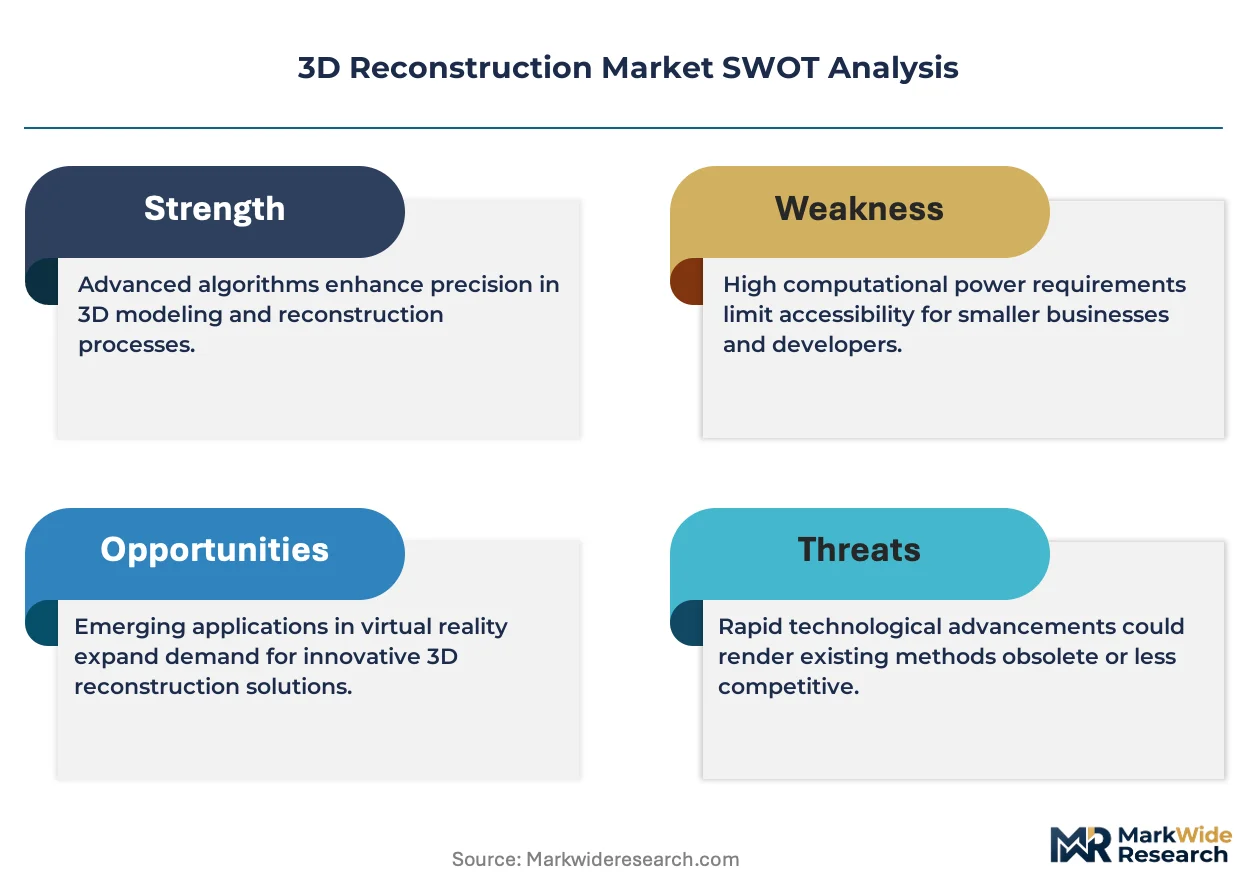
The convergence of photogrammetry algorithms with cloud-native processing architectures is compressing hardware barriers to entry while fragmenting value capture between software vendors and sensor manufacturers.
Growth Catalysts
- FDA 510(k) pathway for patient-specific anatomical models:Surgical planning departments in US hospitals now deploy 3D reconstruction for pre-operative visualization, creating recurring procurement cycles for reconstruction software licenses.
- Photogrammetry algorithm advances:Dense point cloud processing times have dropped substantially, enabling real-time reconstruction pipelines for drone-based surveying operations in construction and agriculture.
- Defense terrain mapping procurement:US Army Corps of Engineers and allied defense agencies sustain demand for millimeter-precision LIDAR systems across base infrastructure and battlefield simulation applications.
Market Restraints
- High-precision sensor cost concentration:Industrial-grade LIDAR units remain priced beyond mid-tier surveying firm budgets, capping addressable market expansion in emerging economies.
- Computational infrastructure requirements:Dense mesh generation from multi-gigabyte point clouds demands GPU clusters that smaller cultural heritage digitization studios cannot provision.
- Geospatial data sovereignty laws:Cross-border point cloud transmission faces restrictions under national security frameworks in China, Russia, and select Middle Eastern jurisdictions.
Strategic Opportunities
- Underpenetrated Indian infrastructure digitization:Smart city mandates under the Ministry of Housing and Urban Affairs create procurement windows for aerial survey reconstruction services across 100 designated urban agglomerations.
- Neural radiance fields (NeRF) convergence:The integration of neural rendering with traditional photogrammetry enables novel-view synthesis from sparse image captures, opening forensic and entertainment applications.
- EU CSRD-driven asset digitization:Corporate sustainability reporting requirements mandate granular facility documentation, pulling industrial reconstruction services into compliance budgets.
Industry Challenges
- Photogrammetrist talent scarcity:Specialized operators capable of managing ground control point networks and bundle adjustment workflows command premium compensation that squeezes service margins.
- ISO 19130-1 compliance timelines:Sensor model certification for geographic imagery delays product launches by 8-14 months, compressing competitive windows.
- Legacy CAD integration friction:Point cloud-to-BIM workflows require manual feature extraction that automation has not yet displaced, limiting throughput in AEC deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Reconstruction Market |
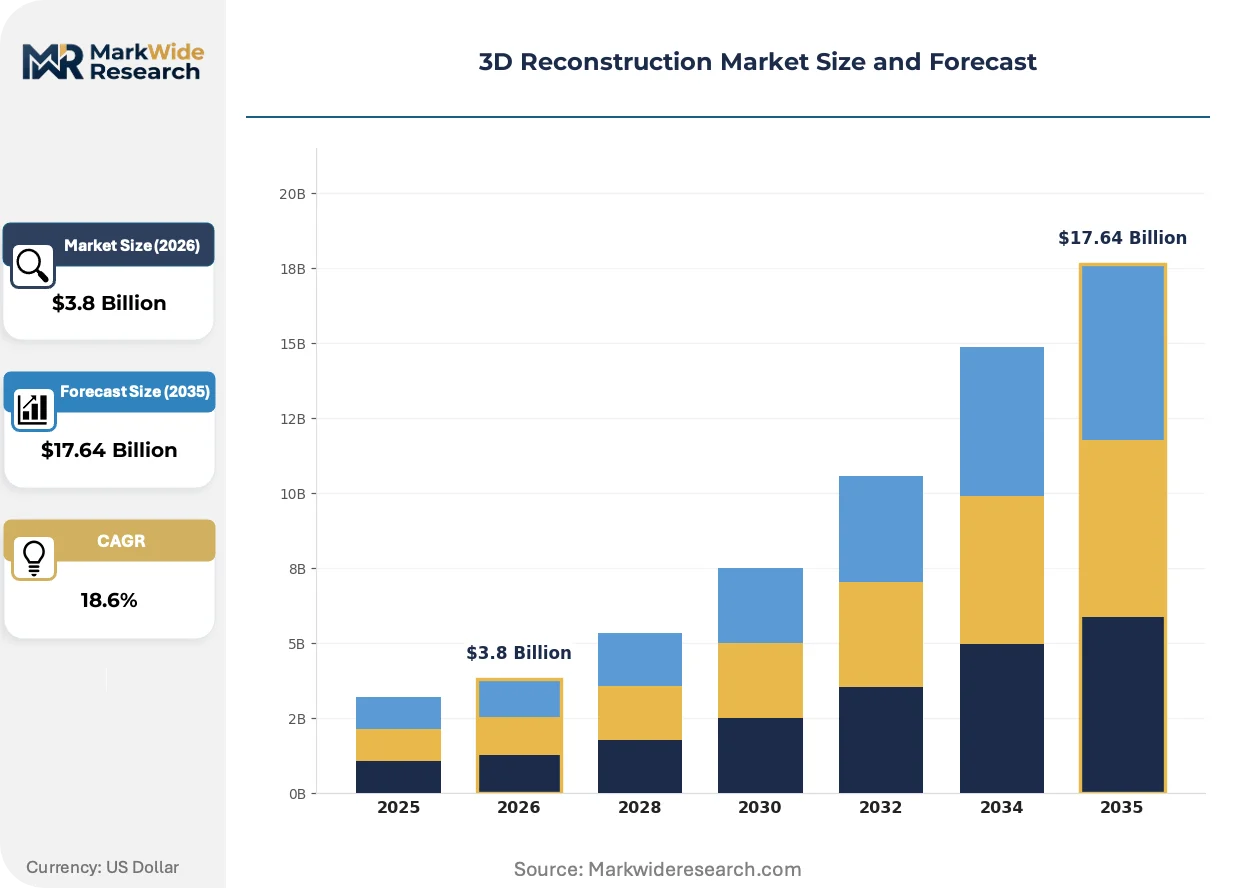
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Tools, Hardware Devices, Services, Platforms Technology: LIDAR, Photogrammetry, Structured Light, Time-of-Flight Application: Healthcare Imaging, Industrial Design, Virtual Reality, Cultural Heritage End User: Architects, Engineers, Game Developers, Educators |
| Companies Covered | Autodesk Inc., Bentley Systems Incorporated, Pix4D SA, Matterport Inc., Trimble, Hexagon AB, Agisoft LLC, NavVis, FARO Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Reconstruction Market Emerging Trajectories
Algorithmic advances in neural rendering and regulatory pressure on infrastructure documentation are restructuring how reconstruction value is captured across hardware, software, and services layers.
Neural radiance fields (NeRF) and Gaussian splatting techniques are decomposing the traditional photogrammetry pipeline by replacing dense matching and meshing with differentiable rendering from unstructured photo collections. Media production studios and real estate marketers in South Korea and Japan have accelerated adoption, compressing project timelines from weeks to hours. The structural consequence is a bifurcation between premium LIDAR applications demanding metrological traceability and volume use cases where neural methods suffice.
Europe's CSRD and the EU Green Deal taxonomy now mandate granular asset-level documentation for carbon accounting and circular economy compliance. Industrial facility operators must maintain accurate 3D as-builts to verify retrofit scope and material inventories. German chemical conglomerates and French utility operators have initiated multi-year digitization programs, pulling reconstruction services into sustained operational budgets rather than episodic capital projects.
Buyers in the AEC sector are unbundling hardware procurement from software licensing and operator training, treating reconstruction as a metered cloud service rather than capital equipment. General contractors in the United Arab Emirates and Saudi Arabia now specify deliverables—LOD 300 BIM models, orthomosaic accuracy thresholds—without mandating specific capture technologies. This specification shift compresses vendor margins while expanding addressable volume among mid-tier construction firms lacking in-house survey capabilities.
3D Reconstruction Market Segmentation
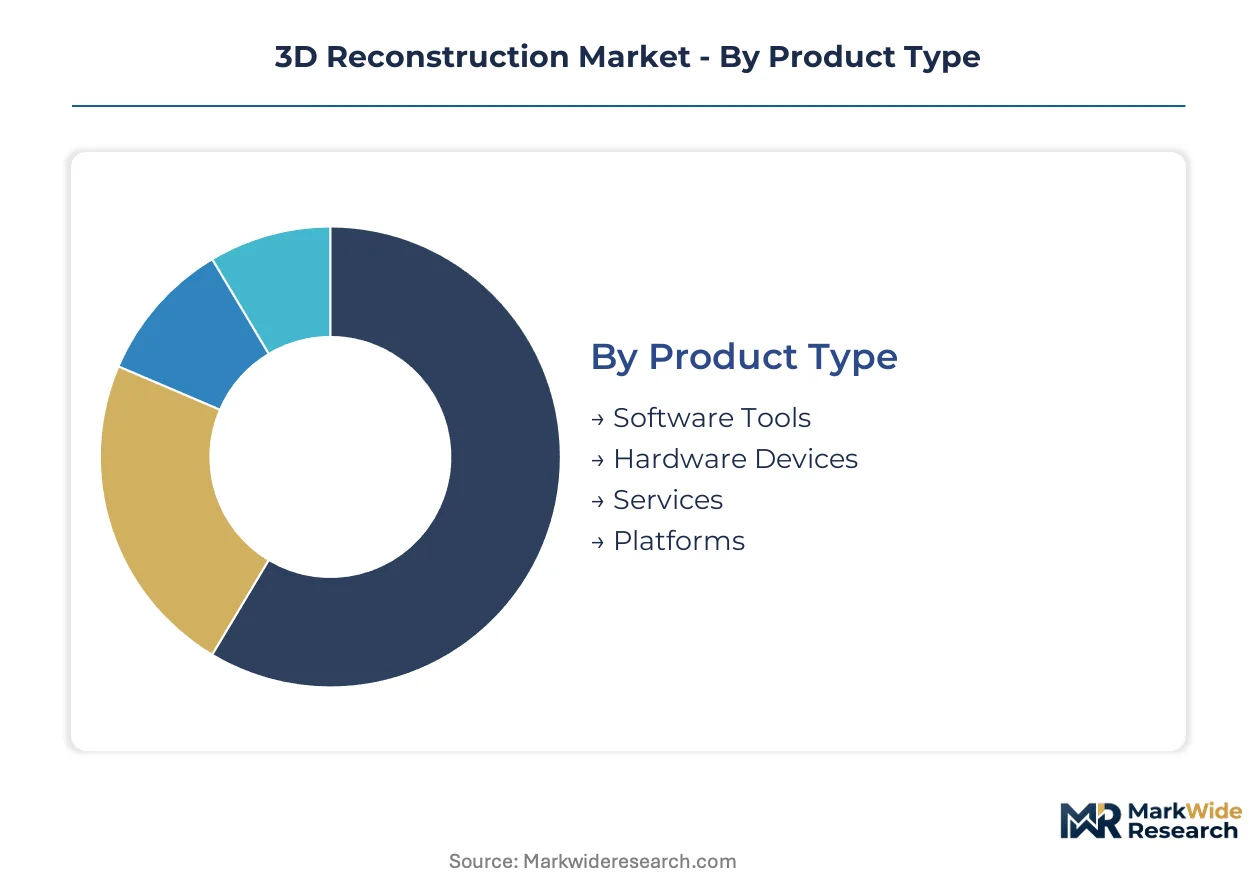
Segmentation in 3D reconstruction reveals how value migrates between software licensing, hardware procurement, and specialized services. Technology choice determines precision thresholds and capital requirements, while end-user specialization shapes workflow integration priorities.
Product Type:
Software Tools face the most acute substitution pressure from open-source photogrammetry pipelines, while Hardware Devices maintain defensive moats through sensor calibration IP and manufacturing scale.
- Software Tools:Photogrammetry suites and point cloud processing applications deploy on cloud-native architectures with GPU acceleration. Demand concentrates among mid-tier AEC firms in the United States seeking to avoid capital-intensive scanner purchases while maintaining LOD 300 BIM deliverables.
- Hardware Devices:Laser scanners, structured light systems, and time-of-flight sensors incorporate proprietary optics and factory calibration protocols. Industrial metrology departments in German automotive manufacturing anchor demand for millimeter-grade precision in adverse factory floor conditions.
- Services:Operator-led capture and processing engagements span cultural heritage digitization and industrial asset inspection.
- Platforms:Integrated sensor-to-software stacks bundle hardware leasing with cloud processing subscriptions.
Software Tools anchors the volume base while Services gains share at the steepest rate as buyers prefer operational expenditure models.
Technology:
Cost tier stratification separates premium precision applications from volume deployment, with capital intensity dropping tenfold between LIDAR and photogrammetry entry points.
- LIDAR:Pulsed laser ranging achieves sub-millimeter accuracy independent of ambient lighting. Defense terrain mapping contracts through the US Army Corps of Engineers sustain premium pricing for long-range terrestrial and aerial systems.
- Photogrammetry:Multi-view stereo reconstruction from standard camera arrays minimizes hardware barriers. Agricultural drone operators in Brazil and Australia drive volume adoption for field surveying and crop monitoring applications.
- Structured Light:Projected pattern triangulation delivers precision for close-range industrial inspection.
- Time-of-Flight:Direct depth sensing enables real-time capture for consumer and prosumer VR applications.
Photogrammetry commands the widest deployment base while Neural Radiance Field convergence accelerates Time-of-Flight expansion in media production.
Application:
Regulatory compliance intensity varies sharply across verticals, with FDA oversight in healthcare imposing validation burdens absent from entertainment use cases.
- Healthcare Imaging:Patient-specific anatomical model reconstruction requires FDA 510(k) clearance for surgical planning deployment. US hospital systems integrate these workflows into pre-operative visualization protocols, creating recurring software procurement cycles.
- Industrial Design:Reverse engineering and quality validation applications demand ISO-certified dimensional tolerancing. German and Japanese manufacturing conglomerates anchor demand through supplier quality mandates.
- Virtual Reality:Real-time environment scanning supports immersive content creation and spatial computing.
- Cultural Heritage:Monument and artifact digitization relies on specialized operator expertise for non-contact documentation.
Healthcare Imaging carries the highest compliance burden while Virtual Reality climbs fastest on gaming and metaverse investment cycles.
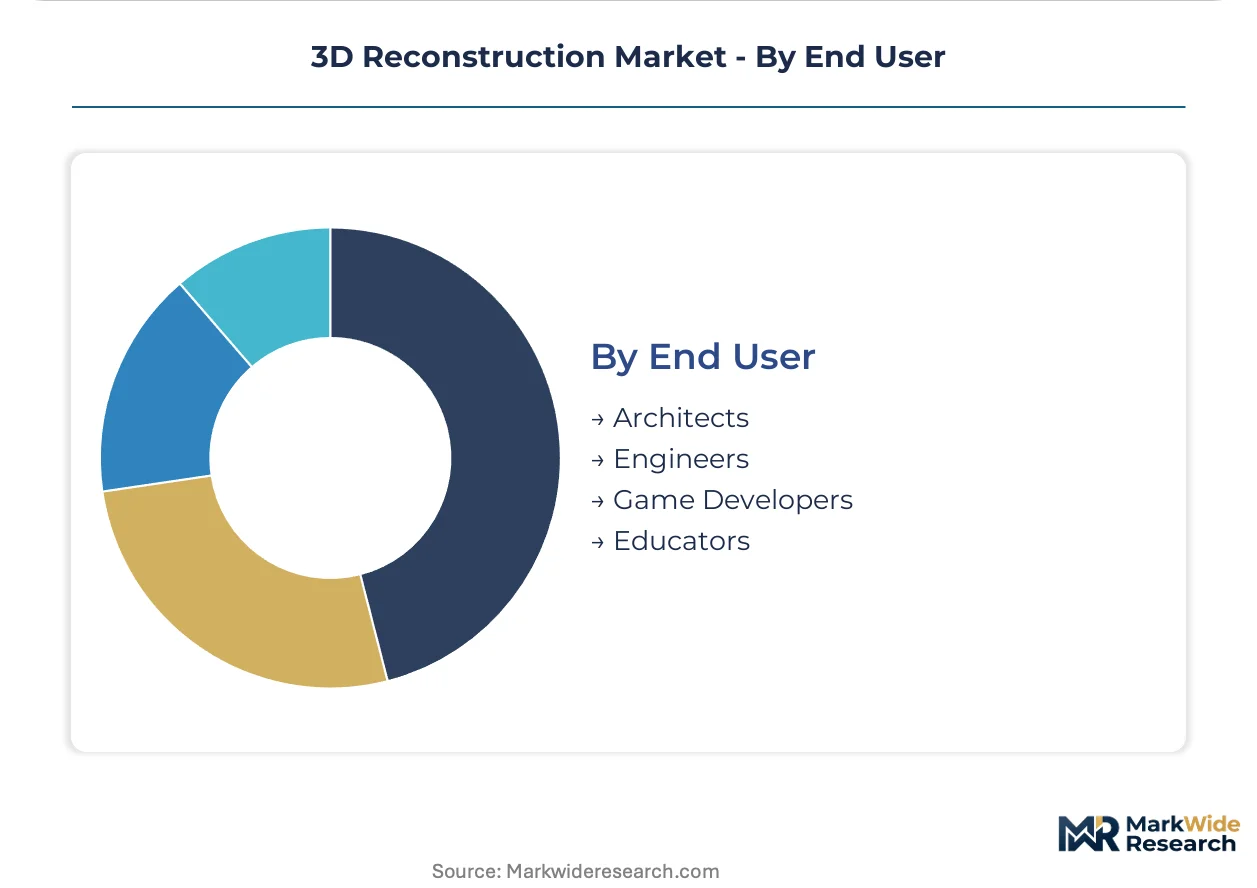
End User:
Customer type determines procurement authority and budget source, with enterprise engineering departments outspending individual creators by orders of magnitude.
- Architects:Design firms specify point cloud-to-BIM workflows for as-built documentation and renovation planning. Large practices in the United Arab Emirates and Saudi Arabia now mandate LOD 300 deliverables without prescribing capture technology.
- Engineers:Civil and structural engineering departments deploy reconstruction for infrastructure condition assessment and deformation monitoring.
- Game Developers:Studios leverage photogrammetry for photorealistic asset creation and environment scanning.
- Educators:University research programs and vocational training centers adopt reconstruction for pedagogy and field methodology instruction.
Engineers represent the largest contract value per engagement while Game Developers expand most quickly on neural rendering adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement in the United States absorbs premium LIDAR pricing without elasticity, while agricultural drone operators in Brazil and Australia drive photogrammetry volume through extreme cost sensitivity. Indian smart city mandates sit between these poles, trading precision for coverage scale.
United States
FDA 510(k) clearance pathways for patient-specific anatomical models sustain premium software licensing in hospital surgical planning departments. FCC spectrum allocations govern LIDAR and time-of-flight sensor deployments in unmanned aerial systems for defense terrain mapping. The US Army Corps of Engineers anchors demand in the Washington DC corridor and California defense clusters.
Germany
EU CSRD-driven asset digitization mandates pull industrial reconstruction services into compliance budgets for chemical conglomerates and utility operators. REACH and RoHS frameworks constrain sensor material specifications and data handling protocols. Bavarian automotive manufacturing clusters anchor demand for millimeter-grade metrology in supplier quality validation workflows.
China
Dual carbon goals and smart city infrastructure mandates accelerate aerial survey procurement across Yangtze River Delta urban agglomerations. MIIT standards and GB certification requirements govern sensor interoperability and data sovereignty for cross-border point cloud transmission. Shanghai and Shenzhen manufacturing bases concentrate structured light system production for industrial inspection applications.
India
Smart city mandates under the Ministry of Housing and Urban Affairs create procurement windows for aerial survey reconstruction services across 100 designated urban agglomerations. BIS certification timelines and DGFT import regulations shape hardware availability for mid-tier surveying firms. Mumbai and Delhi-NCR clusters concentrate service provider capacity for infrastructure digitization programs.
United Arab Emirates
General contractors now specify LOD 300 BIM deliverables without mandating specific capture technologies, compressing vendor margins while expanding addressable volume. MOHAP facility documentation requirements and Dubai Building Code amendments drive as-built digitization for retrofit compliance. Dubai and Abu Dhabi construction markets lead specification shifts toward metered cloud service models.
3D Reconstruction Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with hardware-software bundling creating defensive moats against pure-play software vendors. Autodesk Inc., Hexagon AB, and FARO Technologies Inc. anchor the integrated tier through captive manufacturing or cloud-native platform control. Specialist vendors concentrate on algorithmic differentiation in photogrammetry or neural rendering pipelines. Competitive moves center on M&A for sensor calibration IP and strategic partnerships to embed reconstruction tools within existing AEC workflows.
Within the integrated tier, Autodesk Inc. exemplifies cloud-native platform strategy, Hexagon AB represents sensor-to-software vertical integration, and FARO Technologies Inc. anchors premium hardware positioning through manufacturing control. Among specialized software vendors, Pix4D SA and Agisoft LLC occupy positions in photogrammetry algorithm development, while Matterport Inc. sits within the volume real estate digitization segment. These five entities collectively illustrate the market's structural bifurcation between premium precision applications and cost-optimized volume deployment.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Bentley Systems Incorporated |
| Pix4D SA |
| Matterport Inc. |
| Trimble |
| Hexagon AB |
| Agisoft LLC |
| NavVis |
| FARO Technologies Inc. |
| Others |
Supply Flow & Price Mechanics
Sixteen-week lead times for industrial-grade LIDAR sensor arrays concentrate pricing power with German and Japanese optics manufacturers while compressing margins for downstream systems integrators lacking captive calibration facilities. Inventory buffers for precision laser diodes and MEMS mirror assemblies sit at 45-60 days across Tier 1 distributors, tethering reconstruction hardware pricing to semiconductor foundry capacity allocation decisions.
Pricing Analysis
Extended service contracts and recalibration subscriptions drive lifetime value capture for hardware vendors, with three-tier pricing structure across premium, standard, and economy levels separating FDA-cleared medical systems from uncertified survey tools. Price differentiation rests on ISO 17025 metrology certification and software lock-in depth, with cost compression in photogrammetry software intensifying because open-source pipelines displace licensed seats. Hospital surgical planning departments show lowest price sensitivity; mid-tier AEC firms in emerging markets exhibit highest.
Supply Chain Analysis
Inventory buffers for precision optics and laser ranging modules concentrate supply concentration in Germany, Japan, and China, with Bavarian and Tokyo manufacturing clusters anchoring high-end sensor production. Raw material dependencies draw from rare-earth magnet supplies for scanning actuators, silicon photonics substrates, and specialized optical glass feeds. Single-source vulnerability runs through MEMS foundry capacity for compact LIDAR units. Distribution runs through authorized metrology distributors and direct OEM contracts for defense and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits across the AEC sector as buyers unbundle hardware from software procurement, creating specialist niches for neural rendering pure-plays and metered cloud service operators.
For Market Incumbents: Shield installed base through captive sensor calibration networks and FDA 510(k) clearance moats against neural rendering substitutes. Deepen backward integration into laser diode manufacturing to offset foundry allocation risk. Prioritize cloud-native platform stickiness over perpetual license models. For New Entrants and Emerging Players: Lead with NeRF-based rapid visualization for real estate marketing and forensic reconstruction, where incumbent LIDAR workflows carry 10x cost disadvantage. Target Indian smart city digitization procurement, where specification shifts favor deliverable-based contracts over technology mandates. Anchor go-to-market through UAV operator partnerships rather than direct enterprise sales. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-driven infrastructure play because EU CSRD and FDA surgical planning mandates embed reconstruction into recurring operational budgets rather than discretionary capital cycles. Acquisition targets cluster around photogrammetry algorithm shops with defense clearance pathways and cultural heritage digitization studios with established operator training pipelines. Watch for inflection when neural rendering achieves metrological traceability certification in German automotive supplier audits.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Autodesk's cloud-native embedding captures AEC workflow lock-in against standalone vendors. |
| Acquisition of Specialist Firm | Sensor calibration IP purchases defend premium positioning against commoditized photogrammetry. |
| Strategic Partnership | UAV operator alliances accelerate Indian smart city penetration without direct sales infrastructure. |
| Product Launch | NeRF-based rapid visualization tools compress real estate marketing project timelines from weeks to hours. |
| Geographic Expansion | UAE and Saudi specification shifts toward metered cloud services expand addressable volume among mid-tier contractors. |
Methodological Framework
Initial hypotheses were tested against primary input from photogrammetry operators, hospital biomedical engineers, defense procurement officers, and AEC project managers and refined through secondary validation against FDA 510(k) filings, EU CSRD implementation guidance, customs records for LIDAR and structured light system trade flows, and SEC disclosures from publicly traded vendors. Bottom-up segment sizing triangulated with top-down macroeconomic elasticity checks across the analysis window.
Variance decomposition across technology, application, and end-user dimensions shaped the analytical framework, with deployment model and regional adoption pattern added as cross-cutting variables. CAGRs derived from logistic diffusion curves for neural rendering adoption and infrastructure investment elasticity for compliance-driven digitization. Industry-specific inputs included defense procurement pipeline visibility and smart city tender award timelines.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of medical device classification or abrupt geospatial data sovereignty restrictions would require recalibration. Forecasts reflect documented assumptions around photogrammetry algorithm efficiency trajectories and cloud infrastructure cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Europe 3D Telepresence Market
3D Technology
UK 3D Rendering Services Market
3D Technology
Mobile 3D Market
3D Technology
Generative Design Market
3D Technology
LAMEA Smartphone 3D Camera Market
3D Technology
3D Reconstruction Technology Market
3D Technology
3D Photogrammetry Software Market
3D Technology
3D Rendering Market
3D Technology
3D Rendering Software Market
3D Technology
Global 3D Architecture Software Market
3D Technology
Middle East and Africa 3D 4D Technology Market
3D Technology
Glasses Free 3D Tvs Market
3D Technology
3D Simulation Software Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
3D Technology Market
3D Technology
3D Geospatial Technologies Market