
 LAMEA Hair Removal Wax Market | 2026-2036
LAMEA Hair Removal Wax Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Hair Removal Wax Market Analytics
The LAMEA hair removal wax category is rebalancing between premium salon-grade formulations and mass-market retail strips. Church & Dwight Co., Inc. leverages its distribution infrastructure to anchor shelf presence across Latin American retail channels. Reckitt Benckiser Group PLC competes through brand recognition in home-use depilatory segments. Rica Group specializes in professional-grade hard wax systems that dominate Brazilian and Argentine salon supply chains.
Hair removal wax comprises thermoplastic resin or sugar-based formulations applied to skin, adhered to hair, and removed mechanically to extract hair from the root; melting points typically range from 40°C to 65°C depending on polymer composition, with strip wax requiring cloth or paper substrates while hard wax sets independently for direct removal. Strip wax occupies the highest volume tier across LAMEA retail channels due to low unit cost and consumer familiarity, yet hard wax captures disproportionate margin pools in professional salon and spa end user segments where service pricing supports premium material costs. Sugar wax, positioned within natural formulation variants, is gaining traction among at-home users seeking water-soluble, low-temperature alternatives.
ANVISA in Brazil and SAHPRA in South Africa govern cosmetic safety and ingredient disclosure requirements for depilatory products, while each country's national standards body enforces labeling rules that influence import compliance costs for foreign suppliers. These frameworks elevate barriers for unformulated bulk imports while creating preference for locally compliant packaging and Portuguese-language instructions in Brazil. Stakeholders must monitor evolving mercosur harmonization talks and shifting salon licensing requirements that could reshape professional channel access across the region.
Market Dynamics
Professional salon chains across Brazil and South Africa are driving demand bifurcation between premium hard wax systems and mass-market retail strips, while ANVISA cosmetic safety standards reshape formulation priorities toward organic variants.
Growth Catalysts
- ANVISA cosmetic safety standards:Brazil's pharmaceutical regulator mandates ingredient disclosure and safety testing for depilatory products, elevating compliant local manufacturers above unformulated bulk imports.
- Professional salon expansion:Brazilian and South African salon chains are broadening service menus to include premium waxing treatments, pulling hard wax demand upward.
- Metropolitan corridor concentration:São Paulo and Rio de Janeiro anchor consumption density, creating economies of scale for distribution infrastructure investment.
Market Restraints
- Input cost volatility:Thermoplastic resin prices fluctuate with petrochemical feedstock markets, compressing margin stability for polymer-based wax formulations.
- Regulatory friction:MERCOSUR harmonization talks remain unresolved, forcing suppliers to maintain separate compliance documentation for Brazilian and Argentine markets.
- Substitution threat:Laser hair removal devices capture permanent hair reduction demand among middle-income consumers in major Brazilian cities.
Strategic Opportunities
- Underpenetrated secondary cities:Brazilian interior states beyond the southeastern corridor show sparse professional waxing service coverage relative to per-capita income growth.
- Water-soluble sugar wax:Low-temperature natural formulations attract at-home users seeking simplified cleanup and reduced skin irritation risk.
- Portuguese-language packaging mandate:ANVISA labeling requirements create competitive moats for suppliers with localized packaging capabilities against English-dominant imports.
Industry Challenges
- Licensed esthetician scarcity:Brazilian salon licensing requirements vary by municipality, complicating workforce scaling for expanding chains.
- Supply chain reconfiguration friction:Import compliance costs for foreign suppliers favor local formulation and packaging investments, requiring capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Hair Removal Wax Market |
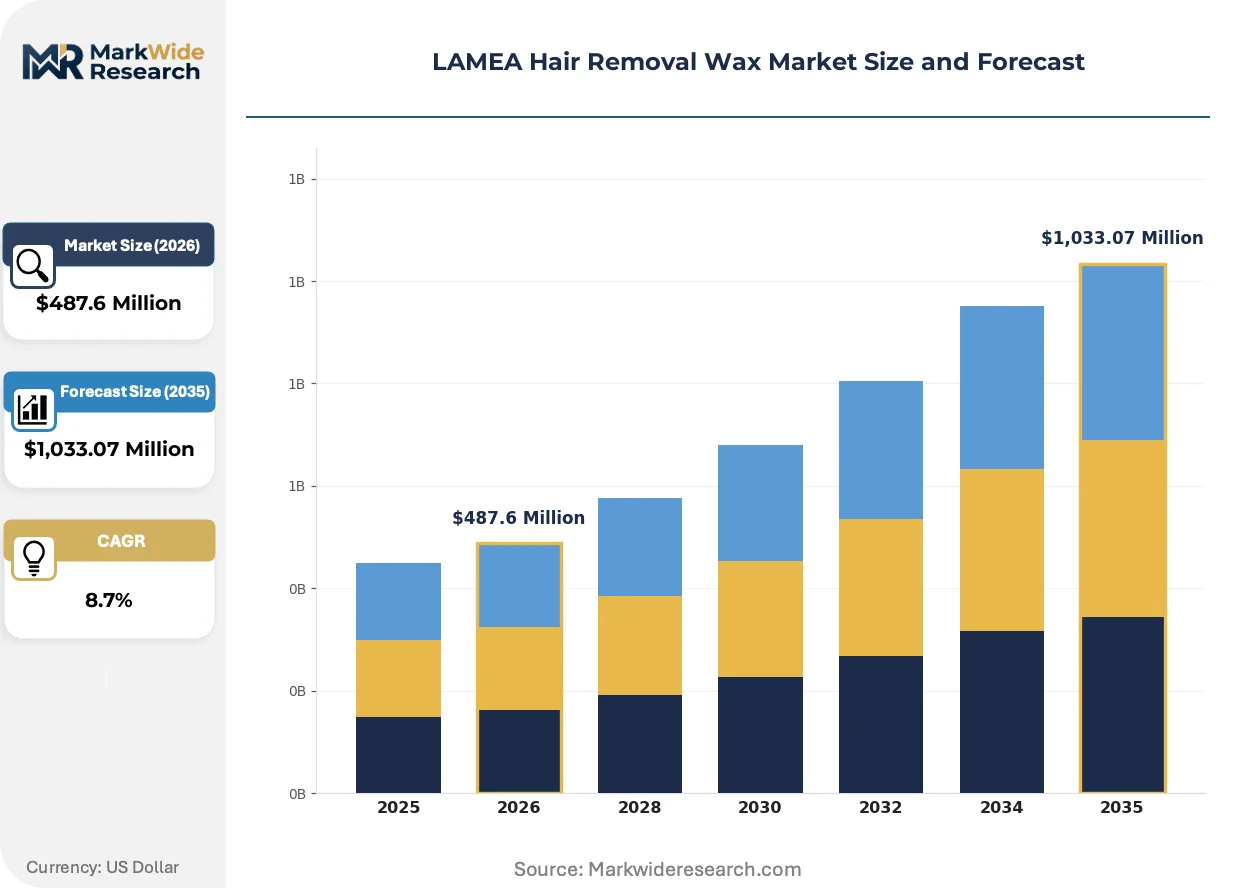
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strip Wax, Hard Wax, Gel Wax, Sugar Wax Application: Face, Body, Bikini, Legs Formulation: Natural, Synthetic, Hypoallergenic, Organic End User: Salons, Spas, At-home Users, Clinics |
| Companies Covered | Church & Dwight Co., Inc., Reckitt Benckiser Group PLC, American International Industries, Rica Group, The Darent Wax Company Ltd., Starpil Wax Co., FILO BIANCO S.r.l., SI&D (Aust) Pty Ltd, Coty, Inc., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Hair Removal Wax Market Evolving Landscape
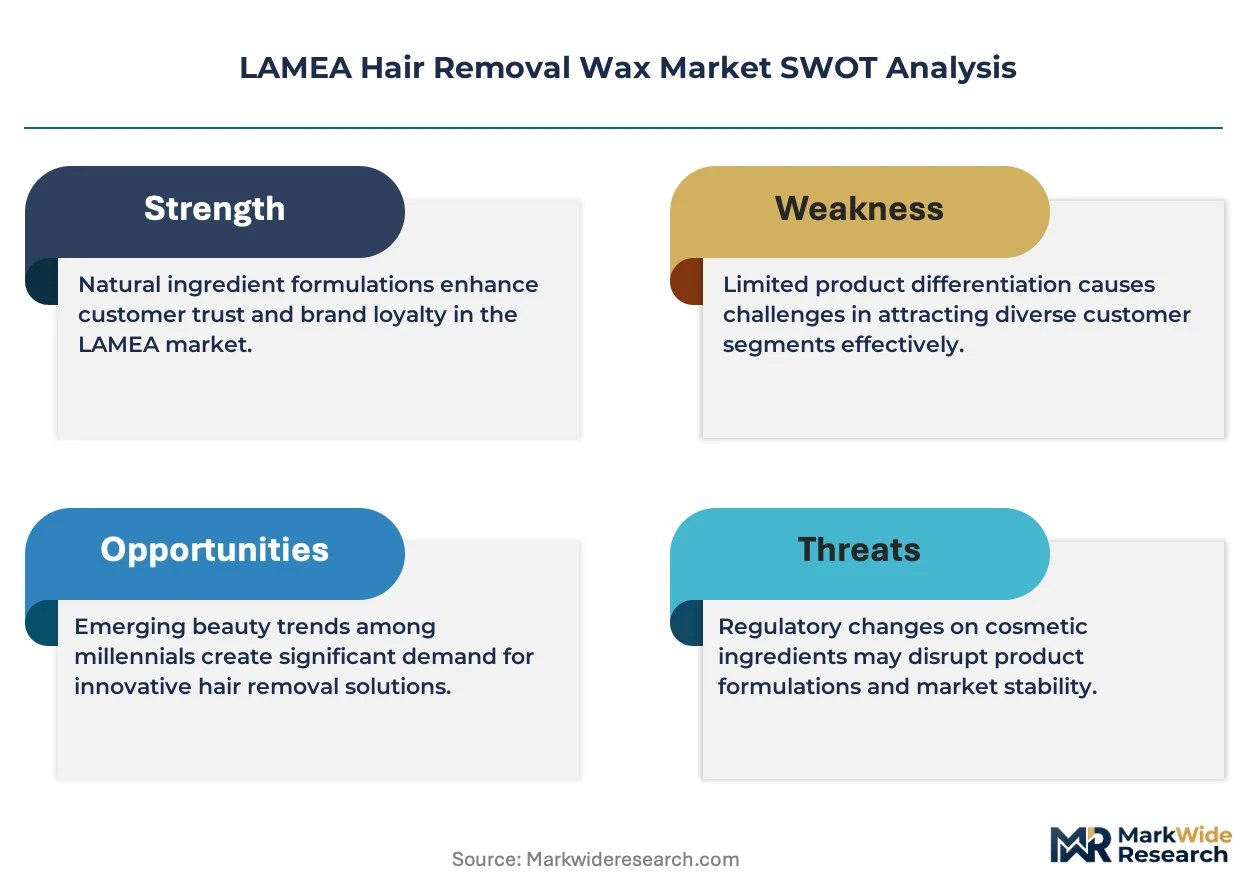
Formulation chemistry and service delivery models are converging around temperature control, natural ingredients, and channel-specific product positioning across the LAMEA region.
Low-temperature polymer blends are absorbing market share from conventional high-melt formulations by reducing burn risk and enabling self-application. At-home users in Brazil and South Africa are adopting these variants fastest, compressing the performance gap between professional and retail-grade products while forcing suppliers to differentiate through additive portfolios rather than base chemistry.
ANVISA's evolving cosmetic safety framework is tightening ingredient disclosure requirements for depilatory products. The regulation forces reformulation cycles for multinational suppliers while creating preference windows for local manufacturers with established Portuguese-language documentation and testing relationships.
Channel disintermediation is reshaping procurement patterns as Brazilian salon chains consolidate supplier relationships through direct sourcing agreements. Professional-grade hard wax procurement is bypassing traditional distribution intermediaries most visibly in São Paulo's dense salon cluster, compressing distributor margins while rewarding manufacturers with captive logistics capabilities.
LAMEA Hair Removal Wax Market Segmentation
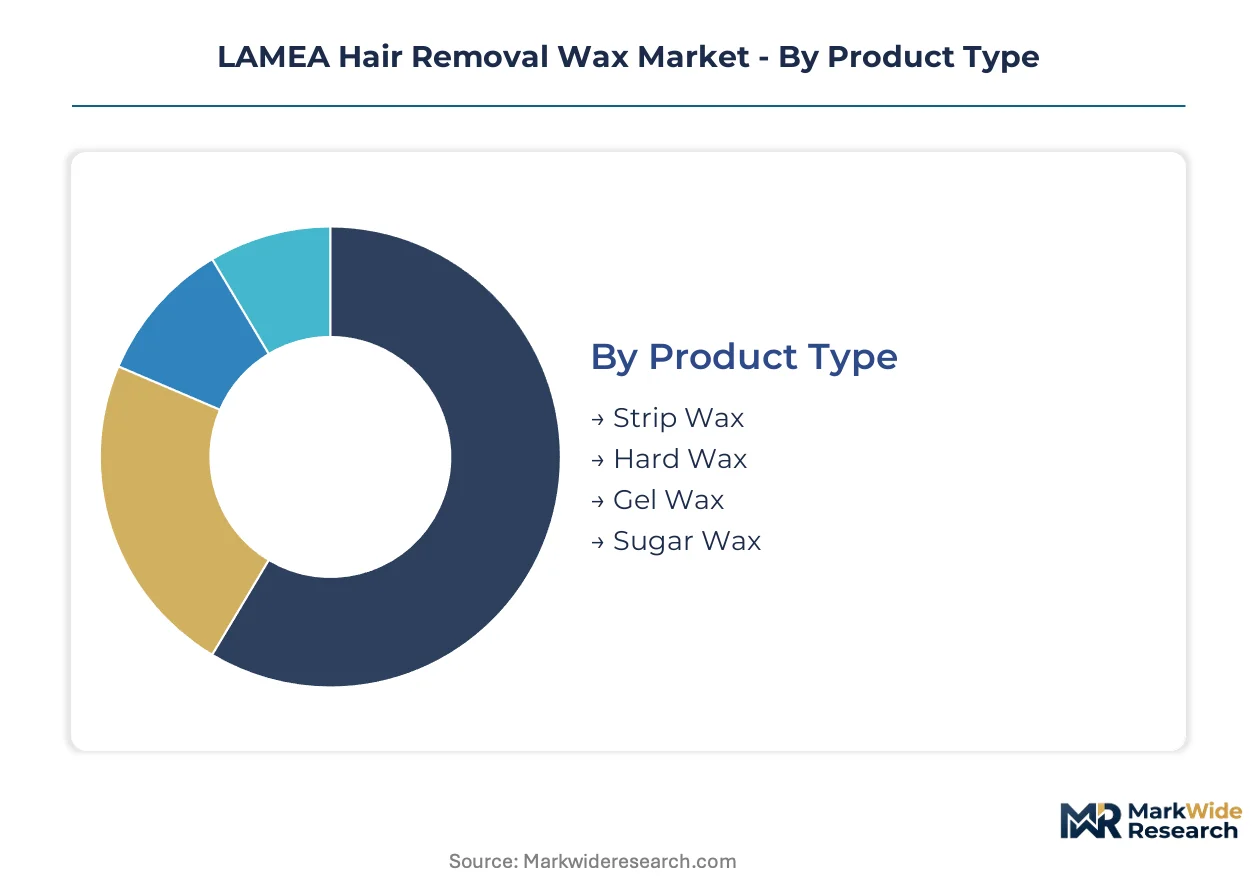
Segmentation in the LAMEA hair removal wax market reveals how formulation chemistry, application site, and service setting create distinct margin pools. Suppliers must calibrate product architecture across these dimensions to capture value in Brazilian metropolitan corridors and South African urban centers.
Product Type:
Strip wax dominates unit volumes through retail accessibility, while hard wax commands premium pricing in professional channels across São Paulo and Rio de Janeiro.
- Strip Wax:Thermoplastic resin formulations applied with cloth or paper substrates enable low-temperature application. Brazilian retail chains in the southeastern corridor stock these variants most densely, driven by at-home user familiarity and price accessibility.
- Hard Wax:Polymer-based systems set independently without strips, permitting direct removal. Argentine and Brazilian salon supply chains favor these formulations where service pricing supports material cost premiums and esthetician labor specialization.
- Gel Wax:Low-viscosity synthetic formulations suit precision facial applications. South African spa channels show rising procurement of these variants for brow and lip services.
- Sugar Wax:Water-soluble natural formulations use sucrose-based chemistry for simplified cleanup. Brazilian at-home users in coastal metropolitan zones adopt these fastest amid ANVISA-influenced preference for ingredient transparency.
Today's leader: Strip Wax. Tomorrow's challenger: Hard Wax.
Application:
Body waxing generates the broadest revenue base, yet bikini services concentrate margin extraction in premium Brazilian salon chains.
- Face:Precision formulations with lower melting points reduce irritation risk for sensitive skin. Brazilian salon licensing requirements for facial services vary by municipality, fragmenting demand concentration.
- Body:Large-surface applications favor economical strip wax deployment. South African spa chains standardize these services across treatment menu tiers.
- Bikini:Specialized hard wax systems dominate professional Brazilian channels where service premiums justify material costs. ANVISA cosmetic safety standards elevate formulation compliance burdens for intimate-area products.
- Legs:High-volume depilation supports retail strip wax consumption. Argentine consumers show strongest at-home leg waxing adoption relative to other applications.
Body waxing anchors current revenue. Bikini services show the steepest expansion trajectory in professional channels.
Formulation:
Natural and organic variants are gaining share fastest as ANVISA disclosure requirements reshape consumer preference in Brazil.
- Natural:Plant-derived base materials exclude synthetic polymers. Brazilian manufacturers with established Portuguese-language documentation capture preference windows from reformulating multinationals.
- Synthetic:Petrochemical-derived resins offer consistent melting behavior and shelf stability. Input cost volatility from thermoplastic feedstock markets compresses margin predictability for these formulations.
- Hypoallergenic:Reduced-irritant additive portfolios target sensitive-skin users. South African clinic channels specify these variants for post-treatment care protocols.
- Organic:Certified ingredient sourcing meets emerging premium positioning. São Paulo salon chains increasingly menu these as upgrade options.
Synthetic formulations retain volume leadership. Organic variants are climbing the fastest amid regulatory tailwinds.
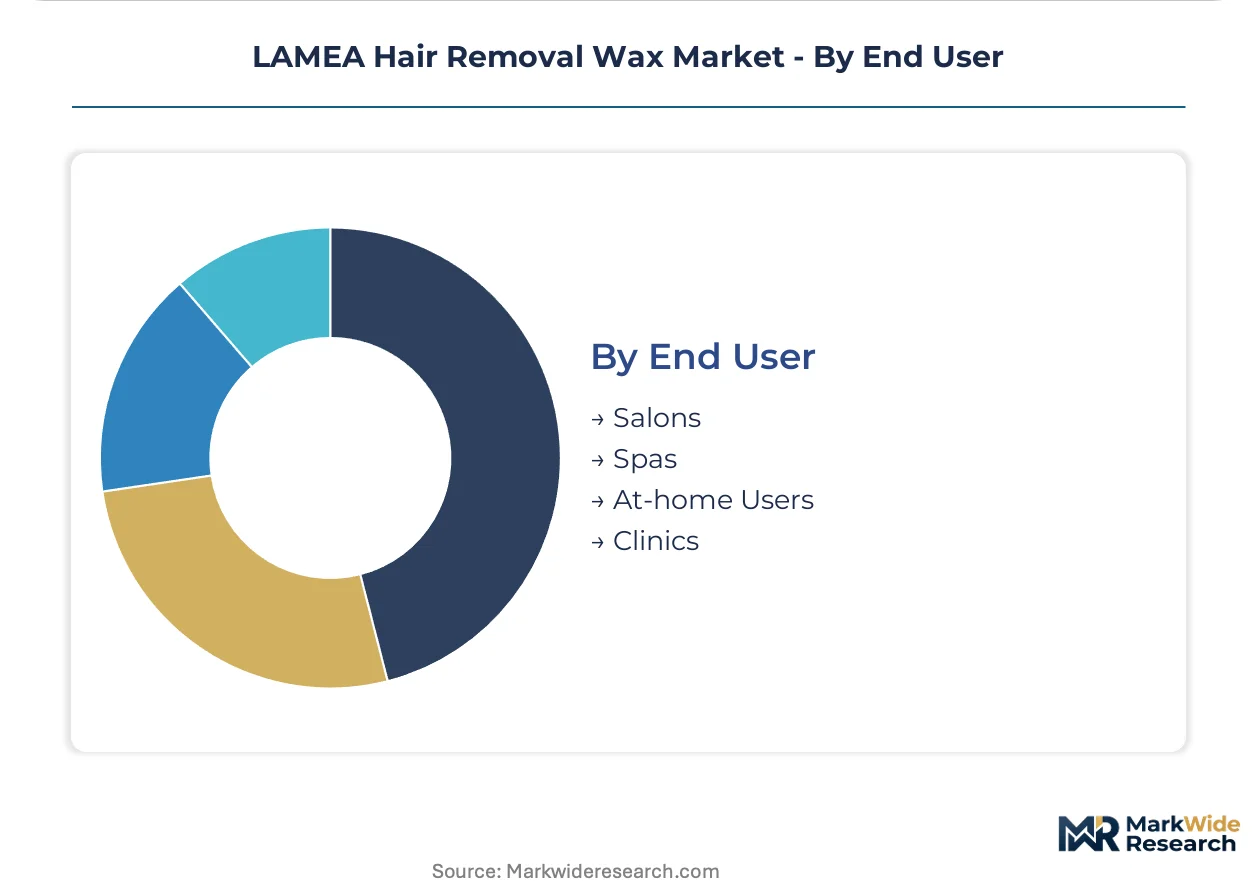
End User:
Salon procurement concentrates demand for professional-grade hard wax systems, while at-home users fragment purchasing across retail strip and sugar variants.
- Salons:Brazilian chains in the southeastern metropolitan corridor consolidate supplier relationships through direct sourcing agreements, bypassing traditional distribution intermediaries.
- Spas:Premium service positioning supports gel wax and organic formulation procurement. South African urban spa clusters drive regional demand concentration.
- At-home Users:Retail channel dependence shapes price sensitivity and brand familiarity requirements. Brazilian consumers show strongest sugar wax adoption for self-application.
- Clinics:Medical-aesthetic settings specify hypoallergenic and low-temperature formulations. Licensed esthetician scarcity in Brazilian municipalities constrains service scaling.
Salons dominate professional-grade procurement. At-home users represent the fastest-growing volume pool as retail formulation quality improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands professional waxing service density unmatched elsewhere in LAMEA, while South Africa's salon chains consolidate procurement faster than Argentine retail channels expand.
Brazil
ANVISA cosmetic safety standards mandate Portuguese-language labeling and ingredient disclosure, elevating compliant domestic manufacturers above unformulated imports. São Paulo and Rio de Janeiro anchor consumption density, with professional salon chains in the southeastern metropolitan corridor consolidating supplier relationships through direct sourcing agreements that bypass traditional distributors.
South Africa
Urban spa clusters in Johannesburg and Cape Town drive premium formulation procurement, while licensed esthetician scarcity constrains service scaling in secondary municipalities. SAHPRA governs cosmetic safety requirements, creating compliance moats for suppliers with established local testing relationships. Salon licensing fragmentation across provinces complicates workforce expansion for expanding chains.
Argentina
MERCOSUR harmonization talks remain unresolved, forcing suppliers to maintain separate compliance documentation from Brazilian operations. Buenos Aires concentrates retail strip wax consumption among at-home users, while salon-grade hard wax procurement lags São Paulo's professional channel density. The country's national standards body enforces labeling rules that elevate import compliance costs.
Mexico
Mexico City Metro and Monterrey anchor demand concentration, with retail channels showing stronger sugar wax adoption than Brazilian interior states. The country's national health regulator oversees cosmetic safety frameworks, though enforcement density varies by region. Professional salon chains in Nuevo León are expanding service menus to include premium waxing treatments.
Chile
Santiago's spa channels specify hypoallergenic formulations for post-treatment care protocols, reflecting premium service positioning. The country's national pharmaceutical regulator maintains cosmetic safety standards that align with broader Latin American harmonization efforts. Metropolitan consumption concentration creates economies of scale for distribution infrastructure investment.
LAMEA Hair Removal Wax Market Competitive Landscape
Top-tier vendors anchor professional salon supply chains, while mass-market retail channels fragment across consumer-facing brands. The vendor base separates into three strategic archetypes: multinational consumer goods conglomerates with Latin American distribution infrastructure, regional specialists in professional-grade formulations, and natural-ingredient challengers exploiting ANVISA disclosure preferences. Dominant competitive moves include backward integration into captive resin supply and geographic expansion through direct salon chain partnerships.
Within the multinational tier, Church & Dwight Co., Inc. and Reckitt Benckiser Group PLC exemplify scale-driven positioning through established retail channel presence. Rica Group occupies a specialist position in professional-grade hard wax systems, representing the regional formulation archetype that dominates Brazilian and Argentine salon supply chains.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Reckitt Benckiser Group PLC |
| American International Industries |
| Rica Group |
| The Darent Wax Company Ltd. |
| Starpil Wax Co. |
| FILO BIANCO S.r.l. |
| SI&D (Aust) Pty Ltd |
| Coty, Inc. |
| Others |
Value Network & Pricing Analysis
Thermoplastic resin price indices cascade through LAMEA hair removal wax supply chains, compressing margin pools for polymer-dependent formulations while elevating sugar-based alternatives. Brazilian ANVISA compliance costs add fixed layers to landed costs, forcing suppliers to recalibrate pricing tiers around certification grade and local formulation capability.
Pricing Analysis
Capacity additions in Brazil's southeastern manufacturing corridor are reshaping price floors for professional-grade hard wax systems. Three-tier pricing structure across premium salon-grade, standard retail, and economy strip variants stratifies by ANVISA certification level and Portuguese-language packaging compliance. Pricing pressure stems from petrochemical feedstock volatility squeezing synthetic formulation margins. At-home users in Argentina and Mexico exhibit highest price sensitivity, while São Paulo salon chains prioritize service consistency over unit cost.
Supply Chain Analysis
Return flows of used wax warmers and packaging materials from Brazilian salon chains create reverse-logistics complexity for equipment suppliers. Manufacturing concentrates in Brazil, Argentina, and Mexico for regional compliance efficiency. Formulation chemistry draws from sucrose supply chains in Brazil's interior states and petrochemical feedstocks from Gulf Coast suppliers. Single-source vulnerability in thermoplastic resin imports elevates risk exposure. Distribution runs through consolidated direct-sourcing agreements between salon chains and manufacturers, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with ANVISA's evolving ingredient disclosure mandates creating recurring reformulation cycles that favor established local testing relationships.
For Market Incumbents: Extend backward integration into captive sucrose supply from Brazil's interior agricultural zones to offset petrochemical price volatility. Deepen channel control through exclusive direct-sourcing agreements with expanding salon chains in secondary municipalities. Laser hair removal device penetration in major Brazilian cities threatens permanent hair reduction demand; counter through low-temperature polymer innovation that narrows the professional-retail performance gap. For New Entrants and Emerging Players: E-commerce platforms serving at-home users in Brazilian interior states beyond the southeastern corridor offer the most penetrable entry vector. Target sugar wax formulations with simplified Portuguese-language compliance documentation to exploit ANVISA disclosure preference windows. Deploy subscription-based replenishment models for recurring strip wax consumption to build brand equity before professional channel expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where ANVISA compliance documentation and established testing relationships create acquisition premiums for local manufacturers over reformulating multinationals. Long-term viability favors vertically integrated specialists with captive formulation and packaging capabilities. Acquisition target archetype: mid-scale Brazilian manufacturers with existing Portuguese-language labeling infrastructure and salon chain relationships. Monitor MERCOSUR harmonization resolution as inflection signal for cross-border scaling economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sucrose Supply | Captive agricultural sourcing from Brazil's interior states insulates margin pools from petrochemical volatility. |
| Direct Salon Chain Partnerships | Bypassing distribution intermediaries in São Paulo's dense salon cluster captures margin compression from channel consolidation. |
| Portuguese-Language Compliance Investment | ANVISA labeling mandates create competitive moats against English-dominant imports in Brazilian retail channels. |
| Low-Temperature Polymer R&D | Reducing burn risk narrows the performance gap between professional and retail-grade formulations for at-home adoption. |
| Secondary City Distribution Expansion | Sparse professional waxing coverage in Brazilian interior states relative to income growth creates whitespace for premium service penetration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged salon chain procurement directors, ANVISA regulatory consultants, thermoplastic resin suppliers, and esthetician training program administrators across Brazil, South Africa, Argentina, and Mexico. Secondary validation drew from customs import records, ANVISA cosmetic registration databases, SEC filings of multinational consumer goods conglomerates, and regional trade association reports. Bottom-up salon census data and top-down retail channel estimates were triangulated to anchor volume assumptions.
Segment-weighting approaches calibrated product type, application site, formulation chemistry, and end-user channel contributions across the modeling period. Hard wax and strip wax volume splits were modeled against salon service pricing data and retail unit economics. CAGRs derived from trend extrapolation of metropolitan corridor consumption density and regulatory compliance cost trajectories. Forecast inputs incorporated ANVISA reformulation cycle frequency and laser hair removal device adoption curves in major Brazilian cities.
The model assumes a particular technology adoption path; alternative pathways for permanent hair reduction technologies would alter the outlook. Forecasts embed assumptions around MERCOSUR harmonization progress and petrochemical feedstock price stability that could shift materially. Practitioners should monitor ANVISA disclosure requirement expansion timelines and salon licensing standardization across Brazilian municipalities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
GCC Hair Styling Products Market
Beauty & Personal Care
France Sustainable Personal Care Market
Beauty & Personal Care
Liquid Soap Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
Facial Care Products Market
Beauty & Personal Care
Global Organic Personal Care and Cosmetic Products Market
Beauty & Personal Care
South America Bath and Shower Products Market
Beauty & Personal Care
Global Personal Care Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Bio-Based Cosmetics Market
Beauty & Personal Care
Skin Care Luxury Cosmetic Market
Beauty & Personal Care
Shaving and Hair Removal Products Market
Beauty & Personal Care
Hair Conditioner Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
Mens Intimate Care Products Market