
 Hair Conditioner Market | 2026-2036
Hair Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Conditioner Market Intelligence
Multi-source ingredient procurement is pivoting toward captive botanical supply chains as volatility in shea butter and argan oil spot markets intensifies. L'Oréal leverages integrated sourcing from Moroccan cooperatives to secure consistent raw material quality. Procter & Gamble sustains massive manufacturing scale across North American and Asian production networks. Unilever competes through formulation science investments targeting sulfate-free and silicone-alternative chemistries.
Hair conditioner is a cationic surfactant-based cosmetic preparation, typically containing fatty alcohols, silicones, and quaternary ammonium compounds at pH 3.5–5.5, designed to deposit conditioning agents onto the hair cuticle after cleansing. Its primary commercial purpose is to reduce friction, improve combability, and restore lipids stripped during shampooing. Rinse-out formulations occupy the largest revenue pool due to universal daily-use penetration, while leave-in conditioners represent the fastest-expanding segment as consumers adopt multi-step hair care routines. Treatment-grade deep conditioners concentrate margin pools in professional salon channels where service-based pricing supports premium positioning.
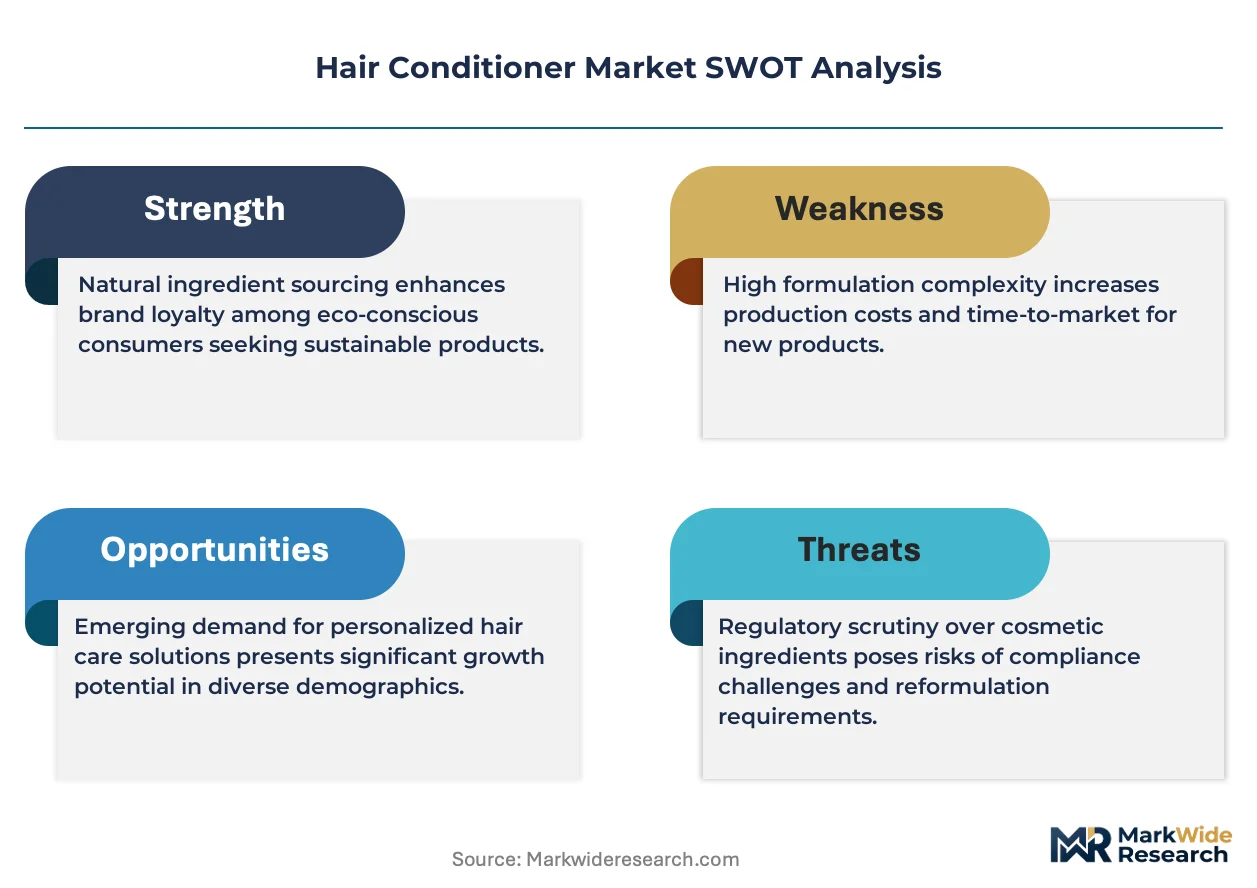
The FDA oversees cosmetic safety labeling under the Federal Food, Drug, and Cosmetic Act, while the EU REACH regulation restricts certain preservative and fragrance allergens in rinse-off products. India's BIS mandates heavy metal testing and ingredient disclosure for imported cosmetic formulations. Stakeholders must monitor evolving state-level chemical bans in California and New York that could cascade into national formulation standards.
Market Dynamics
Professional salon channels are consolidating demand for treatment-grade formulations as humidity-driven hair care routines in tropical urban centers reshape consumption frequency and product tier preferences.
Growth Catalysts
- EU REACH chemical framework:Stricter ingredient disclosure requirements are accelerating reformulation investments toward sulfate-free and silicone-alternative chemistries that command premium positioning.
- Southeast Asian urban humidity:Indonesia and Vietnam exhibit elevated daily conditioner use patterns driven by climate-specific hair management needs in dense metropolitan corridors.
- Captive botanical supply chains:Volatility in shea butter and argan oil spot markets is pulling procurement toward integrated sourcing from Moroccan cooperatives and controlled cultivation networks.
Market Restraints
- Raw material concentration:Moroccan argan oil production remains geographically concentrated, exposing formulation pipelines to harvest volatility and cooperative supply disruptions.
- India BIS import testing:Heavy metal testing mandates and ingredient disclosure requirements for imported cosmetic formulations extend certification timelines and compliance costs.
- Quaternary ammonium compound substitution:Behentrimonium chloride alternatives face performance gaps in cationic deposition efficiency, limiting rapid formulation pivots.
Strategic Opportunities
- Leave-in conditioner segment:Multi-step hair care routine adoption among younger demographics in Vietnam and Indonesia creates white space for lightweight, heat-protective formulations.
- California state-level chemical bans:Proposed restrictions on certain preservatives and fragrance allergens could cascade into national standards, rewarding early reformulation investments.
- Professional salon channel expansion:Service-based pricing models in urban India and Southeast Asia support margin-rich positioning for deep treatment conditioners.
Industry Challenges
- Formulation chemistry expertise:Silicone-alternative conditioning agent development requires specialized polymer science capabilities that remain scarce across mid-tier manufacturers.
- Legacy equipment retooling:pH-controlled cationic surfactant processing lines demand capital-intensive upgrades to accommodate novel fatty alcohol-quaternary compound combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Conditioner Market |
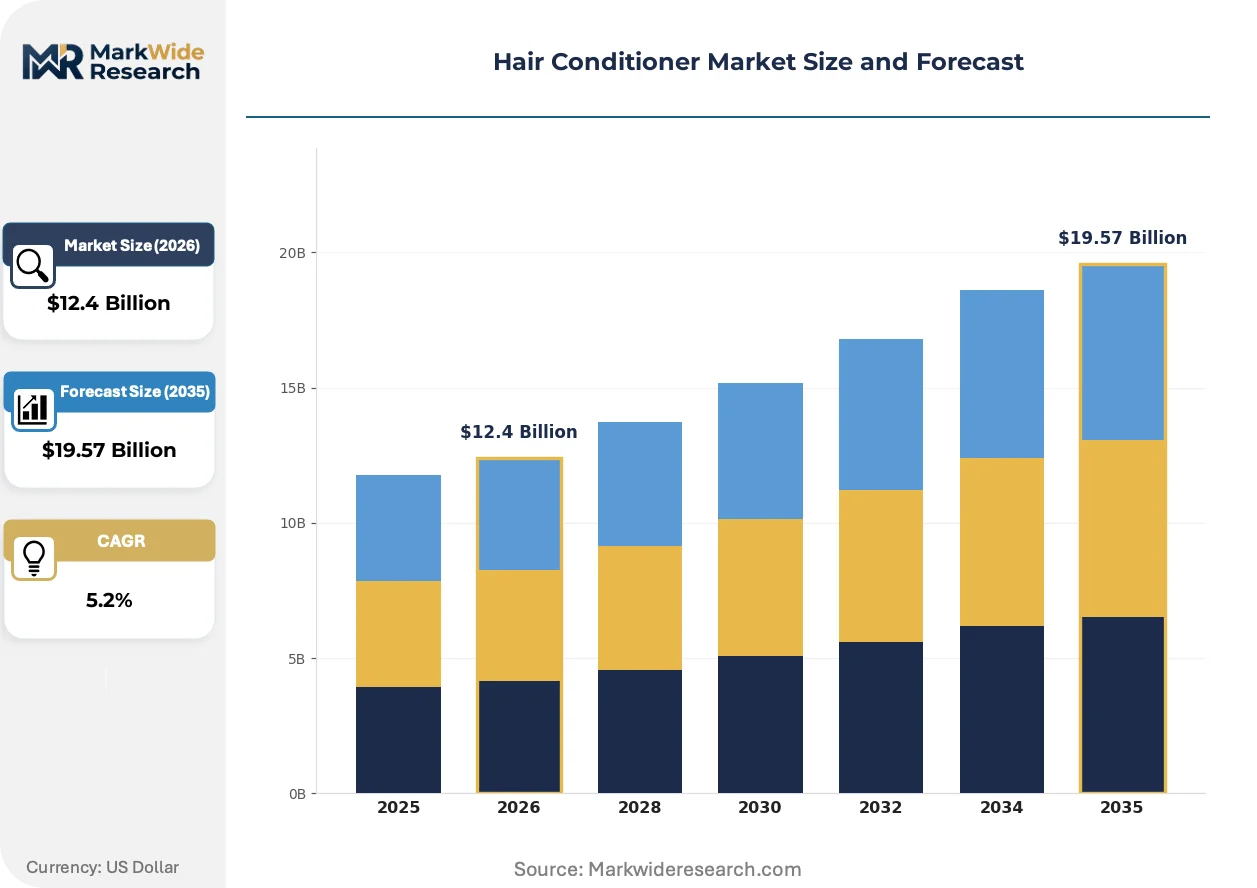
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $19.57 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leave-In, Rinse-Out, Deep Conditioner, Treatment Formulation: Cream, Lotion, Oil, Gel End User: Women, Men, Children, Professionals Distribution Channel: Online, Supermarkets, Drugstores, Salons |
| Companies Covered | L'Oréal, Procter & Gamble, Unilever, Henkel, The Estée Lauder Companies, Johnson & Johnson, Kao Corporation, Beiersdorf, Amway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Conditioner Market Strategic Shifts & Innovations
Biotechnology-derived conditioning agents and precision fermentation processes are rewriting raw material economics while regulatory disclosure mandates compress formulation development cycles.
Fermentation-produced squalane and ceramide analogs are rewriting lipid replacement strategies in rinse-out formulations. Professional salon brands in South Korea and Japan are adopting these inputs at accelerated procurement cycles. The technology is rewriting cost structures for mid-tier manufacturers previously dependent on plant-derived emollients.
India's BIS cosmetic safety standards now mandate expanded heavy metal testing and full ingredient disclosure for imported formulations. This regulatory friction is compressing product registration timelines and forcing reformulation investments before market entry. Professional channel importers targeting Indian metropolitan markets are responding by establishing local testing partnerships and pre-certification laboratories.
Direct-to-consumer subscription models are displacing traditional retail stocking patterns for treatment-grade conditioners. Southeast Asian urban consumers, particularly in Jakarta and Ho Chi Minh City, are shifting toward curated product bundles delivered on replenishment cycles. This channel evolution is most visible among millennial and Gen-Z demographics seeking personalized hair care regimens.
Hair Conditioner Market Segmentation
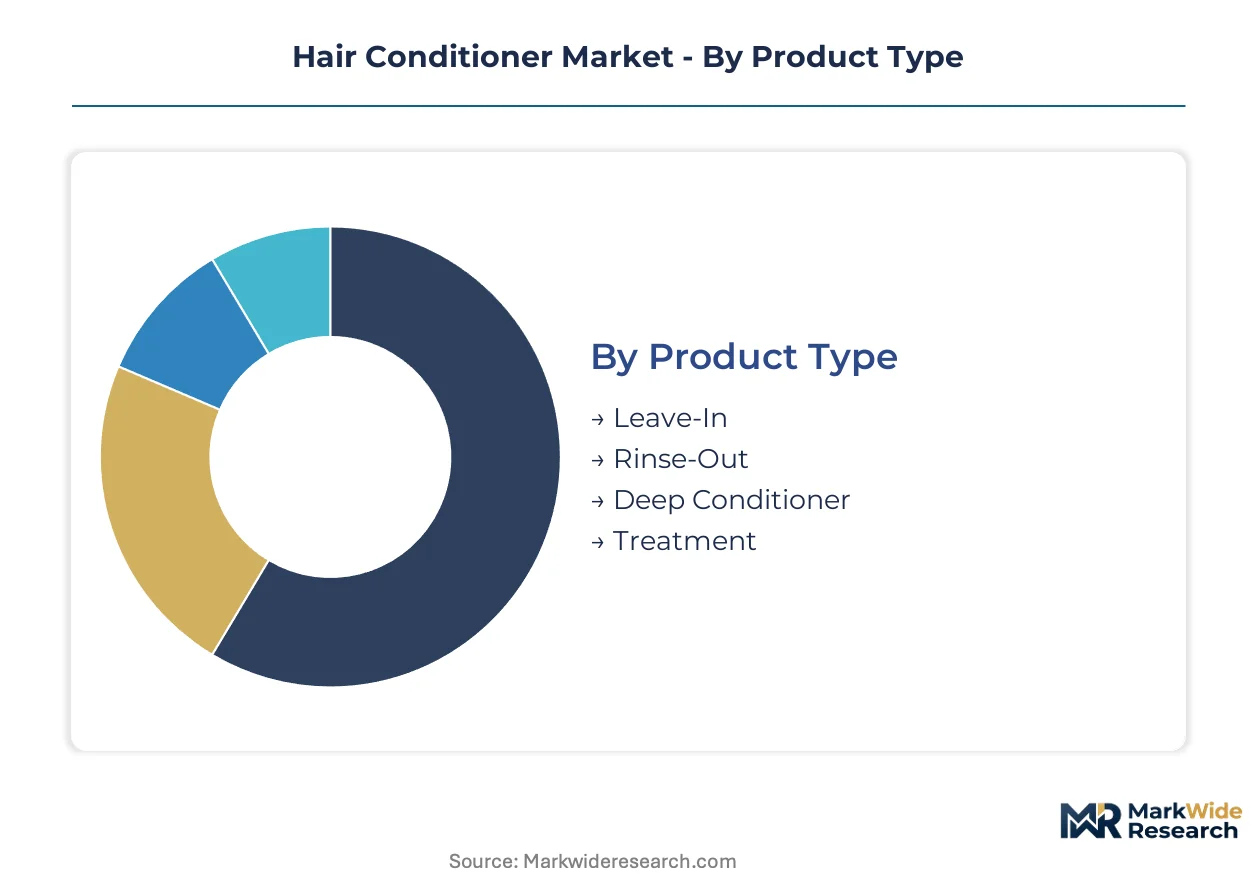
Hair conditioner segmentation reveals distinct upgrade cycles across product tiers, with consumers cycling between daily-use rinse-out formulations and intensive treatment protocols. Channel preferences and formulation chemistry create parallel demand tracks that manufacturers must address through differentiated portfolio architecture.
Product Type:
Upgrade cycles accelerate as consumers layer multiple conditioner formats into expanded hair care routines, shifting from single-product reliance toward protocol-based consumption.
- Rinse-Out:Cationic surfactant-based formulations deposit conditioning agents at pH 3.5–5.5 to restore lipids stripped during shampooing. Daily-use penetration concentrates revenue in Southeast Asian humidity-driven markets where Indonesia and Vietnam consumers apply post-wash treatments as climate-responsive hair management.
- Leave-In:Lightweight formulations designed for heat protection and extended conditioning without rinsing. Demand expansion concentrates among millennial and Gen-Z demographics in Ho Chi Minh City and Jakarta adopting multi-step regimens.
- Deep Conditioner:Treatment-grade formulations targeting intensive lipid restoration through concentrated fatty alcohol and quaternary ammonium compound delivery.
- Treatment:Professional salon-channel products commanding service-based pricing in urban India and Southeast Asian metropolitan corridors.
Volume placements concentrate in Rinse-Out; the faster expansion belongs to Leave-In.
Formulation:
Cost tier differentiation separates mass-market emulsion systems from premium lipid-delivery vehicles, with texture preferences varying by climate and hair type concentration.
- Cream:High-viscosity emulsions containing fatty alcohols and silicones for maximum cuticle deposition. Revenue concentration sits in professional salon channels where service pricing supports premium positioning.
- Lotion:Lower-viscosity fluid systems enabling rapid distribution through hair shafts. Fastest uptake occurs in Southeast Asian online subscription bundles targeting lightweight daily application.
- Oil:Anhydrous or minimal-water formulations leveraging argan, coconut, or fermented squalane for sealing and shine enhancement.
- Gel:Polymer-thickened systems offering defined hold with conditioning benefits, penetrating curly and coily hair segments.
Margin pools concentrate in Cream; steepest expansion trajectory belongs to Oil as biotechnology-derived lipid alternatives rewrite raw material economics.
End User:
Customer type fragmentation demands gender-specific and age-calibrated marketing architecture, with professional channels requiring institutional procurement relationships.
- Women:Primary volume driver across all product tiers, with consumption frequency elevated in tropical urban centers requiring humidity-responsive hair management protocols.
- Men:Emerging segment adopting leave-in and treatment formats as grooming routine complexity increases, particularly in South Korean and Japanese metropolitan markets.
- Children:Mild-formulation demand concentrated in tear-free and hypoallergenic specification requirements.
- Professionals:Salon operators and stylists purchasing treatment-grade conditioners through wholesale distribution, with procurement decisions driven by performance consistency and service compatibility.
Volume concentration remains with Women; the climbing-fastest trajectory belongs to Men as routine expansion accelerates.
Distribution Channel:
Channel maturity varies sharply, with legacy retail facing displacement from direct-to-consumer replenishment models and professional service integration.
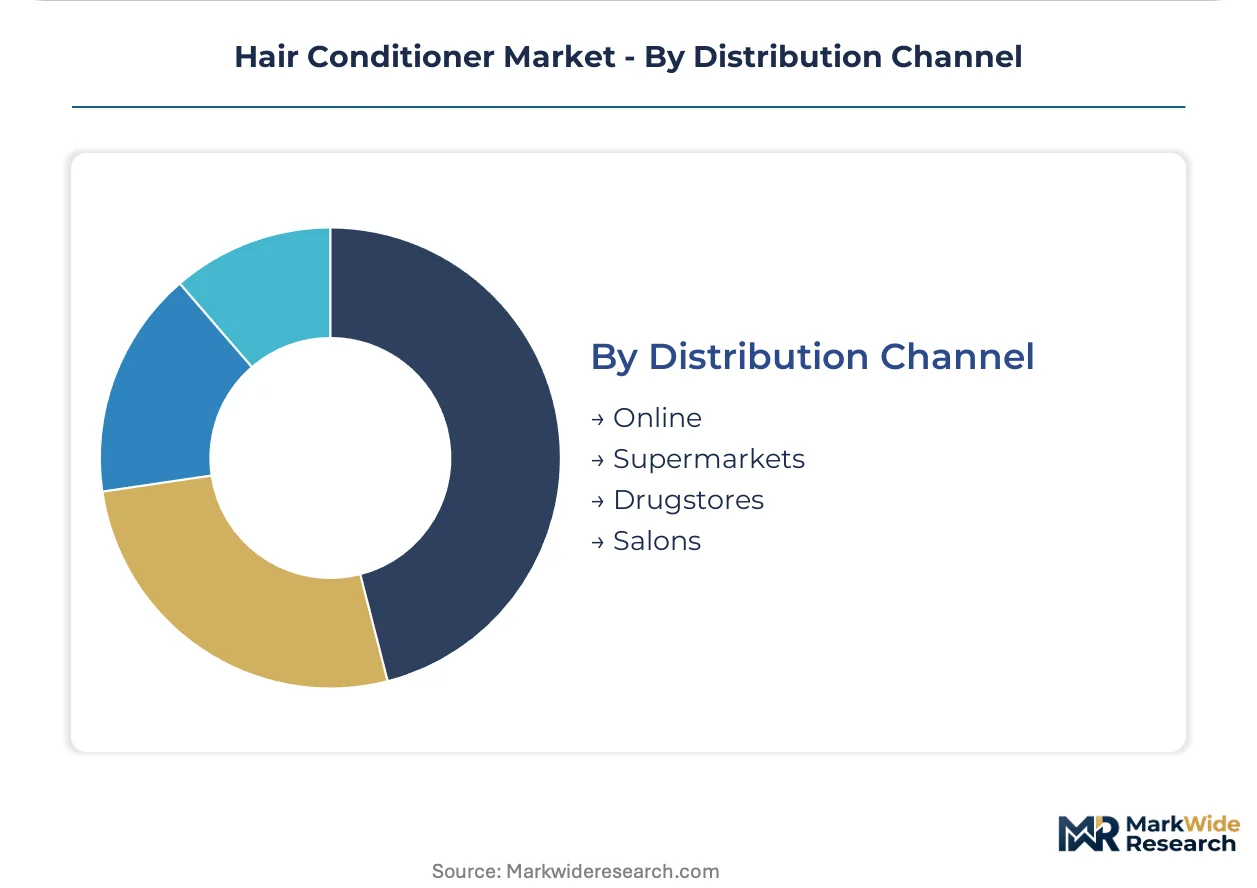
- Supermarkets:Mass-market rinse-out volume concentration through high-frequency stock-keeping unit rotation and promotional pricing cycles.
- Salons:Treatment-grade and professional-exclusive formulations commanding highest margin extraction through service-based pricing in urban India and Southeast Asia.
- Online:Subscription replenishment models displacing traditional retail in Jakarta and Ho Chi Minh City curated bundle deliveries.
- Drugstores:Mid-tier positioning bridging mass and premium segments through pharmacist-adjacent trust positioning.
Volume placements concentrate in Supermarkets; the fastest channel expansion belongs to Online as subscription architecture penetrates Southeast Asian urban demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moroccan argan oil cooperatives anchor supply-side geography for premium lipid sourcing, while Southeast Asian humidity patterns reshape consumption frequency across metropolitan corridors.
United States
California and New York state-level chemical bans on preservatives and fragrance allergens are compressing formulation development cycles. The FDA oversees cosmetic safety labeling under the Federal Food, Drug, and Cosmetic Act. Los Angeles-based direct-to-consumer brands are pioneering subscription replenishment models for treatment-grade conditioners targeting millennial demographics.
India
Humidity-driven daily conditioner use in Mumbai and Delhi-NCR is elevating rinse-out formulation penetration among urban middle-class households. BIS mandates heavy metal testing and full ingredient disclosure for imported cosmetic formulations. Salon operators in Bangalore are consolidating procurement of professional treatment-grade products through wholesale distribution networks.
Indonesia
Jakarta's dense metropolitan population exhibits elevated daily conditioner application rates responsive to tropical climate hair management needs. The country's national cosmetic regulator enforces safety standards aligned with ASEAN harmonization frameworks. Direct-to-consumer subscription bundles are displacing traditional retail stocking patterns among Gen-Z consumers in Surabaya and Bandung.
Vietnam
Ho Chi Minh City consumers are adopting multi-step hair care routines that accelerate leave-in conditioner segment expansion. The Ministry of Health oversees cosmetic product registration with tightening documentation requirements for imported formulations. Urban salon channels in Hanoi are integrating service-based pricing models for deep treatment conditioners targeting professional clientele.
South Korea
Seoul Capital Area consumers drive precision fermentation-derived squalane adoption in rinse-out formulations. MFDS regulates cosmetic safety with accelerated approval pathways for biotechnology-derived ingredients. Professional salon brands in Busan-Ulsan are shortening procurement cycles for fermentation-produced ceramide analogs.
Hair Conditioner Market Key Industry Players
Portfolio diversification dominates the current landscape as incumbent manufacturers reformulate around sulfate-free and silicone-alternative chemistries. The vendor base organizes around three strategic archetypes: integrated multinational consumer goods conglomerates with captive botanical supply chains, mid-tier regional specialists leveraging local formulation expertise, and biotechnology-forward innovators commercializing precision fermentation processes. M&A activity concentrates on Moroccan cooperative supply agreements and Asian digital-native brand acquisitions.
Within the integrated multinational tier, L'Oréal and Procter & Gamble exemplify scale-driven positioning through North American and Asian production network optimization. Unilever occupies a reformulation science position targeting silicone-alternative polymer development. These three conglomerates anchor competitive dynamics through differential investment in captive sourcing from Moroccan cooperatives versus biotechnology-derived lipid platforms.
| Leading Market Players |
|---|
| L'Oréal |
| Procter & Gamble |
| Unilever |
| Henkel |
| The Estée Lauder Companies |
| Johnson & Johnson |
| Kao Corporation |
| Beiersdorf |
| Amway |
| Others |
Cost & Logistics Intelligence
Professional salon operators in Ho Chi Minh City and Jakarta command pricing power through service-bundled treatment protocols, while mass-market rinse-out tiers face compression from direct-to-consumer subscription models. This bifurcation concentrates margin extraction in professional channels while eroding legacy retail markups across Southeast Asian urban corridors.
Pricing Analysis
Service-bundled pricing in professional salons wraps treatment-grade formulations into styling protocols, leaving unbundled retail channels exposed to price transparency. Three-tier pricing structure across premium, standard, and economy levels separates salon-exclusive ceramide concentrates from mass-market cationic surfactants and private-label economy emulsions. Pricing pressure stems from biotechnology-derived squalane cost curves flattening as precision fermentation scales, compressing plant-derived lipid premiums. Mass-market consumers in Indonesian supermarkets exhibit highest price sensitivity; professional salon clients in urban India demonstrate lowest elasticity due to service-integrated value perception.
Supply Chain Analysis
Ocean freight volatility from Moroccan cooperatives through Mediterranean-Suez corridors elevates landed costs for argan oil-dependent formulations. Geographic supply concentration centers on Morocco for argan oil, India for coconut-derived fatty alcohols, and South Korea for fermentation-produced ceramide analogs. Raw material pipelines draw from shea butter West African networks, quaternary ammonium compound Chinese manufacturing bases, and silicone-alternative polymer Japanese specialty chemical producers. Single-source vulnerability runs through Moroccan cooperative harvest cycles exposed to drought-induced yield fluctuations. Distribution runs through professional salon wholesale networks in Southeast Asia, direct-to-consumer subscription platforms in Jakarta and Ho Chi Minh City, and mass-market retail stocking in Indian metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived conditioning agents are displacing plant-extracted lipid platforms, compressing reformulation timelines and rewriting raw material procurement economics across formulation tiers.
For Market Incumbents: To counter biotechnology-forward ingredient commoditization, accelerate captive supply agreements with Moroccan cooperatives and invest in pH-controlled processing line upgrades for novel fatty alcohol-quaternary compound combinations. Secure formulation chemistry talent pools specializing in silicone-alternative polymer science to defend premium positioning against mid-tier private-label encroachment. For New Entrants and Emerging Players: Capture leave-in conditioner white space among millennial and Gen-Z demographics in Surabaya and Bandung through curated subscription bundles emphasizing heat-protective, lightweight protocols. Target professional salon channel fragmentation in Bangalore and Hanoi with treatment-grade positioning backed by local testing partnerships that compress BIS and ASEAN regulatory entry timelines. For Investors and Strategic Acquirers: The window for entry favors biotechnology-forward innovators with precision fermentation capabilities and Asian digital-native brands owning direct-to-consumer subscription infrastructure. Long-term viability hinges on defensible ingredient platforms rather than formulation marketing alone. Watch MFDS and BIS regulatory harmonization progress as inflection signal for accelerated market entry barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Botanical Supply Agreement | Moroccan cooperative integration secures argan oil quality consistency against spot market volatility. |
| Precision Fermentation Scale-Up | South Korean MFDS-approved squalane production rewrites lipid replacement cost structures for mid-tier manufacturers. |
| Direct-to-Consumer Subscription Launch | Jakarta and Ho Chi Minh City replenishment models displace traditional retail stocking patterns among urban millennials. |
| Silicone-Alternative R&D Investment | Polymer science capabilities address EU REACH disclosure mandates while commanding premium positioning. |
| Local Testing Partnership Establishment | Pre-certification laboratories in Mumbai compress BIS heavy metal testing timelines for imported formulations. |
Research Approach
Document review covered customs records, ASEAN cosmetic regulatory filings, and SEC 10-K disclosures from integrated consumer goods conglomerates, complemented by interviews with brand managers, category buyers at Southeast Asian retailers, professional salon procurement heads, and supply planners at Moroccan cooperative networks. Secondary validation drew from BIS cosmetic safety standards documentation, EU REACH substance restriction databases, and MFDS biotechnology ingredient approval pathways. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Cross-referencing historical consumption patterns with panel input from formulation chemists and channel distributors anchored the analytical framework. Segmentation dimensions modeled include product type, formulation chemistry tier, end-user demographic, and distribution channel architecture. CAGRs were derived through iterative reconciliation of primary interview demand signals with secondary trade flow data, incorporating humidity-driven application frequency parameters for tropical urban centers and regulatory compliance cost trajectories for imported formulations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Moroccan harvest volatility, EU REACH substance list expansions, and biotechnology scale-up cost curves. Forecasts reflect documented assumptions about consumer routine adoption rates and regulatory harmonization progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Sustainable Personal Care Market
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Switzerland Cosmetics Market
Beauty & Personal Care
Refillable Deodorants Market
Beauty & Personal Care
Luxury Bath and Body Products Market
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Sun Protection Spray Market
Beauty & Personal Care
Oil Control Lotion Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Global Heated Eyelash Curlers Market
Beauty & Personal Care
US Personal Care Products Market