
 Shaving and Hair Removal Products Market | 2026-2036
Shaving and Hair Removal Products Market Size, Share, and Industry Trends Forecast 2026-2036
Shaving and Hair Removal Products Market Analytics
Laser diode miniaturization is fragmenting the technology stack across portable home-use devices and high-power clinical systems. Alma Lasers leverages its multi-wavelength platform to anchor the professional segment across Middle Eastern and Asian markets. Philips competes through integrated blade systems and connected grooming ecosystems that extend its consumer electronics footprint.
Shaving and hair removal products encompass chemical depilatories, mechanical razors, electric shavers, and optical-laser systems engineered to sever, dissolve, or thermally damage hair follicles across varying skin phototypes, with fluence parameters ranging from 5 J/cm² for home devices to 40 J/cm² for clinical lasers. The primary commercial purpose spans personal grooming, medical dermatology, and professional aesthetic services. Electric shavers and laser systems capture the dominant margin pools as consumers trade up from disposable razors toward rechargeable precision engineering and permanent reduction solutions. Online retail channels now lead volume growth for home-use devices while specialty stores and dermatology clinics sustain premium pricing for clinical-grade equipment.
FDA 510(k) clearance pathways govern laser and intense pulsed light devices in the United States, while the EU MDR and REACH frameworks impose biocompatibility and substance restriction requirements across European markets. China's NMPA classifies high-power laser hair removal systems as Class III medical devices, creating regulatory barriers that favor established manufacturers with clinical trial capabilities. Stakeholders must monitor evolving energy-efficiency standards and dermatological safety protocols as home-use devices approach clinical power thresholds.
Market Dynamics
Laser diode miniaturization is fragmenting the technology stack across portable home-use devices and high-power clinical systems, forcing manufacturers to choose between margin-diluting consumer electronics entry and capital-intensive professional equipment.
Growth Catalysts
- EU MDR compliance windows:Tightened clinical evidence requirements for optical hair removal systems are accelerating consolidation among established manufacturers with trial infrastructure.
- Medical aesthetic chain proliferation:China's tier-one cities host expanding networks of dermatology clinics driving laser device procurement.
- Fluence threshold advancement:Home-use devices approaching clinical power parameters are opening permanent reduction solutions to broader consumer segments.
Market Restraints
- NMPA Class III classification:China's medical device regulator imposes clinical trial mandates that erect barriers for new laser system entrants lacking established capabilities.
- Optical component supply concentration:High-grade laser diode fabrication concentrates among specialized semiconductor foundries, creating input bottlenecks.
- Skin phototype limitation:Melanin absorption constraints in darker skin types restrict addressable population for certain wavelength technologies.
Strategic Opportunities
- Tier-two city penetration:China's secondary urban centers remain underpenetrated for clinical-grade hair removal services relative to saturated tier-one markets.
- Connected grooming ecosystems:Integration of blade systems with subscription-based consumable replenishment creates recurring revenue architectures.
- REACH substance compliance:European chemical restriction frameworks favor depilatory formulations with documented biocompatibility profiles.
Industry Challenges
- Laser safety certification timelines:FDA 510(k) clearance pathways for intense pulsed light devices extend development cycles and compress competitive windows.
- Multi-wavelength platform integration:Engineering teams face complexity harmonizing disparate optical systems within unified device architectures.
- After-sales technical support scaling:Clinical laser deployments require trained service networks that strain manufacturer organizational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shaving and Hair Removal Products Market |
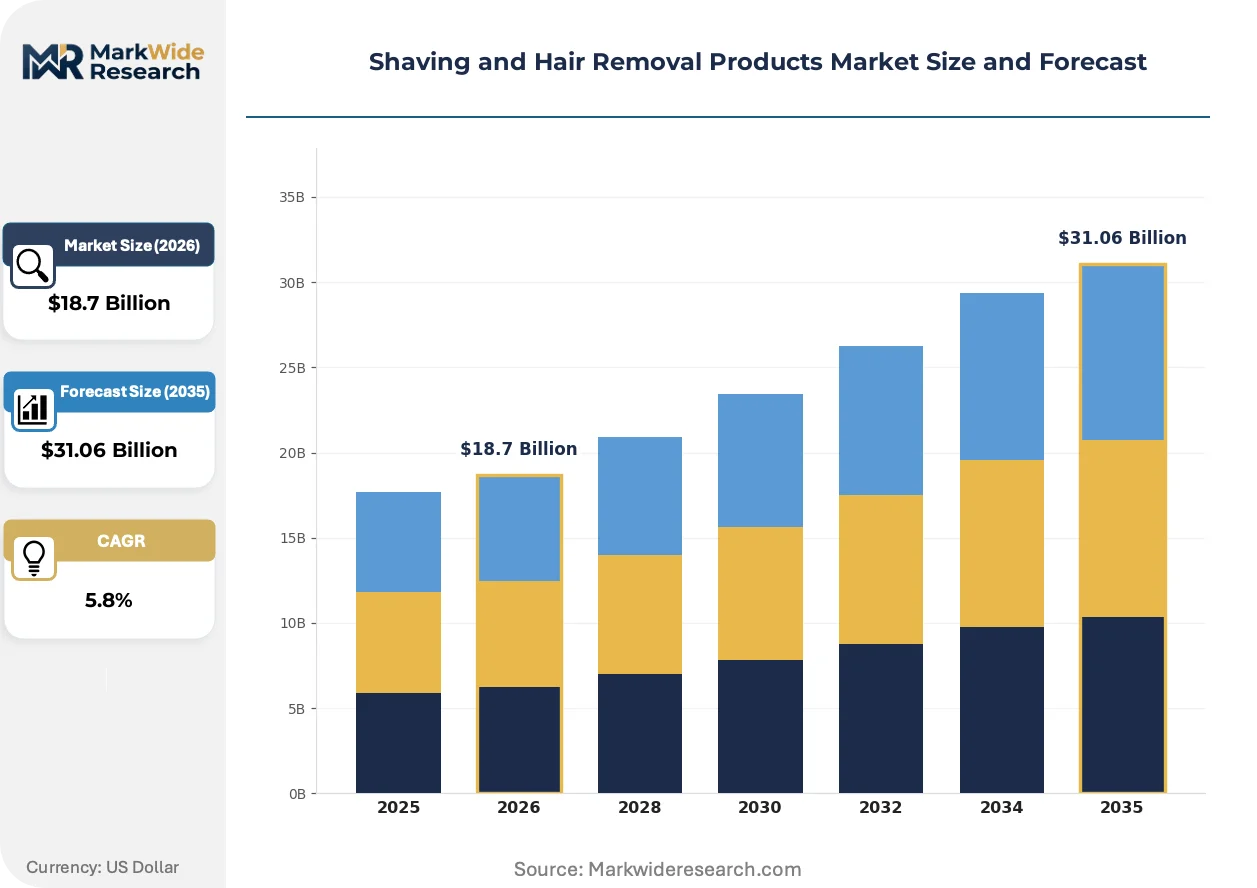
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Razors, Electric Shavers, Wax Strips, Hair Removal Creams End User: Men, Women, Salons, Dermatologists Technology: Chemical, Laser, Optical, Mechanical Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Hologic (Cynosure), Lutronic, Lumenis, Asclepion Laser Technologies, Alma Lasers, Candela Medical, Philips, Fotona, Cutera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shaving and Hair Removal Products Market Evolving Landscape
Energy delivery mechanisms are bifurcating between precision-engineered home devices and clinical-grade thermal systems, with regulatory thresholds increasingly defining competitive boundaries rather than pure technical performance.
Diode laser arrays are migrating from fixed clinical installations toward handheld form factors with equivalent fluence output. Aesthetic medicine practitioners in Seoul and Tokyo are adopting portable systems for mobile service delivery. This migration is compressing the historical separation between professional and consumer device categories, forcing incumbents to defend margin structures across both tiers simultaneously.
REACH substance restriction frameworks are eliminating certain chemical depilatory active ingredients from European formulations. Formulation laboratories are pivoting toward enzymatic and plant-derived alternatives with documented dermatological safety profiles. Manufacturers with pre-positioned compliant portfolios capture shelf space as retailers delist non-conforming products ahead of enforcement deadlines.
Subscription replenishment models are displacing transactional razor cartridge purchases in North American and Western European markets. Direct-to-consumer channels capture recurring revenue streams while specialty retailers lose attach-rate leverage. Dermatology clinics in Germany and France report patient acquisition cost compression through bundled home-device plus in-clinic treatment packages.
Shaving and Hair Removal Products Market Segmentation
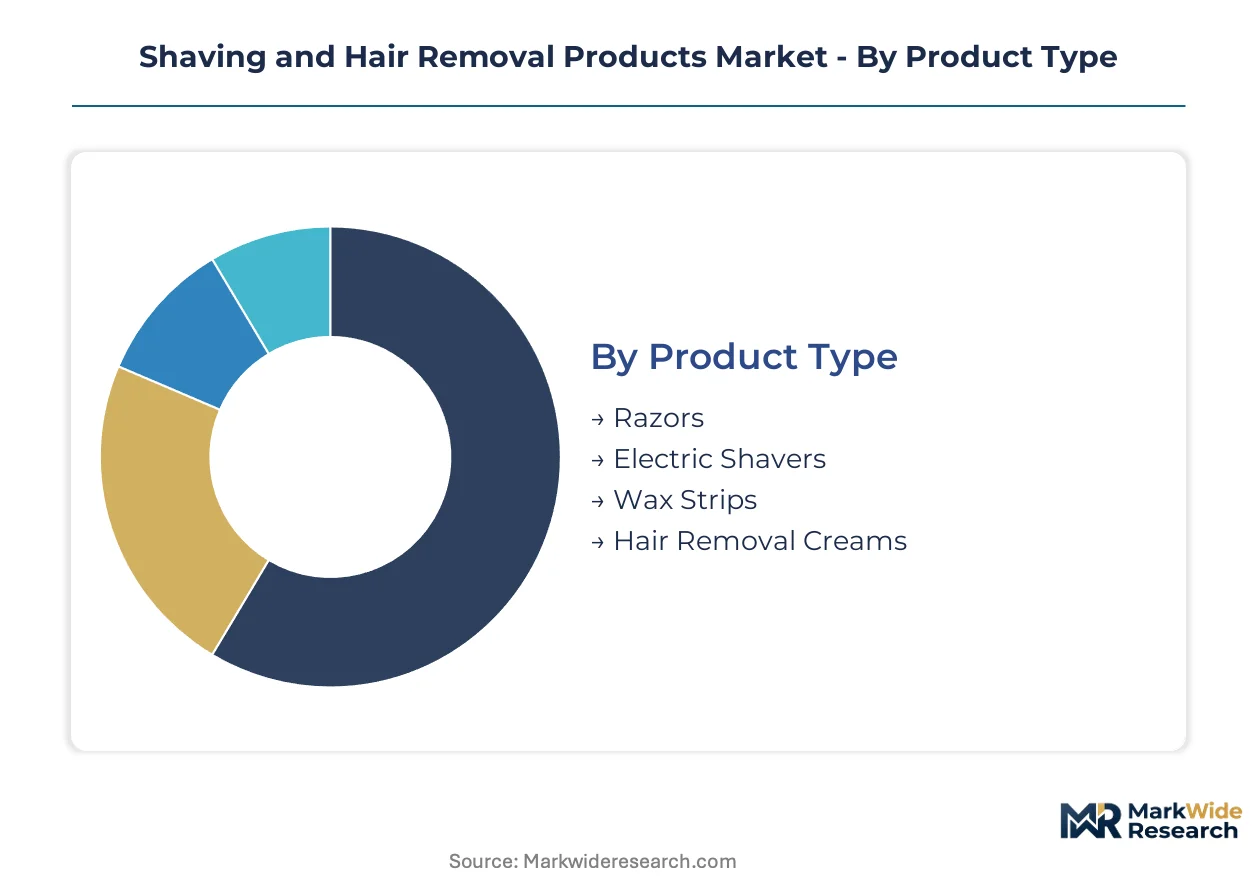
Technology divergence across portable and clinical systems fragments procurement patterns. Service intensity varies sharply between disposable consumables and capital equipment requiring trained maintenance networks.
Product Type:
After-sales service intensity escalates dramatically from single-use disposables to precision-engineered systems requiring calibration protocols and replacement part logistics.
- Razors:Twin-blade and five-blade cartridge systems dominate mass-market shelf space. Demand clusters in North American drugstore chains where subscription replenishment models displace transactional purchasing.
- Electric Shavers:Rotary and foil-head architectures with lithium-ion power management and waterproof IPX7 ratings. German engineering houses and Japanese electronics manufacturers anchor premium positioning through integrated cleaning stations and blade-tracking sensors.
- Wax Strips:Pre-coated fabric substrates with rosin or polymer adhesive formulations. Salon professionals in France and Italy favor microwaveable variants for service flexibility.
- Hair Removal Creams:Thioglycolate-based depilatory formulations with pH buffering systems. REACH compliance pressures are eliminating legacy active ingredients from European formulations.
Electric shavers hold the largest share; momentum sits with hair removal creams as enzymatic alternatives gain regulatory clearance.
End User:
Volume concentration diverges between high-frequency individual purchasers and capital-intensive professional service providers with extended replacement cycles.
- Men:Facial grooming dominance with neck and body hair expansion. Beard-trimming attachments now standard in multi-head electric systems sold through UK and Australian mass retailers.
- Women:Leg, underarm, and facial hair management spanning disposable and permanent reduction modalities. Brazilian and Korean consumers drive premium waxing service frequency.
- Salons:High-throughput service operations requiring durable wax warmers and hard-wax formulations. Equipment procurement concentrates in urban clusters with elevated disposable income.
- Dermatologists:Medical-grade laser and IPL systems with documented fluence parameters for Fitzpatrick skin type protocols. Seoul and Tokyo clinics lead diode laser adoption for permanent reduction services.
Women represent the deepest volume base; dermatologists are climbing the fastest as medical aesthetic chains proliferate.
Technology:
Margin stratification separates commodity chemical processes from semiconductor-dependent optical systems with specialized fabrication requirements.
- Chemical:Alkaline depilatory agents with keratin-disruption mechanisms. Formulation laboratories in Germany and Switzerland pivot toward plant-derived enzymatic substitutes under ECHA substance restriction timelines.
- Laser:Diode arrays at 755nm, 808nm, and 1064nm wavelengths with selective photothermolysis targeting. FDA 510(k) clearance pathways govern US market entry; EU MDR clinical evidence requirements accelerate consolidation among trial-capable manufacturers.
- Optical:Broadband intense pulsed light systems with cut-off filters for skin type adaptation. Home-use devices approaching clinical fluence thresholds are compressing the professional-consumer boundary.
- Mechanical:Precision-ground blade edges with titanium nitride coatings and pivot-head articulation. Japanese steel foundries supply premium substrate material for sustained edge retention.
Mechanical systems command the broadest installed base; laser platforms are expanding most quickly as miniaturization enables portable form factors.
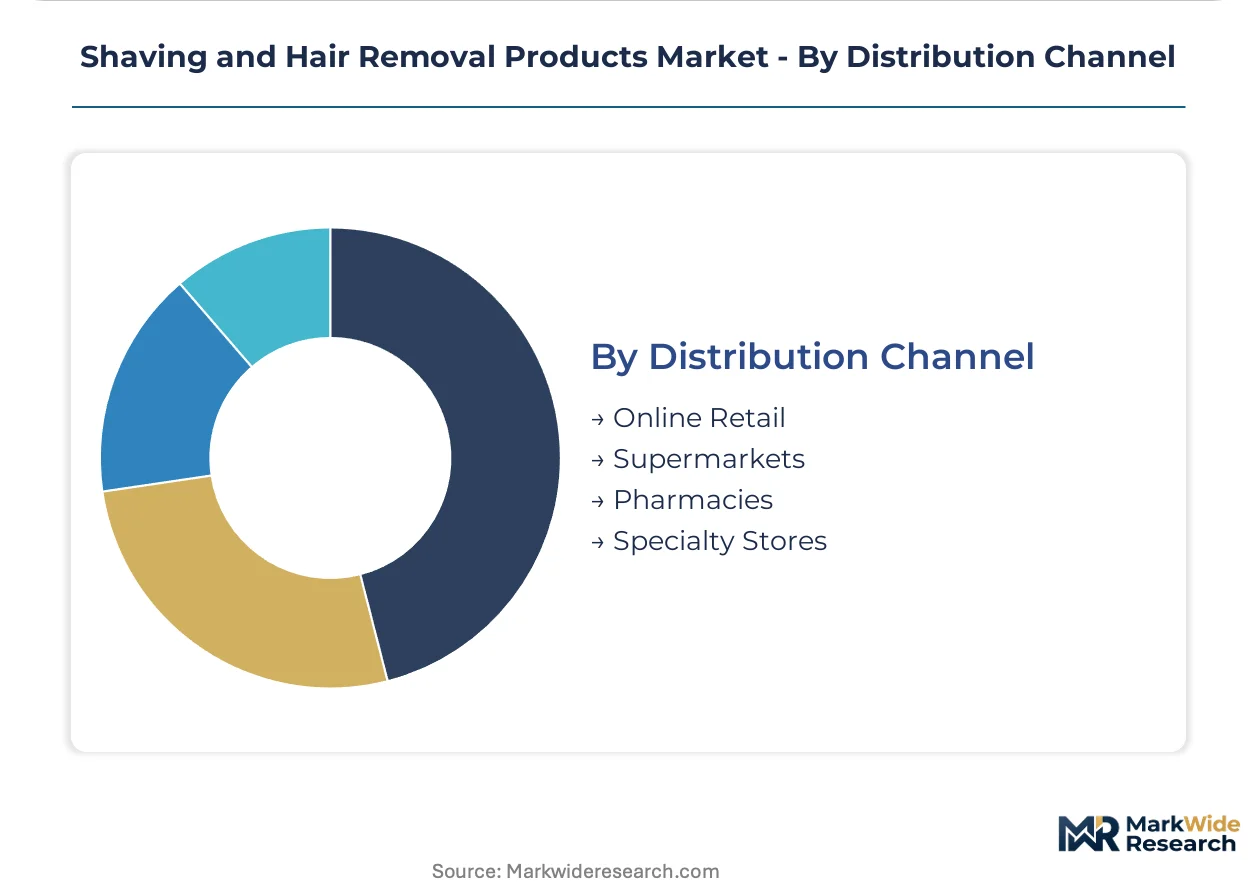
Distribution Channel:
Channel economics fragment between low-touch digital fulfillment and high-touch service environments requiring trained consultation.
- Online Retail:Direct-to-consumer platforms with subscription architecture and replenishment algorithms. Amazon and dedicated brand sites capture recurring razor cartridge revenue previously held by supermarkets.
- Supermarkets:Mass-market blade and depilatory placement with promotional slotting fees. UK and US chains are reducing SKU counts as private-label alternatives capture shelf space.
- Pharmacies:Dermatologist-recommended sensitive-skin formulations and post-treatment care products. French and Italian pharmacy networks maintain professional consultation standards for hair removal cream selection.
- Specialty Stores:Premium electric shaver demonstration and clinical laser system procurement. German electronics retailers and Korean medical aesthetic equipment distributors sustain margin through technical service bundling.
Supermarkets retain the largest transaction volume; online retail is gaining share fastest through subscription lock-in mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered electric shavers and diode laser components to Middle Eastern medical aesthetic chains and North American retail networks, establishing the dominant west-east trade corridor for clinical-grade equipment.
United States
FDA 510(k) clearance pathways govern laser and intense pulsed light device commercialization, extending development timelines for new entrants. Subscription-based razor replenishment models through direct-to-consumer channels now capture significant recurring revenue previously held by brick-and-mortar retailers. Miami and Los Angeles dermatology clusters drive adoption of portable diode systems for mobile aesthetic service delivery.
Germany
Engineering houses in Solingen and Stuttgart anchor premium electric shaver manufacturing through integrated cleaning stations and blade-tracking sensors. REACH substance restriction frameworks eliminate legacy thioglycolate active ingredients from depilatory formulations, favoring compliant enzymatic alternatives. Bavarian medical device distributors sustain margin through technical service bundling for clinical laser procurement.
China
NMPA Class III medical device classification imposes clinical trial mandates for high-power laser hair removal systems, erecting barriers for entrants lacking established capabilities. Tier-one cities host expanding networks of dermatology clinics driving laser device procurement. Shanghai and Beijing medical aesthetic chains proliferate permanent reduction services while tier-two urban centers remain underpenetrated.
South Korea
Seoul dermatology clinics lead diode laser adoption for permanent hair reduction services, with practitioners adopting portable systems for mobile delivery. MFDS medical device regulations align with international standards while maintaining rigorous biocompatibility documentation requirements. Gangnam district aesthetic medicine clusters compress patient acquisition costs through bundled home-device plus in-clinic treatment packages.
Japan
Tokyo aesthetic practitioners drive demand for multi-wavelength laser platforms with selective photothermolysis protocols across Fitzpatrick skin types. METI energy-efficiency standards influence home-use device power management specifications. Osaka and Nagoya electronics manufacturers supply precision laser diode arrays for both domestic clinical installations and export markets.
Shaving and Hair Removal Products Market Competitive Landscape
On the supply side, the industry is bifurcated between capital-intensive professional equipment manufacturers and consumer electronics houses with integrated grooming portfolios. The vendor base stratifies across three tiers: semiconductor-dependent laser system specialists, precision mechanical engineering houses, and mass-market blade consumables producers. Dominant competitive moves include portfolio diversification across professional-consumer boundaries and geographic expansion through distributor partnerships in underpenetrated Asian urban centers.
Within the laser systems tier, Hologic (Cynosure), Lumenis, and Alma Lasers exemplify the capital-intensive archetype with multi-wavelength platform architectures. These entities occupy positions anchored by clinical trial infrastructure and regulatory clearance capabilities across FDA, EU MDR, and NMPA jurisdictions. Philips represents the consumer electronics integration archetype, leveraging connected grooming ecosystems and subscription replenishment mechanics to extend its footprint from mass retail into premium personal care. Lutronic and Candela Medical sit within the specialized professional equipment segment, serving dermatology clinic networks in Seoul, Tokyo, and European metropolitan markets.
| Leading Market Players |
|---|
| Hologic (Cynosure) |
| Lutronic |
| Lumenis |
| Asclepion Laser Technologies |
| Alma Lasers |
| Candela Medical |
| Philips |
| Fotona |
| Cutera |
| Others |
Value Network & Pricing Analysis
Undercapacity in Japanese laser diode foundries is compressing component availability for both clinical and home-use device tiers, forcing manufacturers to absorb input cost volatility or pass through to end markets while scrambling for alternative qualified suppliers.
Pricing Analysis
Current-generation diode laser systems command substantial premiums over prior-generation IPL platforms, while next-generation multi-wavelength architectures remain in limited release with restricted availability. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical systems from CE-marked professional devices and uncertified home-use alternatives. Pricing pressure stems from REACH compliance costs in European depilatory formulations and NMPA trial expenses for China market entry. Salon procurement teams exhibit highest price sensitivity, while dermatology clinics prioritize fluence reliability over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese EMS providers for home-use device assembly and German precision engineering houses for clinical system fabrication. Geographic supply concentration centers on Japan for laser diode arrays, China for lithium-ion power management components, and Germany for precision-ground blade substrates. Raw material dependencies include gallium arsenide wafers, titanium nitride coatings, and thioglycolate precursor chemicals. Single-source vulnerability concentrates in specialized semiconductor foundries. Distribution runs through direct-to-consumer platforms for consumables and specialty medical equipment distributors for capital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of clinical trial infrastructure and multi-jurisdiction regulatory clearance capabilities is concentrating competitive advantage among established manufacturers, leaving aspirant entrants dependent on partnership strategies or niche positioning.
For Market Incumbents: Pre-empt margin erosion in home-use segments by accelerating backward integration into laser diode supply and securing exclusive distribution through Korean medical aesthetic chains. Counter portable device commoditization through proprietary wavelength patents and embedded subscription software. Prioritize EU MDR technical documentation investment to exploit competitor clearance delays. For New Entrants and Emerging Players: Establish a beachhead in tier-two Chinese cities where clinical-grade service penetration lags saturation levels seen in Shanghai and Beijing. Target enzymatic depilatory formulations for European markets facing REACH substance restrictions. Deploy direct-to-consumer subscription mechanics to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Capital is best deployed toward multi-wavelength platform specialists with established FDA and NMPA clearances rather than single-technology device manufacturers facing obsolescence risk. Long-term viability favors entities with clinical trial capabilities spanning US, European, and Chinese regulatory jurisdictions. Monitor NMPA Class III approval velocity as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Regulatory Clearance | NMPA, FDA, and EU MDR simultaneous approval creates defensive moats against fast-follower competition. |
| Backward Integration into Laser Diode Supply | Captive semiconductor sourcing insulates margin from Japanese foundry capacity constraints. |
| Subscription-Based Consumable Replenishment | Recurring revenue architecture locks in razor cartridge demand previously held by supermarkets. |
| Enzymatic Formulation Pivot | REACH-compliant depilatory portfolios capture shelf space as retailers delist thioglycolate alternatives. |
| Tier-Two City Clinic Network Expansion | Underpenetrated Chinese secondary markets offer patient acquisition cost advantages versus saturated tier-one clusters. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dermatology clinic operators, medical device procurement managers, and formulation laboratory directors; and secondary validation against FDA 510(k) filings, NMPA approval databases, ECHA substance restriction timelines, and customs trade records. Bottom-up segmentation modeling triangulated with top-down market sizing across technology tiers and distribution channels.
Forecast inputs considered fluence parameter advancement trajectories, regulatory clearance pipeline velocity, and medical aesthetic chain expansion patterns across the analysis window. Segmentation dimensions modeled include product type, end user archetype, technology platform, and distribution channel. CAGRs derived from installed base growth rates and replacement cycle compression in portable device categories.
Sensitivities concentrate around NMPA regulatory timeline extensions, laser diode foundry capacity allocation shifts, and REACH enforcement acceleration for chemical depilatories. Quarterly review of clearance approval velocity, component lead time indicators, and retailer delisting announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Bar Soap Market
Beauty & Personal Care
Beauty and Personal Care Surfactants Market
Beauty & Personal Care
Natural Deodorant Crystal Market
Beauty & Personal Care
Beard Straightener Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
US Sexual Wellness Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Luxury Personal Care and Cosmetics Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Asia-Pacific Hair Removal Wax Market