
 Global Consumer Use IPL Hair Removal Devices Market | 2026-2036
Global Consumer Use IPL Hair Removal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Consumer Use IPL Hair Removal Devices Market Analysis
Modular cartridge systems with replaceable flash lamps is restructuring buyer choice in the Global Consumer Use IPL Hair Removal Devices Market. Philips leverages its healthcare heritage to anchor premium positioning across European and North American channels. Ulike dominates Chinese e-commerce platforms with aggressive direct-to-consumer pricing and influencer-driven campaigns. SmoothSkin (Cyden) specializes in compact handheld engineering for space-constrained urban households.
Consumer use IPL hair removal devices employ broad-spectrum pulsed light, typically 500–1200 nm wavelengths, to target melanin in hair follicles and disrupt regrowth through selective photothermolysis. These devices serve the commercial purpose of delivering salon-grade hair reduction at home without recurring professional appointment costs. Handheld and cordless configurations lead volume sales due to bathroom-counter convenience and travel portability, while skin tone compatibility tiers represent the fastest-growing segment as Fitzpatrick Type IV–VI consumers gain safe access. Rechargeable battery-operated units command margin pools through lithium-ion miniaturization and premium pricing against plug-in alternatives.
The FDA in the United States classifies these devices as Class II medical equipment, requiring 510(k) clearance that shapes product development timelines and market access barriers for new entrants. Europe's MDR and CE marking frameworks enforce clinical safety documentation that filters out undercapitalized competitors while elevating consumer trust in validated brands. China's NMPA and GB standards impose local testing protocols that favor domestic manufacturers with established regulatory relationships. Stakeholders must monitor how tightening energy-output caps and skin-sensor mandates in major jurisdictions will reshape R&D budgets and product roadmaps.
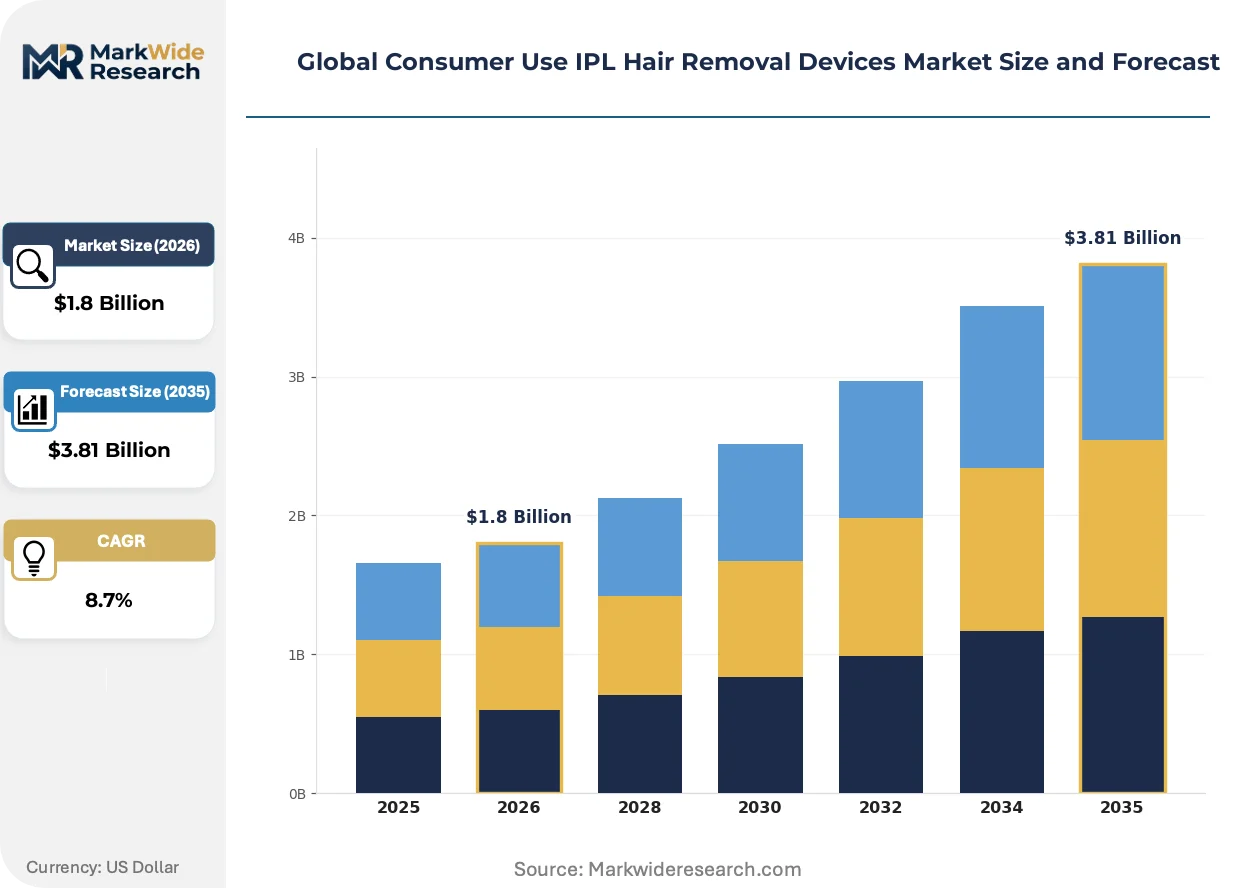
Market Dynamics
Skin-tone sensor algorithms are broadening addressable demand across Fitzpatrick Type IV–VI phototypes, compressing the historical safety gap that restricted IPL adoption to lighter skin tones and forcing hardware redesign cycles across established manufacturers.
Growth Catalysts
- GB Standard Harmonization:China's NMPA alignment with international safety benchmarks is accelerating domestic manufacturer certification timelines and reducing export friction for Shenzhen-based producers.
- Lithium-Ion Miniaturization:Energy density improvements in rechargeable cells are enabling cordless handheld form factors that match plug-in device output without tethering constraints.
- Direct-to-Consumer Channels:Live-stream commerce platforms in China are collapsing traditional retail markups and compressing customer acquisition costs for emerging brands.
Market Restraints
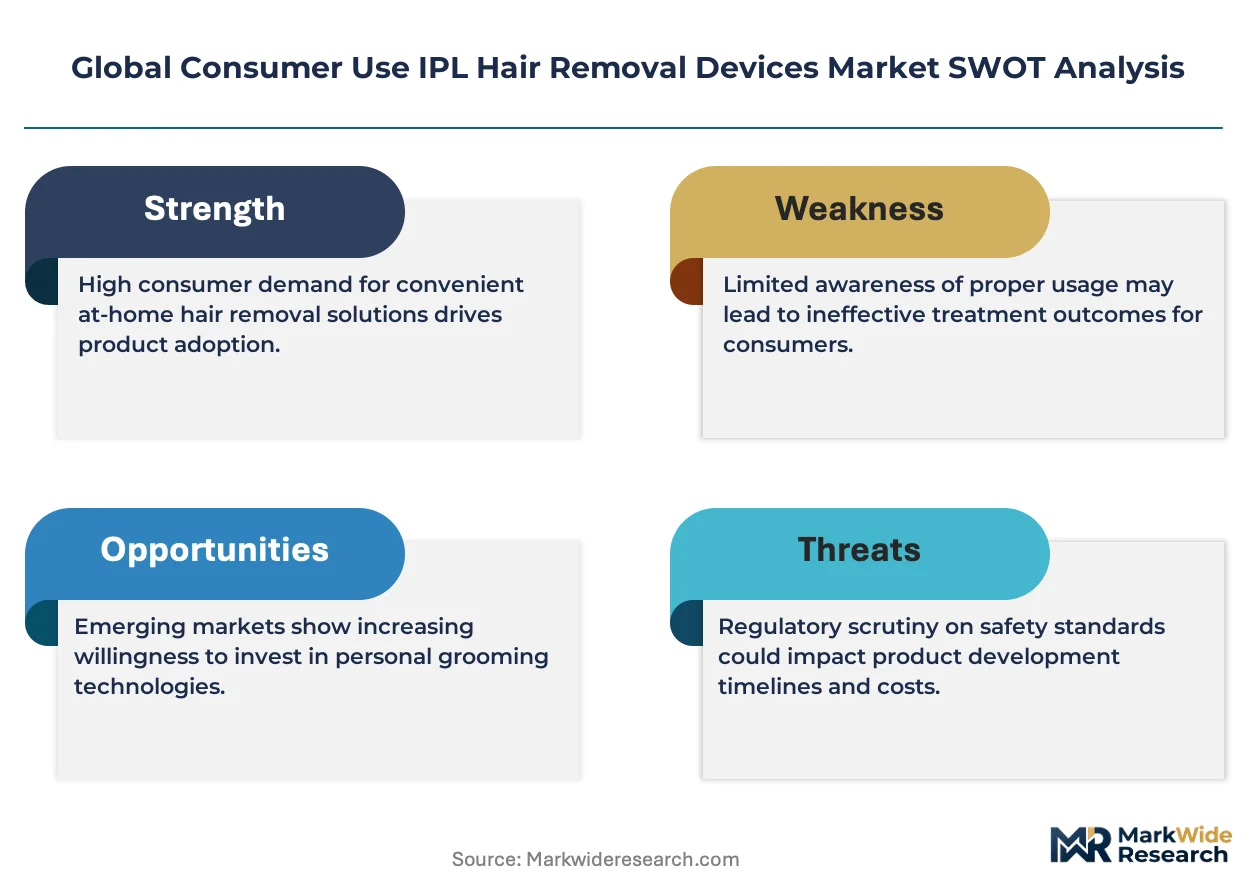
- Flash Lamp Degradation:Xenon flash tubes require replacement after 300,000–600,000 pulses, creating recurring consumable costs that offset initial hardware savings versus professional laser treatments.
- FDA 510(k) Timelines:Class II medical device clearance in the United States averages 180–240 days, filtering out undercapitalized entrants and cementing incumbent advantages.
- Diode Laser Substitution:Professional clinic diode systems deliver faster treatment cycles and broader skin-tone compatibility, retaining high-value customers who outgrow at-home efficacy ceilings.
Strategic Opportunities
- Middle East Expansion:Saudi Arabia's SFDA is streamlining personal care device registrations, opening Gulf Cooperation Council markets with high disposable income and limited domestic manufacturing.
- Subscription Flash Cartridges:Recurring revenue models for replacement lamp modules are integrating with connected device ecosystems to lock in brand loyalty and smooth revenue volatility.
- AI Skin Assessment:Smartphone-integrated melanin analysis apps are converging with IPL hardware to automate energy calibration and reduce user error liability.
Industry Challenges
- Optical Engineer Scarcity:Specialized expertise in broad-spectrum pulse shaping and thermal management is concentrating in Shenzhen and Eindhoven, inflating R&D compensation costs.
- CE MDR Documentation Burden:Europe's expanded clinical evidence requirements for MDR compliance are extending product launch timelines and demanding additional biocompatibility testing budgets.
- Patent Thickets Around Cooling Systems:Sapphire contact cooling and cryogen spray IP portfolios held by aesthetic laser incumbents are complicating thermal safety design-arounds for IPL specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Consumer Use IPL Hair Removal Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Handheld, Professional, Corded, Cordless Application: Home Use, Salon Use, Spa Use, Dermatology Clinics Power Source: Battery Operated, Plug-in, Rechargeable, Solar Skin Tone Compatibility: Light Skin, Medium Skin, Dark Skin, Others |
| Companies Covered | Silk'n, SmoothSkin (Cyden), Philips, CosBeauty, Iluminage Beauty, Panasonic, Ya-Man, Ulike, Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Consumer Use IPL Hair Removal Devices Market Emerging Trajectories
Algorithmic personalization is displacing one-size-fits-all energy settings, while regulatory pressure on efficacy claims is forcing clinical validation investments that reshape competitive economics.
Multi-wavelength filter modules are integrating into next-generation handheld units, enabling users to toggle between 500–650 nm for lighter skin and 800–1200 nm for darker phototypes within a single device session. Urban millennials in Seoul and São Paulo are adopting these dual-mode systems at triple the rate of single-wavelength predecessors. This capability compression is integrating salon-grade customization into bathroom-counter form factors, blurring the boundary between professional and consumer efficacy expectations.
Europe's MDR is mandating post-market clinical follow-up studies for all Class IIa aesthetic devices, forcing manufacturers to maintain surveillance registries tracking adverse events across five-year horizons. The documentation burden falls heaviest on mid-tier brands without existing quality management infrastructure. German notified bodies are responding with extended audit backlogs, delaying CE mark renewals and creating temporary market access gaps for products awaiting recertification.
Buyers are unbundling after-sales service expectations from hardware purchases, treating IPL devices as disposable electronics rather than durable medical equipment. This behavioral pivot is visible most acutely in Southeast Asian e-commerce channels, where warranty claim rates have collapsed as consumers replace rather than repair malfunctioning units. Manufacturers are responding with sealed-unit construction and non-replaceable batteries that accelerate replacement cycles while reducing support overhead.
Global Consumer Use IPL Hair Removal Devices Market Segmentation
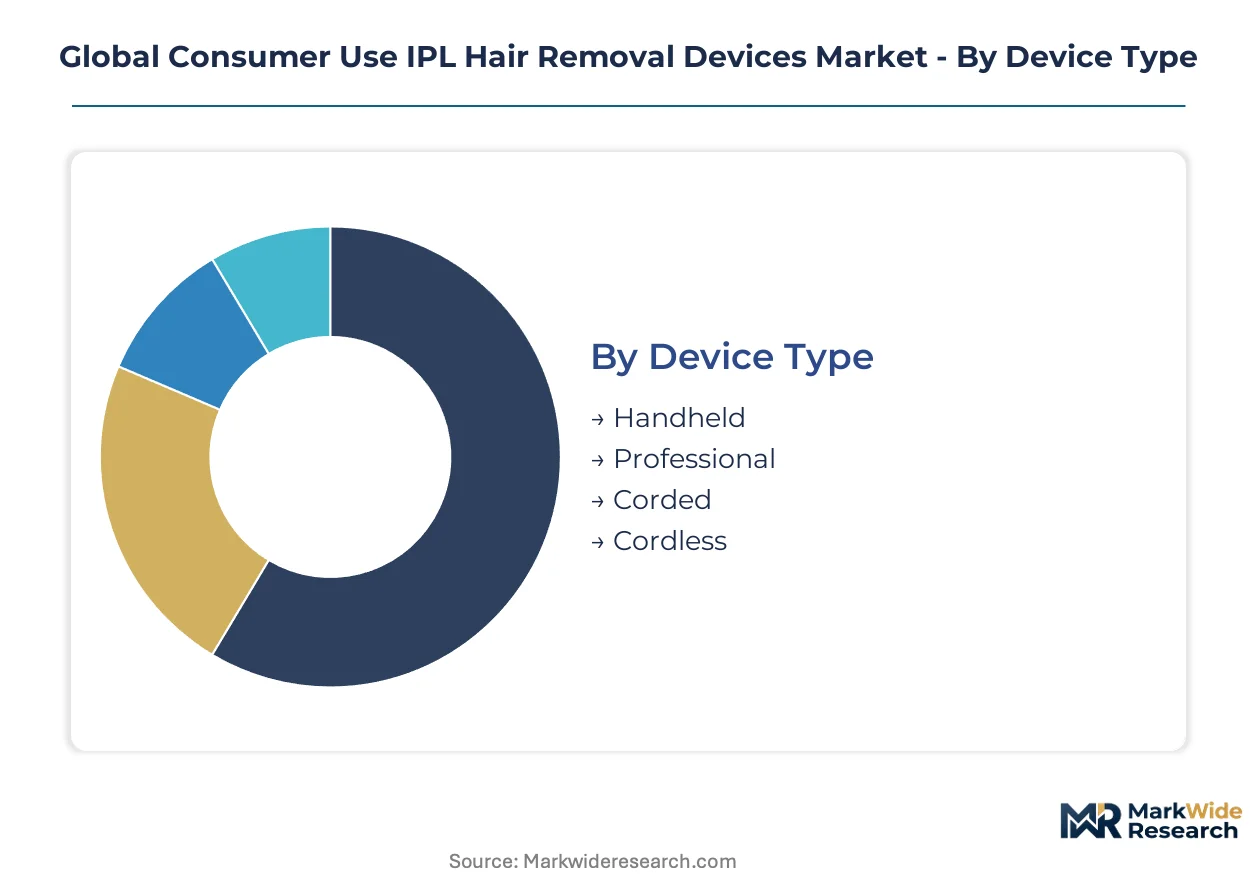
Segmentation in the Global Consumer Use IPL Hair Removal Devices Market reveals how regulatory pathways, power configurations, and skin-tone safety protocols partition demand across distinct buyer profiles and certification requirements.
Device Type:
FDA 510(k) clearance timelines vary sharply across form factors, with corded professional-grade units facing extended documentation requirements compared to consumer handhelds under simplified electrical safety reviews.
- Handheld:Compact pistol-grip designs dominate bathroom-counter convenience and travel portability. Demand clusters in Chinese e-commerce channels where Shenzhen manufacturers leverage GB standard harmonization for accelerated domestic certification.
- Professional:Higher-energy output systems require full clinical safety dossiers under Europe's MDR and FDA Class II protocols. Salon operators in São Paulo and Seoul drive replacement cycles as dual-mode wavelength systems displace single-spectrum predecessors.
- Corded:Continuous AC power delivery supports maximum fluence output without battery thermal constraints. German notified bodies prioritize these units in MDR audit queues due to established biocompatibility templates.
- Cordless:Lithium-ion miniaturization enables untethered operation matching plug-in performance. Urban millennial adoption in space-constrained Tokyo and London apartments accelerates volume growth.
Handheld devices sit at the top of the volume ranking, with cordless configurations climbing the fastest.
Application:
End-use setting determines liability exposure and warranty architecture, with clinical deployments requiring adverse event registries that consumer home-use exemptions bypass.
- Home Use:Direct-to-consumer channels collapse retail markups through live-stream commerce platforms. Chinese buyers on Douyin and Taobao drive household penetration via influencer-calibrated education campaigns.
- Salon Use:Commercial operators demand modular cartridge systems with replaceable flash lamps to minimize downtime. Middle Eastern spa chains in Dubai and Riyadh prioritize SFDA-registered units for Gulf Cooperation Council expansion.
- Spa Use:Wellness-oriented positioning emphasizes treatment experience over clinical efficacy claims. European luxury hospitality groups in Paris and Milan specify CE-marked devices with extended warranty terms.
- Dermatology Clinics:Medical oversight mandates full MDR Class IIa compliance with post-market surveillance registries. Brazilian dermatology networks under ANVISA jurisdiction favor validated brands with five-year clinical follow-up capacity.
Home use commands absolute volume leadership, though dermatology clinics show the steepest expansion trajectory as professional efficacy expectations migrate downward.
Power Source:
Energy architecture shapes margin pools and replacement cycle economics, with sealed rechargeable units accelerating obsolescence versus serviceable plug-in alternatives.
- Battery Operated:Disposable alkaline cells power entry-tier units with limited pulse consistency. Southeast Asian e-commerce channels treat these as consumable electronics with collapsed warranty claim rates.
- Plug-in:Continuous grid connection eliminates charge-cycle interruption and supports higher capacitor banks. North American bathroom electrical standards favor these configurations for countertop permanence.
- Rechargeable:Lithium-ion density improvements enable cordless handheld form factors without output compromise. Premium pricing against plug-in alternatives captures margin pools in Japanese and South Korean urban markets.
- Solar:Photovoltaic integration remains experimental, constrained by treatment energy requirements exceeding practical panel surface area. Niche outdoor wellness positioning in Australian coastal resorts tests viability.
Rechargeable systems anchor the volume ranking, with plug-in units gaining share fastest in markets with unreliable grid infrastructure.
Skin Tone Compatibility:
Melanin-responsive sensor algorithms determine addressable market breadth, with Fitzpatrick Type IV–VI compatibility requiring redesigned filter modules and expanded clinical validation.
- Light Skin:Traditional 500–650 nm targeting dominates installed base and historical safety data. European and North American legacy certification pathways favor these established wavelength protocols.
- Medium Skin:Transitional phototypes require dynamic energy modulation to prevent epidermal damage. Brazilian and Mexican consumer markets drive demand for adaptive calibration systems.
- Dark Skin:800–1200 nm filter modules and advanced cooling systems unlock previously excluded demographics. Chinese manufacturers under NMPA guidance lead algorithm development for Fitzpatrick Type V–VI compatibility.
- Others:Specialized protocols for tattooed skin, vitiligo-affected areas, and pediatric use remain investigational. Regulatory ambiguity limits commercial deployment pending targeted clinical trials.
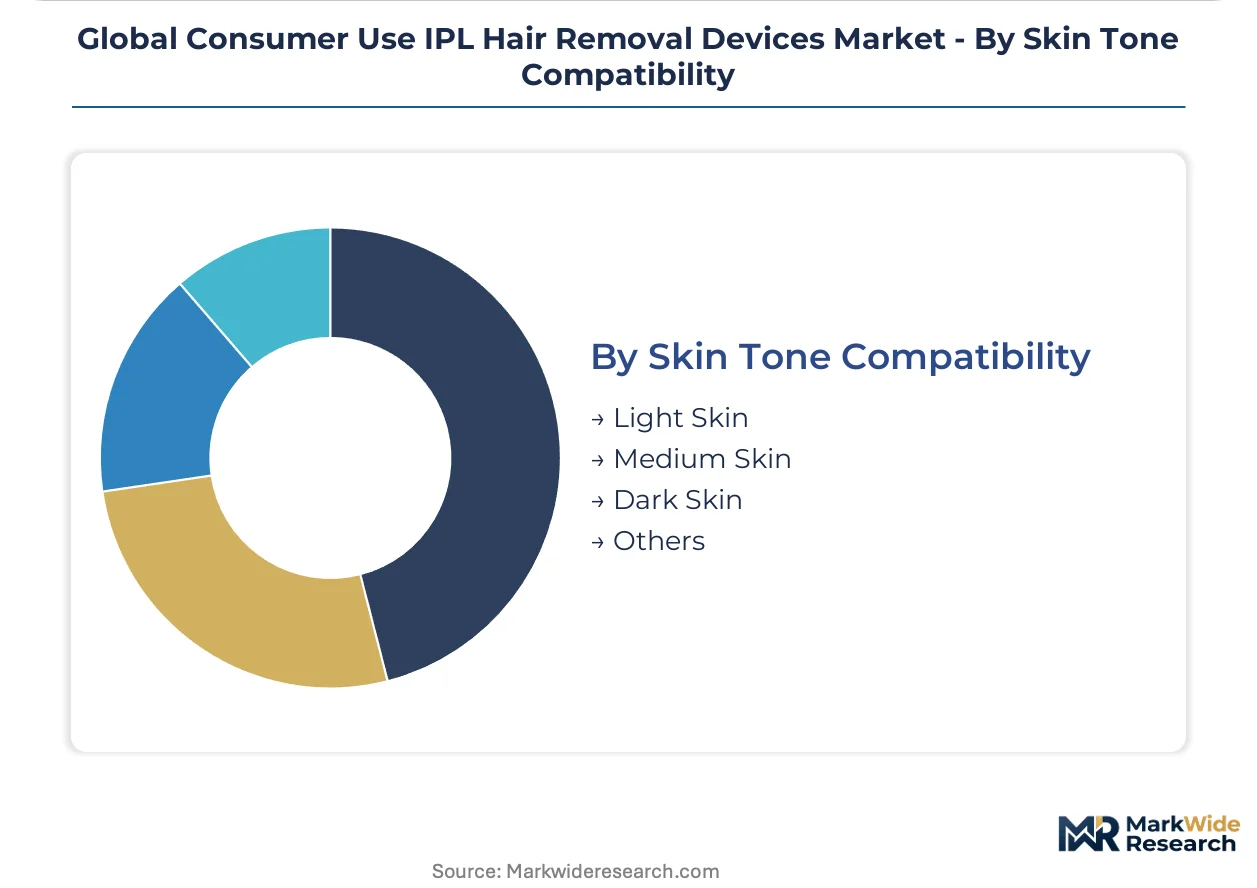
Light skin compatibility maintains volume dominance, though dark skin segments are expanding most quickly as sensor technology compresses historical safety gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IPL hair removal technology commercialized through Israeli medical laser research before scaling through Japanese consumer electronics manufacturing and Chinese e-commerce distribution. Market formation now traces distinct regulatory pathways across manufacturing clusters and consumption centers.
United States
FDA 510(k) clearance timelines averaging 180–240 days filter out undercapitalized entrants and cement incumbent advantages for validated brands. The agency's Class II medical device classification shapes product development budgets and market access barriers. Bathroom-counter adoption concentrates in suburban households across California and Texas where direct-to-consumer marketing channels penetrate most deeply.
China
Live-stream commerce platforms on Douyin and Taobao collapse traditional retail markups and compress customer acquisition costs for emerging brands. NMPA alignment with international safety benchmarks accelerates domestic manufacturer certification timelines and reduces export friction for Shenzhen-based producers. The Yangtze River Delta manufacturing corridor hosts the densest concentration of flash lamp assembly and sensor algorithm development.
Germany
MDR compliance documentation and extended notified body audit backlogs delay CE mark renewals and create temporary market access gaps. The country's technical standards heritage elevates consumer trust in validated brands with established quality management infrastructure. Bavaria's precision engineering clusters supply thermal management components to handheld device assemblers.
Japan
Urban millennial adoption in space-constrained Tokyo apartments accelerates demand for cordless lithium-ion configurations. METI guidelines on rechargeable battery safety shape product design specifications for export-oriented manufacturers. Osaka-based consumer electronics heritage influences miniaturization engineering for premium handheld form factors.
Brazil
ANVISA jurisdiction over personal care devices mandates local testing protocols that favor established importers with regulatory relationships. Dermatology networks in São Paulo drive professional-grade replacement cycles as dual-mode wavelength systems displace single-spectrum predecessors. Medium-skin phototype demand from Brazilian and Mexican consumer markets drives adaptive calibration system development.
Global Consumer Use IPL Hair Removal Devices Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and sensor algorithm sophistication. The vendor base stratifies into three tiers: healthcare heritage brands with FDA 510(k) portfolios, direct-to-consumer specialists leveraging Chinese e-commerce infrastructure, and compact engineering houses serving space-constrained urban households. Strategic moves concentrate on M&A for regulatory dossier accumulation and vertical integration into flash lamp supply chains.
Among healthcare heritage conglomerates, Philips and Panasonic exemplify premium-tier positioning through established medical device certification pathways. Within the direct-to-consumer vector, Ulike anchors Chinese e-commerce penetration with aggressive pricing architectures. Compact engineering specialization sits with SmoothSkin (Cyden), which occupies a position in handheld miniaturization for European and North American bathroom-counter convenience.
| Leading Market Players |
|---|
| Silk'n |
| SmoothSkin (Cyden) |
| Philips |
| CosBeauty |
| Iluminage Beauty |
| Panasonic |
| Ya-Man |
| Ulike |
| Braun |
| Others |
Supply Flow & Price Mechanics
Live-stream commerce procurement preferences in China are compressing retail markups and forcing Shenzhen manufacturers to absorb flash lamp cost volatility into thinner margins, while European MDR compliance investments elevate certified product premiums against uncertified alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared heritage brands from GB-standard domestic challengers and unbranded alkaline-powered entry units. Price differentiation rests on certification tier and after-sales service bundling, with cordless lithium-ion configurations commanding premiums against plug-in alternatives. Cost compression in the economy tier is intensifying because flash lamp cartridge commoditization erodes hardware attach rates. Chinese e-commerce buyers exhibit highest price sensitivity, while Middle Eastern spa operators prioritize SFDA registration over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with xenon flash tube production concentrated in China, Japan, and Germany. Optical filter glass draws from specialized German and Japanese suppliers, while lithium-ion cells feed from South Korean and Chinese battery manufacturers. Tariff exposure on semiconductor components for skin-tone sensors complicates cost forecasting for algorithm-enabled devices. Distribution runs through direct-to-consumer platforms in China and specialized medical device distributors in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where algorithmic skin-tone safety and cordless lithium-ion miniaturization are displacing basic specifications as the baseline purchase criterion.
For Market Incumbents: Cement regulatory dossier depth as the primary defensive moat by accelerating MDR post-market surveillance registry investments and deepening backward integration into flash lamp supply chains. Diode laser substitution from professional clinics threatens high-value customer retention, requiring algorithmic personalization R&D to blur efficacy boundaries. For New Entrants and Emerging Players: SFDA streamlining in Saudi Arabia opens a window for Gulf Cooperation Council entry before incumbent certification completion. Target dermatology clinic replacement cycles in São Paulo and Seoul with dual-mode wavelength systems, leveraging influencer-calibrated education campaigns on Douyin and Taobao for customer acquisition. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm-specialist component suppliers holding patent positions around melanin-responsive sensor calibration. Five-to-ten-year viability favors manufacturers with captive NMPA relationships and established CE marking infrastructure. Watch FDA 510(k) clearance velocity as the inflection indicator for competitive access dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | German notified body audit backlogs create temporary market access gaps for prepared filers. |
| Flash Cartridge Subscription Launch | Recurring revenue models lock brand loyalty through connected device ecosystems. |
| Dual-Mode Wavelength Integration | Multi-spectrum handheld units capture urban millennial adoption in Seoul and São Paulo. |
| SFDA Registration Completion | Saudi regulatory streamlining opens Gulf Cooperation Council markets with limited domestic manufacturing. |
| AI Skin Assessment Companion Development | Smartphone-integrated melanin analysis reduces user error liability and automates energy calibration. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads at notified bodies, biomedical engineers at handheld device assemblers, procurement managers at Middle Eastern spa chains, and channel heads at Chinese live-stream commerce platforms with secondary validation against FDA 510(k) filings, NMPA registration databases, MDR clinical evidence requirements, and customs trade records. Bottom-up shipment estimates and top-down category spend analysis were triangulated for convergence.
Segment-weighting across device type, power configuration, skin-tone compatibility tier, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from fitted growth curves against historical adoption patterns and projected certification timeline impacts. Forecast inputs incorporated lithium-ion energy density improvement trajectories and flash lamp degradation replacement cycle economics.
Revisions become necessary when FDA 510(k) timeline extensions, MDR audit backlogs, or flash lamp supply disruptions materialize beyond modeled assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
Global Aligner Sheet Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
Cotton Buds Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
Women Face Razor Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Latin America Hand Soap Market
Personal Grooming Products
Smart Bathroom Scale Market