
 Global Organic Personal Care and Cosmetic Products Market | 2026-2036
Global Organic Personal Care and Cosmetic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Personal Care and Cosmetic Products Market Outlook
ECOCERT and COSMOS certification tiers is redrawing competitive boundaries among premium organic formulators. L'Oréal S.A. leverages its botanical research network across France and Brazil to secure rare plant extract supply chains. Natura & Co anchors its market position through The Body Shop's ethically sourced ingredient commitments. Unilever PLC extends its organic portfolio via specialty channels that reward transparent labeling.
Organic personal care and cosmetic products denote formulations containing minimum certified organic content, typically requiring plant-derived ingredients grown without synthetic pesticides or genetically modified organisms, with preservation achieved through approved natural compounds or cold-processing methods. These products serve consumers seeking reduced chemical exposure and environmental traceability in daily hygiene and beauty routines. Skincare commands the largest revenue pool as facial serums and anti-aging treatments attract repeat premium purchases, while haircare represents the fastest-expanding category as sulfate-free and botanical shampoo adoption spreads through professional salon recommendations. Online Retail channels capture disproportionate growth velocity through direct-to-consumer subscription models that bypass traditional beauty counter markups.
The USDA National Organic Program, EU REACH, and COSMOS-standard governance collectively determine which ingredient suppliers qualify for certified product claims across North American and European shelf space. ECHA's evolving restricted substance lists force reformulation cycles that favor vertically integrated botanical extractors over commodity chemical traders. Stakeholders must monitor certification body harmonization efforts between COSMOS and NSF/ANSI 305 standards, as divergence in organic content thresholds threatens to fragment export compliance costs for multi-region brands.
Market Dynamics
Certification body fragmentation between COSMOS and NSF/ANSI 305 standards is forcing dual-track compliance investments from multinational formulators seeking cross-border shelf placement. This structural friction elevates costs for mid-tier brands while consolidating advantage among vertically integrated botanical extractors with captive certification expertise.
Growth Catalysts
- EU REACH chemical restrictions:ECHA's expanding restricted substance lists accelerate reformulation demand toward plant-derived alternatives, expanding addressable market for certified organic suppliers across European retail networks.
- Professional salon channel endorsement:Sulfate-free and botanical haircare recommendations from licensed stylists drive trial-to-repeat conversion rates exceeding conventional mass-market advertising efficiency.
- South Korean beauty retail expansion:Certified organic shelf space growth in Seoul's premium department stores creates new premium positioning opportunities for ECOCERT-compliant skincare lines.
Market Restraints
- Organic raw material cost volatility:Climate-sensitive botanical harvests in Madagascar and Morocco concentrate supply risk, with cold-pressed argan and shea butter prices subject to drought-induced harvest compression.
- Preservation efficacy limitations:Approved natural compounds deliver shorter shelf stability versus synthetic alternatives, constraining distribution radius and inventory turnover economics for mass-market retail placement.
- Certification timeline friction:COSMOS and ECOCERT audit cycles extending 12-18 months delay product launch velocity for reformulated lines targeting seasonal beauty calendar windows.
Strategic Opportunities
- Indian urban premium channel underpenetration:Mumbai and Bangalore's specialty beauty retailers show accelerating shelf space allocation for imported organic certifications, with domestic Ayurveda-organic hybrid positioning largely unoccupied by global brands.
- Direct-to-consumer subscription models:Replenishment-based skincare routines bypass traditional beauty counter markups while capturing recurring revenue streams and first-party consumption data.
- USDA National Organic Program cosmetic expansion:Proposed rulemaking to clarify personal care organic content thresholds would reduce state-level label fragmentation and streamline multi-channel distribution compliance.
Industry Challenges
- Formulation chemist scarcity:Cross-functional expertise spanning cosmetic chemistry, organic certification protocols, and natural preservation systems concentrates among a limited pool of specialists, inflating compensation premiums and team build-out timelines.
- Traceability system integration:Blockchain and farm-to-face verification platforms require capital-intensive ERP reconfiguration for legacy brands with fragmented supplier networks across multiple continents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Personal Care and Cosmetic Products Market |
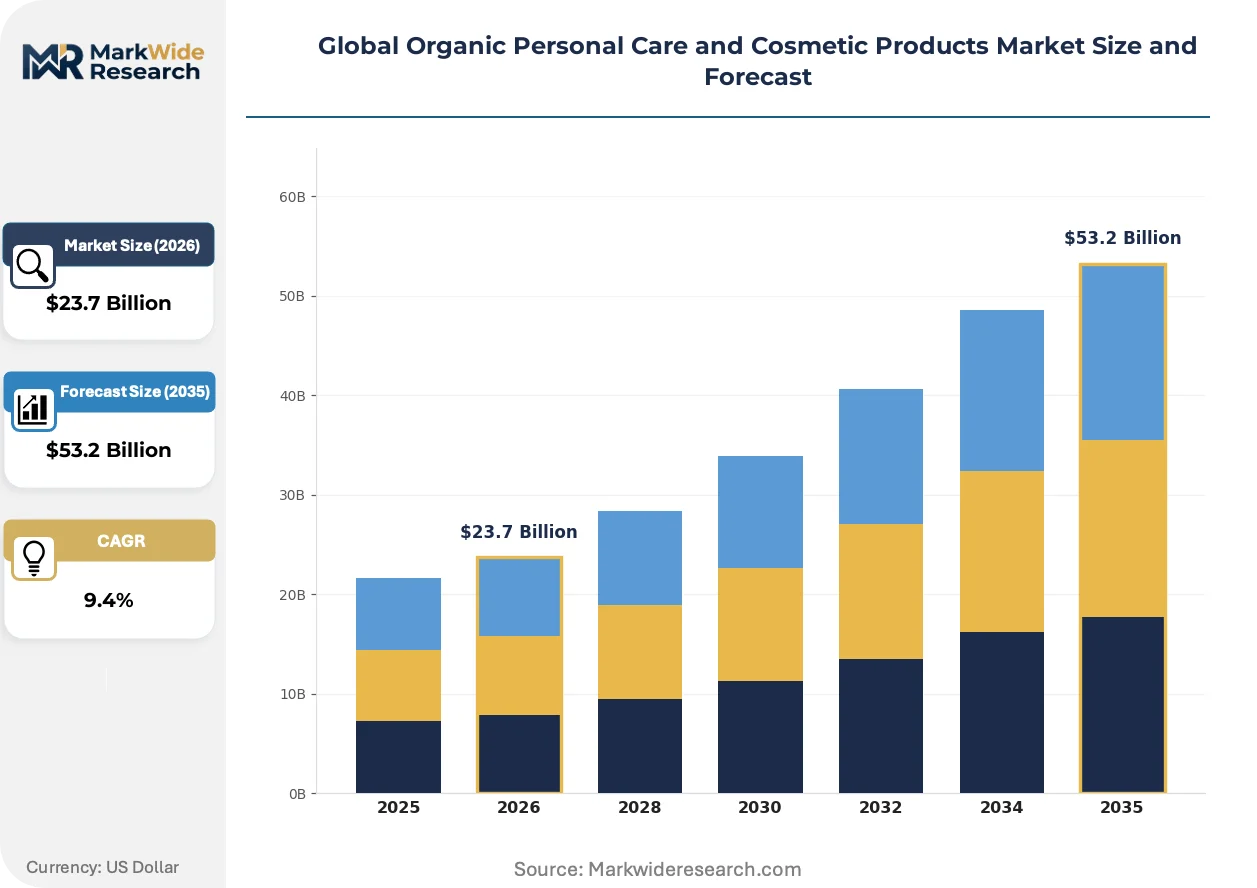
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Ingredient Type: Natural Extracts, Essential Oils, Plant-Based Waxes, Organic Colors Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Beauty Salons End User: Adults, Teenagers, Children, Professionals |
| Companies Covered | L'Oréal S.A., The Procter & Gamble Company, Unilever PLC, The Estée Lauder Companies Inc., Beiersdorf AG, Natura & Co, Yves Rocher, L'Occitane en Provence, Burt's Bees Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Personal Care and Cosmetic Products Market Strategic Shifts
Biotechnology-derived ingredients and precision fermentation are redrawing ingredient sourcing economics while regulatory harmonization efforts and channel disintermediation compress traditional value chain capture points.
Cold-processed emulsion technology is supplanting heat-dependent manufacturing for sensitive botanical actives. Premium facial serum formulators in Germany and France adopt these methods to preserve antioxidant potency in vitamin C and polyphenol-rich extracts. The structural consequence is compressing minimum viable batch sizes and enabling micro-brand entry with limited capital equipment.
ECHA's SCIP database requirements under the Waste Framework Directive mandate supply chain disclosure of substances of very high concern. Cosmetic manufacturers must now map ingredient origins through tier-three suppliers, accelerating consolidation toward vertically integrated botanical extractors with documented chain-of-custody systems. German and French formulators face the steepest compliance ramps given their export volume concentration.
Ingredient-conscious consumers now verify certification claims through third-party apps before purchase, bypassing brand-controlled messaging. This behavior shift compresses marketing effectiveness for aspirational organic positioning without independent validation. South Korean and US metropolitan markets show the highest app-assisted verification rates, forcing transparency investments ahead of regulatory mandates.
Global Organic Personal Care and Cosmetic Products Market Segmentation
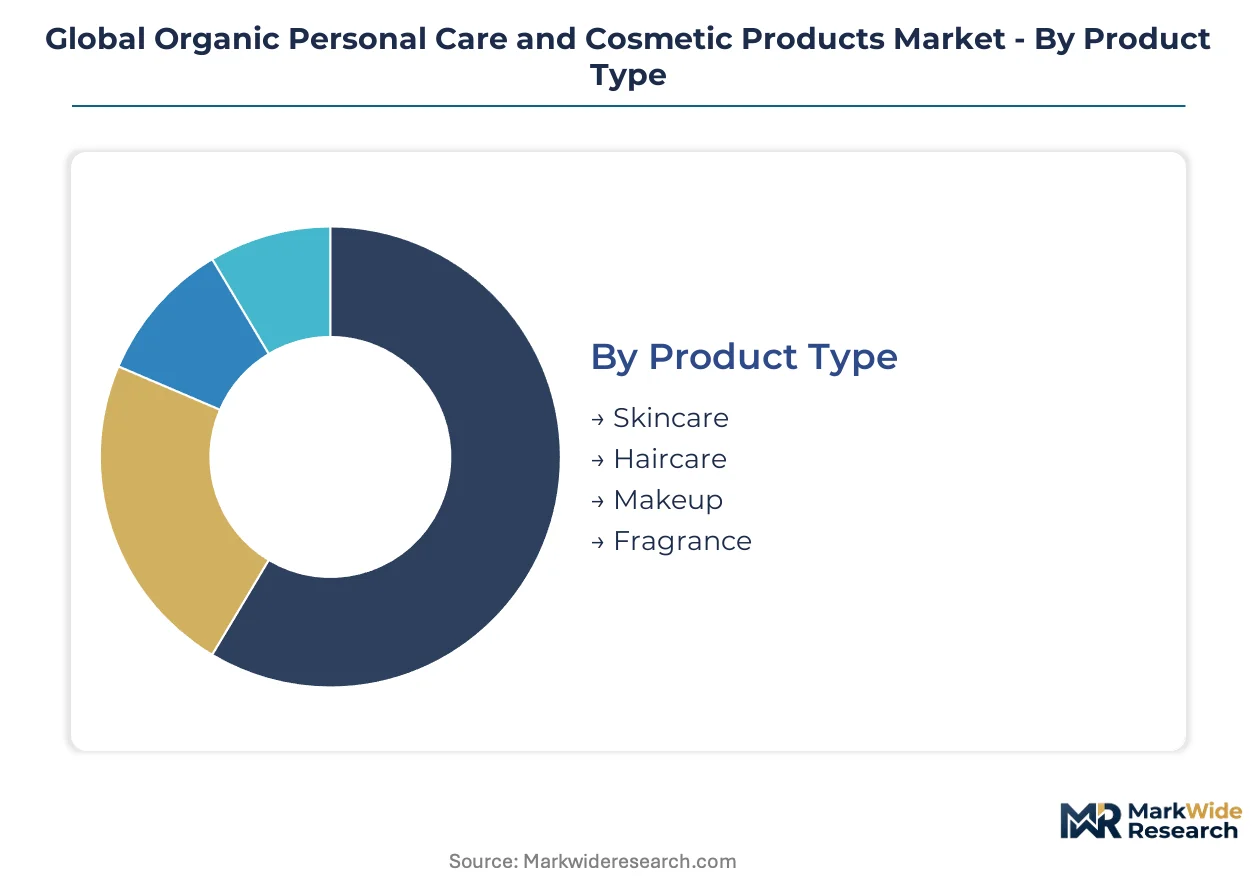
Certification requirements and distribution economics vary sharply across product formulations and buyer demographics. Segment-specific sourcing protocols and channel economics determine margin capture and compliance burden for formulators targeting cross-border placement.
Product Type:
Skincare and haircare lines concentrate production in France and Germany for EU shelf placement, while makeup and fragrance segments rely more heavily on export-led manufacturing from South Korea and the United States.
- Skincare:Facial serums and anti-aging treatments incorporate cold-processed emulsions to preserve polyphenol potency in vitamin C and botanical extracts. Demand clusters in German and South Korean premium department stores where ECOCERT-compliant lines command repeat purchase loyalty.
- Haircare:Sulfate-free and botanical shampoo formulations accelerate through professional salon endorsement channels. Licensed stylists in Seoul and New York drive trial-to-repeat conversion rates exceeding mass-market advertising efficiency.
- Makeup:Mineral-based foundations and organic color cosmetics face shorter shelf stability constraints from approved natural preservation systems.
- Fragrance:Alcohol-free and essential oil-based scents require specialized cold-processing to prevent volatile compound degradation during manufacturing.
Skincare holds the largest share; momentum sits with haircare as salon channel penetration deepens.
Ingredient Type:
Cost tier stratification separates commodity botanicals from precision-extracted actives, with extraction method determining certification eligibility and price positioning.
- Natural Extracts:Cold-pressed argan from Morocco and shea butter from Madagascar supply foundational moisturizing bases. Climate-sensitive harvests concentrate supply risk in drought-prone growing regions.
- Essential Oils:Lavender from Provence and tea tree from Australia provide fragrance and antimicrobial properties. Steam distillation and CO2 extraction methods preserve organic certification integrity.
- Plant-Based Waxes:Candelilla and carnauba waxes replace petroleum-derived emollients in lip balms and solid formulations.
- Organic Colors:Mineral pigments and plant-derived dyes face restricted palette breadth versus synthetic alternatives, constraining cosmetic shade range.
Natural extracts dominate volume; essential oils are climbing the fastest on professional formulation demand.
Distribution Channel:
Channel selection determines certification documentation requirements, with direct-to-consumer models reducing shelf-space compliance burden versus retail placement.
- Online Retail:Subscription-based skincare routines bypass traditional beauty counter markups while capturing first-party consumption data. Direct-to-consumer models in the United States and South Korea show disproportionate growth velocity.
- Specialty Stores:Curated organic beauty retailers in Mumbai and Bangalore allocate expanding shelf space to imported ECOCERT and COSMOS-certified lines.
- Supermarkets:Mass-market placement requires extended shelf stability that natural preservation systems struggle to deliver.
- Beauty Salons:Licensed professional channels provide credible endorsement for sulfate-free and botanical haircare conversion.
Online retail captures the steepest expansion trajectory; specialty stores anchor premium positioning.
End User:
Demographic targeting shapes formulation complexity and price tier, with professional segments demanding clinical-grade organic certification.
- Adults:Anti-aging and daily skincare routines drive recurring revenue through subscription replenishment models. German and French formulators target this segment with cold-processed serum lines.
- Teenagers:Acne-focused botanical treatments gain traction through social media verification behaviors and third-party certification app usage.
- Children:Hypoallergenic and fragrance-minimal formulations face stringent safety testing requirements under EU REACH and FDA cosmetic guidance.
- Professionals:Makeup artists and salon technicians require performance-grade organic products that match synthetic alternatives in coverage and durability.
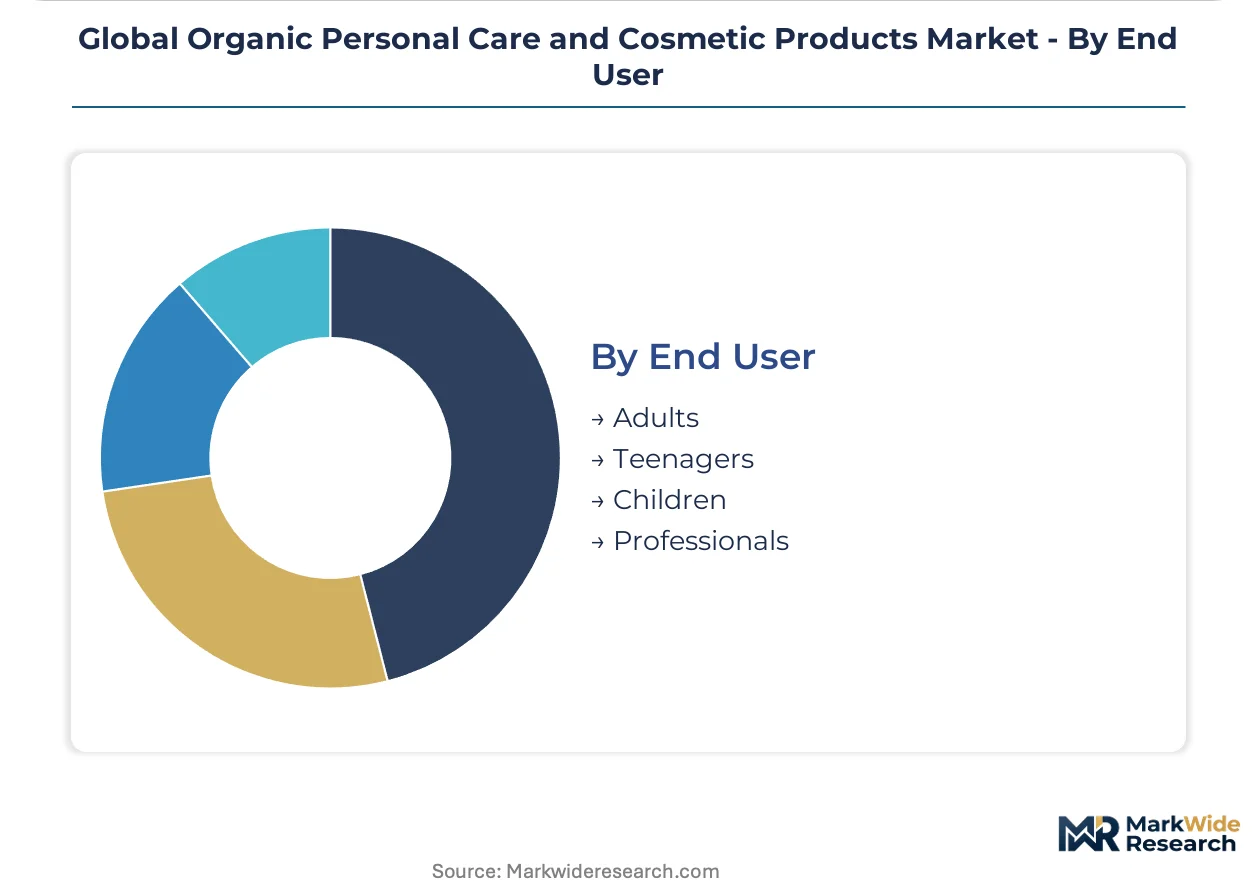
Adults command the largest revenue pool; professionals represent the fastest-growing segment on B2B procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Botanical extraction facilities cluster in France and Germany where ECOCERT and COSMOS certification infrastructure anchors European supply chains. Cold-processing equipment manufacturers in these markets serve formulators across multiple continents. Demand diffusion now outpaces supply expansion in Seoul, Mumbai, and São Paulo specialty retail channels.
Germany
ECOCERT-compliant skincare lines dominate premium department store shelves in Berlin and Munich. The country's Federal Office of Consumer Protection and Food Safety enforces strict organic labeling requirements under EU REACH frameworks. Formulation clusters in Hamburg and Düsseldorf specialize in cold-processed emulsion technology for sensitive botanical actives.
United States
Direct-to-consumer subscription models in New York and Los Angeles bypass traditional beauty counter economics. The USDA National Organic Program governs cosmetic organic content claims through proposed rulemaking that would clarify personal care thresholds. Manufacturing concentrates in California and New Jersey where natural preservation system R&D facilities serve boutique and mass-market brands simultaneously.
South Korea
Seoul's premium department stores allocate expanding shelf space to imported ECOCERT-certified skincare lines. The Ministry of Food and Drug Safety regulates cosmetic safety while K-beauty export protocols facilitate cross-border organic certification recognition. Busan-based logistics hubs distribute botanical ingredients to domestic formulators and re-export markets across Asia-Pacific.
France
Provence lavender and botanical extract supply chains serve Paris-based luxury formulators. ANSM oversees cosmetic product safety while the country's EU Green Deal implementation accelerates chemical restriction timelines. Grasse fragrance houses and Lyon cosmetic chemistry clusters develop alcohol-free essential oil preservation systems for organic fragrance lines.
India
Mumbai and Bangalore specialty retailers show accelerating shelf space allocation for imported organic certifications. The Food Safety and Standards Authority of India regulates cosmetic safety standards while Ayurveda-organic hybrid positioning remains largely unoccupied by global brands. Domestic formulators in Gujarat and Maharashtra blend traditional botanical knowledge with ECOCERT compliance protocols for export markets.
Global Organic Personal Care and Cosmetic Products Market Competitive Environment
Concentration sits with diversified beauty conglomerates that leverage botanical research networks across multiple continents. Mid-tier certified organic specialists face margin compression from dual-track COSMOS and NSF/ANSI 305 compliance investments. Three archetypes dominate: vertically integrated extractors with captive certification expertise, direct-to-consumer micro-brands exploiting cold-processing batch flexibility, and legacy mass-market players extending organic lines through specialty channel acquisitions. Competitive moves center on supply chain backward integration into rare plant sourcing and direct-to-consumer subscription infrastructure buildout.
Within the diversified conglomerate tier, L'Oréal S.A. exemplifies botanical research network deployment across France and Brazil. The Estée Lauder Companies Inc. occupies a position emphasizing premium positioning through department store channel relationships. Natura & Co represents the vertically integrated extractor archetype with ethically sourced ingredient commitments through The Body Shop's supply chain infrastructure.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Procter & Gamble Company |
| Unilever PLC |
| The Estée Lauder Companies Inc. |
| Beiersdorf AG |
| Natura & Co |
| Yves Rocher |
| L'Occitane en Provence |
| Burt's Bees Inc. |
| Others |
Value Chain & Pricing Dynamics
Cold-processed emulsion technology replacing heat-dependent manufacturing simultaneously redistributes production capacity toward France and Germany while compressing minimum viable batch economics for premium skincare formulators. This substitution dynamic concentrates pricing power among equipment-owning botanical extractors and fragments margin capture for contract manufacturers lacking captive cold-processing infrastructure.
Pricing Analysis
EU REACH chemical restrictions dictate the pricing tier structure across European retail networks, separating ECOCERT-certified premium lines from conventional natural-positioned alternatives. Price differentiation hinges on certification grade and volume scale, with COSMOS-organic tiers commanding shelf-space premiums over NSF/ANSI 305 equivalents. Cost compression in mid-tier segments is intensifying because dual-track compliance investments inflate fixed costs without corresponding brand premium capture. Mass-market buyers through supermarket channels exhibit highest price sensitivity, while professional salon procurement shows lowest elasticity due to performance-grade formulation requirements.
Supply Chain Analysis
Strategic stockpiling of climate-sensitive botanicals dominates inventory strategy over just-in-time approaches, reflecting harvest volatility in Madagascar and Morocco. Raw material sourcing draws from cold-pressed argan suppliers in Morocco, shea butter cooperatives in Madagascar, and lavender distilleries in Provence. Single-source vulnerability concentrates in drought-prone growing regions where rainfall variation compresses annual harvest yields. Distribution runs through Busan-based logistics hubs for Asia-Pacific re-export and Hamburg-Düsseldorf formulation clusters for EU shelf placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a certification-investment cycle as EU Green Deal implementation and REACH expansion synchronize regulatory timelines, creating conditions for margin recovery among compliant formulators.
For Market Incumbents: Fortify supply chain control through backward integration into Moroccan argan and Madagascar shea butter cooperatives before climate volatility intensifies procurement cost swings. Deepen captive certification expertise across COSMOS and NSF/ANSI 305 protocols to compress dual-track compliance overhead relative to mid-tier competitors lacking scale economies. For New Entrants and Emerging Players: Anchor in Mumbai and Bangalore specialty retail channels where Ayurveda-organic hybrid positioning remains largely unoccupied by established global brands. Exploit cold-processing batch flexibility to serve professional makeup artist and salon technician segments demanding performance-grade organic alternatives without legacy mass-market shelf stability constraints. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer subscription platforms possessing first-party consumption data infrastructure but lacking backward-integrated botanical supply chains. Long-term viability over the next decade favors targets combining captive rare plant sourcing with documented ECOCERT chain-of-custody systems. Monitor ECHA restricted substance list expansion velocity as the critical inflection signal for reformulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Botanical Sourcing | Captive supply of Moroccan argan and Madagascar shea butter insulates margin from climate-induced harvest compression. |
| Direct-to-Consumer Subscription Infrastructure | First-party data capture from Seoul and Los Angeles replenishment models bypasses traditional beauty counter economics. |
| Dual Certification Protocol Harmonization | Unified COSMOS-NSF compliance systems reduce audit cycle friction and accelerate seasonal product launch velocity. |
| Cold-Processing Capacity Expansion | German and French equipment investments preserve polyphenol potency in vitamin C formulations for premium serum lines. |
| Blockchain Traceability Platform Deployment | Farm-to-face verification satisfies South Korean and US metropolitan consumer app-assisted certification verification behavior. |
Study Parameters
A standing panel of formulation chemists, ECOCERT audit specialists, specialty retail category buyers, and professional salon procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA restricted substance database updates, EU Green Deal implementation timelines, USDA National Organic Program rulemaking dockets, and customs records of botanical ingredient trade flows. Bottom-up segment sizing triangulated against top-down category spend estimates from premium department store channel data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product type, ingredient extraction method, distribution channel format, and end-user demographic cohort. CAGRs were derived from growth rate convergence analysis applied to certification penetration curves and channel shift dynamics. Forecast inputs incorporated professional salon endorsement conversion rates and direct-to-consumer subscription retention patterns.
Decision-makers should treat outputs as directional under stable EU REACH implementation and climate volatility assumptions; material deviation would warrant model refresh. Forecasts reflect documented base conditions including certification body harmonization progress and botanical harvest yield trends. Revision becomes warranted when ECHA restricted substance expansion velocity or drought frequency in key growing regions crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
Portable Atomizer Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
Nail Salon Market
Beauty & Personal Care
Delivery Systems in Personal Care Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Cosmetics and Personal Care Products Direct Selling Market
Beauty & Personal Care
Refillable Deodorants Market
Beauty & Personal Care
Stretch Mark Removal Products Market
Beauty & Personal Care
Organic Beauty and Personal Care Ingredients Market
Beauty & Personal Care
Spas and Beauty Salons Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
Luxury Personal Care and Cosmetics Market
Beauty & Personal Care
Hand Soap in Retail Market