
 South America Bath and Shower Products Market | 2026-2036
South America Bath and Shower Products Market Size, Share, and Industry Trends Forecast 2026-2036
South America Bath and Shower Products Market Analytics
Aftermarket service revenue from refill and subscription formats is tilting margin pools away from single-use packaging. Unilever leverages its direct-to-consumer platform to capture recurring revenue streams in Brazil and Argentina. Natura & Co anchors its position through botanical supply chain integration across Amazonian sourcing cooperatives. Procter & Gamble competes via concentrated formula innovations that reduce per-use cost for price-sensitive Colombian households.
Bath and shower products encompass surfactant-based cleansers, emollient-enriched washes, and solid-format soaps formulated with pH-balanced systems for epidermal compatibility. Manufacturing employs cold-process saponification or hot-melt compounding with rheology modifiers to achieve viscosity targets between 500 and 5000 cP for pump dispensing. Shower gels dominate value contribution due to higher per-liter pricing and fragrance premiumization, while bar soaps retain volume leadership in rural distribution corridors where unit economics favor low-cost formats. Online retail represents the fastest-expanding channel as logistics networks penetrate secondary cities, though supermarkets still control shelf-space negotiations and promotional visibility.
ANVISA governs cosmetic safety assessments and ingredient prohibitions across Brazil, while Argentina's national pharmaceutical regulator enforces parallel labeling standards for imported personal care goods. REACH-aligned frameworks in Chile and Colombia are tightening preservative restrictions, compelling reformulation investments among multinational suppliers. Stakeholders must monitor regulatory divergence between Mercosur harmonization proposals and national-level chemical registry requirements to anticipate compliance cost allocation across manufacturing footprints.
Market Dynamics
ANVISA's tightening cosmetic ingredient disclosure mandates are forcing wholesale reformulation transparency across Brazilian manufacturing footprints, compressing legacy opaque supply chains while elevating compliance costs as the central competitive differentiator.
Growth Catalysts
- Urban millennial premiumization:São Paulo and Rio de Janeiro metropolitan clusters demonstrate concentrated demand for emollient-enriched washes and fragrance-premiumized shower gels, pulling per-liter pricing upward.
- REACH-aligned frameworks:Chile and Colombia are tightening preservative restrictions, compelling multinational suppliers to invest in reformulation capabilities that transfer to Mercosur markets.
- Logistics network penetration:Secondary city distribution infrastructure expansion enables online retail channel growth for refill and subscription formats.
Market Restraints
- Surfactant input volatility:Palm-derived and petrochemical feedstock price swings compress margin stability for cold-process saponification operations.
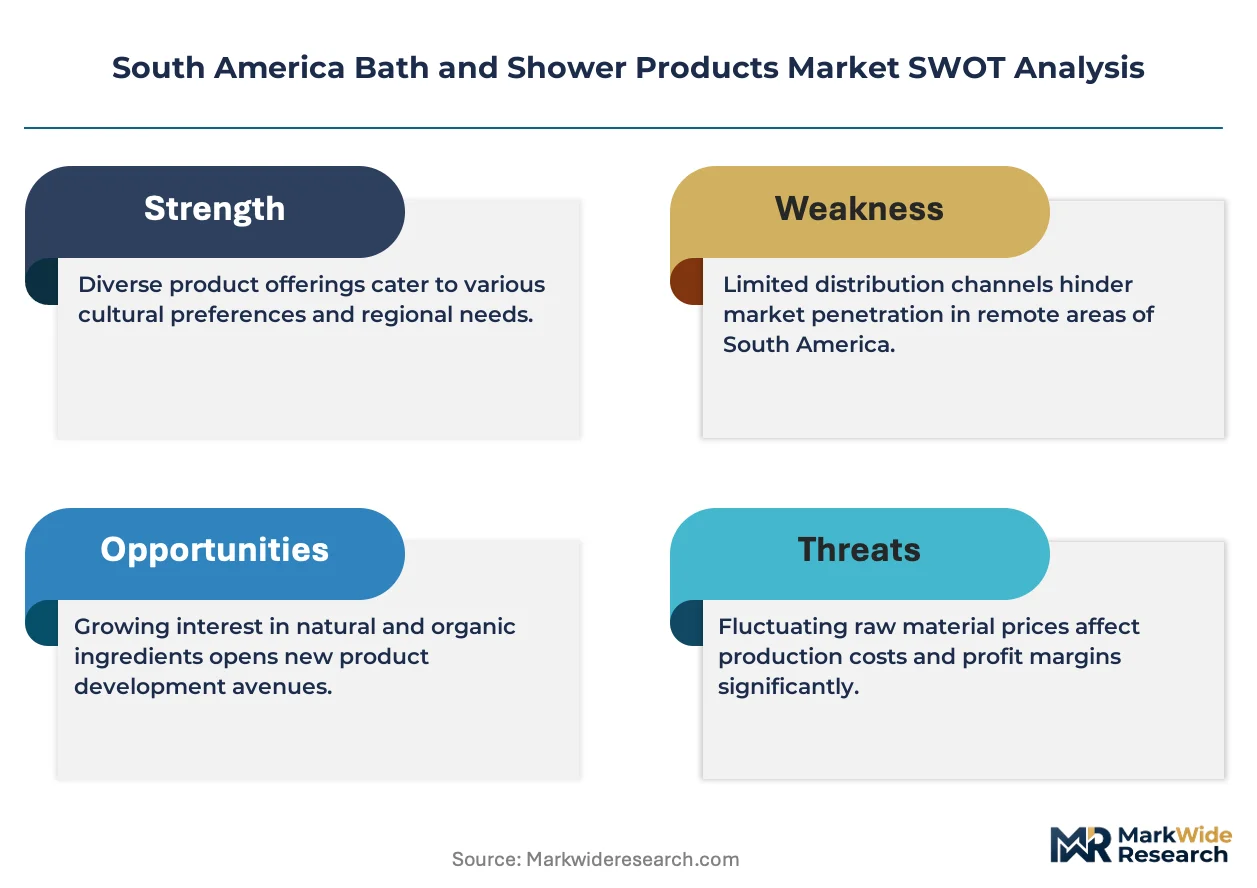
- Amazonian botanical supply concentration:Natura & Co's cooperative sourcing integration limits independent access to certified sustainable raw material streams.
- Rural unit economics:Bar soap volume leadership in non-metropolitan corridors constrains value-per-unit expansion despite stable shipment volumes.
Strategic Opportunities
- Argentine direct-to-consumer platforms:Subscription model penetration remains underdeveloped relative to Brazil, creating whitespace for recurring revenue capture.
- Colombian concentrated formula adoption:Price-sensitive households demonstrate receptivity to reduced per-use cost structures through compact dosing innovations.
- Mercosur harmonization tailwinds:Proposed cross-border chemical registry alignment would streamline multi-country compliance overhead for regional suppliers.
Industry Challenges
- Regulatory divergence monitoring:Stakeholders must track gaps between national-level chemical registries and Mercosur proposals, fragmenting compliance resource allocation.
- Cold-melt compounding capex:Rheology modifier integration for 500-5000 cP viscosity targets demands equipment upgrades at mid-scale manufacturing footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Bath and Shower Products Market |
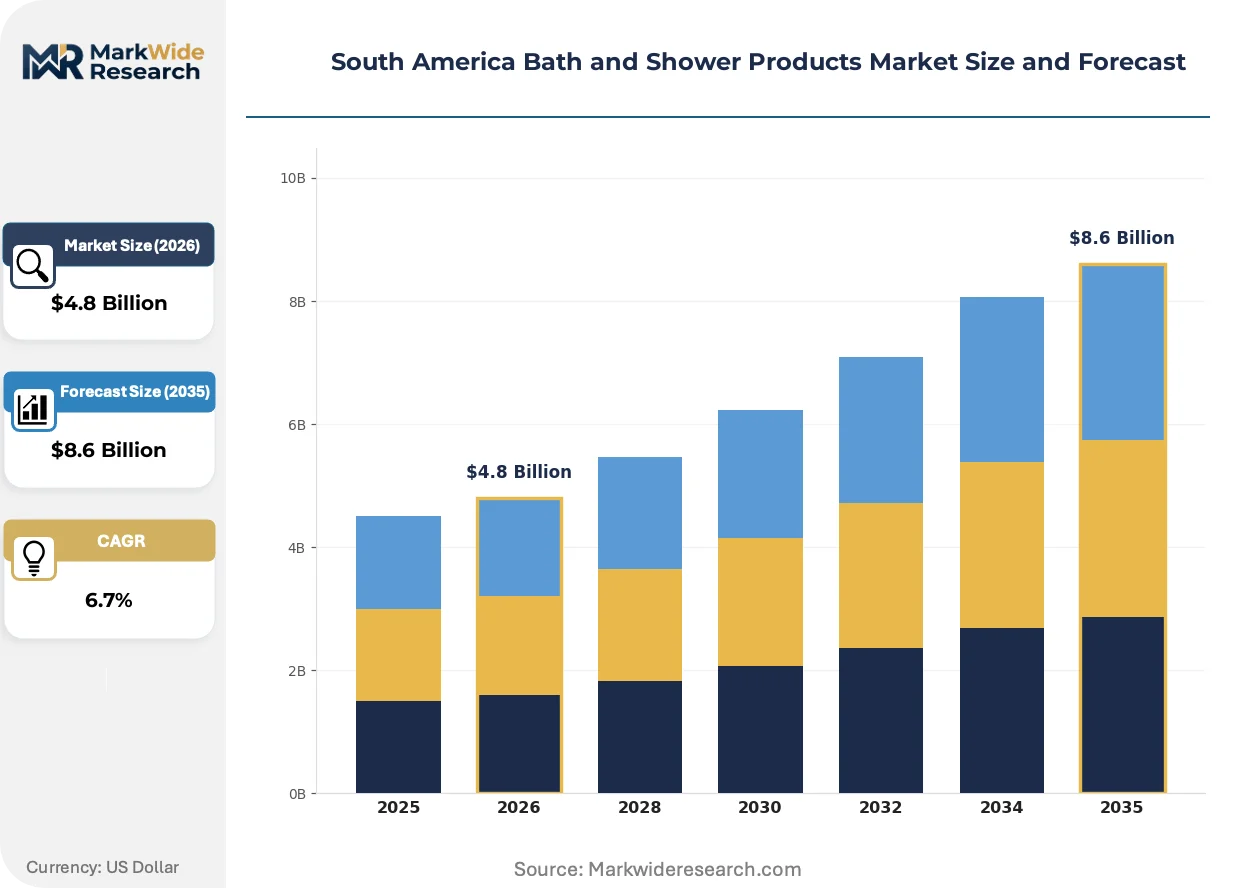
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shower Gels, Bath Oils, Bar Soaps, Shower Creams End User: Men, Women, Children, Elders Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores Packaging Type: Bottles, Tubes, Jars, Sachets |
| Companies Covered | Unilever, Procter & Gamble, Colgate-Palmolive Company, Beiersdorf AG, L’Oréal, Johnson & Johnson, Natura & Co, Henkel AG & Co. KGaA, L’Artisan Parfumeur S.A.R.L, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Bath and Shower Products Market Evolving Landscape
Digital infrastructure is compressing traditional channel hierarchies while regulatory chemistry restrictions and shifting procurement authority reshape competitive positioning across the South American bath and shower landscape.
Solid-format soap bars with embedded pH-balancing microencapsulation are virtualizing liquid-format dominance in urban sustainability-conscious segments. São Paulo-based millennials demonstrate accelerating adoption of waterless cleansing formats. This virtualization is compressing conventional surfactant volume requirements while elevating formulation complexity as the primary technical battleground.
ANVISA's expanded cosmetic safety assessment protocols now mandate pre-market notification for novel preservative systems. Brazilian manufacturers face extended timeline-to-shelf for imported active ingredients. Shower gel segments with extended shelf-life claims are responding by accelerating domestic stability testing infrastructure investment.
Supermarket shelf-space negotiation authority is fragmenting as online retail logistics achieve secondary city penetration. Traditional hypermarket chains in Colombia and Chile are ceding promotional visibility to direct-to-consumer platforms. This channel rotation is most visible in Argentina's metropolitan corridors where subscription refill models displace single-use packaging at point-of-purchase.
South America Bath and Shower Products Market Segmentation
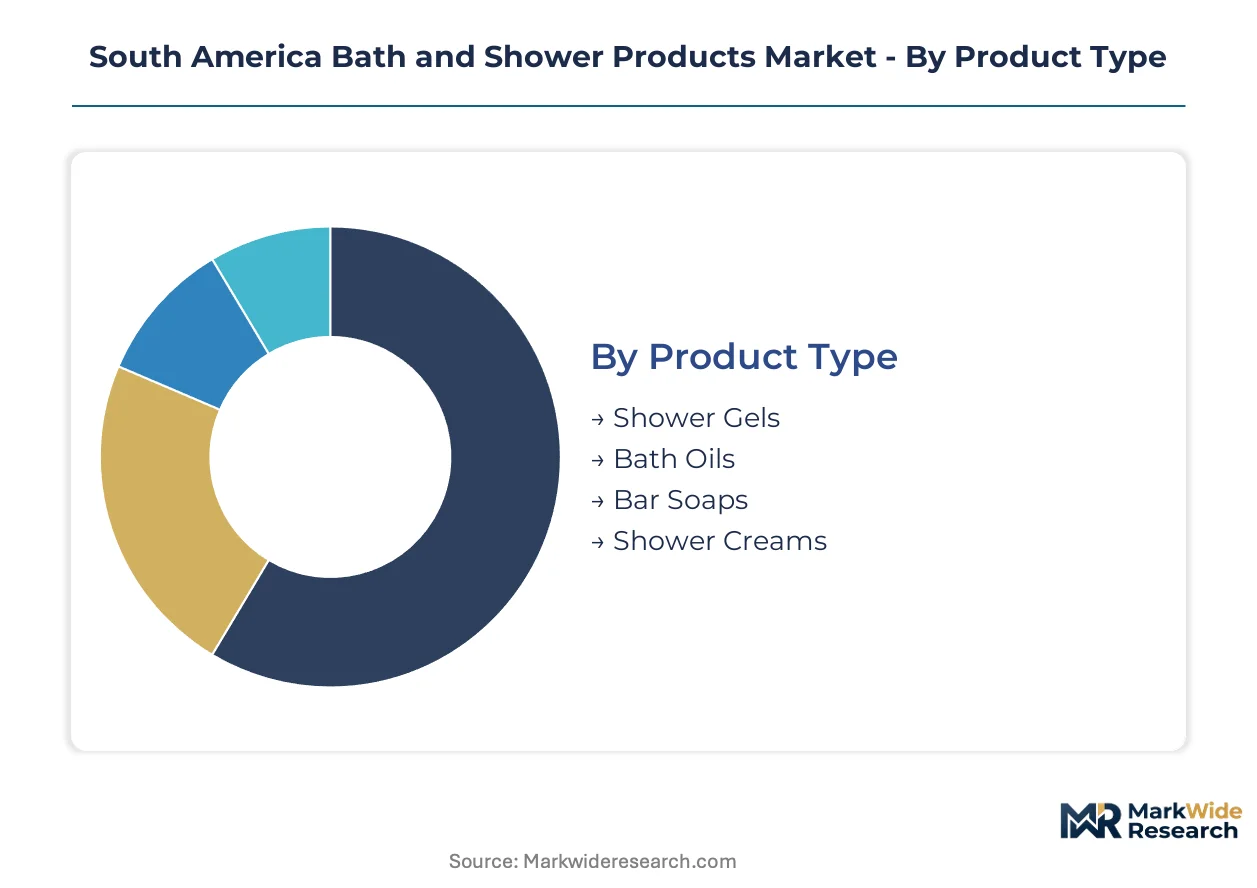
Bath and shower segmentation in South America reflects divergent cost sensitivities between metropolitan and rural corridors, with format choices directly tied to logistics infrastructure maturity and regulatory disclosure requirements. Understanding these splits enables targeted margin capture across Brazil's southeastern manufacturing clusters and Argentina's emerging direct-to-consumer channels.
Product Type:
Use-case spectrum spans from daily hygiene maintenance to therapeutic skin conditioning, with viscosity specifications and emollient loadings calibrated to water hardness variations across São Paulo, Rio de Janeiro, and Bogotá municipal supplies.
- Shower Gels:Surfactant-based formulations with 500-5000 cP viscosity targets enable pump dispensing and fragrance layering. São Paulo and Rio de Janeiro metropolitan clusters concentrate demand for emollient-enriched variants as urban millennials trade up from basic cleansing.
- Bar Soaps:Cold-process saponification yields solid formats with pH-balanced systems for epidermal compatibility. Rural distribution corridors across Brazil's interior and Colombia's Andean provinces favor these low-cost, shelf-stable formats despite compressed per-unit value.
- Bath Oils:Lipid-rich emollients targeting therapeutic and relaxation positioning in spa-adjacent retail channels.
- Shower Creams:Hybrid viscosity profiles bridging gel fluidity with lotion conditioning for dry-climate households in Chile's central valley.
Established volume favors Bar Soaps; emerging adoption favors Shower Gels.
End User:
Demographic targeting reflects distinct skin biology requirements and purchasing authority distribution within South American household structures.
- Women:Primary procurement decision-makers across Brazilian and Argentine households, driving premiumization in fragrance-complex shower gels and botanical-enriched formats. ANVISA's ingredient disclosure mandates particularly influence this segment's label scrutiny.
- Men:Growing addressable market as grooming routines expand beyond basic hygiene, with concentrated formula preferences emerging in Colombian price-sensitive segments.
- Children:Hypoallergenic formulation requirements with stringent preservative restrictions under REACH-aligned Chilean and Colombian frameworks.
- Elders:Skin-barrier-supporting emollient systems addressing age-related epidermal dehydration, concentrated in urban healthcare-adjacent retail.
Women dominate current value capture; men represent the steepest expansion trajectory.
Distribution Channel:
Channel hierarchy is compressing as logistics networks achieve secondary city penetration and subscription platforms displace traditional shelf-space negotiations.
- Online Retail:Fastest-climbing channel as Brazil and Argentina develop direct-to-consumer infrastructure for refill and subscription formats. São Paulo-based logistics hubs enable same-day delivery in metropolitan corridors.
- Supermarkets:Legacy channel controlling promotional visibility and price-point anchoring, though ceding share to digital platforms in Colombia and Chile.
- Pharmacies:Therapeutic and dermatologist-recommended product positioning, particularly for sensitive-skin segments under ANVISA oversight.
- Specialty Stores:Premium fragrance and botanical storytelling environments, concentrated in Rio de Janeiro and Buenos Aires upscale retail corridors.
Supermarkets retain volume leadership; online retail is gaining share fastest.
Packaging Type:
Format selection balances dispensing ergonomics, shelf stability, and sustainability positioning against unit economics constraints in multi-tier price environments.
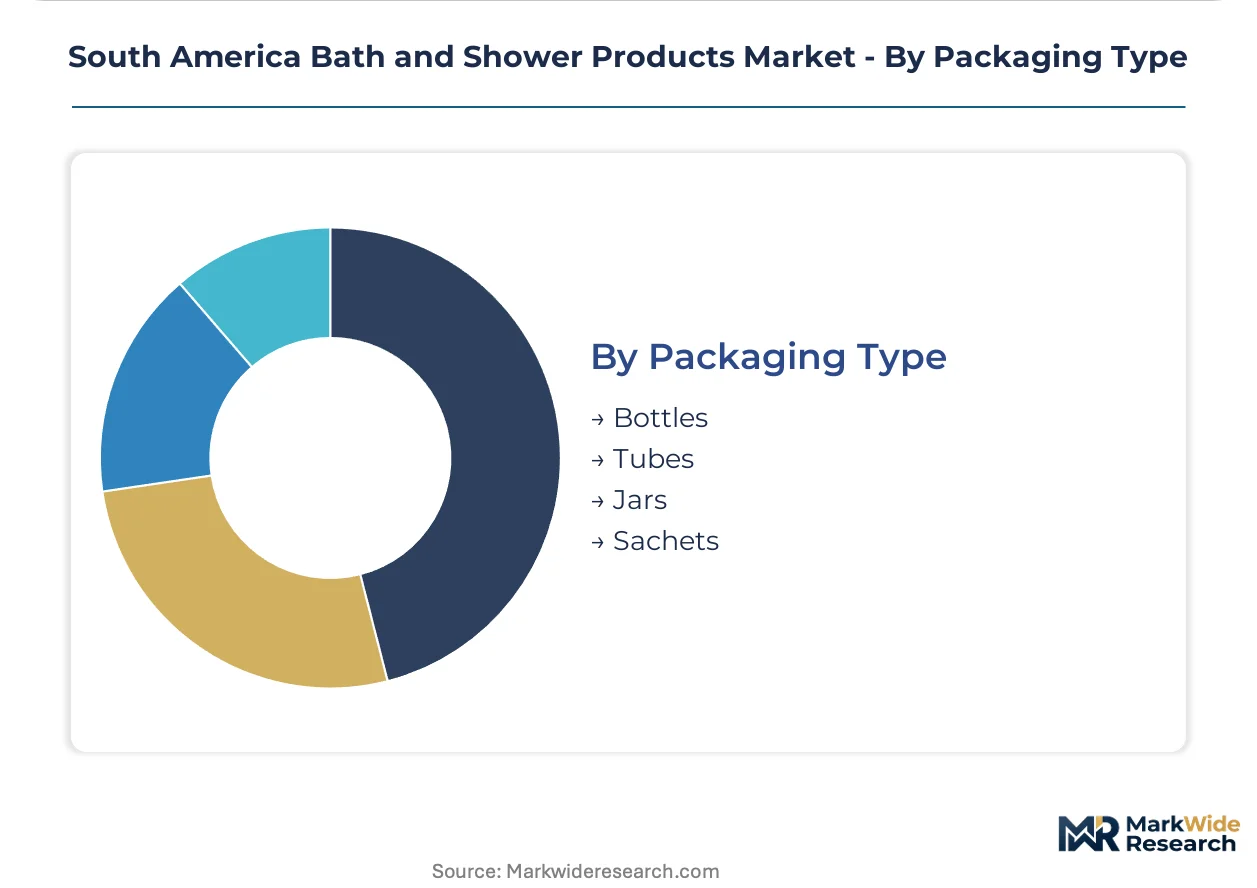
- Bottles:Standard pump and flip-cap configurations for family-size shower gels, dominating Brazilian southeastern manufacturing output.
- Tubes:Collapsible formats for travel and trial sizes, aligned with subscription sampling strategies in Argentine direct-to-consumer platforms.
- Jars:Wide-mouth containers for solid and semi-solid formats, prevalent in premium bath oil positioning.
- Sachets:Single-use sachets address rural affordability constraints and trial conversion in Colombia's price-sensitive interior provinces.
Bottles anchor manufacturing scale; sachets enable penetration into underserved rural corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes bath and shower products through premium emollient-enriched formats, while Colombia and Argentina favor concentrated formulas and rural bar soap distribution. This consumption-mix differential shapes manufacturing footprints and channel strategies across the continent.
Brazil
São Paulo and Rio de Janeiro metropolitan clusters drive demand for fragrance-premiumized shower gels with viscosity specifications calibrated to municipal water hardness. ANVISA governs cosmetic safety assessments and ingredient prohibitions, forcing wholesale reformulation transparency across southeastern manufacturing corridors. São Paulo anchors production scale with cold-process saponification facilities serving both domestic volume and Mercosur export positioning.
Argentina
Buenos Aires households demonstrate accelerating adoption of subscription refill models displacing single-use packaging at point-of-purchase. The national pharmaceutical regulator enforces parallel labeling standards for imported personal care goods, extending timeline-to-shelf for novel preservative systems. Metropolitan corridor logistics hubs enable same-day delivery infrastructure for direct-to-consumer platforms.
Colombia
Price-sensitive households in Bogotá and interior provinces concentrate demand for concentrated formulas reducing per-use cost structures. REACH-aligned frameworks are tightening preservative restrictions, compelling multinational suppliers to invest in domestic stability testing capabilities. Andean rural distribution corridors retain bar soap volume leadership where unit economics favor low-cost formats.
Chile
Dry-climate households in Santiago's central valley drive hybrid shower cream adoption bridging gel fluidity with lotion conditioning. REACH-aligned regulatory frameworks align with European chemical registry standards, streamlining compliance for EU-origin suppliers. Secondary city logistics penetration enables online retail channel growth for refill formats.
South America Bath and Shower Products Market Competitive Landscape
Capability concentration sits with botanical supply chain integrators; scale advantage sits with multinational formula innovators. The vendor base spans three tiers: global FMCG conglomerates with concentrated R&D pipelines, regional specialists with cooperative sourcing integration, and private-label manufacturers serving price-tier distribution. Strategic moves center on direct-to-consumer platform construction and cold-melt compounding equipment upgrades for viscosity-target compliance.
Within the multinational tier, Unilever and Procter & Gamble exemplify scale-driven positioning through recurring revenue capture and concentrated formula innovations respectively. Natura & Co anchors the regional specialist archetype through Amazonian cooperative sourcing integration. These three occupy positions spanning premium subscription models, price-sensitive household penetration, and certified sustainable raw material streams.
| Leading Market Players |
|---|
| Unilever |
| Procter & Gamble |
| Colgate-Palmolive Company |
| Beiersdorf AG |
| L’Oréal |
| Johnson & Johnson |
| Natura & Co |
| Henkel AG & Co. KGaA |
| L’Artisan Parfumeur S.A.R.L |
| Others |
Value Network & Pricing Analysis
Palm-derived surfactant concentration in Southeast Asian processing hubs directly determines margin pool distribution between cold-process saponification operators and finished goods brand owners across Brazilian manufacturing corridors.
Pricing Analysis
Long-term offtake contracts for Amazonian botanical extracts anchor premium-tier pricing stability, while spot-market surfactant procurement governs economy-format volatility. Three-tier pricing structure across premium, standard, and economy levels separates Natura & Co's certified cooperative-sourced lines from multinational mid-tier offerings and private-label bar soap penetration. Price differentiation rests on emollient loading intensity and ANVISA disclosure compliance certification. Cost compression in economy tiers is intensifying because petrochemical feedstock volatility transmits directly to cold-process operators. Colombian interior households demonstrate highest price sensitivity; São Paulo metropolitan millennials show lowest elasticity for fragrance-premiumized formats.
Supply Chain Analysis
Extended payment terms from Brazilian supermarket chains strain mid-scale manufacturer working capital, accelerating supply-chain finance facility adoption among cold-melt compounding operators. Manufacturing concentration spans Brazil's southeastern corridor, Argentina's Buenos Aires industrial belt, and Colombia's Bogotá processing zones. Raw material dependencies include palm kernel derivatives, Amazonian botanical extracts, and petrochemical-based rheology modifiers. Single-source vulnerability concentrates in certified sustainable cooperative supply streams controlled by integrated regional specialists. Distribution runs through supermarket shelf-space negotiations in legacy channels, with direct-to-consumer platforms capturing fastest-growing refill format volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription platform interoperability between Argentine logistics hubs and Brazilian manufacturing clusters marks the decisive ecosystem inflection, redefining customer acquisition economics away from shelf-space dependency.
For Market Incumbents: Pre-empt direct-to-consumer platform consolidation by acquiring Argentine subscription infrastructure before logistics network maturity closes entry windows. Anchor defensive positioning through backward integration into Amazonian cooperative sourcing networks, denying independent access to certified sustainable raw material streams. Cold-melt compounding equipment upgrades at São Paulo manufacturing footprints represent the critical capacity lever against viscosity-target compliance mandates. For New Entrants and Emerging Players: Mid-market concentrated formula segments in Colombia's interior provinces represent the most penetrable entry point, with price-sensitive household receptivity to per-use cost reduction exceeding metropolitan premiumization saturation. Argentine subscription refill whitespace offers secondary attack vector before incumbent platform lock-in solidifies. Go-to-market execution should prioritize sachet-to-tube conversion sampling through direct-to-consumer trial programs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed mid-scale Brazilian manufacturers lacking cold-melt compounding upgrade capital. Long-term viability favors platform-enabled recurring revenue models over transactional shelf-space dependency. Watch ANVISA-Mercosur regulatory harmonization progress as signal for compliance cost consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Unilever's Brazilian subscription infrastructure captures recurring revenue streams away from supermarket intermediaries. |
| Botanical Supply Chain Integration | Natura & Co's Amazonian cooperative sourcing secures certified sustainable raw material access denied to competitors. |
| Concentrated Formula Innovation | Procter & Gamble's compact dosing reduces per-use cost for Colombian price-sensitive household penetration. |
| Cold-Melt Compounding Upgrade | Rheology modifier integration achieves 500-5000 cP viscosity targets for ANVISA-compliant pump dispensing formats. |
| Subscription Refill Format Expansion | Argentine metropolitan logistics hubs enable same-day delivery displacing single-use packaging at point-of-purchase. |
Research Methodology
Cross-validation between primary interviews with brand managers at Unilever and Natura & Co and secondary validation through ANVISA regulatory filings anchors the qualitative findings. Stakeholder roles engaged include category buyers at Brazilian supermarket chains, supply planners at Argentine direct-to-consumer platforms, technical R&D directors at Colombian manufacturing facilities, and channel sales heads across Chilean pharmacy networks. Secondary sources encompass customs records for surfactant import flows, Nielsen retail audit data for format share tracking, SEC filings from multinational parent entities, and Mercosur harmonization proposal documentation. Bottom-up volume modeling triangulates against top-down category value estimates.
Calibration against historical CAGRs from adjacent personal care categories validates the projection framework across the analysis window. Segmentation dimensions modeled include product type viscosity specifications, end-user demographic procurement authority, distribution channel logistics maturity, and packaging format sustainability positioning. CAGRs derive from regression-adjusted trend extrapolation incorporating urban millennial premiumization rates and regulatory compliance cost trajectories. Forecast inputs incorporate ANVISA disclosure mandate implementation timelines and secondary city logistics penetration curves.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Argentine inflation volatility, or Colombian peso stability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and cooperative supply stream expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Natural Hair Care Product Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
France Sustainable Personal Care Market
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
BB Cushions Market
Beauty & Personal Care
India Herbal Shampoo Market
Beauty & Personal Care
Japan Beauty and Personal Care Products Market
Beauty & Personal Care
Portable Atomizer Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
Stretch Mark Removal Products Market
Beauty & Personal Care
DIY Haircut Kits Market
Beauty & Personal Care
Spas and Beauty Salons Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Skin Care Luxury Cosmetic Market
Beauty & Personal Care
Slimming Cream Market