
 Hair Removal Spray Market | 2026-2036
Hair Removal Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Removal Spray Market Foresight
Premium-grade depilatory formulations with skin-conditioning additives is rotating the Hair Removal Spray market toward higher-margin positioning. Veet leverages its global manufacturing footprint to sustain volume leadership across mass retail channels. Nair differentiates through specialized variants targeting coarse hair textures. Sally Hansen anchors the North American pharmacy segment with dermatologist-tested positioning.
Hair removal spray denotes a topical depilatory product delivered via pressurized aerosol, cream, gel, or foam vehicle, typically containing alkaline agents such as calcium thioglycolate or potassium hydroxide that hydrolyze keratin bonds at the skin surface. The aerosol segment dominates unit sales due to convenience and even coverage, though gel formats command superior margins among professional salon buyers. Distribution through online channels is expanding fastest as direct-to-consumer brands bypass traditional retail slotting fees, while supermarket placements remain the volume anchor for mass-market aerosol lines.
Regulatory scrutiny from the EPA governs aerosol propellant formulations in the United States, while the EU REACH framework restricts specific chemical sensitizers in leave-on skin products. The FDA's over-the-counter monograph system shapes labeling requirements and active ingredient concentrations permitted in domestic retail sales. Stakeholders must monitor evolving state-level cosmetic safety legislation and ingredient disclosure mandates that could reshape formulation costs and market access conditions.
Market Dynamics
The Hair Removal Spray market is contending with a fundamental tension between alkaline depilatory chemistry and plant-derived alternatives as EU REACH restrictions tighten on thioglycolate compounds. This regulatory compression is forcing reformulation investments while simultaneously opening premium positioning for botanical actives.
Growth Catalysts
- At-home aesthetic sophistication:Brazilian consumers maintain elevated per-capita consumption due to tropical climate conditions and established beauty rituals. Salon-grade formulations now migrate to domestic channels.
- REACH-driven botanical substitution:The EU framework restricts calcium thioglycolate concentrations in leave-on products. Manufacturers pivot to enzymatic and plant-based keratinolytic agents to preserve market access.
- Aerosol convenience premium:Pressurized delivery systems dominate unit economics through even coverage and reduced application time. Professional clinics adopt spray formats for pre-treatment protocols.
Market Restraints
- Input cost volatility:Potassium hydroxide and calcium thioglycolate prices fluctuate with industrial chemical feedstock markets. Margin compression hits mass-market aerosol lines disproportionately.
- Regulatory fragmentation:The EPA governs propellant formulations in the United States while FDA monographs dictate active concentration ceilings. Dual compliance burdens constrain cross-border product standardization.
- Substitution threat from IPL devices:Intense pulsed light home systems capture permanent hair reduction demand. Depilatory sprays face share erosion in the premium consumer segment.
Strategic Opportunities
- Professional channel expansion:Salons in São Paulo and Rio de Janeiro represent underpenetrated volume for clinical-strength formulations. Brazilian aesthetic culture supports premium service bundling.
- E-commerce disintermediation:Direct-to-consumer brands bypass supermarket slotting fees through proprietary digital channels. Subscription models lock recurring revenue for gel-format premium lines.
- PLI scheme alignment:India's production-linked incentive framework rewards domestic manufacturing of cosmetic actives. Contract manufacturers can capture cost advantages for export-oriented production.
Industry Challenges
- Formulation chemist scarcity:Expertise in alkaline keratin hydrolysis at cosmetic-grade purity concentrates in legacy European and North American suppliers. Talent migration lags facility relocation.
- Propellant transition capex:The EPA's volatile organic compound restrictions mandate hydrocarbon-to-compressed gas conversions. Aerosol filling lines require substantial retooling investment.
- State-level disclosure mandates:California's Proposition 65 and emerging cosmetic ingredient registries impose labeling complexity. Compliance timelines compress product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Removal Spray Market |
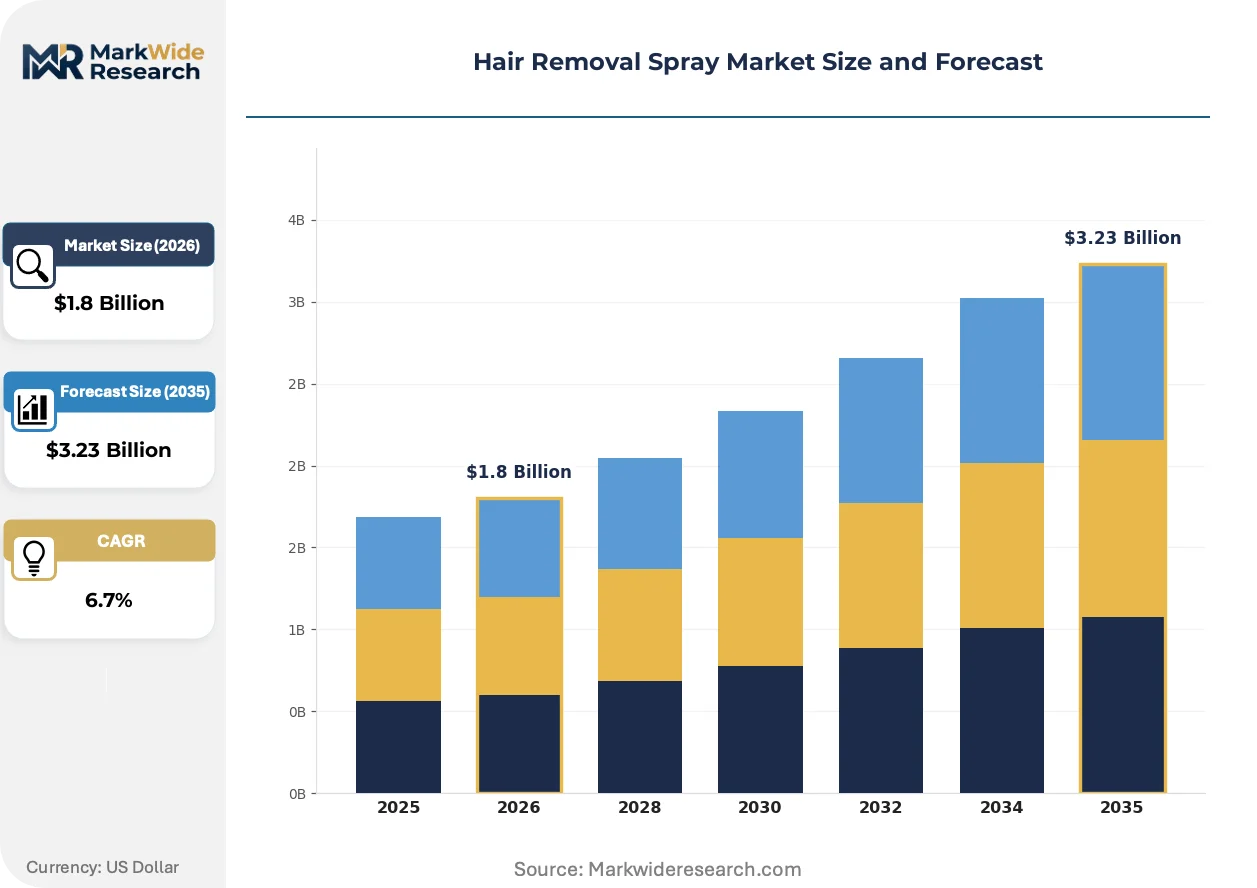
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol, Cream, Gel, Foam End User: Men, Women, Salons, Clinics Application: Body, Facial, Sensitive Areas, Legs Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Veet, Nair, Sally Hansen, GiGi, Elite, Bliss, LCM Laboratory, Jolen, Parissa Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Removal Spray Market Shifts & Advancements
Formulation chemistry and distribution architecture are diverging simultaneously. The market witnesses parallel tracks of clinical-grade professionalization and mass-market accessibility, each demanding distinct technical and commercial capabilities.
Botanical enzymatic depilatories utilizing papain and bromelain extracts are bifurcating the active ingredient landscape. Professional salon buyers in Brazil and Southern Europe adopt these alternatives for sensitive-skin protocols. The technology is compressing synthetic thioglycolate demand in premium segments while mass retail retains alkaline chemistry for cost positioning.
REACH authorization requirements for chemical sensitizers are tightening disclosure obligations across EU member states. Manufacturers must submit extended safety data dossiers for calcium thioglycolate variants. Professional-grade gel formats face the steepest compliance burden due to prolonged skin contact protocols.
Subscription-based replenishment models are displacing supermarket impulse purchases among millennial and Gen-Z cohorts. Direct-to-consumer brands capture recurring revenue through personalized hair-type matching algorithms. This behavioral shift concentrates most visibly in North American urban markets where pharmacy channel loyalty has eroded.
Hair Removal Spray Market Segmentation
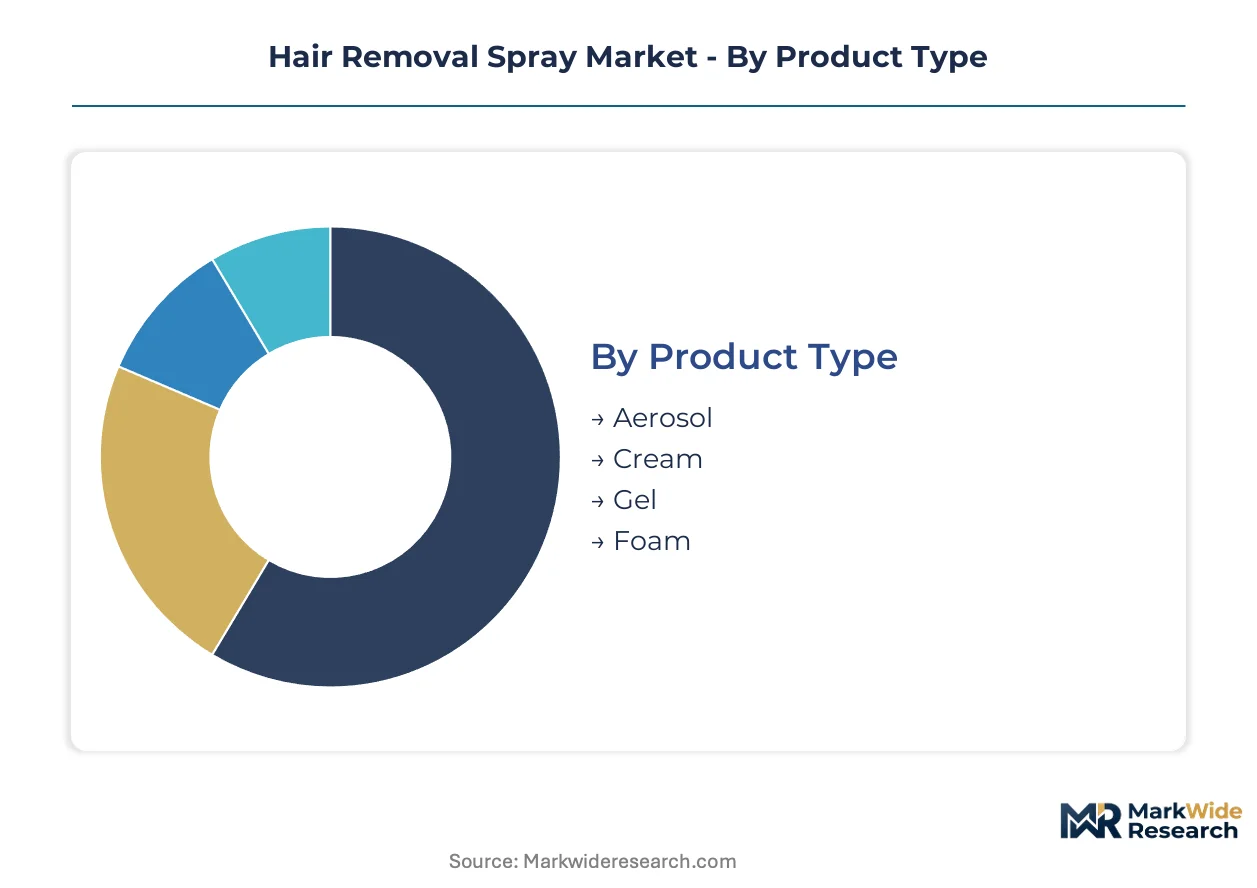
Segmentation in hair removal spray markets determines formulation chemistry, packaging format, and channel economics. Distinct user requirements across demographics and use cases force parallel product architectures that reshape manufacturing priorities and margin structures.
Product Type:
Aerosol formats dominate mass retail through pharmacy and supermarket channels, while gel and cream variants concentrate in professional salon procurement and direct-to-consumer subscriptions.
- Aerosol:Pressurized delivery systems combine hydrocarbon or compressed gas propellants with alkaline depilatory suspensions. Brazilian consumers purchase aerosol formats at elevated per-capita rates due to tropical climate demands and established at-home beauty rituals. EPA volatile organic compound restrictions are forcing propellant transitions that raise unit production costs.
- Gel:Thixotropic formulations enable precise application and extended skin contact protocols. Professional clinics in São Paulo and Rio de Janeiro specify gel formats for pre-treatment hair reduction, supporting premium service bundling. EU REACH disclosure requirements for prolonged-contact products impose steepest compliance burdens on this segment.
- Cream:Traditional emulsion vehicles retain cost positioning in emerging markets through simplified manufacturing and established supply chains.
- Foam:Low-density aerated formulations target convenience-oriented consumers seeking faster application and rinse cycles.
By volume, Aerosol leads. By growth pace, Gel is climbing the fastest.
End User:
Cost tier stratification separates mass-market personal use from professional service applications, with formulation strength and skin-conditioning additives determining price positioning.
- Women:The largest addressable base drives innovation in sensitive-skin protocols and botanical enzymatic alternatives. North American and Brazilian markets show strongest subscription adoption for personalized hair-type matching services.
- Salons:Professional buyers demand clinical-strength formulations with precise application control. Brazilian aesthetic culture supports premium service bundling in São Paulo and Rio de Janeiro metropolitan areas.
- Men:Coarse hair texture specialization and body-grooming normalization expand addressable demand, particularly in urban North American markets.
- Clinics:Medical-spa and dermatology settings require hypoallergenic certification and extended safety documentation under FDA and EU regulatory frameworks.
Women generate highest absolute revenue. Salons deliver steepest margin expansion.
Application:
Volume concentration varies sharply by body zone, with larger surface areas supporting mass-market economics and precision applications commanding formulation premiums.
- Legs:Extensive surface area sustains highest unit consumption and economies of scale in aerosol manufacturing. Brazilian tropical climate sustains year-round demand concentration.
- Facial:Precision requirements and sensitive-skin protocols drive enzymatic and botanical formulation adoption. Professional channel preference concentrates in Southern European and Brazilian salon markets.
- Body:Torso and back applications support men's grooming segment expansion through specialized coarse-hair formulations.
- Sensitive Areas:Hypoallergenic certification and dermatologist testing requirements create barrier to entry, concentrating supply among established pharmaceutical-grade manufacturers.
Legs anchor volume throughput. Facial applications gain share fastest through premium positioning.
Distribution Channel:
Channel migration is reshaping margin capture, with digital disintermediation compressing traditional retail economics while subscription models lock recurring revenue.
- Online:Direct-to-consumer brands bypass supermarket slotting fees through proprietary digital channels. North American urban markets show strongest pharmacy channel erosion as millennial and Gen-Z cohorts shift to subscription replenishment.
- Supermarkets:Impulse purchase placement and promotional pricing sustain volume for mass-market aerosol lines, though margin compression intensifies from input cost volatility.
- Pharmacies:Dermatologist-tested positioning and regulatory credibility anchor North American volume, particularly among sensitive-skin product variants.
- Specialty Stores:Beauty-focused retailers support premium gel and botanical format discovery, with professional-grade products targeting salon supply relationships.
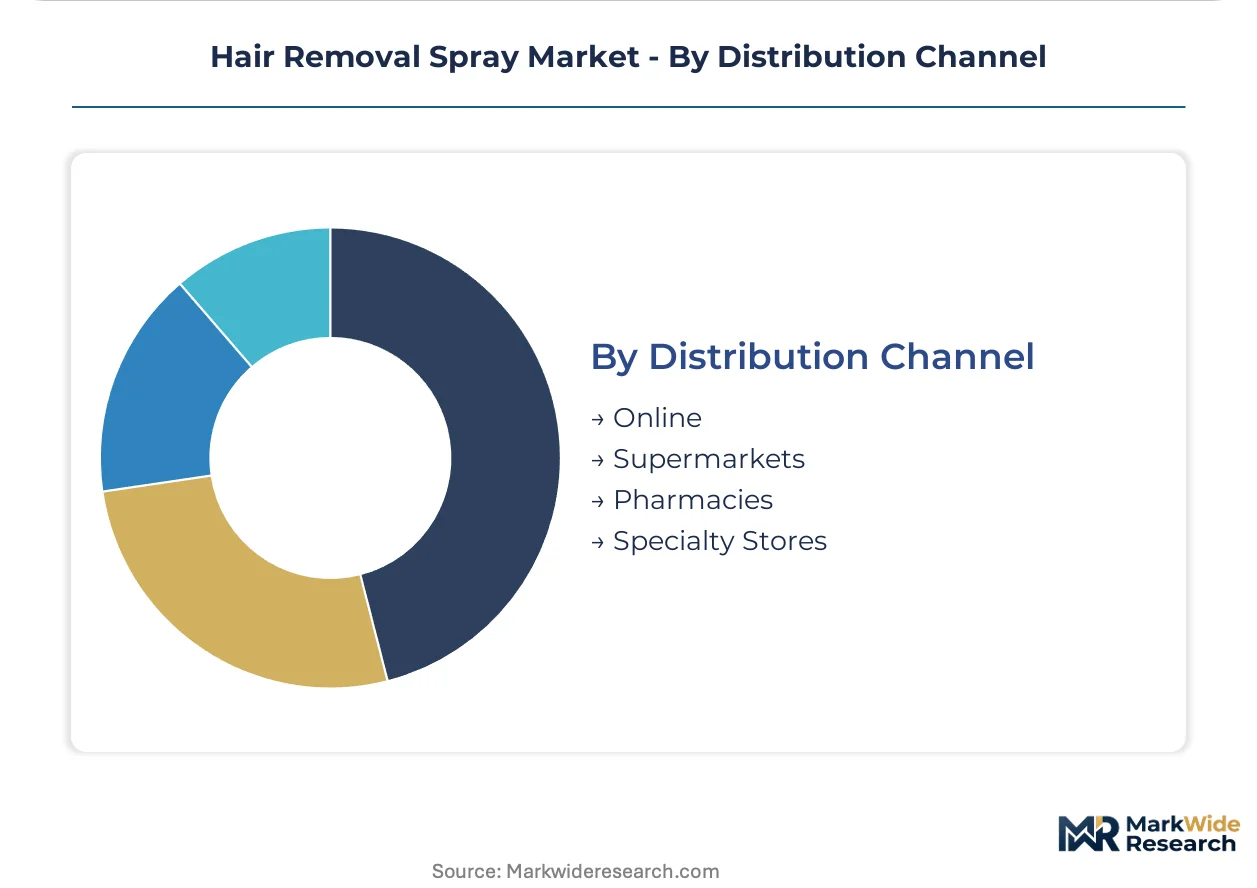
Supermarkets retain volume leadership. Online channels are expanding most quickly through subscription conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing in China and Germany supplies depilatory actives to formulation hubs in Brazil and the United States, while regulatory divergence across EPA, REACH, and ANVISA frameworks fragments product standardization and cross-border shipment economics.
United States
Pharmacy channel volume concentrates in dermatologist-tested positioning, with millennial cohorts migrating toward subscription replenishment models. The FDA's over-the-counter monograph system governs calcium thioglycolate concentration ceilings and labeling requirements. Manufacturing clusters in New Jersey and North Carolina supply aerosol filling capacity for mass retail distribution.
Brazil
Tropical climate conditions and established aesthetic culture sustain the world's highest per-capita consumption of depilatory sprays. ANVISA registration requirements for cosmetic products impose documentation burdens on imported formulations. São Paulo and Rio de Janeiro metropolitan areas anchor professional salon procurement for clinical-strength gel variants.
Germany
EU REACH restrictions on thioglycolate compounds drive reformulation investment toward enzymatic alternatives. ECHA authorization dossiers for chemical sensitizers compress product development timelines. Industrial chemical production in the Rhine-Ruhr region supplies potassium hydroxide feedstock to European formulation facilities.
China
Domestic manufacturing capacity for aerosol propellants and alkaline actives supports export-oriented production. The National Medical Products Administration governs cosmetic ingredient safety assessments and import registration. Yangtze River Delta chemical clusters produce calcium thioglycolate at scale for global supply chains.
India
Production-linked incentive schemes reward domestic manufacturing of cosmetic actives and finished formulations. The Central Drugs Standard Control Organization regulates depilatory product classification between cosmetics and pharmaceuticals. Maharashtra and Gujarat host contract manufacturing facilities serving Middle East and African export markets.
Hair Removal Spray Market Competitive Landscape
Concentration sits with multinational consumer goods conglomerates commanding mass retail shelf space and established regulatory compliance infrastructure. Three archetypes define competitive positioning: aerosol volume leaders with global manufacturing footprints, gel-format specialists targeting professional salon channels, and direct-to-consumer entrants exploiting digital disintermediation. Capacity expansion in Brazilian and Indian manufacturing zones and strategic partnerships with contract formulation houses represent the dominant competitive moves reshaping supply architecture.
Among heritage consumer goods incumbents, Veet and Nair exemplify the scale-driven archetype through sustained pharmacy and supermarket channel presence, while Sally Hansen anchors dermatologist-tested positioning within North American retail. These entities occupy positions spanning mass-market aerosol economics and premium gel-format development, reflecting the market's bifurcation between convenience-driven volume and professional-grade margin capture.
| Leading Market Players |
|---|
| Veet |
| Nair |
| Sally Hansen |
| GiGi |
| Elite |
| Bliss |
| LCM Laboratory |
| Jolen |
| Parissa Laboratories |
| Others |
Supply & Pricing Matrix
EU REACH authorization requirements for calcium thioglycolate variants simultaneously gate supplier qualification and stratify price tiers across the Hair Removal Spray market. Manufacturers must submit extended safety data dossiers to preserve market access, concentrating premium positioning among firms with compliance infrastructure while mass-market aerosol lines absorb disproportionate margin compression from dual EPA-FDA regulatory burdens.
Pricing Analysis
Salon and clinic buyers anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on formulation strength certification and dermatologist-testing protocols. Cost compression in mass-market aerosol tiers intensifies because potassium hydroxide feedstock volatility feeds through to finished goods. Individual consumers in emerging markets exhibit highest price sensitivity, while Brazilian professional clinics demonstrate lowest sensitivity due to service-bundling economics.
Supply Chain Analysis
China and Germany anchor industrial-scale production of calcium thioglycolate actives and potassium hydroxide feedstock for global formulation networks. Manufacturing draws from Yangtze River Delta chemical clusters and Rhine-Ruhr industrial bases. Single-source vulnerability concentrates in EU REACH-compliant botanical enzymatic alternatives where papain and bromelain extraction capacity remains limited. Distribution runs through contract manufacturing facilities in India and Brazil for regional market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH-driven botanical substitution represents a high-growth disruption reshaping competitive economics, with enzymatic alternatives capturing premium positioning as thioglycolate restrictions tighten.
For Market Incumbents: Consolidate regulatory compliance infrastructure as a defensive moat against direct-to-consumer entrants lacking REACH dossier capabilities. Add aerosol filling capacity in São Paulo to capture Brazilian professional channel growth. Deepen backward integration into botanical enzymatic supply chains before feedstock scarcity elevates input costs. For New Entrants and Emerging Players: ANVISA fast-track certification for cosmetic products opens Brazilian market entry before incumbents complete local manufacturing transitions. Target underpenetrated men's grooming segments in North American urban markets with coarse-hair specialized formulations. Deploy subscription-based replenishment models to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: EU REACH authorization milestones reshape the acquisition landscape toward firms with completed thioglycolate safety dossiers. Prioritize contract manufacturers with dual EPA-FDA compliance infrastructure and established Brazilian ANVISA registration. Monitor EPA volatile organic compound restriction timelines as capex inflection signals for aerosol line retooling requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Enzymatic Reformulation | REACH-compliant papain and bromelain alternatives capture premium salon positioning in Southern Europe. |
| Compressed Gas Propellant Transition | EPA volatile organic compound mandates force hydrocarbon-to-compressed gas retooling investment. |
| Direct-to-Consumer Subscription Launch | Digital disintermediation bypasses supermarket slotting fees and locks recurring revenue. |
| Professional Channel Expansion | São Paulo and Rio de Janeiro salon procurement supports clinical-strength gel premiumization. |
| Contract Manufacturing Partnership | India's PLI scheme rewards domestic cosmetic active production for Middle East export markets. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with formulation chemists, regulatory affairs directors at depilatory manufacturers, salon procurement managers in São Paulo and Rio de Janeiro, and e-commerce channel heads; alongside secondary validation through FDA over-the-counter monograph filings, ECHA REACH authorization databases, ANVISA cosmetic registration records, and trade flow data from Yangtze River Delta export clusters. Bottom-up demand modeling triangulated against top-down chemical feedstock consumption patterns.
Across the analysis window, forecasts employed segmented modeling across product type, end user, application zone, and distribution channel dimensions. CAGRs derived from historical volume trajectories adjusted for regulatory inflection timing and channel migration velocity. Industry-specific inputs incorporated REACH authorization pipeline status and EPA volatile organic compound compliance timelines.
Decision-makers should treat outputs as directional under sustained REACH enforcement and stable feedstock pricing assumptions; material deviation in regulatory timelines or potassium hydroxide cost volatility would warrant model refresh. Recalibration cycles align with material shifts in EU authorization milestones and state-level cosmetic disclosure mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
US Cosmetics Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
China Antibacterial Soap Market
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
Hair Serums Ingredient Market
Beauty & Personal Care
Colombia Cosmetics Products Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Global Heated Eyelash Curlers Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market