
 Bio-Based Cosmetics Market | 2026-2036
Bio-Based Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
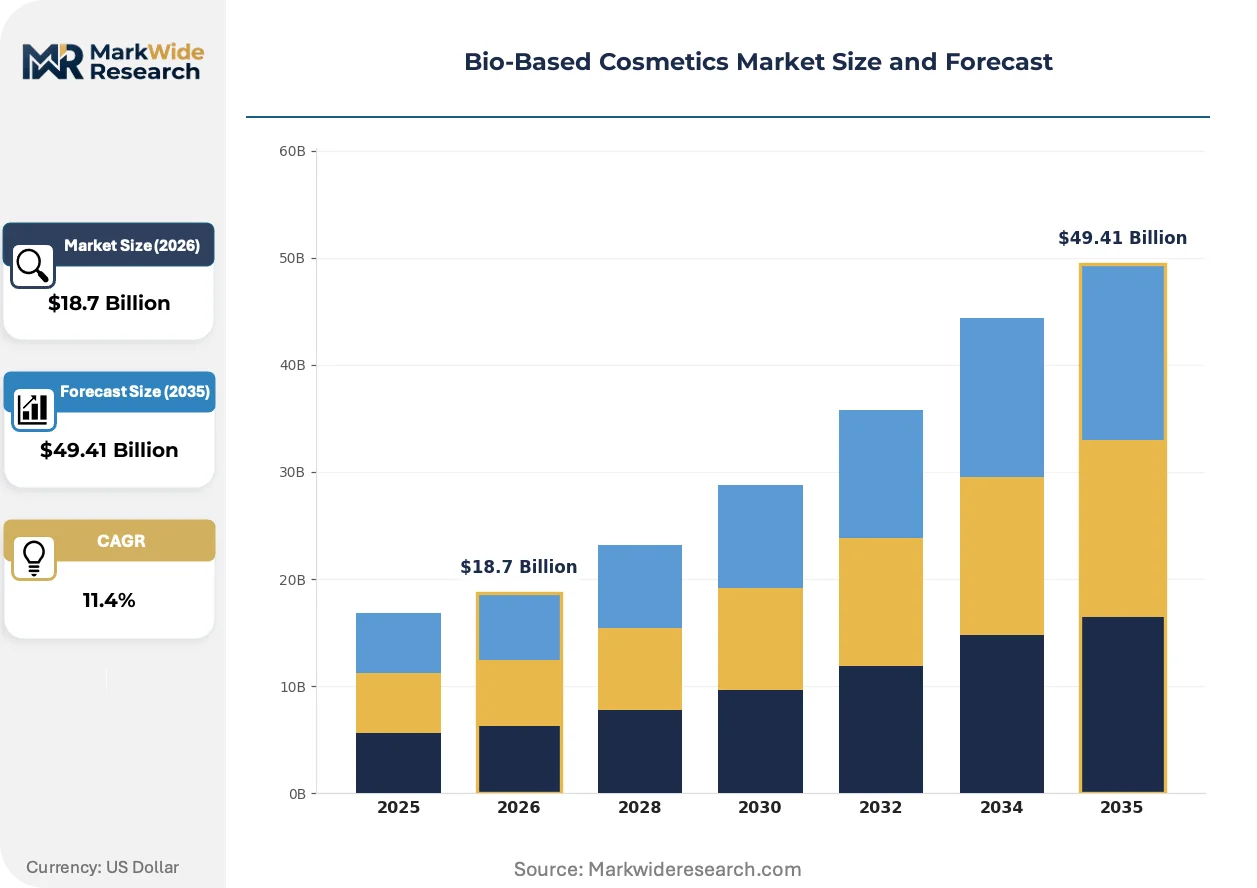
Bio-Based Cosmetics Market Outlook
The premium tier is pivoting toward certified organic formulations with full supply chain transparency, while commodity tiers compete on natural-origin percentages without third-party validation. L'Oréal leverages integrated botanical sourcing networks across multiple continents. BASF SE anchors its position through fermentation-derived active ingredients. Unilever differentiates via mass-market accessibility of bio-based claims at scale.
Bio-based cosmetics comprise personal care formulations where key functional ingredients derive from renewable biological sources rather than petrochemical feedstocks, typically incorporating botanical extracts with specified polyphenol concentrations or cold-pressed essential oils retaining terpene profiles for antioxidant or antimicrobial performance. These products serve consumers seeking reduced synthetic chemical exposure alongside measurable dermatological benefits. Skincare commands the deepest margin pools due to clinical positioning of plant-derived retinol alternatives and peptide complexes. Haircare registers the fastest trajectory as salon professionals switch to bio-surfactant shampoos. Fragrance remains the most mature segment, constrained by the technical challenge of replicating synthetic fixative longevity with natural extracts alone.
EMA guidelines on cosmetic ingredient safety assessments and REACH registration requirements for botanical substances shape European formulation standards, while the EU Green Deal pushes brands toward biodegradable packaging cascades. FDA oversight of cosmetic labeling in the United States creates divergence in permissible structure-function claims between jurisdictions. ISO 16128 standards for natural and organic cosmetic ingredients provide a harmonized analytical baseline for cross-border certification. Stakeholders must weigh the capital intensity of backward integration into raw botanical cultivation against the regulatory risk of emerging restrictions on wild-harvested species.
Market Dynamics
Formulators face mounting pressure from the EU Green Deal's biodegradability mandates and REACH registration requirements for botanical actives, forcing capital reallocation toward verified supply chains and fermentation-derived alternatives to wild-harvested species.
Growth Catalysts
- REACH compliance tiers:ECHA's phased registration deadlines for botanical substances accelerate formalization of extraction protocols and analytical documentation among European suppliers.
- Clean beauty retail penetration:Sephora and Ulta Beauty's clean certification programs in the United States create shelf-space premiums for bio-based claims with third-party validation.
- Fermentation-derived actives:Biotechnology platforms producing squalane and ceramides from sugar feedstocks bypass agricultural land constraints and pesticide residue concerns.
Market Restraints
- Wild-harvesting restrictions:CITES listings for sandalwood and certain orchid species constrain fragrance formulators dependent on traditional extraction sources.
- Cold-pressed oil volatility:Climate-induced yield fluctuations for argan, rosehip, and marula oils create input cost instability for mid-tier brands without forward contracts.
- Natural fixative limitations:Ambroxan and synthetic musk replacements from plant sources deliver shorter scent longevity, compressing fragrance segment margins.
Strategic Opportunities
- Salon professional conversion:Bio-surfactant shampoos and conditioners capture share among independent stylists in Germany and France seeking differentiated service menus.
- ISO 16128 certification arbitrage:Harmonized natural content calculation standards enable cross-border positioning for brands entering Asian markets with established European credentials.
- Biodegradable packaging mandates:EU single-use plastic directives drive demand for cellulose-based films and molded fiber containers compatible with bio-based formulations.
Industry Challenges
- Phytochemistry analytical capacity:Standardized polyphenol and terpene quantification requires investment in HPLC-MS infrastructure that smaller formulators lack.
- Multi-certification stacking:Simultaneous pursuit of COSMOS, Ecocert, and B Corp standards creates documentation overhead and audit fatigue.
- Legacy petrochemical integration:Reformulating silicone-dependent haircare and color cosmetics with bio-based emollients demands extensive stability testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Cosmetics Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Makeup, Skincare, Haircare, Fragrance Ingredient Type: Botanical Extracts, Essential Oils, Natural Wax, Fruits Customer Type: Retail Consumers, Professional Salons, E-commerce Shoppers, Bulk Buyers Packaging Type: Glass Containers, Biodegradable Tubes, Recyclable Jars, Pump Dispensers |
| Companies Covered | L'Oréal, BASF SE, Unilever, Estée Lauder Companies, Shiseido, Procter & Gamble, LVMH, Evonik Industries AG, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Cosmetics Market Strategic Shifts
Biotechnology platforms and precision fermentation are displacing conventional extraction methods for high-value actives, while regulatory frameworks on both sides of the Atlantic harden documentation requirements for natural claims.
Precision fermentation for squalane and rare cannabinoids is integrating into mainstream skincare manufacturing. Mid-tier brands in France and Germany now specify biotech-derived alternatives in RFPs to suppliers. This shift is compressing lead times from agricultural harvest cycles to bioreactor batch schedules, reducing exposure to climate volatility.
REACH registration requirements for botanical substances are tightening substance documentation obligations across European supply chains. Formulators must now submit full toxicological dossiers for plant extracts previously grandfathered under generic classifications. Haircare applications face the steepest compliance burden due to scalp contact duration and rinse-off classification debates.
Ingredient provenance verification has become a primary purchase criterion among premium skincare buyers. Direct-to-consumer brands leverage blockchain-tracked supply chains as competitive differentiation against mass-market natural claims. This pattern concentrates in the United States and United Kingdom, where clean beauty subscription services reward transparency with recurring revenue lock-in.
Bio-Based Cosmetics Market Segmentation
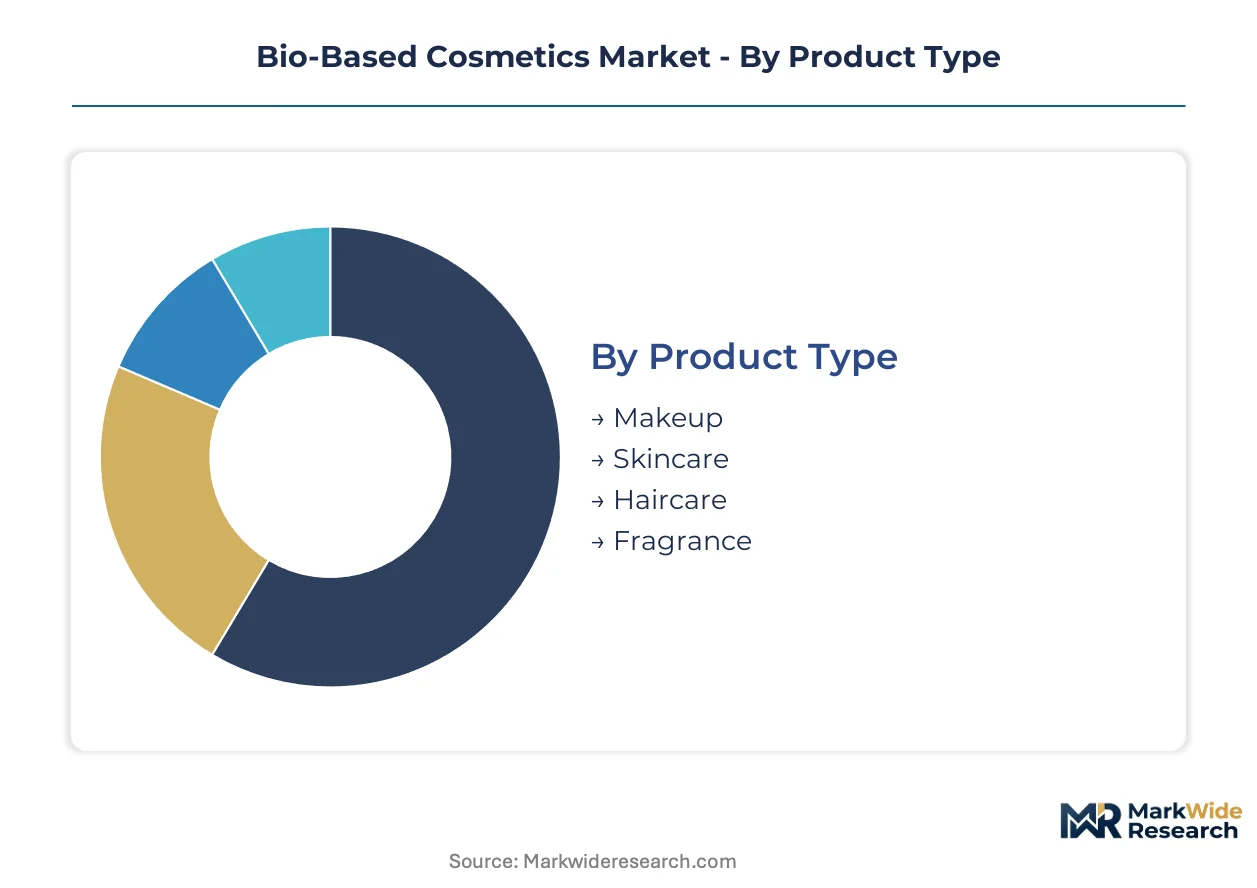
Segmentation in bio-based cosmetics reveals divergent margin structures and compliance burdens across product categories. Formulators must align R&D investment with the specific certification requirements and buyer sophistication of each segment tier.
Product Type:
Clinical efficacy claims drive premium pricing power across functional categories, with dermatological positioning commanding the steepest formulation investment.
- Skincare:Plant-derived retinol alternatives and peptide complexes anchor clinical positioning. Demand concentrates in France and Germany where pharmacy retail channels reward ECHA-compliant documentation with shelf placement.
- Haircare:Bio-surfactant shampoos and conditioners target salon professionals switching from silicone-dependent legacy formulations. Independent stylists in Germany and France seek differentiated service menus that command service premiums.
- Fragrance:Natural fixatives face technical constraints on scent longevity versus synthetic alternatives.
- Makeup:Color cosmetics struggle with bio-based pigment stability and coverage performance trade-offs.
Volume sits with Skincare; growth tilts toward Haircare.
Ingredient Type:
Supply chain traceability requirements reshape sourcing economics, with wild-harvested species facing mounting regulatory pressure across European jurisdictions.
- Botanical Extracts:Standardized polyphenol concentrations require HPLC-MS analytical infrastructure that filters smaller suppliers. REACH registration deadlines for botanical substances accelerate formalization of extraction protocols among European suppliers.
- Essential Oils:Cold-pressed terpene profiles deliver antioxidant and antimicrobial performance in preservative-free formulations. Climate-induced yield fluctuations for rosehip and marula oils create input cost instability for mid-tier brands lacking forward contracts.
- Natural Wax:Emollient bases for solid formulations and lip products.
- Fruits:Enzyme-rich extracts for gentle exfoliation claims.
Commercial gravity centers on Botanical Extracts; steepest expansion trajectory belongs to Essential Oils.
Customer Type:
Channel selection determines certification complexity, with professional and bulk segments demanding documentation that retail consumers rarely verify.
- Professional Salons:Service-menu differentiation drives bio-surfactant specification. Independent stylists in Germany and France convert fastest as they seek competitive separation from mass-market retail offerings.
- E-commerce Shoppers:Subscription services reward transparency with recurring revenue lock-in. Direct-to-consumer brands leverage blockchain-tracked supply chains as competitive differentiation in the United States and United Kingdom.
- Retail Consumers:Mass-market accessibility of bio-based claims at scale.
- Bulk Buyers:Private-label manufacturers seeking ISO 16128 certification arbitrage for Asian market entry.
Revenue concentrates with E-commerce Shoppers; Professional Salons gain share fastest.
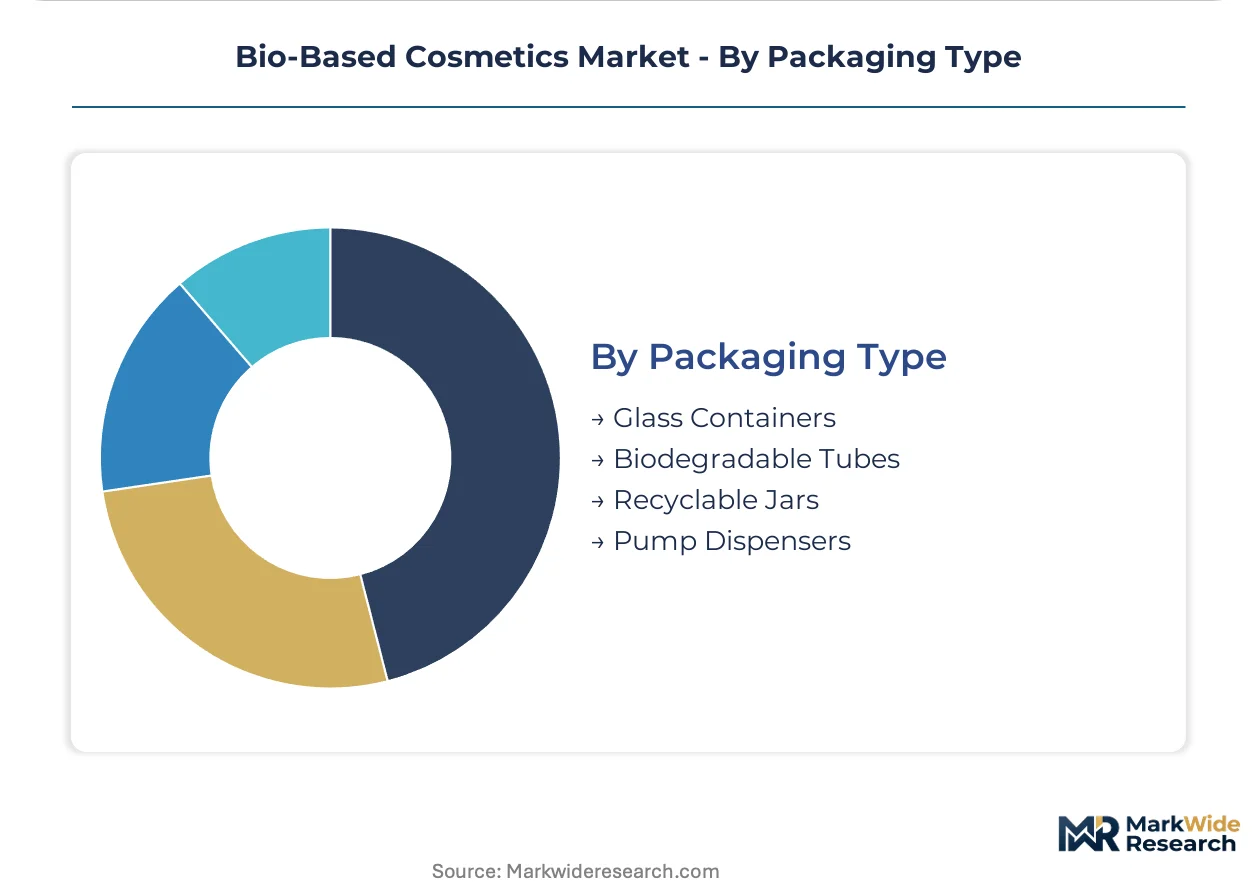
Packaging Type:
EU single-use plastic directives cascade through formulation-packaging compatibility requirements, elevating material science to competitive priority.
- Biodegradable Tubes:Cellulose-based films and molded fiber containers align with EU Green Deal mandates. Brands entering European markets must demonstrate packaging biodegradability alongside formulation claims.
- Glass Containers:Premium positioning with established recycling infrastructure in France and Germany supports circular economy narratives.
- Recyclable Jars:Widest compatibility across product viscosity ranges.
- Pump Dispensers:Convenience-driven adoption in hand care and body lotion categories.
Regulatory tailwinds favor Biodegradable Tubes; Glass Containers retain premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors the European bio-based cosmetics ecosystem through its dense cluster of pharmacy retail channels and formulation laboratories serving premium skincare brands. The United States and Germany follow as volume centers, each shaped by distinct regulatory architectures and distribution infrastructures.
United States
Clean beauty subscription services in New York and Los Angeles drive recurring revenue models that reward supply chain transparency. FDA labeling requirements for cosmetic structure-function claims create stricter boundaries than European counterparts allow. Sephora's headquarters in San Francisco sets certification standards that cascade through national retail networks.
Germany
Independent salon professionals in Berlin and Hamburg convert rapidly to bio-surfactant haircare for service-menu differentiation. REACH registration deadlines enforced by ECHA accelerate toxicological documentation for botanical extracts. The Rhine-Ruhr industrial corridor concentrates fermentation-derived active ingredient manufacturing for export across European markets.
France
Pharmacy retail channels in Paris and Lyon privilege ECHA-compliant documentation with premium shelf placement for clinical skincare positioning. ANSM enforces stricter safety assessment protocols than EU baseline requirements. Grasse maintains fragrance extraction expertise despite CITES constraints on traditional wild-harvested materials.
United Kingdom
Direct-to-consumer brands in London leverage blockchain-tracked supply chains as competitive differentiation against mass-market claims. Post-Brexit regulatory divergence from REACH creates compliance complexity for cross-border formulation trade. Manchester and Birmingham host contract manufacturers serving private-label entrants seeking ISO 16128 certification.
Japan
Department store beauty halls in Tokyo and Osaka demand rigorous documentation of botanical provenance for premium positioning. METI guidelines on quasi-drug classifications create additional approval layers for functional skincare claims. Osaka-based suppliers specialize in fermentation-derived ceramides for regional brand formulation.
Bio-Based Cosmetics Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and supply chain transparency dimensions. The vendor base organizes into three tiers: integrated multinationals with captive botanical networks, specialized ingredient suppliers with fermentation platforms, and private-label manufacturers competing on natural-origin percentages. Strategic moves concentrate on backward integration into raw material cultivation and multi-certification stacking for cross-border market access.
Within the integrated multinational tier, L'Oréal and Unilever occupy positions defined by scale advantages in botanical sourcing networks and mass-market distribution reach. BASF SE anchors the specialized ingredient supplier segment through fermentation-derived active manufacturing. These three entities exemplify divergent paths to bio-based positioning: premium clinical efficacy claims, accessible mass-market natural percentages, and upstream biotechnology platform control respectively.
| Leading Market Players |
|---|
| L'Oréal |
| BASF SE |
| Unilever |
| Estée Lauder Companies |
| Shiseido |
| Procter & Gamble |
| LVMH |
| Evonik Industries AG |
| Clariant AG |
| Others |
Value Chain & Pricing Dynamics
Clean beauty subscription services in the United States and United Kingdom now mandate blockchain-tracked provenance documentation, forcing suppliers to absorb traceability infrastructure costs that compress mid-tier margins while premium brands capture certification premiums.
Pricing Analysis
Clinical efficacy claims anchor value-based pricing for plant-derived retinol alternatives and peptide complexes. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-compliant pharmacy-channel formulations from mass-market natural-percentage claims and unverified commodity offerings. Cost compression in the essential oils tier is intensifying because climate-induced yield fluctuations for argan and rosehip inputs destabilize forward contract pricing. Professional salons exhibit lowest price sensitivity due to service-menu premium capture, while retail consumers drive volume through promotional elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore coordinate hub-and-spoke patterns for fermentation-derived actives and cold-pressed botanical oils. Manufacturing gravity centers on France, Germany, and the United States for formulation and packaging, with India and Morocco supplying raw argan, rosehip, and marula feedstocks. The chain draws from agricultural harvest cycles vulnerable to drought stress and CITES-restricted wild-harvested species. Single-source vulnerability concentrates in Grasse for fragrance extraction expertise. Distribution runs through pharmacy retail channels in France, clean beauty specialty retailers in the United States, and department store beauty halls in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration deadlines for botanical substances create a supply-constrained environment where verified extraction capacity props pricing power for compliant suppliers.
For Market Incumbents: Anticipate margin compression from biotechnology platforms displacing conventional agricultural sourcing for squalane and ceramides. Defensive consolidation should prioritize backward integration into captive botanical cultivation in Morocco and India to secure climate-resilient input streams. Certification investment in COSMOS and Ecocert stacking preserves pharmacy-channel shelf placement against emerging private-label entrants. For New Entrants and Emerging Players: Enter via the salon professional segment in Germany and France where independent stylists seek differentiated bio-surfactant service menus with limited incumbent loyalty. White-space concentrates in biodegradable packaging-compatible formulations for EU Green Deal compliance. Direct-to-consumer subscription models with blockchain-tracked supply chains offer the most penetrable go-to-market angle in the United States and United Kingdom. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-platform specialists given biotechnology's displacement of agricultural land constraints and pesticide residue risks. Long-term viability favors upstream bioreactor capacity over extraction-dependent models. Watch ECHA registration completion rates as the inflection signal for supply-side consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Cultivation | Captive supply of climate-resilient botanicals in Morocco and India reduces yield volatility exposure. |
| Fermentation Platform Scale-Up | Bioreactor capacity for squalane and ceramides bypasses agricultural land constraints and REACH documentation burdens. |
| Multi-Certification Stacking | Simultaneous COSMOS, Ecocert, and ISO 16128 credentials unlock cross-border pharmacy and e-commerce channel access. |
| Biodegradable Packaging Transition | Cellulose-based films and molded fiber containers align with EU single-use plastic directives and Green Deal mandates. |
| Salon Professional Channel Capture | Independent stylist conversion in Berlin and Hamburg builds service-menu differentiation with recurring bulk purchasing. |
Study Parameters
Document review covered customs and trade data for botanical oil imports, ECHA registration databases, FDA cosmetic labeling guidance, and ISO 16128 certification records, complemented by interviews with formulation R&D directors, pharmacy retail category managers, salon professional purchasing coordinators, and fermentation platform operations leads. Secondary validation drew from SEC filings of listed personal care companies, EU Green Deal implementation reports, and REACH compliance tracking systems. Bottom-up segment sizing triangulated against top-down market value reconstructions.
Segmentation outputs across product type, ingredient source, customer channel, and packaging format were modeled over the projection horizon. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions for premium versus commodity tier formulations. Industry-specific inputs incorporated REACH registration timeline phasing, climate yield models for agricultural feedstocks, and biotechnology platform capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated CITES expansion to additional botanical species or breakthrough synthetic biology cost reductions. Periodic stress-testing of base assumptions is recommended given regulatory divergence between EU REACH and post-Brexit UK frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
Global Cosmetic Products Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
Face Oil Market
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
Global Beauty and Personal Care Products Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Japan Beauty Fridges Market
Beauty & Personal Care
US Sexual Wellness Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
Waterless Cosmetics Market
Beauty & Personal Care
Saudi Arabia Body Care and Personal Hygiene Market
Beauty & Personal Care
Beard Grooming Products Market
Beauty & Personal Care
Facial Care Products Market