
 Mens Intimate Care Products Market | 2026-2036
Mens Intimate Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Mens Intimate Care Products Market Outlook
E-commerce distribution for men's intimate care is fragmenting as direct-to-consumer subscriptions, pharmacy portals, and mass-market platforms compete for wallet share. Procter & Gamble Company leverages its shelf-space dominance in supermarkets to sustain volume leadership in deodorants and cleansers. Unilever PLC anchors its position through specialized men's grooming sub-brands that compete on formulation credibility. Beiersdorf AG differentiates via dermatological testing credentials that resonate with professionals seeking irritation-free daily care routines.
Mens intimate care products encompass topical formulations engineered for genital and perineal hygiene, typically incorporating pH-balanced surfactant systems, antimicrobial actives, and moisture-absorbing bases manufactured through emulsion or aerosol processes. These products serve commercial purposes spanning odor mitigation, friction reduction, and post-hair removal soothing across consumer and occupational contexts. Grooming creams and cleansers command the deepest margin pools as consumers trade up from basic bar soap to specialized formulations. Daily care and odor control applications are expanding fastest among athletes and professionals who integrate these products into post-gym and pre-work routines. The online retailers channel is capturing disproportionate growth as subscription mechanics lock in recurring revenue and reduce price transparency.
FDA cosmetic labeling requirements and EU REACH restrictions on fragrance allergens are elevating compliance costs for new entrants while rewarding incumbents with established toxicology dossiers. The EU Green Deal's packaging waste directives are forcing reformulation toward concentrated formats and refillable dispensers that alter unit economics. India's BIS quality standards for personal care imports are tightening market access for unbranded or white-label suppliers. Stakeholders must monitor how regulatory divergence between North American and European cosmetic frameworks reshapes portfolio prioritization and manufacturing location decisions.
Market Dynamics
Formulation chemistries free from talc and aluminum salts are forcing incumbent manufacturers to rebuild supply chains and toxicology dossiers under intensifying FDA and EU cosmetic safety scrutiny. This regulatory compression is accelerating while professional end users in workplace settings tighten appearance standards and reject legacy irritant-heavy products.
Growth Catalysts
- EU REACH restrictions on fragrance allergens:Incumbents with established toxicology dossiers capture shelf space as compliance costs eliminate unbranded competitors from German and French pharmacy channels.
- Athletic end-use vertical:Post-gym intimate care routines are normalizing among collegiate and professional sports programs, expanding daily-use frequency beyond traditional morning-only application patterns.
- pH-balanced surfactant systems:Dermatological testing credentials now function as table stakes for professional demographic penetration, elevating formulation R&D investment across the competitive set.
Market Restraints
- Aluminum salt substitution costs:Reformulation toward potassium alum and zinc ricinoleate alternatives raises raw material input costs by double-digit percentages for aerosol deodorant manufacturers.
- Supply concentration in German specialty chemical houses:Three mid-cap suppliers control the majority of dermocosmetic-grade emulsifier production, creating bottleneck risk for new entrants scaling manufacturing.
- Technical limitation in natural preservative efficacy:Clean-label antimicrobial actives demonstrate shorter shelf stability versus paraben alternatives, constraining distribution radius for direct-to-consumer subscription models.
Strategic Opportunities
- Underpenetrated Indian tier-2 cities:BIS quality standards for personal care imports are tightening, rewarding early movers who establish local manufacturing or joint ventures before full enforcement.
- EU Green Deal packaging waste directives:Concentrated formats and refillable dispensers alter unit economics toward higher-margin recurring revenue models with reduced per-unit shipping costs.
- Convergence of telemedicine and subscription commerce:Digital health platforms in the United States are integrating intimate care products into post-consultation recommendation engines, bypassing traditional retail gatekeepers.
Industry Challenges
- Toxicologist certification scarcity:Qualified professionals capable of navigating divergent FDA cosmetic labeling and EU REACH dossier requirements command premium compensation, stretching mid-cap R&D budgets.
- Legacy ERP integration with direct-to-consumer fulfillment:Manufacturers with supermarket-centric supply chain infrastructure face twelve-to-eighteen-month timelines to retrofit for subscription mechanics and dynamic inventory allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mens Intimate Care Products Market |
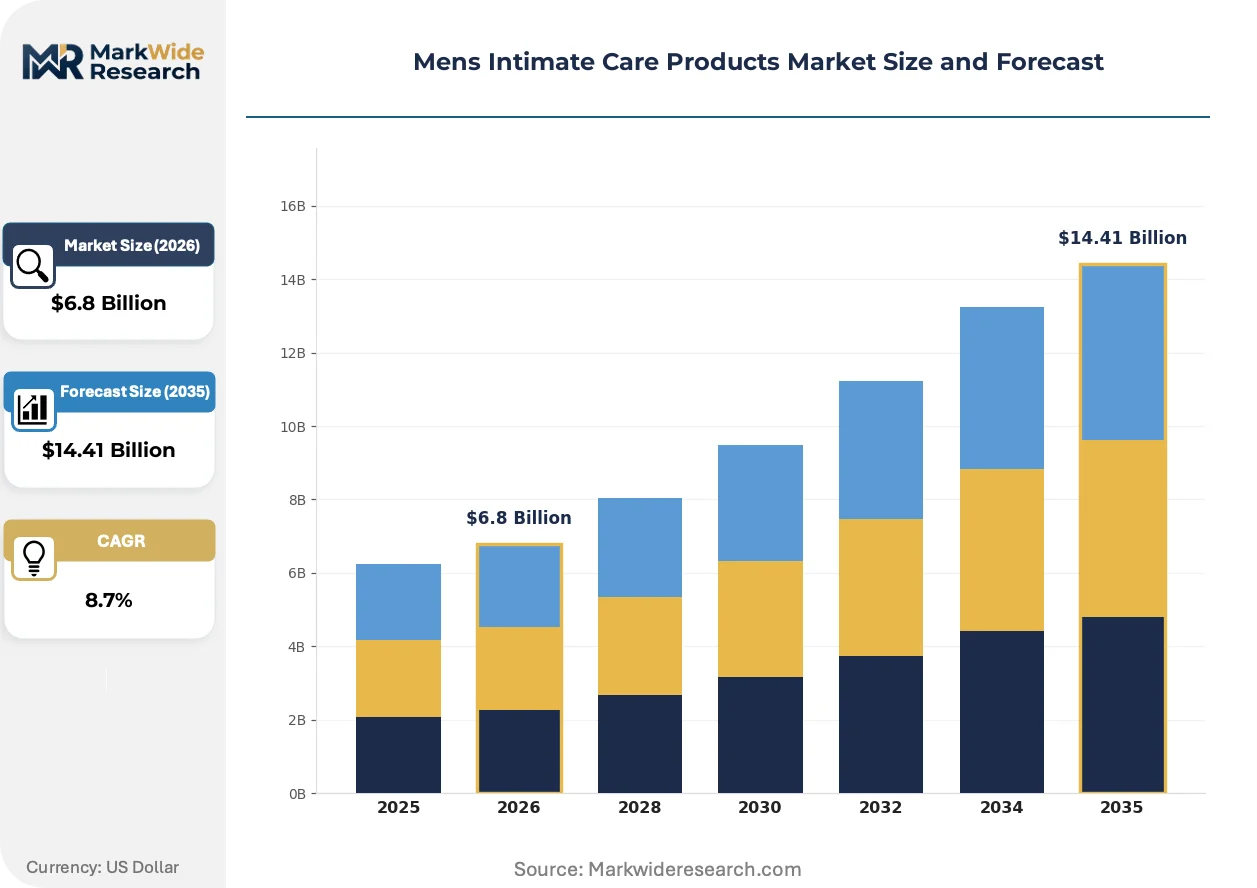
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grooming Creams, Deodorants, Cleansers, Powders Application: Pre-Shave, Post-Shave, Daily Care, Odor Control End User: Men, Athletes, Professionals, Teenagers Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Colgate-Palmolive Company, Church & Dwight, Procter & Gamble Company, Edgewell Personal Care, Coty Inc., Unilever PLC, L'Oréal S.A., Kimberly-Clark Corporation, Beiersdorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mens Intimate Care Products Market Strategic Shifts
Microbiome-conscious formulation science is redefining product architecture, as consumers reject broad-spectrum antimicrobial approaches in favor of selective bacterial balance maintenance. This shift is compressing legacy product lifecycles and rewarding brands with credible dermatological partnerships.
Prebiotic fiber complexes and postbiotic lysates are rendering obsolete traditional antiseptic-based intimate care formulations that indiscriminately eliminate bacterial populations. Professional end users in healthcare and corporate environments are adopting these technologies fastest, integrating them into pre-work and post-shift hygiene protocols. The structural consequence is margin compression for commodity antiseptic manufacturers unable to pivot toward microbiome-compatible actives.
EU Green Deal packaging waste directives are mandating concentrated formats and refillable dispensers that alter unit economics across the category. Manufacturers must redesign manufacturing lines for bulk concentrate production and establish reverse logistics networks for dispenser return. German and French markets are experiencing the most acute compliance pressure, with retailers demanding proof of packaging reduction roadmaps before contract renewal.
Subscription mechanics are locking in recurring revenue and reducing price transparency for male consumers who previously comparison-shopped across mass-market platforms. Direct-to-consumer brands capture disproportionate growth by bundling intimate care with adjacent grooming categories, displacing single-product pharmacy purchases. This pattern is most visible in the United States, where digital-native brands leverage post-gym and pre-work routine integration to establish habit formation.
Mens Intimate Care Products Market Segmentation
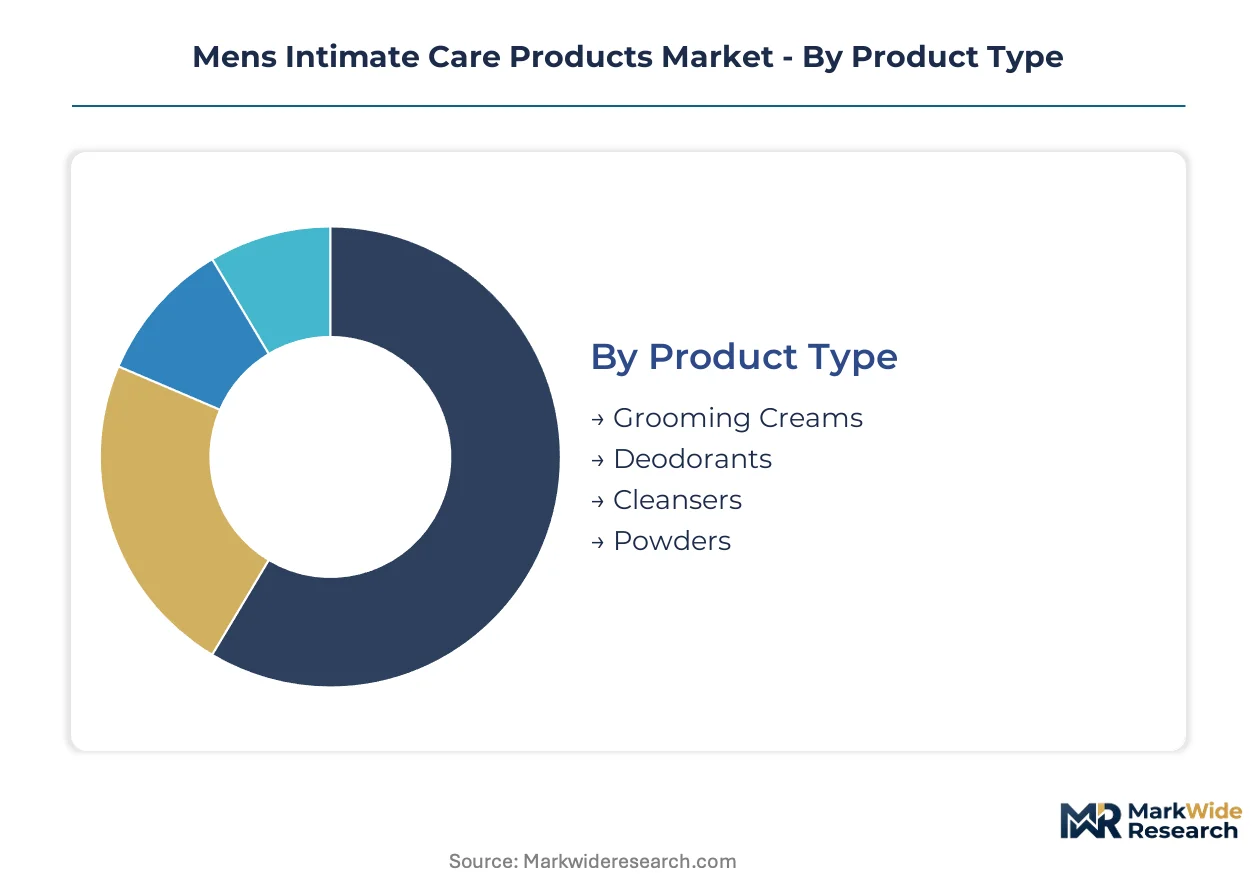
Segmentation in men's intimate care reveals how formulation sophistication and channel access determine margin capture. Distinct user routines across athletic, professional, and daily contexts create parallel demand curves that reward specialized positioning over mass-market commoditization.
Product Type:
After-sales service intensity runs highest for formulations requiring dermatological consultation or subscription replenishment, locking users into recurring revenue architectures.
- Grooming Creams:Emulsion-based formulations incorporating pH-balanced surfactants and soothing actives for pre- and post-hair removal care. Demand concentrates among professionals in the United States who integrate these into pre-work grooming protocols, with workplace appearance standards tightening irritation tolerance thresholds. These products command the deepest margin pools as consumers trade up from basic bar soap.
- Deodorants:Aerosol and stick formats utilizing potassium alum and zinc ricinoleate alternatives to aluminum salts under FDA and EU cosmetic safety scrutiny. Athletes in collegiate and professional sports programs drive daily-use frequency expansion beyond traditional morning-only application patterns.
- Cleansers:Liquid and foam wash systems engineered for genital and perineal hygiene with antimicrobial actives.
- Powders:Talc-free moisture-absorbing bases using cornstarch and silica derivatives for friction reduction.
Grooming creams hold the largest share; momentum sits with deodorants as reformulation cycles accelerate.
Application:
Cost tier differentiation separates premium dermatologically-tested formulations from mass-market alternatives, with professional users absorbing price premiums for irritation-free credentials.
- Daily Care:Routine maintenance formulations emphasizing microbiome balance through prebiotic fiber complexes and postbiotic lysates. Professionals in healthcare and corporate environments in Germany adopt these fastest, integrating them into pre-work and post-shift hygiene protocols. The shift compresses legacy antiseptic product lifecycles.
- Odor Control:Targeted antimicrobial systems replacing broad-spectrum approaches with selective bacterial balance maintenance. Post-gym intimate care routines normalize among athletes, expanding application frequency and subscription attachment rates.
- Pre-Shave:Softening and lubricating preparations for hair removal optimization.
- Post-Shave:Soothing and repair formulations addressing irritation and microtrauma.
Daily care commands volume leadership; odor control gains share fastest among subscription commerce adopters.
End User:
Customer type stratification reveals how occupational context shapes formulation requirements and price elasticity, with workplace-driven users showing lowest sensitivity to premium positioning.
- Professionals:Workplace-appearance-conscious users prioritizing dermatological testing credentials and irritation-free daily routines. This segment in the United States and Germany absorbs premium pricing as corporate grooming standards tighten, with telemedicine platforms integrating recommendations into post-consultation engines.
- Athletes:Collegiate and professional sports participants normalizing post-gym intimate care protocols. Post-gym and pre-work routine integration in the United States establishes habit formation that locks in recurring purchase patterns.
- Men:General adult male consumers across demographic ranges.
- Teenagers:Entry-level users developing initial category habits and brand loyalties.
Professionals represent the largest addressable base; athletes climb the fastest as sports program adoption spreads.
Distribution Channel:
Supply concentration in German specialty chemical houses for dermocosmetic-grade emulsifiers shapes which channels can sustain formulation credibility at scale.
- Online Retailers:Direct-to-consumer platforms and subscription services capturing disproportionate growth through bundled intimate care and adjacent grooming categories. Digital-native brands in the United States leverage reduced price transparency and habit-formation mechanics to displace single-product pharmacy purchases.
- Pharmacies:German and French pharmacy channels where EU REACH restrictions on fragrance allergens reward incumbents with established toxicology dossiers, eliminating unbranded competitors through compliance cost barriers.
- Supermarkets:Mass-market shelf-space competition dominated by volume leaders with legacy supply chain infrastructure.
- Specialty Stores:Curated retail environments emphasizing men's grooming sub-brand credibility and formulation storytelling.
Online retailers are expanding most quickly; pharmacies retain the highest margin per transaction through credential-dependent purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's distribution dominance for dermocosmetic-grade emulsifiers feeding formulation houses across Western Europe. India's Jawaharlal Nehru Port Trust channels personal care raw materials into Maharashtra's manufacturing belt. The United States' interstate highway network enables direct-to-consumer fulfillment velocities that subscription models require.
United States
Telemedicine platforms integrate intimate care recommendations into post-consultation engines, bypassing traditional retail gatekeepers. FDA cosmetic labeling requirements elevate compliance costs for new entrants while rewarding incumbents with established toxicology dossiers. Subscription commerce clusters in Austin and Brooklyn leverage reduced price transparency to lock in recurring revenue from professionals.
Germany
EU REACH restrictions on fragrance allergens eliminate unbranded competitors from pharmacy channels through compliance cost barriers. The EU Green Deal's packaging waste directives force reformulation toward concentrated formats and refillable dispensers. Düsseldorf and Hamburg host formulation R&D centers where dermatological testing credentials function as table stakes.
India
BIS quality standards for personal care imports tighten market access for white-label suppliers, rewarding early movers with local manufacturing. Tier-2 cities in Maharashtra and Karnataka develop specialized men's personal care retail fixtures. Mumbai's pharmaceutical corridor attracts joint ventures seeking pre-emptive compliance positioning before full enforcement.
France
ANSM oversight of cosmetic safety dossiers creates credential-dependent purchasing patterns in Parisian pharmacy networks. Retailers demand proof of packaging reduction roadmaps before contract renewal under EU Green Deal mandates. Lyon houses microbiome-conscious formulation labs serving professional demographic penetration.
United Kingdom
Post-Brexit divergence from EU REACH frameworks reshapes portfolio prioritization for manufacturers serving both markets. London's direct-to-consumer brands bundle intimate care with adjacent grooming categories, displacing single-product purchases. The Southeast corridor concentrates subscription fulfillment infrastructure for athletic end-user acquisition.
Mens Intimate Care Products Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in emulsifier and active ingredient supply. The vendor base organizes around three tiers: multinational CPG conglomerates with shelf-space dominance, mid-cap dermocosmetic houses with dermatological credibility, and digital-native subscription brands with direct consumer relationships. Dominant competitive moves include portfolio diversification into adjacent grooming categories and backward integration into captive emulsifier supply.
Within the multinational tier, Procter & Gamble Company and Unilever PLC occupy positions anchored by supermarket distribution infrastructure and men's grooming sub-brand architectures. Beiersdorf AG exemplifies the dermatological-credibility archetype through specialized testing protocols. These three entities represent distinct strategic postures: volume leadership through retail gatekeeper capture, formulation credibility competition, and irritation-free daily care positioning respectively.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Church & Dwight |
| Procter & Gamble Company |
| Edgewell Personal Care |
| Coty Inc. |
| Unilever PLC |
| L'Oréal S.A. |
| Kimberly-Clark Corporation |
| Beiersdorf AG |
| Others |
Value Chain & Pricing Dynamics
German specialty chemical houses controlling dermocosmetic-grade emulsifier production concentrate upstream margin capture, with three mid-cap suppliers dictating input pricing that cascades into finished product tiering across subscription and pharmacy channels.
Pricing Analysis
Volume-discount tiering structures separate dermatologically-tested premium formulations from mass-market alternatives, with certification grade and after-sales bundling as primary price differentiation drivers. Cost compression in the aluminum-free deodorant tier intensifies as potassium alum and zinc ricinoleate substitution raises raw material inputs. Professionals in corporate healthcare environments show lowest price sensitivity, absorbing premiums for irritation-free credentials, while general male consumers comparison-shop across mass-market platforms.
Supply Chain Analysis
Contract-manufacturing concentration sits with mid-cap dermocosmetic houses in Germany and France, alongside toll manufacturers in India's Maharashtra belt serving local joint ventures. Formulation chemistry draws from cornstarch and silica derivatives for talc-free powders, prebiotic fiber complexes, and postbiotic lysates for microbiome-conscious lines. Single-source vulnerability runs through German emulsifier suppliers, with distribution running through direct-to-consumer fulfillment networks in the United States and pharmacy wholesale in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs through this market as microbiome-conscious formulation science splits demand curves between legacy antiseptic users and selective bacterial balance adopters, creating parallel niche architectures.
For Market Incumbents: Pre-empt subscription commerce displacement by capturing direct-to-consumer fulfillment infrastructure before digital-native brands consolidate habit-formation mechanics. Backward integration into captive emulsifier supply hedges against German specialty chemical house bottleneck risk. Dermatological testing credential investment locks in professional demographic pricing power as workplace appearance standards tighten. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 cities before BIS quality standards full enforcement eliminates white-label import pathways. Local manufacturing joint ventures in Maharashtra and Karnataka bypass tightening personal care import barriers. Telemedicine platform partnership in the United States offers go-to-market angle through post-consultation recommendation engine integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dermocosmetic houses holding dermatological credibility but lacking direct-to-consumer subscription mechanics. Five-to-ten year viability frames around microbiome-compatible active patent estates and refillable dispenser reverse logistics infrastructure. Signal to watch is EU Green Deal packaging waste directive compliance roadmap submission rates ahead of retailer contract renewal cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome-Compatible Formulation Patent Estate | Prebiotic fiber complex IP locks in professional demographic switching costs against legacy antiseptic competitors. |
| Refillable Dispenser Reverse Logistics Network | EU Green Deal compliance positions brands for German and French pharmacy channel contract renewals. |
| Telemedicine Platform Integration | Post-consultation recommendation engines in the United States bypass traditional retail gatekeeper capture costs. |
| Local Manufacturing Joint Venture in India | Maharashtra-based production preempts BIS quality standard enforcement against white-label import competitors. |
| Dermatological Testing Credential Expansion | Irritation-free certification investment captures workplace-appearance-conscious professional premium pricing. |
Study Parameters
Operator-level perspectives from formulation chemists, pharmacy category buyers, subscription commerce operations directors, and dermatology clinic procurement managers anchored the qualitative base. Primary interview findings triangulated against FDA cosmetic labeling guidance documents, EU REACH fragrance allergen restriction filings, BIS personal care import quality circulars, and Nielsen retail audit data. Bottom-up unit economics modeling and top-down category sizing approaches converged on volume and value estimates.
Scenario-bracketing framed analytical development across the projection horizon, with segmentation dimensions spanning product type, application context, end-user occupational category, and distribution channel architecture. CAGRs derived from adoption curve modeling for microbiome-conscious formulations and subscription commerce penetration rates. Aluminum salt substitution cost trajectories and EU packaging waste directive compliance timelines served as industry-specific forecast inputs.
Stress conditions across emulsifier supply concentration, natural preservative shelf stability limitations, and regulatory divergence between FDA cosmetic frameworks and EU REACH dossier requirements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding professional workplace grooming standard adoption velocity and athletic program intimate care protocol normalization. Quarterly review of subscription commerce churn rates, pharmacy channel compliance certification submission volumes, and Indian joint venture formation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
Australia Facial Care Market
Beauty & Personal Care
Hair Removal Products Market
Beauty & Personal Care
Aluminium-Free Deodorants Market
Beauty & Personal Care
Canada Dermocosmetics Market
Beauty & Personal Care
Electric Nail Files Market
Beauty & Personal Care
Spas and Beauty Salons Market
Beauty & Personal Care
Luxury Bath and Body Products Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Cosmetic Serum Market
Beauty & Personal Care
Europe Shampoo Market
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
Global Beauty and Personal Care Products Market
Beauty & Personal Care
Mass Beauty & Personal Care Products Market