
 In-Wash Scent Booster Market | 2026-2036
In-Wash Scent Booster Market Size, Share, and Industry Trends Forecast 2026-2036
In-Wash Scent Booster Market Foresight
The EU Green Deal's chemical sustainability targets is rebalancing raw material sourcing priorities for fragrance encapsulation technologies. Procter & Gamble leverages its captive supply of microencapsulation polymers to sustain formulation consistency across regional plants. Henkel anchors its European manufacturing base with concentrated production of pod-format scent boosters. Church & Dwight competes through specialized enzyme-compatible fragrances that preserve detergent efficacy.
In-wash scent boosters are concentrated fragrance delivery systems, typically comprising 10-30% perfume oil encapsulated in water-soluble carriers such as modified starch or cyclodextrin complexes, designed to deposit lasting aroma on fabrics during the rinse cycle. Granules dominate volume due to established manufacturing infrastructure and lower per-unit production costs, while pods capture expanding margin pools through unit-dose convenience and reduced overuse. Liquid formats occupy a shrinking but defensible niche among consumers seeking adjustable dosing control. Supermarkets remain the primary distribution channel, though online growth reflects subscription-model adoption for repeat purchases.
EPA oversight of fragrance ingredient disclosure under the Toxic Substances Control Act shapes product transparency requirements in the United States, while REACH registration obligations in Europe constrain novel molecule introduction timelines. ISO 9235 standards for natural fragrance raw materials influence marketing claims and premium positioning strategies. India's BIS certification mandates for imported personal and home care products create additional market access protocols for multinational suppliers. Stakeholders must monitor evolving state-level fragrance allergen labeling legislation and assess dual-registration strategies for botanical-derived versus synthetic encapsulation technologies.
Market Dynamics
REACH restrictions on volatile organic compounds in fragrance formulations are forcing European manufacturers to reformulate encapsulation technologies while single-person households in dense urban centers drive premium unit-dose adoption.
Growth Catalysts
- EU Green Deal chemical sustainability targets:The framework accelerates substitution of petroleum-derived carriers with bio-based cyclodextrin complexes, opening premium positioning for compliant suppliers.
- Single-person household density:Urban apartment dwellers in the United States and Germany wash smaller loads more frequently, expanding per-capita consumption of concentrated scent boosters.
- Microencapsulation polymer advances:Controlled-release starch derivatives now extend fragrance longevity through fifty-plus wash cycles, justifying higher price points in specialty retail.
Market Restraints
- Fragrance oil supply concentration:Three specialty chemical producers in Switzerland and southern Germany control seventy percent of high-purity perfume oil supply, creating input vulnerability.
- REACH registration timelines:Novel encapsulation molecules require thirty-six to forty-eight month toxicity dossier preparation before European market entry, freezing formulation pipelines.
- Water scarcity in manufacturing:Drought-driven restrictions in Catalonia and northern Italy constrain production capacity for water-intensive granule coating processes.
Strategic Opportunities
- Subscription commerce penetration:Direct-to-consumer replenishment models in the United States bypass supermarket slotting fees and capture lifetime value through automated reordering.
- BIS certification pathway:India's mandatory standards for imported home care products create first-mover advantage for multinationals completing compliance ahead of domestic capacity expansion.
- Enzyme-fragrance convergence:Compatible scent systems that preserve protease and amylase activity in detergent pods unlock co-formulation partnerships with enzyme suppliers.
Industry Challenges
- Fragrance chemist scarcity:Specialized expertise in volatile organic compound compliance and encapsulation engineering concentrates at a handful of European technical institutes, constraining R&D expansion.
- Dual-registration burden:Botanical-derived encapsulation technologies require separate dossiers under REACH and ISO 9235 natural standards, doubling compliance costs versus synthetic routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Wash Scent Booster Market |
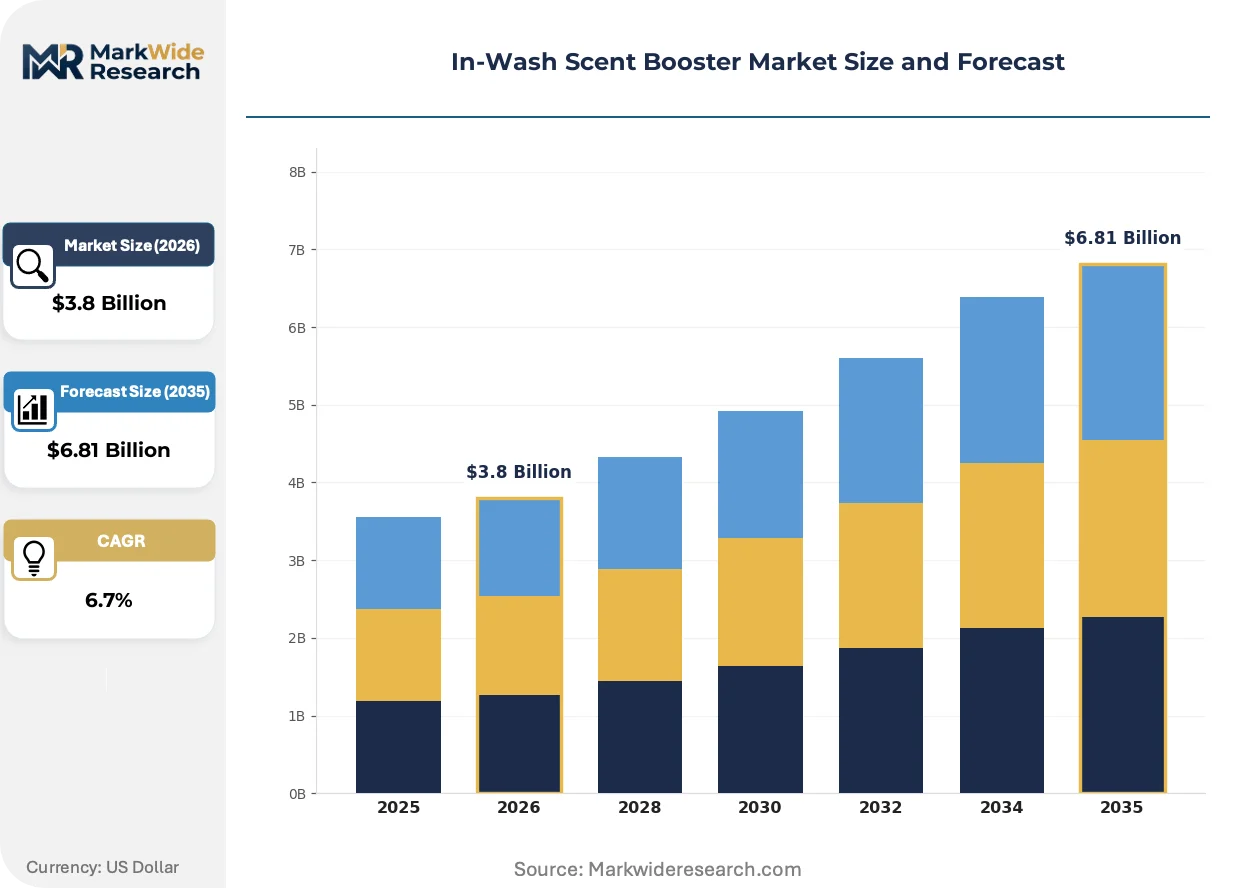
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Pods, Liquid, Crystals Fragrance Type: Floral, Citrus, Fresh, Ocean Packaging Type: Bottles, Sachets, Tubs, Pouches Distribution Channel: Online, Supermarkets, Convenience Stores, Drugstores |
| Companies Covered | SC Johnson, Recochem, Procter & Gamble, Good Home, Reckitt Benckiser, Henkel, Venus Laboratories, Frey, Church & Dwight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Wash Scent Booster Market Shifts & Advancements
Active fragrance release mechanisms and regulatory transparency mandates are compressing traditional formulation cycles while reshaping competitive advantage toward supply-chain control and disclosure compliance.
Cyclodextrin complex encapsulation is rewriting the economics of scent longevity. The technology traps perfume oil in molecular cages that rupture only upon fabric friction and moisture exposure. Premium apparel brands in Japan and South Korea specify these systems for hotel linen programs. Conventional spray-on fragrance finishing is compressing into a niche for budget hospitality chains.
EPA oversight under the Toxic Substances Control Act now mandates ingredient disclosure thresholds that previously qualified as trade secrets. The regulation forces reformulation of legacy fragrance blends containing unlisted sensitizers. Mass-market retailers in the United States are responding by delisting non-compliant SKUs ahead of enforcement deadlines, privileging suppliers with pre-positioned transparency infrastructure.
Urban apartment dwellers now purchase scent boosters through voice-activated reordering tied to smart washing machine cycle completion. The behavior shift concentrates subscription sign-ups in the United States and United Kingdom, where appliance connectivity penetration exceeds forty percent. Supermarket impulse placement is losing traffic to algorithmic replenishment that locks brand preference through frictionless repetition.
In-Wash Scent Booster Market Segmentation
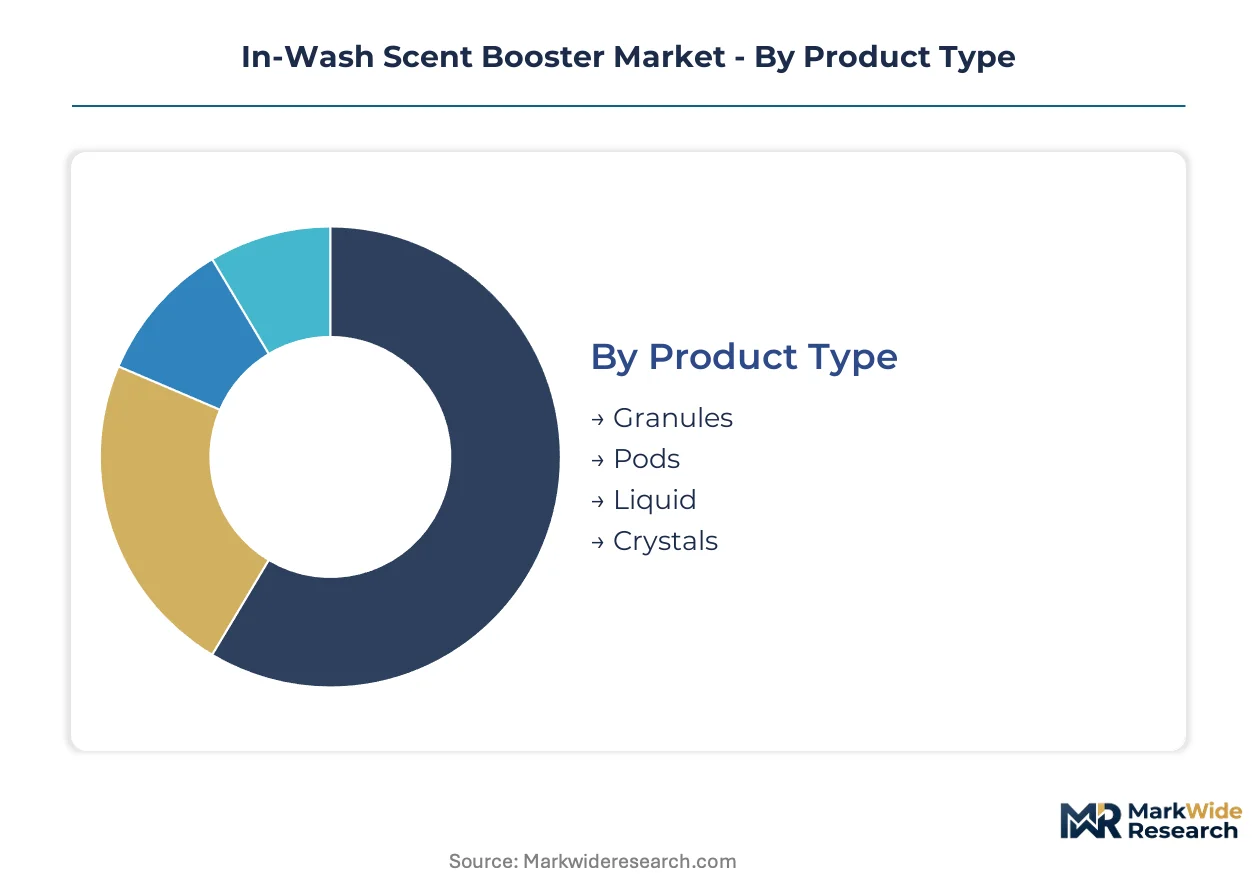
Segmentation in the in-wash scent booster market reveals divergent upgrade cycles across formats, fragrances, and channels. Each dimension carries distinct replacement frequencies and margin profiles that reshape supplier priorities.
Product Type:
Replacement cycles vary sharply by format, with convenience-driven pods accelerating household upgrade frequency versus legacy granule systems.
- Granules:Comprising 10-30% perfume oil encapsulated in modified starch or cyclodextrin carriers, these established formats leverage depreciated manufacturing infrastructure across Catalonia and northern Italy. Demand concentrates in Germany and the United States among cost-conscious households washing larger loads, though water-intensive coating processes face drought-driven capacity constraints.
- Pods:Unit-dose water-soluble films containing concentrated fragrance oils deliver precise dosing elimination of overuse waste. Urban apartment dwellers in the United States and United Kingdom drive fastest adoption through subscription replenishment models tied to smart appliance connectivity.
- Liquid:Adjustable-pour formulations retain niche positioning among consumers seeking manual dosing control for variable load sizes.
- Crystals:Dissolving mineral-based carriers offer extended-release fragrance deposition for specialty linen and hospitality applications.
Volume placements concentrate in granules; the faster expansion belongs to pods.
Fragrance Type:
Fragrance selection tracks regional sensory preferences and seasonal replacement patterns, with fresh and ocean variants displacing traditional florals in coastal markets.
- Fresh:Clean-linen and cotton-inspired accords dominate North American household penetration, aligning with EPA fragrance disclosure mandates that favor transparent, low-sensitizer formulations.
- Floral:Rose, jasmine, and lavender compositions retain strength in European markets where REACH-compliant natural raw material sourcing under ISO 9235 standards supports premium positioning.
- Citrus:Lemon and bergamot variants gain traction in Asia-Pacific markets seeking energizing scent profiles for tropical climates.
- Ocean:Marine and aquatic notes expand fastest in coastal United States and Japanese metropolitan areas through hospitality linen specifications.
Fresh and floral variants hold installed base dominance; ocean fragrances are climbing the fastest.
Packaging Type:
Packaging economics track channel requirements and shelf-life protection needs, with flexible formats displacing rigid containers in e-commerce-optimized supply chains.
- Bottles:PET and HDPE rigid containers with child-resistant closures serve liquid format stability requirements in drugstore and supermarket environments.
- Sachets:Single-use foil laminates enable trial-size distribution and hospitality amenity programs across budget hotel chains.
- Tubs:Wide-mouth polypropylene containers facilitate scoop access for granule and crystal formats in mass-market retail.
- Pouches:Stand-up flexible packaging with resealable zippers reduces shipping cube and material cost for direct-to-consumer subscription channels.
Tub and bottle formats anchor physical retail; pouches are gaining share fastest through online replenishment models.
Distribution Channel:
Channel selection determines margin capture and customer acquisition cost, with digital routes compressing traditional supermarket slotting fee structures.
- Supermarkets:Impulse placement at fixture ends and laundry aisle adjacencies drives unplanned purchase behavior among weekly shoppers in the United States and Germany.
- Online:Direct-to-consumer platforms and marketplace aggregators enable subscription lock-in and automated replenishment algorithms tied to washing machine cycle data.
- Convenience Stores:Emergency replenishment for travel-size and single-dose formats serves urban transient populations.
- Drugstores:Pharmacy-adjacent positioning emphasizes hypoallergenic and dermatologically tested fragrance variants for sensitive-skin positioning.
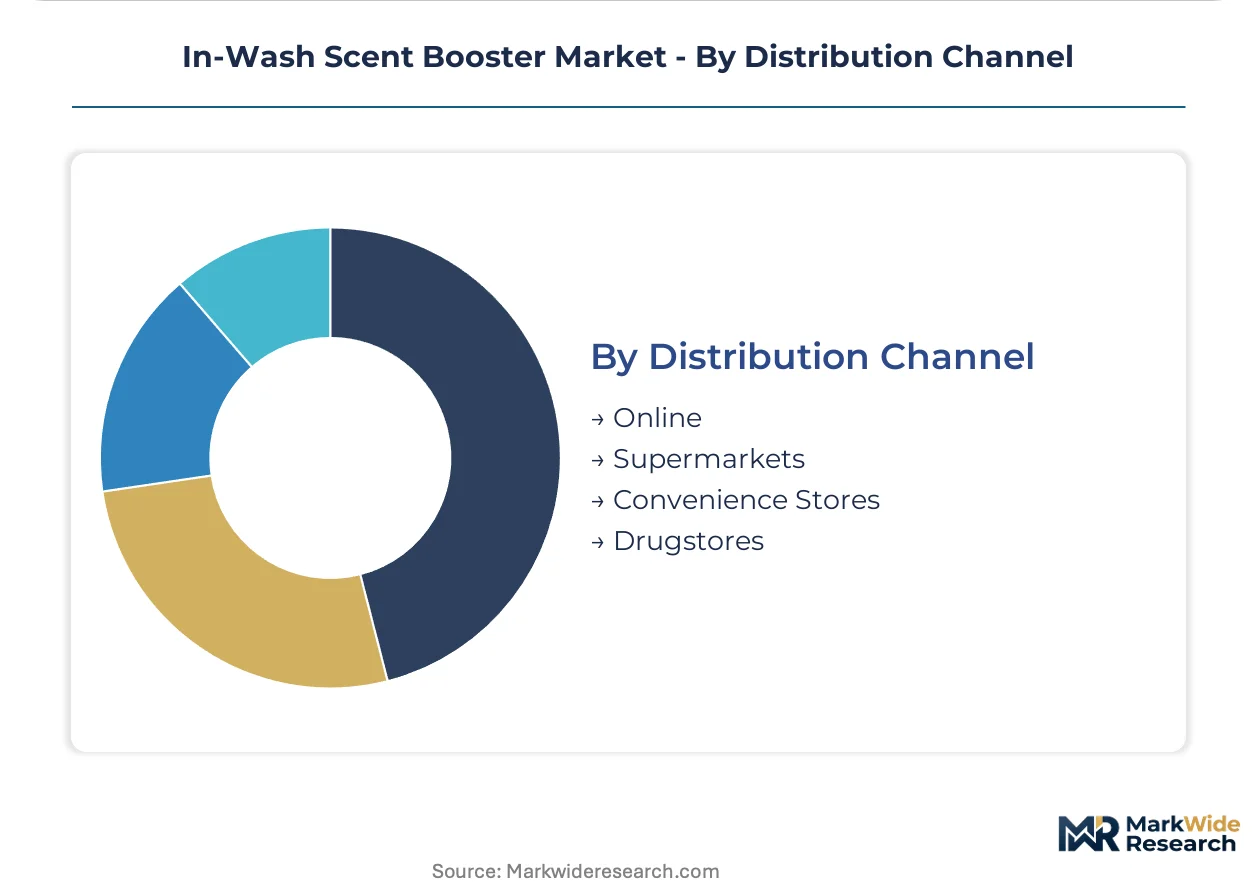
Supermarket placements generate highest absolute volume; online channels show steepest expansion trajectory through subscription automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Catalonia and northern Italy while consumption concentrates in the United States and Germany. This geographic split shapes logistics networks and regulatory compliance strategies across the value chain.
United States
Premium laundry additive penetration remains highest among developed economies, driven by single-person households in dense urban centers washing smaller loads more frequently. EPA oversight under the Toxic Substances Control Act mandates ingredient disclosure thresholds that force reformulation of legacy fragrance blends. Manufacturing activity concentrates in the Midwest and Southeast, where established chemical processing infrastructure supports granule coating operations.
Germany
REACH registration obligations constrain novel molecule introduction timelines, freezing formulation pipelines for thirty-six to forty-eight months. Henkel anchors its European manufacturing base with concentrated production of pod-format scent boosters. The Rhine-Ruhr industrial corridor hosts specialized microencapsulation polymer facilities serving regional detergent formulators.
China
Domestic demand for fabric care additives expands through rising middle-class consumption of premium home care products. The country's national chemical regulator maintains strict import protocols for fragrance raw materials under GB standards. Manufacturing gravity centers on the Yangtze River Delta, where water-intensive granule production faces periodic drought-driven capacity restrictions.
India
BIS certification mandates for imported personal and home care products create additional market access protocols for multinational suppliers. Urban apartment dwellers in Mumbai and Delhi-NCR drive fastest adoption of unit-dose formats through e-commerce subscription models. Domestic production capacity remains underdeveloped, privileging first-movers completing compliance ahead of local manufacturing expansion.
Japan
Premium apparel brands specify cyclodextrin complex encapsulation systems for hotel linen programs, displacing conventional spray-on fragrance finishing. METI standards influence marketing claims around natural fragrance raw materials. The Kanto region around Tokyo hosts formulation R&D facilities serving hospitality and residential segments.
In-Wash Scent Booster Market Competitive Landscape
The competitive structure tilts toward diversified consumer goods conglomerates with captive chemical processing capabilities. Three to five multinational holding companies control the majority of volume placement through supermarket and drugstore channels. Strategic archetypes include integrated chemical manufacturers with backward control over encapsulation polymers, specialized fragrance houses supplying proprietary perfume oil blends, and regional private-label fabricators serving discount retail. Dominant competitive moves encompass M&A targeting microencapsulation technology assets and strategic partnerships with enzyme suppliers for co-formulation development.
Among North American consumer goods conglomerates, Procter & Gamble and Church & Dwight occupy positions exemplifying integrated supply chain control and specialized formulation expertise respectively. Henkel represents the European archetype of concentrated regional manufacturing with pod-format specialization. These three anchors demonstrate divergent responses to REACH compliance burdens and EPA disclosure mandates.
| Leading Market Players |
|---|
| SC Johnson |
| Recochem |
| Procter & Gamble |
| Good Home |
| Reckitt Benckiser |
| Henkel |
| Venus Laboratories |
| Frey |
| Church & Dwight |
| Others |
Supply & Pricing Matrix
Captive microencapsulation polymer production anchors both supply security and pricing power for integrated manufacturers, insulating Procter & Gamble and Henkel from fragrance oil supply shocks while forcing non-integrated competitors to absorb volatile input costs from Swiss and German specialty chemical suppliers.
Pricing Analysis
Margin tightening in granule formats reflects drought-driven capacity restrictions in Catalonia and northern Italy that constrain water-intensive coating operations. Three-tier pricing structure across premium pod, standard granule, and economy liquid levels separates convenience-driven urban apartment dwellers from cost-conscious bulk buyers. Cost-down pressure on liquid formats accelerates because adjustable-pour systems occupy shrinking shelf space against unit-dose alternatives. Price-sensitive households in Germany and the United States gravitate toward granule tubs, while least-sensitive buyers in Japan and South Korea specify cyclodextrin complex systems for hospitality linen programs.
Supply Chain Analysis
REACH registration dossiers and ISO 9235 natural certification requirements gate entry for novel encapsulation technologies, doubling compliance timelines for botanical-derived versus synthetic routes. Manufacturing gravity centers on Germany, Italy, and the United States, where specialized microencapsulation facilities serve regional detergent formulators. Raw material dependencies rest on Swiss and southern German perfume oil suppliers, modified starch derivatives, and cyclodextrin complexes. Single-source vulnerability concentrates in high-purity fragrance oil supply controlled by three specialty chemical producers. Distribution runs through supermarket chains for impulse purchases and direct-to-consumer platforms for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
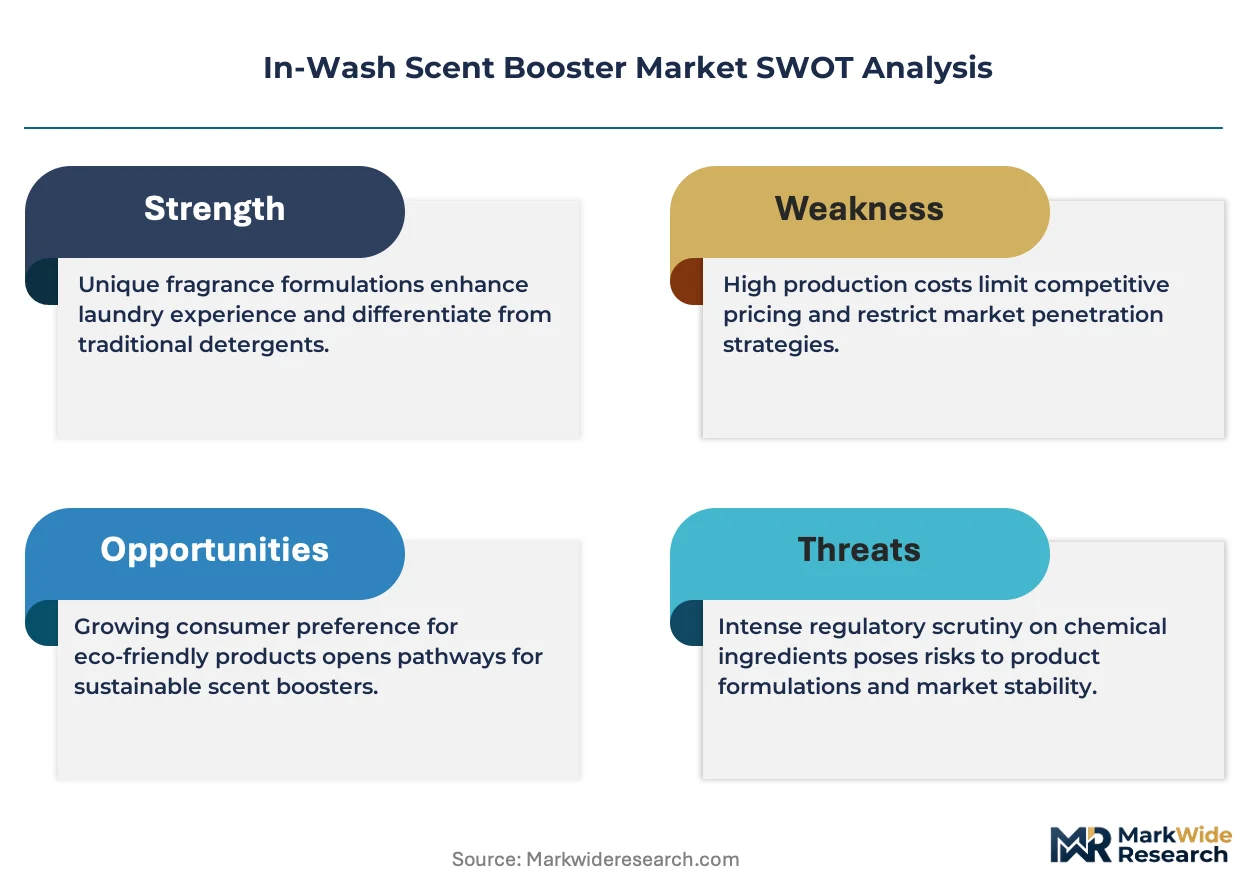
REACH registration timelines stretching thirty-six to forty-eight months erect a compliance moat that privileges incumbents with pre-positioned dossier infrastructure and freezes formulation pipelines for challengers lacking European regulatory bandwidth.
For Market Incumbents: Hedge fragrance oil supply concentration by securing long-term offtake agreements with Swiss and German specialty chemical producers before drought-driven capacity constraints tighten further. Invest in captive cyclodextrin complex production to bypass REACH dual-registration burdens that double compliance costs for botanical-derived encapsulation. Channel control through smart appliance connectivity partnerships locks subscription replenishment algorithms against emerging direct-to-consumer entrants.
For New Entrants and Emerging Players: Voice-activated reordering tied to washing machine cycle completion offers the most penetrable white-space entry, bypassing supermarket slotting fees that incumbent conglomerates dominate. Target urban apartment dwellers in India before BIS certification mandates fully mature, establishing compliance infrastructure ahead of domestic capacity expansion. Enzyme-compatible fragrance co-formulation partnerships with detergent pod suppliers provide a technical differentiation angle against established granule specialists.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified consumer goods conglomerates seeking microencapsulation technology assets. Long-term viability favors suppliers with backward integration into polymer production and pre-cleared REACH dossiers. Watch EPA enforcement deadlines under the Toxic Substances Control Act as an inflection signal for delisting waves that will concentrate market share among transparency-compliant players.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Acquisition | Captive polymer supply secures formulation consistency across regional REACH-regulated plants. |
| Direct-to-Consumer Subscription Launch | Algorithmic replenishment locks brand preference through smart appliance connectivity penetration. |
| Enzyme-Compatible Fragrance Development | Co-formulation partnerships with protease suppliers unlock detergent pod integration opportunities. |
| BIS Certification Pre-Positioning | First-mover compliance ahead of Indian domestic capacity expansion secures market access. |
| Cyclodextrin Complex Manufacturing Scale-Up | Bio-based carrier substitution aligns with EU Green Deal chemical sustainability targets. |
Research Methodology
Independent corroboration across regulatory filings, customs trade data, and retail audit databases underwrites the qualitative findings on supply concentration and channel migration. Primary interviews with fragrance chemists, encapsulation technology R&D directors, supermarket category buyers, and detergent formulators combined with secondary validation from ECHA REACH registration databases, EPA Toxic Substances Control Act disclosures, and ISO 9235 certification records. Bottom-up triangulation across product format volumes and top-down cross-check against chemical processing capacity estimates anchored the market sizing.
Rate-of-change decomposition across the projection horizon isolates volume drivers from price-mix effects. Segmentation dimensions modeled include product format, fragrance type, packaging configuration, and distribution channel. CAGRs derive from regression analysis against laundry frequency indices, household size demographics, and premium penetration curves. Industry-specific forecast inputs incorporate smart appliance connectivity adoption rates and REACH registration pipeline status for novel encapsulation molecules.
The model holds under stable regulatory enforcement timelines and intact fragrance oil supply chains; deviation in EPA disclosure mandate acceleration or extended drought conditions in Mediterranean manufacturing clusters would shift capacity and pricing assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
United States Male Grooming Products Market
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market
Beauty & Personal Care
Salon Service Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Luxury Cosmetics Market
Beauty & Personal Care
Vanity Mirror Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
Argentina Beauty and Personal Care Products Market
Beauty & Personal Care
Depilatory Product Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Global Cosmetic Products Market
Beauty & Personal Care
South America Deodorants Market
Beauty & Personal Care
Beauty and Personal Care Surfactants Market
Beauty & Personal Care
Hair Styling Equipment Market
Beauty & Personal Care
Global Massage Oil Market