
 Indonesia Used Car Financing Market | 2026-2036
Indonesia Used Car Financing Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Used Car Financing Market Foresight
Indonesian captive finance subsidiaries is restructuring origination workflows to absorb rising volumes from second-hand vehicle transactions. Bussan Auto Finance leverages its motorcycle-lending heritage to anchor motorcycle-to-car cross-sell pipelines across tier-two cities. Oto Multiartha sustains a branch-dense network that dominates physical credit assessment in Central and East Java. Adira Dinamika Multi Finance differentiates through used-car certification partnerships that reduce default risk on older vehicle collateral.
Used car financing encompasses secured credit instruments collateralized by pre-owned vehicles, typically requiring appraisal of chassis integrity, odometer verification, and residual-value modeling against depreciation curves. The primary commercial purpose channels liquidity to borrowers excluded from new-car credit tiers while generating interest-income spreads for non-bank financial companies. Bank loans occupy the largest share of financing-type volumes due to lower cost-of-funds, yet peer-to-peer lending registers the fastest structural ascent as fintech platforms embed AI-driven credit scoring. Fleet owners represent a concentrated margin pool within customer-type segmentation because bulk origination reduces per-unit acquisition costs and servicing overhead.
OJK mandates shape product architecture through down-payment floors and transparent annual-percentage-rate disclosures that constrain predatory structuring. Bank Indonesia macroprudential rules on loan-to-value ratios directly throttle credit availability during tightening cycles, filtering demand toward regulated non-bank lenders with flexible underwriting. Stakeholders must monitor OJK digital-lending licensing enforcement and the trajectory of BI rate adjustments as decisive variables for portfolio yield and delinquency trajectory.
Market Dynamics
OJK's 2024 down-payment floor adjustments and APR disclosure mandates are compressing origination margins while redirecting volume toward non-bank financial companies with flexible underwriting engines. This regulatory pivot is the dominant structural force reshaping competitive positioning across Java's urban corridors.
Growth Catalysts
- Digitized Credit Scoring:AI-driven risk models embedded in mobile platforms now enable real-time borrower assessment for ride-hailing drivers in Jakarta and Surabaya, collapsing traditional branch-based timelines.
- OJK Licensing Framework:The Financial Services Authority's streamlined digital-lending permits have reduced barriers for fintech entrants, accelerating credit penetration among previously unbanked used-car purchasers.
- Motorcycle-to-Car Migration:Tier-two city borrowers graduating from two-wheeler financing represent a captive pipeline, with established motorcycle lenders leveraging existing payment histories for cross-sell conversion.
Market Restraints
- Bank Indonesia LTV Caps:Macroprudential loan-to-value ratio tightening during rate-hike cycles directly throttles conventional bank credit availability, forcing demand toward higher-cost non-bank channels.
- Depreciation Curve Uncertainty:Residual-value modeling for older vehicle collateral suffers from sparse transaction data in secondary markets outside Java, elevating collateral risk premiums.
- Fossil Fuel Price Volatility:Subsidy fluctuations for Pertalite and Pertamax directly impact driver-operators' debt-service capacity, injecting payment delinquency risk into fleet-owner portfolios.
Strategic Opportunities
- Sumatra and Sulawesi Penetration:Credit density in Medan and Makassar remains substantially below Javan levels, offering first-mover advantages for platforms with localized collection infrastructure.
- Embedded Fleet Telematics:Convergence of GPS tracking with payment systems enables usage-based underwriting and dynamic repossession triggers, reducing loss-given-default for commercial vehicle pools.
- BI Rate Cycle Positioning:Anticipated central bank easing would compress funding costs for non-bank lenders, creating margin expansion windows before rate transmission to retail borrowers.
Industry Challenges
- Field Appraiser Shortage:Chassis integrity verification and odometer fraud detection require trained assessors, yet certification programs in Central and East Java produce insufficient pipeline to match origination velocity.
- Legacy Core Integration:Established non-bank financial companies face friction merging digital onboarding workflows with decades-old loan servicing systems, delaying real-time payment processing deployment.
- Repossession Legal Timelines:Indonesian civil procedure constraints extend collateral recovery cycles, inflating carrying costs and complicating loss-forecasting accuracy for securitized portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Used Car Financing Market |
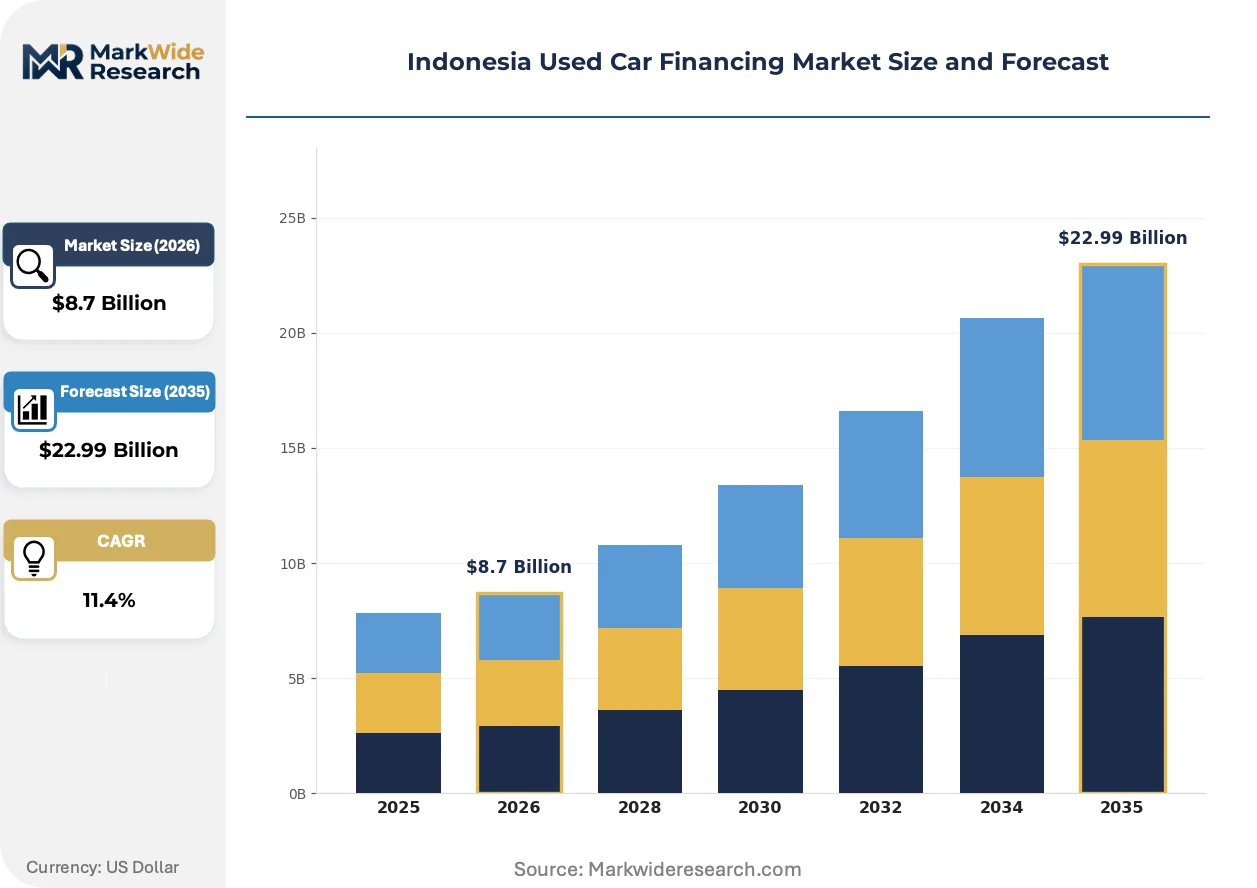
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Type: Bank Loans, Credit Unions, Peer-to-Peer Lending, Private Financing Customer Type: First-Time Buyers, Repeat Buyers, Fleet Owners, Individual Sellers Vehicle Type: SUVs, Sedans, Hatchbacks, Trucks Loan Duration: Short-Term Loans, Medium-Term Loans, Long-Term Loans, Flexible Financing |
| Companies Covered | Bussan Auto Finance, Oto Multiartha, PT Toyota Astra Financial Services, Adira Dinamika Multi Finance, PT JACCS Mitra Pinasthika Mustika Finance Indonesia (MPM Finance), Astra Credit Companies (ACC), Dipo Star Finance, Mandiri Tunas Finance, BFI Finance Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Used Car Financing Market Shifts & Advancements
Technology convergence and regulatory transparency mandates are compressing traditional origination advantages while elevating data-centric underwriting models. These forces are redistributing market share from branch-heavy incumbents toward algorithm-native entrants.
Machine-learning credit scoring is rewriting how risk is priced in used-car portfolios. Fintech platforms deploy alternative data streams—mobile wallet histories, ride-hailing earnings patterns, and utility payment records—to assess borrowers excluded from conventional bureau files. Adoption concentrates among gig-economy drivers in Greater Jakarta, where thin-file applicants now access financing within hours rather than weeks. This compression of assessment timelines is rewriting competitive dynamics, forcing established players to retrofit legacy decision engines or cede originations to digital-native rivals.
OJK's mandatory annual-percentage-rate disclosure rules now require standardized total-cost-of-credit presentations across all promotional materials. The regulation eliminates hidden fee structures that previously obscured true borrowing costs, particularly in dealer-arranged financing. Non-bank lenders with simpler product architectures gain comparative clarity advantages, while multi-fee competitors face restructuring pressure. Compliance investment is heaviest among branch-dense networks with decentralized marketing execution.
Ride-hailing drivers are consolidating vehicle procurement through fleet aggregator arrangements rather than individual credit applications. Aggregators negotiate bulk financing terms with lenders, then sublease vehicles to drivers under revenue-sharing contracts. This channel shift displaces direct-to-driver originations and concentrates counterparty risk with a smaller pool of fleet operators. The pattern is most visible in Surabaya and Bandung, where platform-mediated employment has normalized fleet-dependent mobility access over individual asset ownership.
Indonesia Used Car Financing Market Segmentation
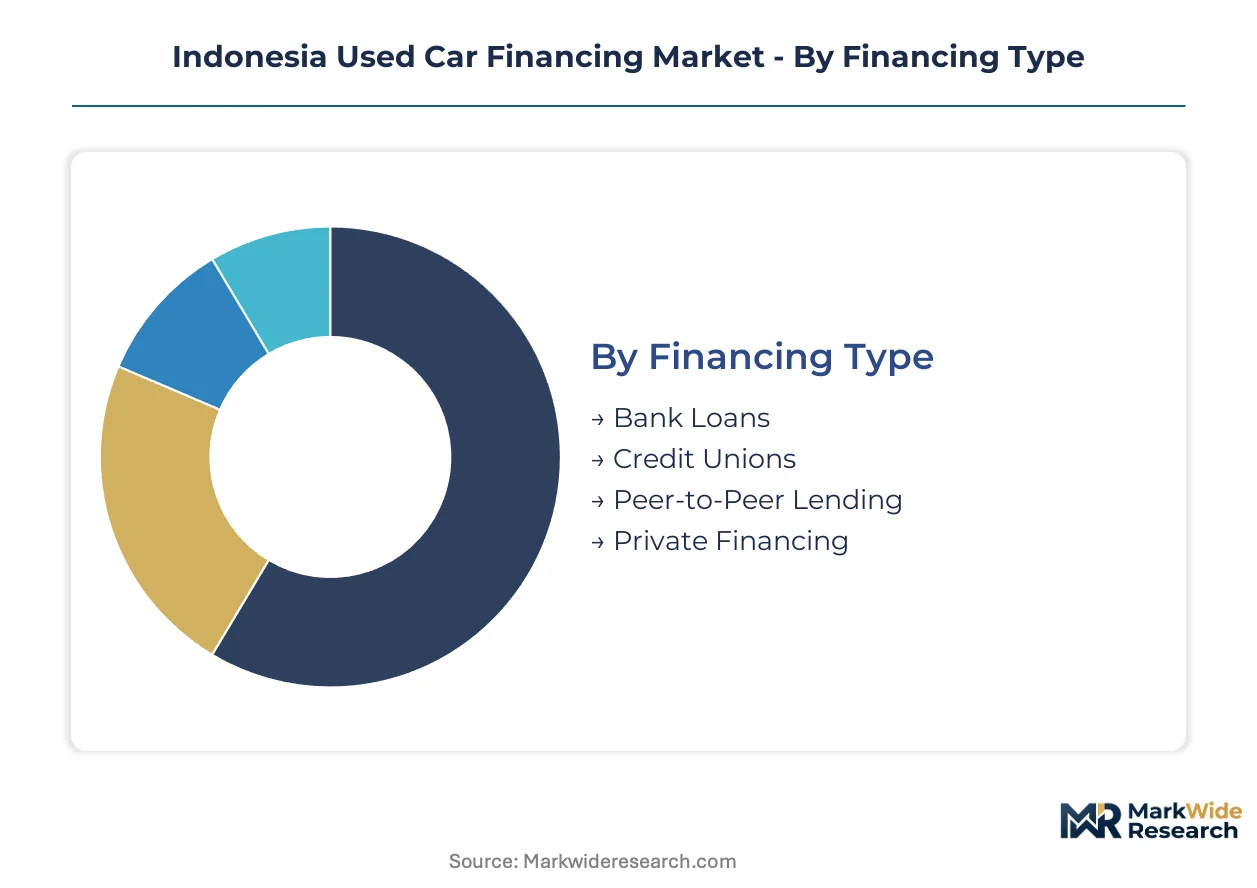
Segmentation in Indonesia's used car financing market reveals how lender product architecture and borrower profiles intersect. Each dimension carries distinct risk-weighting implications and origination cost structures that shape competitive strategy across Java and emerging island markets.
Financing Type:
Cost of funds and regulatory burden separate channels more sharply than borrower credit quality alone.
- Bank Loans:Deposit-funded balance sheets enable rate advantages that dominate volume in Greater Jakarta and Surabaya. OJK loan-to-value enforcement filters riskier collateral toward non-bank alternatives, compressing bank exposure to newer vehicle vintages with verified residual curves.
- Peer-to-Peer Lending:AI-driven scoring platforms collapse approval timelines from weeks to hours for ride-hailing drivers with thin bureau files. Fintech licensing under OJK's streamlined digital framework accelerates penetration among unbanked purchasers in tier-two Javan cities.
- Credit Unions:Member-based structures concentrate in Central Java agricultural cooperatives with collateral requirements stricter than commercial banks.
- Private Financing:Informal arrangements persist in outer island markets with sparse regulated lender presence, carrying rate premiums reflecting collection risk.
Bank loans lead volumes today; peer-to-peer lending is gaining share fastest.
Customer Type:
Repeat transaction history and fleet scale create divergent unit economics for originators.
- Fleet Owners:Bulk procurement concentrates counterparty risk with aggregator platforms in Surabaya and Bandung. Revenue-sharing sublease structures displace individual driver credit applications, reducing per-unit servicing overhead while embedding telematics for dynamic repossession triggers.
- First-Time Buyers:Thin-file applicants without bureau history dominate motorcycle-to-car migration pipelines in tier-two cities. Motorcycle lender payment records substitute for conventional scoring, enabling cross-sell conversion at acquisition costs below cold prospecting.
- Repeat Buyers:Established payment histories unlock preferential rate tiers and accelerated approval workflows through existing lender relationships.
- Individual Sellers:Self-financed inventory turnover creates intermittent liquidity demand addressed through short-term secured facilities against vehicle collateral.
Fleet owners concentrate margin contribution; first-time buyers show the steepest expansion trajectory.
Vehicle Type:
Depreciation velocity and secondary market liquidity differentiate collateral risk profiles.
- SUVs:Residual value stability in Java's urban corridors supports longer-duration financing with lower loss-given-default. Family-oriented demand in Jakarta suburbs sustains transaction velocity that feeds reliable price discovery for appraisal benchmarking.
- Sedans:Corporate fleet retirement pipelines supply standardized units with documented maintenance histories that reduce field assessment burden. Odometer verification protocols concentrate on this segment given higher absolute collateral values.
- Hatchbacks:Compact dimensions and fuel efficiency align with ride-hailing platform requirements in dense urban environments.
- Trucks:Commercial utilization patterns in Sumatra and Sulawesi plantation logistics create specialized underwriting demands around usage-based wear modeling.
Sedans anchor current origination volumes; SUVs are climbing the fastest as family mobility preferences shift.
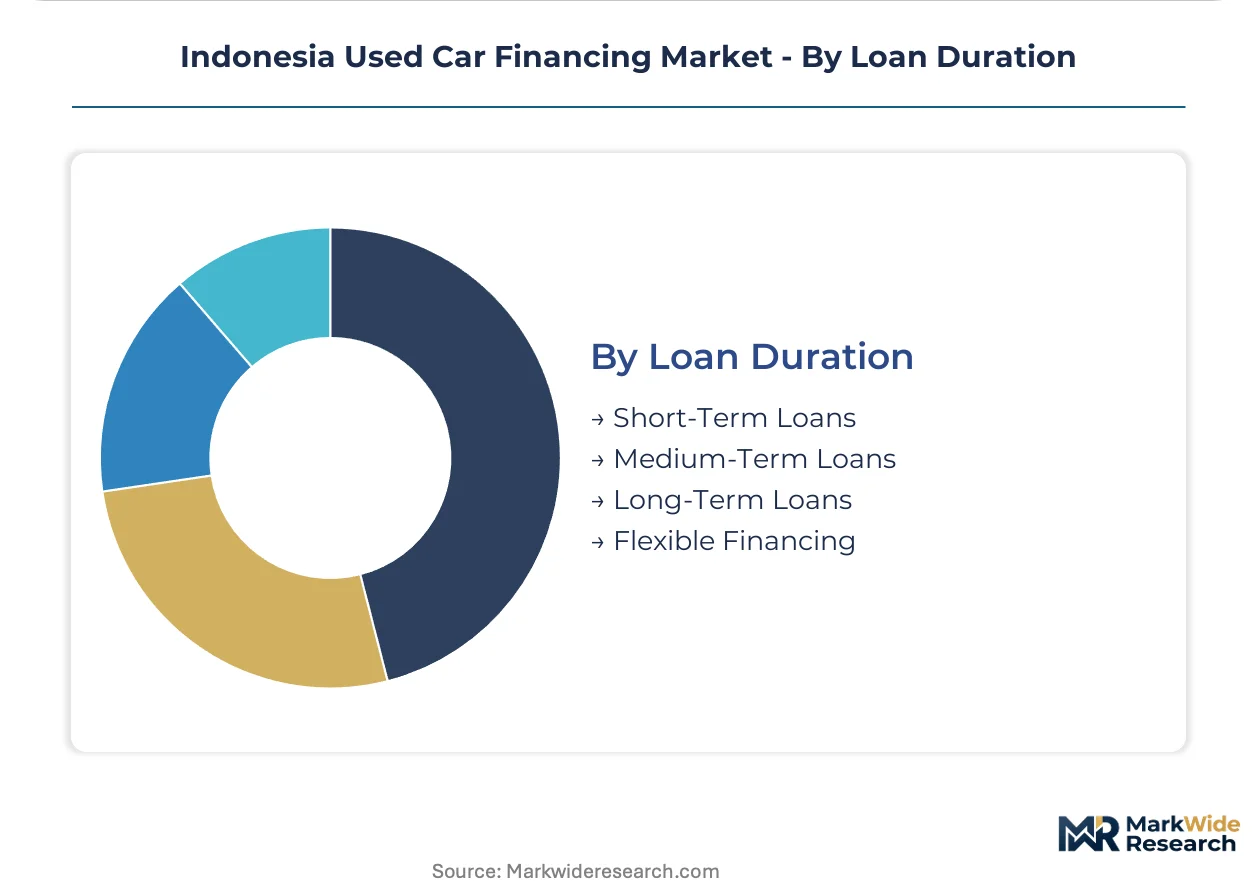
Loan Duration:
Maturity structure determines interest rate risk exposure and refinancing cycle frequency.
- Medium-Term Loans:Three-to-five year tenors balance monthly affordability with collateral value retention through the obligation life. This structure dominates used-car financing in Java where depreciation curves are best documented.
- Short-Term Loans:Twelve-to-twenty-four month structures serve fleet aggregator working capital needs and individual seller inventory turnover. Compressed duration limits Bank Indonesia rate cycle exposure for non-bank lenders with floating funding costs.
- Long-Term Loans:Extended amortization stretches affordability for newer used vehicles with residual curves supporting extended obligation horizons.
- Flexible Financing:Seasonal payment structures align with agricultural income patterns in Central Java cooperative lending.
Medium-term loans dominate outstanding balances; short-term structures are expanding most quickly with fleet channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between OJK-mandated down-payment floors and Bank Indonesia LTV caps is redirecting origination flows toward non-bank channels with compliance flexibility. Java-based lenders exploit this gap to capture volume from outer island markets with thinner regulated presence.
Greater Jakarta
Ride-hailing platform employment concentrates driver-borrower demand in Depok, Tangerang, and Bekasi satellite corridors. OJK digital-lending licensing enforcement operates most intensively here, filtering unlicensed fintech entrants. Fleet aggregator platforms in South Jakarta now intermediate bulk vehicle procurement, displacing individual credit applications.
Central Java
Agricultural income seasonality shapes flexible repayment structures through cooperative credit unions in Semarang and Surakarta. Bank Indonesia macroprudential rules transmit unevenly to rural borrowers, pushing demand toward motorcycle-lending heritage firms with adapted underwriting. Branch-dense physical networks in Yogyakarta sustain field appraisal capacity for chassis integrity verification.
East Java
Surabaya's manufacturing base generates corporate fleet retirement pipelines feeding standardized sedan collateral. OJK APR disclosure mandates face implementation friction among decentralized dealer networks in Malang and Sidoarjo. Second-hand vehicle transaction velocity in Gresik supports residual-value modeling with documented depreciation curves.
North Sumatra
Medan's credit density remains substantially below Javan benchmarks, creating first-mover positioning for platforms with localized collection infrastructure. The national financial services authority's regulatory perimeter extends less densely here, permitting operational experimentation. Plantation logistics in Deli Serdang generate commercial truck financing demand with usage-based wear modeling requirements.
South Sulawesi
Makassar's urbanization trajectory replicates Javan credit penetration patterns at earlier development stages. Sparse secondary market transaction data elevates collateral risk premiums for older vehicle vintages. Digital onboarding workflows from Jakarta-based lenders now target this corridor through agent-network partnerships.
Indonesia Used Car Financing Market Competitive Landscape
Captive finance subsidiaries anchor one tier; independent non-bank specialists hold origination flexibility advantages in regulatory transition periods. Market structure tilts toward established branch networks with motorcycle-lending heritage retrofitting car portfolios. Three archetypes dominate: manufacturer-captive funders leveraging dealer control, fintech platforms deploying algorithmic scoring, and diversified non-bank financial companies with physical assessment infrastructure. Competitive moves concentrate on cross-sell pipeline activation and telematics integration for fleet risk monitoring.
Within the diversified non-bank tier, Adira Dinamika Multi Finance and Oto Multiartha exemplify branch-dense incumbents adapting to digital onboarding imperatives. Bussan Auto Finance occupies a position representing motorcycle-to-car migration pathway specialization. These entities sit within a competitive set where used-car certification partnerships and field appraiser certification capacity differentiate collateral risk management approaches.
| Leading Market Players |
|---|
| Bussan Auto Finance |
| Oto Multiartha |
| PT Toyota Astra Financial Services |
| Adira Dinamika Multi Finance |
| PT JACCS Mitra Pinasthika Mustika Finance Indonesia (MPM Finance) |
| Astra Credit Companies (ACC) |
| Dipo Star Finance |
| Mandiri Tunas Finance |
| BFI Finance Indonesia |
| Others |
Supply & Pricing Matrix
Funding cost spreads from Bank Indonesia rate cycles transmit directly through non-bank lender pricing tiers, compressing margins for branch-heavy incumbents while algorithm-native platforms capture volume with leaner cost structures. This cost cascade reshapes competitive positioning across Java's urban corridors and outer island expansion zones.
Pricing Analysis
Distributor margin stacking through dealer-arranged financing channels obscures true borrowing costs until OJK-mandated APR disclosures forced standardization. Three-tier pricing structure across premium certified, standard verified, and economy unverified vehicle collateral segments now dominates product architecture. Cost compression in economy-tier originations intensifies because thin-file borrower acquisition expenses and field appraisal overhead concentrate in this segment. Fleet aggregator platforms exhibit lowest price sensitivity due to bulk negotiation leverage, while individual first-time buyers in tier-two cities face highest sensitivity to down-payment thresholds.
Supply Chain Analysis
Logistics costs for field appraiser deployment across Indonesia's archipelago geography inflate origination expenses outside Java's concentrated branch networks. Vehicle collateral sourcing draws from Japan, South Korea, and domestic fleet retirement pipelines, with residual-value modeling resting on transaction velocity in secondary markets. Single-source vulnerability concentrates in telematics hardware for fleet monitoring systems, where component availability constrains embedded finance product rollout. Distribution runs through dealer networks in urban corridors and agent partnerships in outer island markets with sparse regulated lender presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
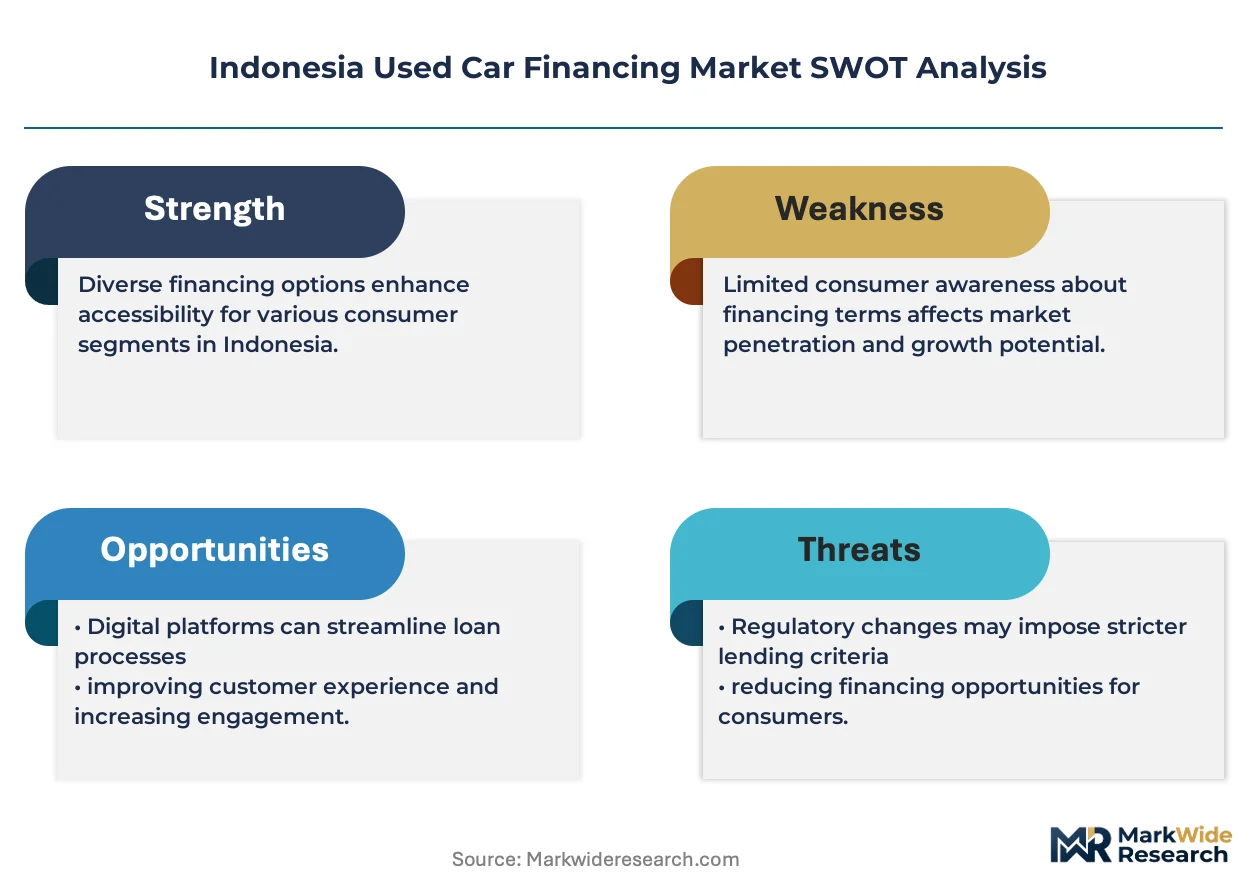
Indonesia's used car financing market operates as a regulatory compounder where OJK's APR disclosure mandates and down-payment floor adjustments continuously reshape competitive viability for originators.
For Market Incumbents: Cement branch-dense physical networks as defensible moats by integrating digital onboarding workflows with existing field appraisal certification capacity. Threat from algorithm-native fintech platforms with AI-driven scoring engines demands accelerated legacy core modernization to preserve origination velocity. Channel control through exclusive dealer relationships and captive certification partnerships for older vehicle collateral serves as the priority defensive lever. For New Entrants and Emerging Players: Enter via Sumatra and Sulawesi corridors where credit density lags Javan benchmarks and localized collection infrastructure remains underdeveloped. Medan and Makassar present the most penetrable geographies for platforms with agent-network distribution models adapted to sparse secondary market data environments. Go-to-market positioning should emphasize motorcycle-lending heritage cross-sell pipelines where existing payment histories substitute for conventional bureau files. For Investors and Strategic Acquirers: Roll-up economics work for diversified non-bank financial companies with motorcycle-to-car migration specialization because borrower graduation patterns create predictable origination pipelines with below-market acquisition costs. Long-term viability over the coming decade hinges on telematics integration capabilities and regulatory compliance infrastructure. Watch OJK digital-lending licensing enforcement intensity as the decisive inflection signal for fintech platform valuations versus incumbent resilience.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Integration Partnership | Embedded GPS tracking enables dynamic repossession triggers for fleet portfolios, reducing loss-given-default. |
| Certification Partnership Expansion | Used-car verification alliances with inspection networks lower collateral risk premiums on older vehicle vintages. |
| Digital Onboarding Platform Launch | Mobile-first origination compresses approval timelines from weeks to hours for ride-hailing driver segments. |
| Outer Island Agent Network Buildout | Localized collection infrastructure unlocks first-mover positioning in Medan and Makassar credit markets. |
| Legacy Core System Modernization | Real-time payment processing deployment closes competitive gap with algorithm-native fintech originators. |
Research Methodology
Bottom-up borrower segment modeling reconciled against top-down lender origination tracking forms the analytical core of this study. Primary interviews with credit risk officers at non-bank financial companies, OJK regulatory affairs specialists, fleet aggregator platform executives, and field appraisal certification program administrators combined with secondary validation. Secondary sources encompass OJK licensing disclosure databases, Bank Indonesia macroprudential bulletins, vehicle registration data from regional transportation authorities, and trade association origination volume reports. Triangulation between these channels ensures segmentation integrity across financing type, customer archetype, and regional dimensions.
Historical trendline analysis of origination volumes, delinquency trajectories, and funding cost spreads established baseline growth parameters across the projection horizon. The forecast framework models financing type segmentation alongside customer type migration patterns, vehicle collateral depreciation curves, and loan duration preference shifts. CAGRs derive from regression analysis against macroeconomic variables including BI rate cycles, urbanization velocity, and ride-hailing platform employment expansion. Industry-specific inputs incorporate OJK regulatory amendment calendars and digital lending license issuance velocity.
The model holds under stable regulatory enforcement intensity and gradual BI rate normalization; deviation in accelerated OJK digital-lending crackdowns or fossil fuel subsidy volatility would shift volume trajectories and margin projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Singapore Used Car Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
Thailand Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
Norway Used Car Market
Used Vehicles
Used Cars Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Portugal Used Car Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Australia Used Car Market
Used Vehicles
Malaysia Used Car Market