
 China Used Car Market | 2026-2036
China Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
China Used Car Market Analysis
Modular vehicle certification bundling is pivoting how Chinese consumers evaluate used car purchases. Guazi leverages its nationwide inspection network to anchor trust in remote transactions. Youxinpai competes through real-time auction interfaces that compress settlement cycles. Autohome sustains editorial content integration that steers buyer consideration sets before platform engagement.
A used car denotes a previously registered passenger vehicle resold through secondary ownership transfer, typically assessed via frame integrity, powertrain diagnostic readouts, and cosmetic grading protocols. The China Used Car Market serves household mobility substitution and fleet renewal cycles across ownership tiers. Sedan and SUV categories dominate transaction volume, though electric vehicle listings within fuel type segmentation are attracting disproportionate buyer inquiry growth. Online marketplace channels capture rising traffic share, yet dealership networks retain margin concentration through financing attachment and extended warranty packaging.
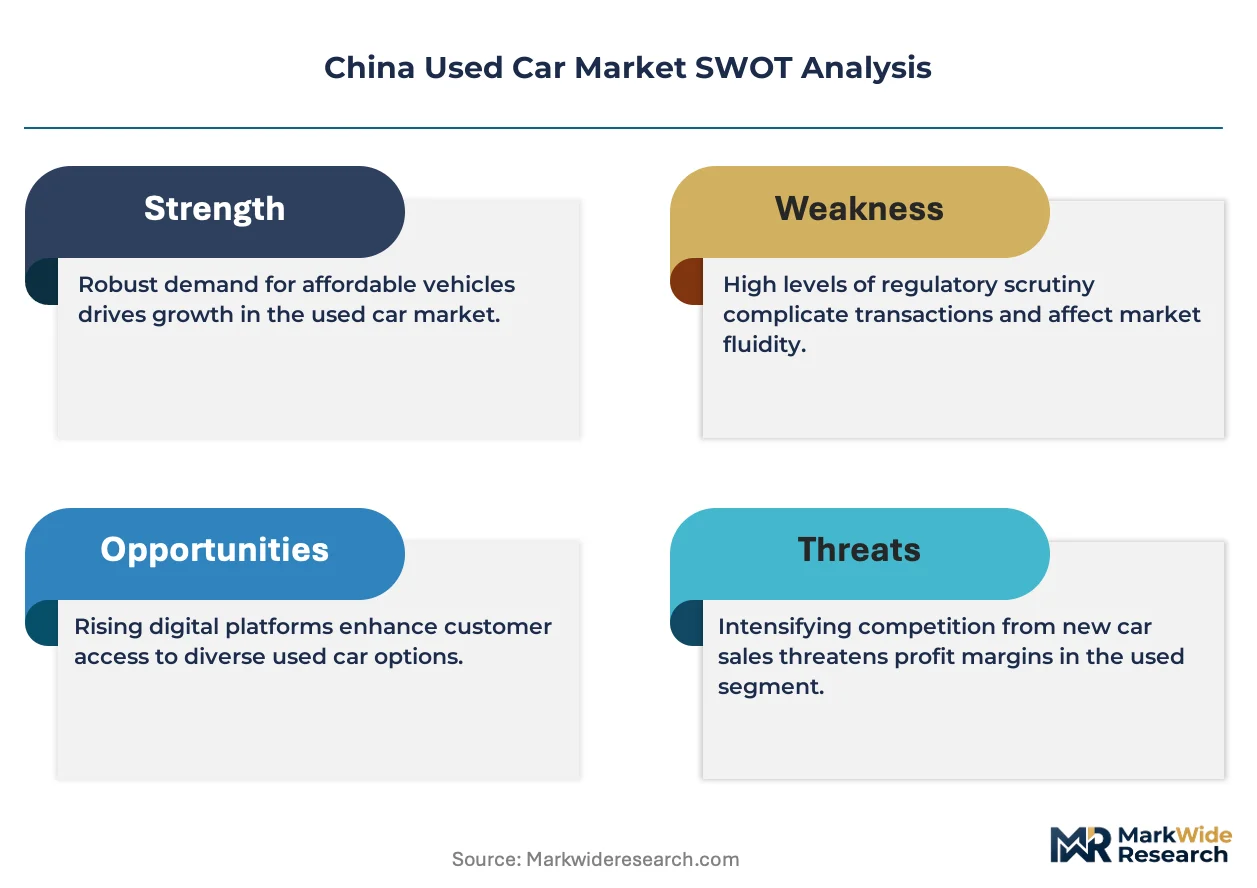
SAMR enforces disclosure standards for odometer accuracy and collision history, while MIIT mandates battery health reporting for new energy used vehicle transfers. These frameworks elevate compliance costs for non-certified inventory but expand addressable demand among risk-averse buyers. Stakeholders must monitor how provincial implementation variance in GB standards inspection affects cross-regional arbitrage feasibility and platform inventory fungibility.
Market Dynamics
MIIT battery traceability mandates are forcing wholesale documentation upgrades across China's used vehicle resale infrastructure, compressing settlement timelines while elevating compliance costs for non-certified inventory.
Growth Catalysts
- Digital transaction platforms:First-time buyers in lower-tier cities now complete remote purchases through inspection-backed online channels, bypassing traditional dealership intermediaries entirely.
- MIIT new energy vehicle standards:Mandatory battery health reporting creates standardized disclosure frameworks that reduce information asymmetry for electric vehicle transactions.
- Provincial capital clusters:Chengdu, Wuhan, and Xi'an are expanding offline inspection infrastructure fastest, drawing inventory liquidity away from saturated eastern coastal markets.
Market Restraints
- Cross-regional inspection variance:Provincial implementation differences in GB standards create friction for inventory arbitrage between municipalities, limiting platform fungibility.
- Certification cost concentration:SAMR disclosure requirements for odometer accuracy and collision history impose disproportionate burdens on small independent dealers with limited capital reserves.
- Residual value opacity:Rapid new energy vehicle model turnover and battery degradation uncertainty compress holding-period calculations for fleet operators.
Strategic Opportunities
- Western provincial penetration:Sichuan, Hubei, and Shaanxi provinces show underpenetrated digital marketplace adoption relative to their transaction volume growth potential.
- Financing attachment innovation:Embedded credit products tied to certified pre-owned vehicles capture margin concentration currently retained by traditional dealership networks.
- Dual carbon goal alignment:Extended vehicle lifecycle utilization through formalized resale channels supports national emissions reduction targets, potentially unlocking preferential policy treatment.
Industry Challenges
- Inspection technician scarcity:Battery diagnostic certification programs have not scaled to match new energy vehicle listing growth, creating bottlenecked settlement queues.
- Legacy system integration:Provincial vehicle registration databases lack API standardization, forcing manual data reconciliation during ownership transfers.
- Warranty claim adjudication:Disputes over powertrain coverage boundaries between original manufacturers and secondary market sellers generate transaction friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Used Car Market |
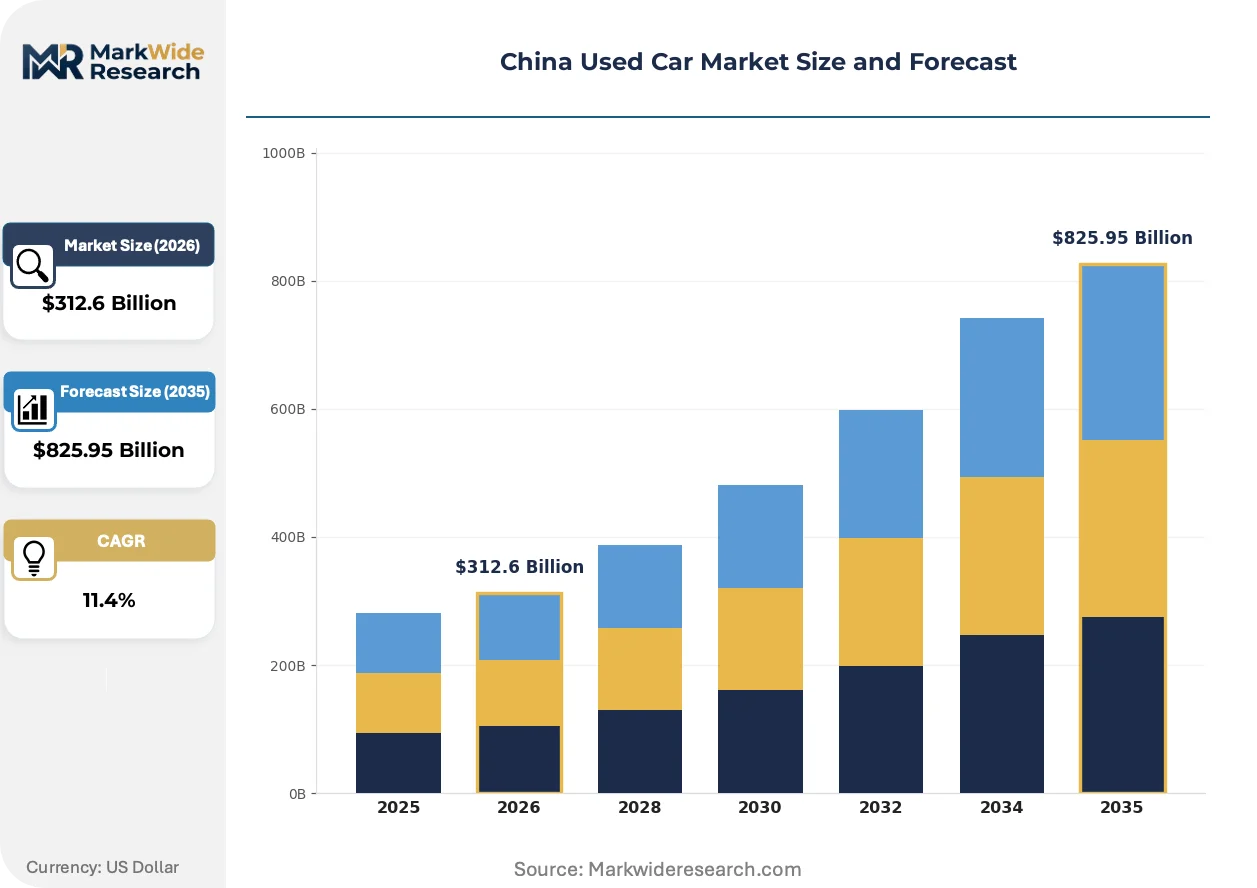
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $825.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Certification Status: Certified Pre-Owned, Non-Certified, Warranty Available, As-Is Fuel Type: Petrol, Diesel, Electric, Hybrid Sales Channel: Online Marketplace, Dealership, Auction, Private Sale |
| Companies Covered | Autohome, Youxinpai, Guazi, Bitauto, 51Auto, Renrenche, China Auto, UCAR, Che168, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Used Car Market Emerging Trajectories
Remote transaction infrastructure is converging with physical inspection networks to reshape how trust is manufactured in distributed vehicle resale, collapsing the traditional geographic constraints on buyer-seller matching.
Blockchain-based ownership verification is converging with real-time battery telemetry to enable condition-adjusted pricing algorithms. Fleet operators and institutional sellers are adopting these tools fastest, using continuous health monitoring to justify premium residuals. This technology convergence is compressing the due diligence window from days to hours for certified electric vehicle listings.
SAMR disclosure enforcement is tightening odometer accuracy penalties while MIIT expands battery traceability to cover second ownership transfers. These parallel regulatory tracks are elevating compliance costs for uncertified inventory but expanding addressable demand among risk-averse household buyers. The used electric vehicle segment faces the steepest documentation requirements, driving consolidation toward platforms with captive inspection capabilities.
Buyer consideration formation now occurs through editorial content integration before platform engagement, reversing the traditional discovery sequence. Younger consumers in provincial capitals research vehicle histories through video-based inspection walkthroughs rather than physical lot visits. This behavioral shift is most pronounced in Chengdu and Xi'an, where digital-native buyers treat remote transactions as default rather than exception.
China Used Car Market Segmentation
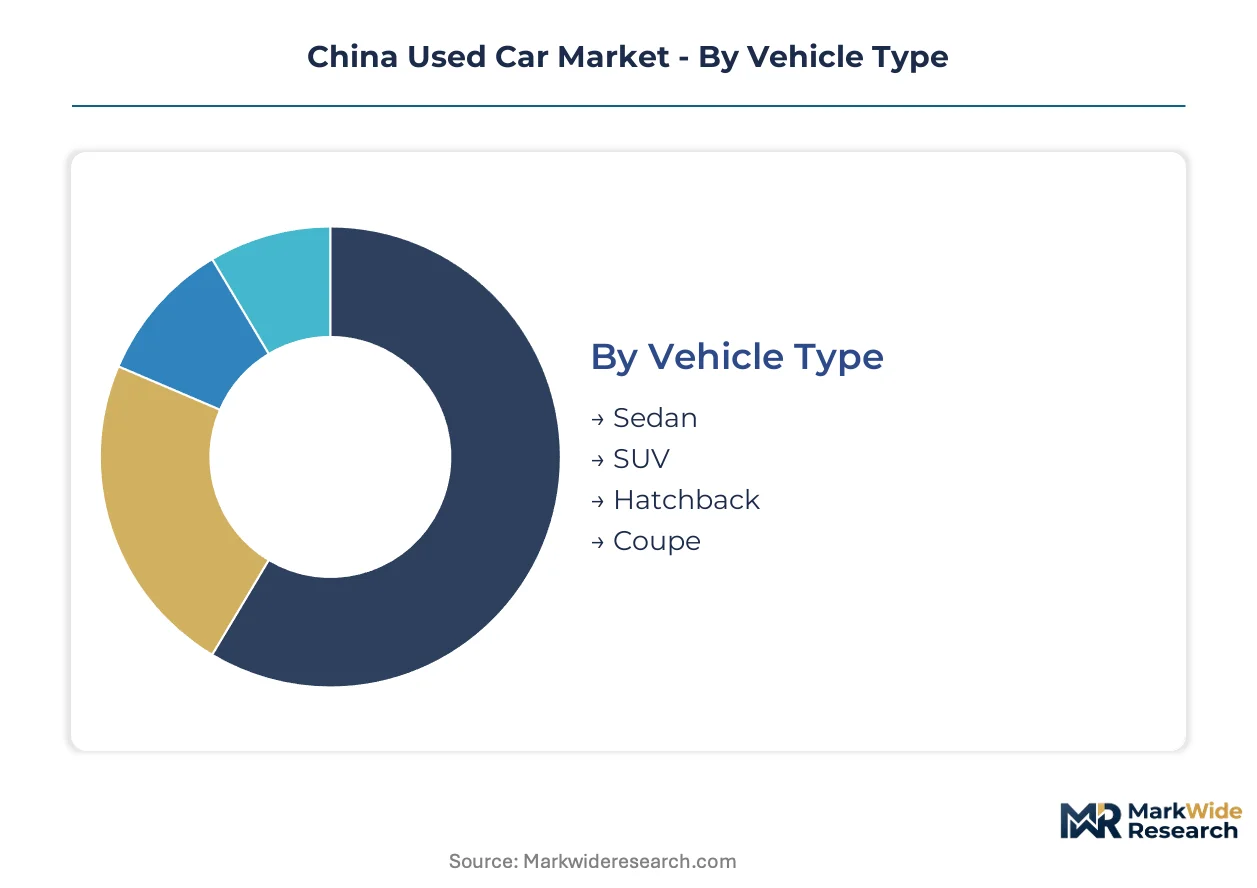
Segmentation reveals how transaction infrastructure and buyer risk tolerance fragment across China's used vehicle resale channels. Each axis exposes distinct margin structures, compliance burdens, and platform specialization opportunities.
Vehicle Type:
Body architecture determines inspection protocol complexity and residual value stability in Chinese secondary markets.
- Sedan:Three-box construction with dedicated cargo compartments dominates urban household transactions. MIIT traceability requirements for frame integrity assessment concentrate demand in Chengdu and Wuhan where certified inspection networks have scaled fastest.
- SUV:Elevated ride height and unibody or ladder-frame architectures command premium positioning in western provincial markets. Cross-regional arbitrage friction limits inventory fungibility between Sichuan and coastal municipalities due to GB standards implementation variance.
- Hatchback:Compact two-box designs with integrated cargo areas attract first-time buyers in lower-tier cities seeking maneuverability.
- Coupe:Two-door sport configurations with sloping rooflines occupy niche positioning among enthusiast segments in provincial capitals.
Mature deployment sits with Sedan. Newer deployment is concentrated in SUV.
Certification Status:
Documentation tiering separates risk-bearing capacity between institutional platforms and independent dealers.
- Certified Pre-Owned:SAMR-mandated odometer verification and collision history disclosure anchor buyer trust. Guazi's nationwide inspection network leverages this tier to justify remote transaction premiums in Xi'an and Chengdu.
- Warranty Available:Powertrain coverage extensions transfer residual risk from buyers to sellers or third-party underwriters. Fleet operators adopting continuous battery health monitoring use this tier to justify premium residuals for electric vehicle listings.
- Non-Certified:Limited documentation imposes due diligence burdens on buyers but enables price-sensitive transactions.
- As-Is:Zero warranty transfer places full condition risk on purchasers, compressing settlement timelines for distressed inventory.
Platform investment concentrates on Certified Pre-Owned. Margin compression is deepest in As-Is.
Fuel Type:
Powertrain chemistry dictates regulatory documentation intensity and technician certification requirements.
- Electric:Battery health reporting mandates under MIIT new energy vehicle standards create the steepest compliance gradient. Real-time telemetry integration with blockchain verification enables condition-adjusted pricing algorithms that compress due diligence windows.
- Hybrid:Dual powertrain architectures combine combustion and electric components, requiring diagnostic capabilities across both systems. Inspection technician scarcity for battery diagnostic certification creates bottlenecked settlement queues relative to listing growth.
- Petrol:Internal combustion engines with established maintenance protocols dominate transaction volume.
- Diesel:Compression-ignition powertrains serve commercial fleet renewal cycles in provincial logistics corridors.
Regulatory pressure is intensifying on Electric. Transaction velocity remains highest in Petrol.
Sales Channel:
Channel selection determines financing attachment rates and buyer demographic reach.
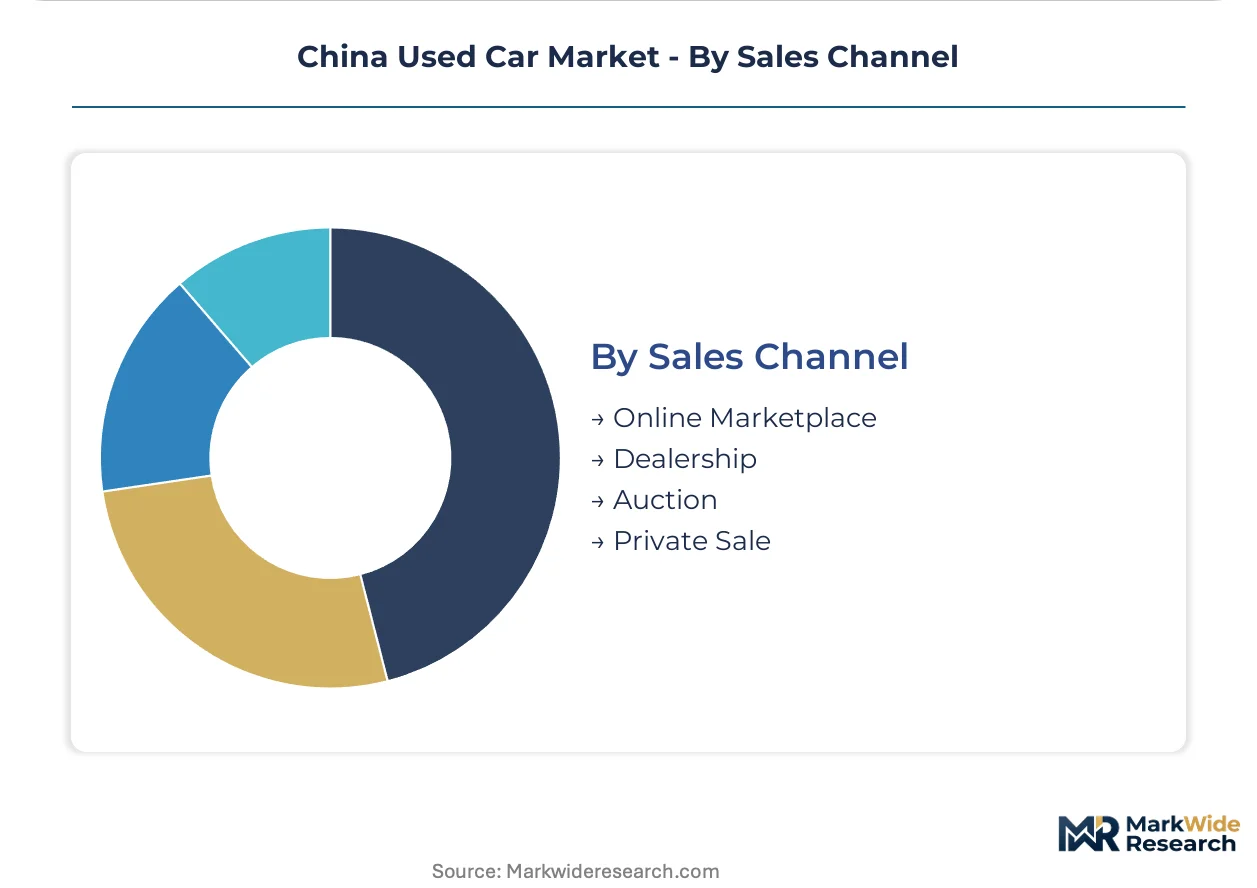
- Online Marketplace:Remote transaction infrastructure with inspection-backed trust mechanisms bypass traditional dealership intermediaries. Youxinpai's real-time auction interfaces compress settlement cycles while capturing rising traffic share from digital-native buyers.
- Dealership:Physical lot presence with financing attachment and extended warranty packaging retains margin concentration. Legacy system integration gaps in provincial vehicle registration databases force manual data reconciliation during ownership transfers.
- Auction:Time-bound competitive bidding accelerates inventory turnover for institutional sellers.
- Private Sale:Direct buyer-seller matching minimizes intermediary fees but maximizes information asymmetry risks.
Capital allocation is shifting toward Online Marketplace. Dealership retains financing margin dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's used car production infrastructure clusters in eastern manufacturing zones while consumption demand shifts inland toward western provincial capitals. This geographic mismatch creates logistics arbitrage opportunities for platforms with distributed inspection networks.
Sichuan-Chongqing
Chengdu anchors western China's fastest-growing used vehicle transaction volume as first-time buyers migrate from rural counties. MIIT battery traceability mandates compress settlement timelines for electric vehicle transfers across Chengdu's municipal registration system. The Sichuan-Chongqing economic corridor expands offline inspection infrastructure to capture liquidity from underserved western markets.
Hubei
Wuhan's automotive heritage supports technician training pipelines that alleviate battery diagnostic certification bottlenecks. SAMR disclosure enforcement for odometer accuracy elevates compliance costs for independent dealers in the Yangtze River midstream region. The Wuhan metropolitan cluster draws inventory from coastal oversupply markets through improved cross-regional logistics connectivity.
Shaanxi
Xi'an's digital-native buyer demographic treats remote transactions as default rather than exception, accelerating online marketplace penetration. GB standards implementation variance between Shaanxi and neighboring provinces creates friction for inventory arbitrage into Gansu and Ningxia. The Xi'an-Xianyang integration zone concentrates certified pre-owned vehicle financing attachment innovation.
Guangdong
Pearl River Delta saturation pushes surplus inventory inland as eastern coastal markets face margin compression. SAMR mandates on collision history disclosure impose disproportionate documentation burdens on Shenzhen's high-volume independent dealers. Guangzhou's legacy dealership networks retain financing margin dominance despite online marketplace traffic share erosion.
Beijing-Tianjin-Hebei
Beijing's vehicle quota system channels demand toward used car substitution rather than new vehicle registration. MIIT new energy vehicle standards enforce battery health reporting that elevates certified pre-owned premiums in the capital's regulated market. Tianjin's port infrastructure supports inbound inventory flows from northeastern manufacturing bases.
China Used Car Market Vendor Landscape
The competitive structure tilts toward platform-based intermediaries with captive inspection capabilities. National marketplace operators consolidate transaction liquidity while regional dealership networks retain financing attachment margins. Three archetypes dominate: vertically integrated inspection-platform hybrids, auction-interface specialists, and content-integrated discovery engines. Capacity expansion into western provincial markets and strategic partnerships with battery diagnostic certification providers represent the dominant competitive vectors.
Within the inspection-platform hybrid tier, Guazi and Youxinpai exemplify divergent trust-manufacturing approaches. Guazi anchors remote transaction premiums through nationwide physical inspection network density. Youxinpai occupies a position emphasizing real-time auction interfaces that compress settlement cycles for institutional sellers. Autohome represents the content-integrated archetype, steering buyer consideration sets through editorial vehicle history coverage before platform engagement occurs.
| Leading Market Players |
|---|
| Autohome |
| Youxinpai |
| Guazi |
| Bitauto |
| 51Auto |
| Renrenche |
| China Auto |
| UCAR |
| Che168 |
| Others |
Supply Flow & Price Mechanics
Certified-versus-non-certified vehicle bifurcation creates divergent margin architectures across China's used car resale infrastructure, with SAMR-mandated disclosure tiers concentrating pricing power in inspection-backed inventory while compressing returns on undocumented stock. This tier divergence reshapes both procurement patterns and downstream distribution economics.
Pricing Analysis
Margin tightening in non-certified inventory reflects SAMR odometer verification and collision history mandates that elevate compliance costs for small independent dealers. Three-tier pricing structure across certified pre-owned, warranty-backed, and as-is segments stratifies buyer risk tolerance. Cost-down pressure on as-is transactions accelerates because first-time buyers in lower-tier cities migrate toward inspection-guaranteed channels. Fleet operators exhibit lowest price sensitivity, while rural household buyers in Sichuan and Hubei provinces drive maximum price elasticity.
Supply Chain Analysis
Single-source vulnerability sits with eastern coastal manufacturing clusters that generate surplus inventory for western provincial consumption. Supply concentration in Guangdong, Jiangsu, and Zhejiang provinces feeds from OEM production overruns and fleet renewal cycles. Raw material dependencies span lithium-ion battery packs, aluminum body panels, and semiconductor control modules. Tariff exposure on cross-regional logistics creates settlement friction between municipalities with divergent GB standards implementation. Distribution runs through platform-controlled inspection networks that bypass traditional dealership intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's used car market operates under technician certification scarcity that constrains electric vehicle transaction velocity and props certified pre-owned premiums. Battery diagnostic bottlenecks limit settlement throughput, preserving margin concentration for platforms with captive inspection capabilities.
For Market Incumbents: Acquire battery diagnostic certification capacity in Chengdu and Wuhan to preempt technician scarcity bottlenecks. Defensive consolidation should prioritize backward integration into real-time telemetry providers that enable condition-adjusted pricing algorithms. Threat substitution from blockchain-based ownership verification platforms demands immediate API standardization investments with provincial vehicle registration databases. For New Entrants and Emerging Players: First-time buyers in Xi'an and lower-tier western cities represent the most penetrable archetype for digital-native marketplace positioning. White-space targets include embedded financing attachment for certified pre-owned electric vehicles and cross-regional arbitrage facilitation between Shaanxi and neighboring provinces. Go-to-market execution should leverage video-based inspection walkthroughs that collapse traditional geographic constraints on buyer-seller matching. For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated inspection-platform hybrids with western provincial network density. Long-term viability over the next decade hinges on MIIT regulatory compliance scalability and dual carbon goal alignment. The signal to watch is provincial implementation convergence on GB standards inspection protocols that unlock inventory fungibility across municipal boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Inspection Network Expansion | Captive technician certification in Chengdu and Wuhan compresses settlement timelines for electric vehicle transfers. |
| Battery Telemetry Integration | Real-time health monitoring partnerships with MIIT-authorized diagnostic providers enable condition-adjusted pricing premiums. |
| Cross-Regional Logistics Partnership | Western corridor connectivity between Sichuan-Chongqing and coastal oversupply markets unlocks arbitrage margin capture. |
| Embedded Financing Product Launch | Credit attachment tied to SAMR-certified inventory transfers margin concentration from legacy dealership networks. |
| Provincial Database API Standardization | Automated ownership transfer reconciliation eliminates manual data friction during MIIT-mandated battery traceability compliance. |
Methodological Framework
Independent corroboration across MIIT regulatory filings, SAMR enforcement bulletins, and provincial vehicle registration databases underwrites the qualitative findings on compliance cost distribution. Primary interviews with used car platform operations executives, battery diagnostic certification providers, and dealership network managers combined with secondary validation from automotive production databases and customs trade records. Bottom-up transaction volume estimates and top-down economic indicator triangulation anchor the market sizing framework.
Rate-of-change decomposition across the analysis window isolates volume drivers from price evolution in electric versus combustion vehicle segments. Segmentation dimensions modeled include vehicle body architecture, certification documentation tier, powertrain chemistry, and sales channel configuration. CAGRs derive from regression against macroeconomic proxies and technology adoption curves. Forecast inputs incorporate MIIT battery traceability mandate rollout timelines and provincial capital infrastructure investment pipelines.
Revisions become necessary when GB standards implementation variance narrows unexpectedly or battery diagnostic certification programs scale faster than projected. Forecasts reflect documented assumptions about regulatory enforcement intensity and technician training pipeline throughput. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Sri Lanka Used Car Market
Used Vehicles
Spain Used Car Market
Used Vehicles
Used Cars Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
India Used Car Market
Used Vehicles
South Africa Used Car Market
Used Vehicles
Vintage Car Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
UAE Used Cars Industry Market
Used Vehicles
United Arab Emirates Used Car Market