
 Portugal Used Car Market | 2026-2036
Portugal Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Portugal Used Car Market Insights
Certified automotive technician shortages is reorganizing how dealers scale reconditioning operations across Portugal. BCA leverages its auction infrastructure to move volume efficiently between Iberian markets. Standvirtual controls digital listing traffic through platform consolidation. Caetano Retail anchors physical retail presence with service bay integration in Greater Lisbon.
A used car denotes a previously registered motor vehicle offered for resale through commercial or private channels, typically subjected to mechanical inspection, mileage verification, and cosmetic reconditioning prior to transaction completion. Its primary purpose centers on providing affordable mobility access while extending vehicle economic utility across multiple ownership cycles. SUV listings command structural premium positioning within vehicle type segmentation due to family buyer preference and residual value retention. Electric fuel type entries face constrained supply pipelines as corporate fleet off-cycles lag consumer trade-in velocity. Certified Pre-Owned condition grades concentrate margin pools through warranty-backed pricing differentiation and finance product attachment.
EU Green Deal vehicle emissions standards and national ICE restrictions shape fleet renewal timing and eligible resale inventory composition. Portugal's energy regulator and environmental authority coordinate charging infrastructure certification requirements that influence electric used car marketability. The country's central bank and consumer protection framework govern auto finance disclosure and buy-here-pay-here lending practices. Stakeholders must monitor regulatory calendar alignment between EU-wide phase-out mandates and national incentive taper schedules to optimize inventory acquisition and pricing strategies.
Market Dynamics
Fleet operators across Portugal are accelerating ICE vehicle offloading ahead of EU Green Deal phase-out deadlines, compressing wholesale supply cycles and restructuring auction-to-retail arbitrage windows for dealers in Lisbon and Porto corridors.
Growth Catalysts
- EU Green Deal mandates:ICE phase-out timelines force corporate fleet renewal, flooding wholesale channels with three-to-five-year-old diesel and petrol inventory that dealers recondition for resale.
- Metropolitan demand concentration:Lisbon and Porto urban corridors concentrate buyer liquidity, enabling faster inventory turns and reducing working capital lock-up for dealership networks.
- Digital auction infrastructure:BCA and similar platforms compress transaction friction between Iberian markets, expanding addressable buyer pools beyond physical showroom catchments.
Market Restraints
- Certified technician scarcity:Reconditioning bay capacity bottlenecks at dealership service centers limit volume scaling despite available auction supply.
- Electric vehicle pipeline constraints:Corporate fleet off-cycles for battery-electric models lag consumer trade-in velocity by eighteen to thirty-six months, choking certified pre-owned EV availability.
- Charging infrastructure certification:Portugal's energy regulator imposes technical validation requirements that delay electric used car marketability and compress resale margins.
Strategic Opportunities
- Algarve and Coimbra expansion:Secondary metropolitan zones outside Lisbon-Porto axis show underpenetrated digital listing density relative to household vehicle ownership rates.
- Subscription-to-ownership conversion:Rental fleet operators pilot flexible tenure models that transition short-term users into certified pre-owned purchases with embedded financing.
- Warranty-backed finance attachment:Certified Pre-Owned condition grades enable higher-margin product bundling through extended coverage and maintenance plans.
Industry Challenges
- Diagnostic equipment capex requirements:Electric and hybrid vehicle reconditioning demands specialized tooling that smaller independent dealers cannot amortize across limited volume.
- Multi-platform inventory synchronization:Dealers manage listing fragmentation across Standvirtual, OLX, and physical auction channels with inconsistent pricing transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portugal Used Car Market |
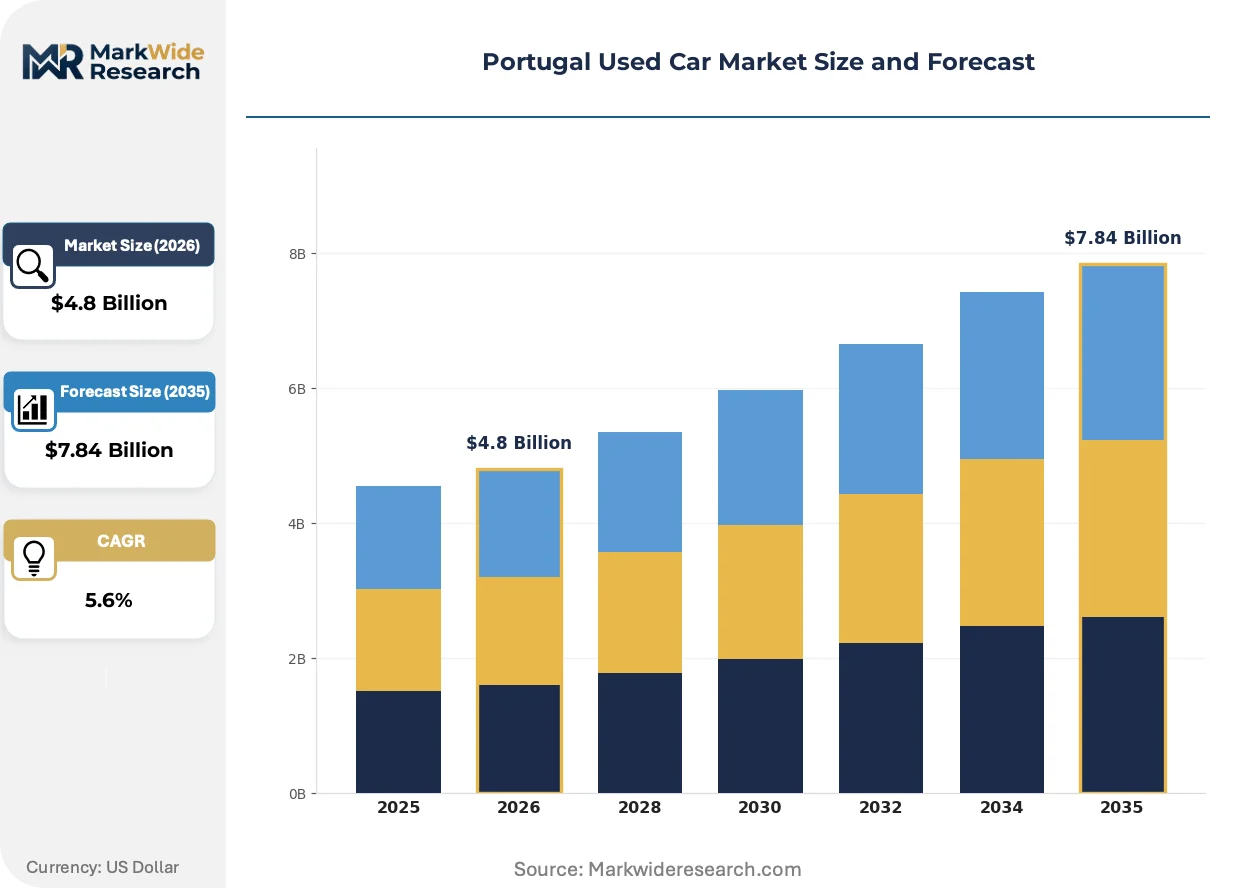
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Coupe Fuel Type: Petrol, Diesel, Hybrid, Electric Condition: Certified Pre-Owned, Non-Certified, New-Old Stock, Damaged Sales Channel: Dealership, Online Marketplace, Private Seller, Auction |
| Companies Covered | BCA, Nors Group, OOYYO Corp, AutoAcordo, Caetano Retail, ALD Automotive, Guia do Automóvel, Standvirtual, Auto SAPO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portugal Used Car Market Trends and Innovations
Vehicle lifecycle data transparency is compressing information asymmetry between wholesale sellers and retail buyers, forcing dealers to reposition around inspection credibility and warranty backing rather than opaque pricing arbitrage.
Blockchain-enabled provenance tracking is decomposing the traditional reliance on paper service histories and odometer declarations. Fleet operators and large dealer groups in Greater Lisbon are piloting immutable maintenance records to accelerate buyer trust formation. This technology is decomposing the due diligence burden that previously justified certified pre-owned price premiums, compressing margin pools toward inspection quality and warranty terms.
EU Green Deal vehicle emissions standards are tightening eligible resale inventory composition through CO2-based registration restrictions. Portugal's environmental authority coordinates with the energy regulator to align charging infrastructure certification with resale eligibility criteria. Diesel-heavy segments face accelerated depreciation as municipal access restrictions expand across Porto and Lisbon low-emission zones.
Private seller bypass of traditional dealer intermediaries is fragmenting listing origination toward peer-to-peer platforms. Younger demographic cohorts in Lisbon metropolitan area favor direct transaction models with third-party inspection overlays rather than dealership reconditioning markups. This behavioral pivot concentrates dealer value-add around financing access, warranty underwriting, and trade-in handling rather than sourcing and display functions.
Portugal Used Car Market Segmentation
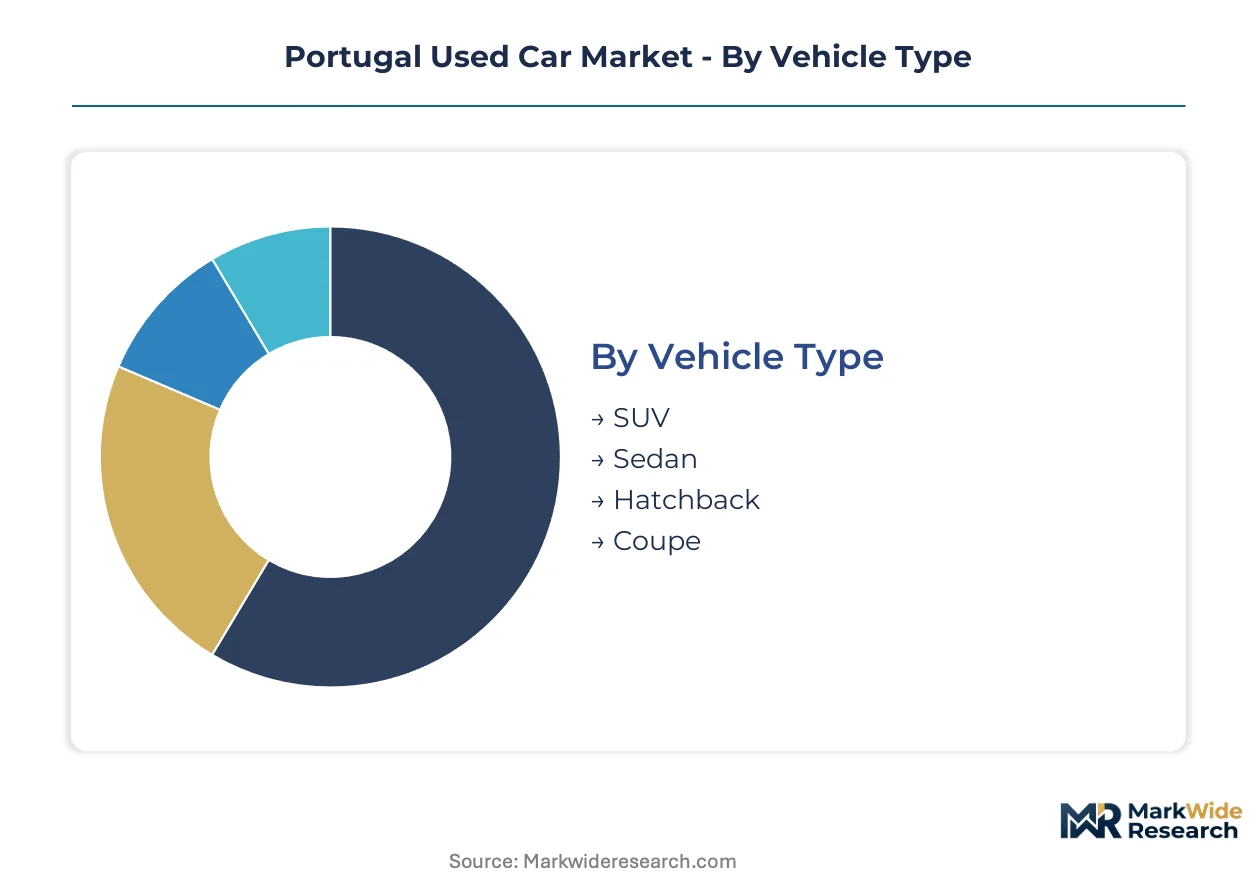
Segmentation in Portugal's used car market reveals how margin pools concentrate around certification-backed inventory and metropolitan sales channels. Dealers align procurement and reconditioning investments against these structural divides to optimize working capital efficiency.
Vehicle Type:
Margin concentration tilts toward utility-focused body styles that retain resale velocity across ownership cycles.
- SUV:Higher ground clearance and modular seating configurations attract family buyers across Lisbon and Porto metropolitan corridors. Structural premiums persist due to residual value retention and preference for all-weather capability on Portugal's coastal and interior road networks.
- Sedan:Three-box configurations dominate corporate fleet off-cycles entering wholesale channels. Demand concentrates among professional buyers in Greater Lisbon seeking understated mobility with established maintenance cost predictability.
- Hatchback:Compact dimensions suit urban parking constraints in Porto's dense historic districts.
- Coupe:Two-door specialty vehicles occupy niche positioning with limited volume turnover.
The dominant share belongs to SUV, while Hatchback is closing the gap fastest on urban density constraints.
Fuel Type:
Regulatory pressure on emissions is fragmenting margin structures across propulsion technologies.
- Petrol:Internal combustion engines with spark ignition dominate auction volume from three-to-five-year-old fleet returns. Lisbon dealers favor petrol inventory for its mechanical simplicity and faster reconditioning turnaround relative to diesel particulate filter maintenance.
- Diesel:Compression-ignition units face accelerated depreciation as municipal low-emission zones expand across Porto city center. Demand concentrates in rural Alentejo and Centro regions where highway fuel economy outweighs urban access restrictions.
- Hybrid:Dual-powertrain vehicles bridge regulatory compliance with range security.
- Electric:Battery-electric supply pipelines lag fleet off-cycle timing by eighteen to thirty-six months.
Petrol retains volume leadership, though Hybrid is expanding most quickly on EU Green Deal alignment.
Condition:
Certification tiers separate price-transparent commodity inventory from warranty-backed premium positioning.
- Certified Pre-Owned:Dealer-backed inspection protocols and extended coverage enable finance product attachment. Greater Lisbon networks concentrate margin extraction through service bay integration and captive warranty underwriting.
- Non-Certified:As-is transactions dominate peer-to-peer platforms and independent lot inventory. Porto corridor buyers accept mechanical risk for upfront cost reduction on older model years.
- New-Old Stock:Unregistered prior-model-year units bypass depreciation from initial ownership.
- Damaged:Salvage-grade vehicles flow to specialist rebuilders and export channels.
Certified Pre-Owned commands pricing power, while Non-Certified is gaining share fastest on platform-enabled private sales.
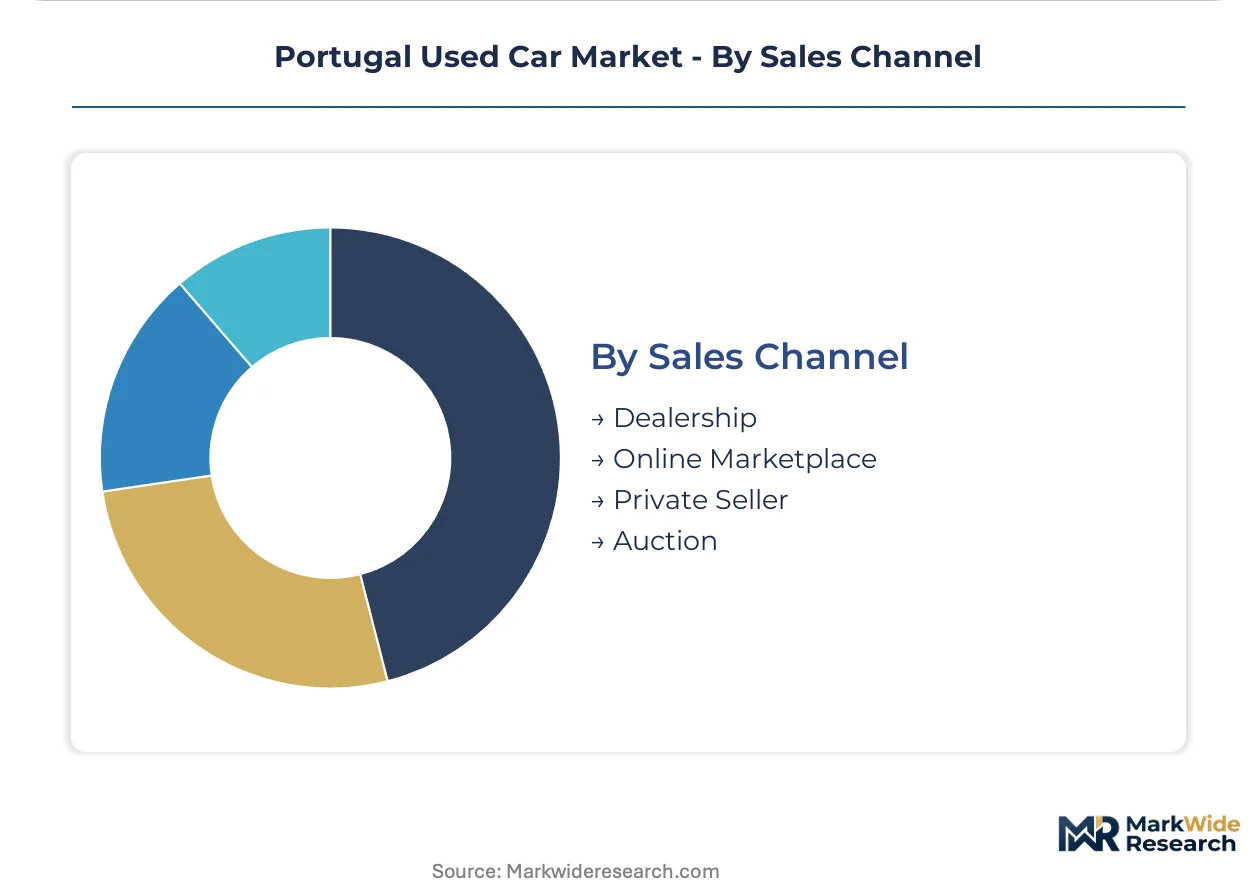
Sales Channel:
Channel selection determines buyer liquidity access and inventory velocity for dealers.
- Dealership:Physical showrooms with service integration anchor trade-in handling and financing access. Caetano Retail and similar groups in Greater Lisbon leverage reconditioning credibility to justify markup over digital alternatives.
- Online Marketplace:Standvirtual and consolidated platforms compress search friction for metropolitan buyers. Listing density concentrates in Lisbon-Porto corridors where digital penetration outpaces physical lot coverage.
- Private Seller:Direct transactions fragment toward peer-to-peer platforms with third-party inspection overlays.
- Auction:BCA infrastructure moves volume efficiently between Iberian wholesale markets.
Dealership holds structural advantages on financing attachment, though Online Marketplace is climbing the fastest on generational preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan corridors in Portugal concentrate used car transactions differently than rural hinterlands, with Lisbon and Porto absorbing three-to-five-year-old fleet off-cycles while Algarve and Centro regions favor older diesel inventory for highway economy.
Greater Lisbon
Corporate fleet renewal under EU Green Deal mandates floods wholesale channels with petrol and diesel vehicles. Portugal's environmental authority coordinates low-emission zone expansion with municipal traffic restrictions. Lisbon's dense dealership networks, led by Caetano Retail service bay integration, compress reconditioning turnaround for certified pre-owned inventory.
Porto Metropolitan Area
Urban density constraints elevate hatchback demand for historic district parking compatibility. The country's energy regulator imposes charging infrastructure certification that delays electric used car marketability. Standvirtual's digital listing density concentrates buyer liquidity in this corridor, enabling faster inventory turns than physical lot coverage alone.
Algarve
Tourism-dependent household mobility preferences skew toward affordable SUV segments for coastal and interior road networks. EU Green Deal ICE phase-out timelines pressure rental fleet operators to offload inventory ahead of access restrictions. Secondary metropolitan zones here show underpenetrated digital auction infrastructure relative to vehicle ownership rates.
Coimbra
University city demographics drive compact vehicle demand among younger buyer cohorts favoring peer-to-peer transaction models. Portugal's central bank governs auto finance disclosure requirements that shape buy-here-pay-here lending practices. BCA auction infrastructure extends wholesale access to this corridor, bridging Iberian market arbitrage windows.
Centro Region
Rural highway fuel economy priorities sustain diesel demand despite accelerated depreciation in urban low-emission zones. National ICE restriction calendars align with EU-wide phase-out mandates to structure fleet renewal timing. Independent dealers here face diagnostic equipment capex barriers for electric and hybrid reconditioning.
Portugal Used Car Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Portugal's used car market. Auction platforms and retail dealership groups with captive service infrastructure capture margin pools through reconditioning credibility and financing attachment. Three archetypes dominate: digital marketplace operators compressing search friction, auction infrastructure providers moving volume across Iberian wholesale markets, and integrated retail-service networks anchoring physical presence. Competitive moves concentrate on platform consolidation for listing density and service bay capacity expansion for certified pre-owned throughput.
Within the auction infrastructure tier, BCA exemplifies cross-border volume movement between Iberian markets. Among digital marketplace operators, Standvirtual and Auto SAPO occupy positions consolidating listing traffic and buyer liquidity. Caetano Retail represents the integrated retail-service archetype, anchoring physical presence with reconditioning and warranty underwriting capabilities in Greater Lisbon.
| Leading Market Players |
|---|
| BCA |
| Nors Group |
| OOYYO Corp |
| AutoAcordo |
| Caetano Retail |
| ALD Automotive |
| Guia do Automóvel |
| Standvirtual |
| Auto SAPO |
| Others |
Pricing and Supply Chain Analysis
Auction-lot throughput scale at BCA's Iberian hubs compresses per-unit procurement costs for Lisbon-Porto dealer networks while simultaneously elevating price floors for certified reconditioning grades. This scale dynamic concentrates margin extraction among integrated retail-service operators with captive service bay capacity, fragmenting pricing power across non-certified inventory tiers.
Pricing Analysis
Long-term fleet offtake contracts between rental operators and dealer groups anchor volume pricing for three-to-five-year-old petrol and diesel inventory entering wholesale channels. Price differentiation rests on certification grade — Certified Pre-Owned warranties command structural premiums over as-is peer-to-peer transactions — while cost compression in non-certified tiers intensifies from platform-enabled price transparency. Corporate fleet buyers exhibit lowest price sensitivity due to embedded financing access, whereas younger demographic cohorts in Coimbra and Porto historic districts drive acute sensitivity in compact hatchback segments.
Supply Chain Analysis
Strategic stockpile preferences dominate fleet operator behavior, with rental companies accelerating ICE vehicle offloading ahead of EU Green Deal phase-out deadlines rather than maintaining depreciating inventory. Supply concentration feeds from Spain, France, and Germany through BCA's cross-border auction infrastructure, with diagnostic equipment and specialized reconditioning tooling representing critical component dependencies. Single-source vulnerability concentrates in certified technician labor pools, constraining throughput expansion despite available auction volume. Distribution runs through digital marketplace platforms, physical dealership networks, and direct peer-to-peer channels in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service bay capacity bottlenecks and certified technician scarcity fragment competitive advantage toward operators with integrated reconditioning infrastructure, compressing returns for asset-light listing platforms.
For Market Incumbents: Secure captive warranty underwriting capabilities and expand service bay throughput in Greater Lisbon to defend margin pools against platform-enabled price transparency. Vertical integration into diagnostic equipment leasing programs addresses technician scarcity while locking in independent dealer dependencies. EU Green Deal regulatory calendar alignment represents the critical threat requiring inventory acquisition timing precision. For New Entrants and Emerging Players: Differentiate on subscription-to-ownership conversion models targeting Algarve tourism-dependent households with flexible tenure structures. The Algarve and Coimbra corridors offer the most penetrable geographic white space, with underdeveloped digital auction infrastructure relative to vehicle ownership density. A go-to-market angle anchored in third-party inspection overlays with embedded financing access bypasses incumbent reconditioning markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated retail-service networks with captive finance penetration and extended warranty attachment. Long-term viability favors operators with service bay capacity expansion runway and technician training pipeline investments. Acquisition target archetype: regional dealership groups with underutilized reconditioning infrastructure. The signal to watch is EU Green Deal phase-out acceleration compressing ICE fleet off-cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Service Bay Capacity Expansion | Addresses certified technician scarcity constraining reconditioning throughput for CPO inventory. |
| Digital Auction Infrastructure Investment | BCA platform integration compresses procurement friction between Iberian wholesale markets. |
| Subscription-to-Ownership Conversion Programs | Rental fleet pilots transition short-term users into certified pre-owned purchases with embedded financing. |
| Warranty-Backed Finance Product Bundling | Extended coverage and maintenance plans extract margin from CPO condition grade differentiation. |
| Charging Infrastructure Certification Alignment | Portugal's energy regulator coordination accelerates electric used car marketability and resale velocity. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with fleet procurement managers, dealership operations directors, certified automotive technicians, digital platform product leads, and auto finance underwriters. Secondary validation drew from vehicle registration databases, EU Green Deal regulatory filings, central bank auto lending disclosures, and auction transaction records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across metropolitan and regional corridor clusters.
Across the analysis window, forecasts applied a cohort-component framework tracking vehicle age, propulsion architecture, and certification tier against fleet renewal cycles and consumer trade-in velocity. Segmentation dimensions modeled include vehicle type, fuel category, condition grade, and sales channel. CAGRs were derived from logistic diffusion curves fitted to historical penetration patterns, with EU Green Deal phase-out calendars and charging infrastructure buildout schedules serving as primary exogenous inputs.
Material uncertainties — regulatory acceleration or delay, technician training pipeline expansion, and electric vehicle fleet off-cycle timing — sit outside the modeled envelope. Forecasts reflect assumptions regarding policy continuity and infrastructure investment execution. Revision becomes warranted when EU Green Deal implementation crosses acceleration thresholds or charging certification requirements shift materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Malaysia Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Qatar Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
China Used Car Market
Used Vehicles
Netherlands Used Car Market