
 Used Cars Market | 2026-2036
Used Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Used Cars Market Analysis
The EU Green Deal is decoupling diesel demand from used vehicle residual values across European wholesale channels. CarMax leverages its centralized reconditioning infrastructure to sustain margin capture on certified pre-owned units. AutoNation anchors its regional footprint through fixed-price digital retailing that reduces negotiation friction. Carvana competes on logistics density, controlling last-mile delivery costs that erode profitability for smaller platforms.
A used car denotes a previously registered motor vehicle transferred through retail or wholesale channels after initial ownership, typically assessed via odometer reading, structural integrity inspection, and powertrain diagnostic scoring to determine resale eligibility and warranty qualification. Certified pre-owned segments command premium pricing due to manufacturer-backed inspection protocols and extended coverage terms that reduce buyer risk. Electric powertrain inventory remains thin relative to gasoline listings, creating supply bottlenecks as battery health verification standards mature. SUV body styles dominate transaction volume in North American secondary markets where utility preferences persist across income tiers.
EPA emissions enforcement and NHTSA safety recall compliance shape vehicle eligibility for interstate resale in the United States. The EU AI Act and GDPR provisions govern automated valuation algorithms and consumer data handling across European digital marketplaces. India's BIS fuel efficiency labeling and state-level roadworthiness mandates filter import eligibility for pre-owned inventory. Stakeholders must monitor how battery degradation certification protocols reshape electric vehicle liquidity and lender collateral policies.
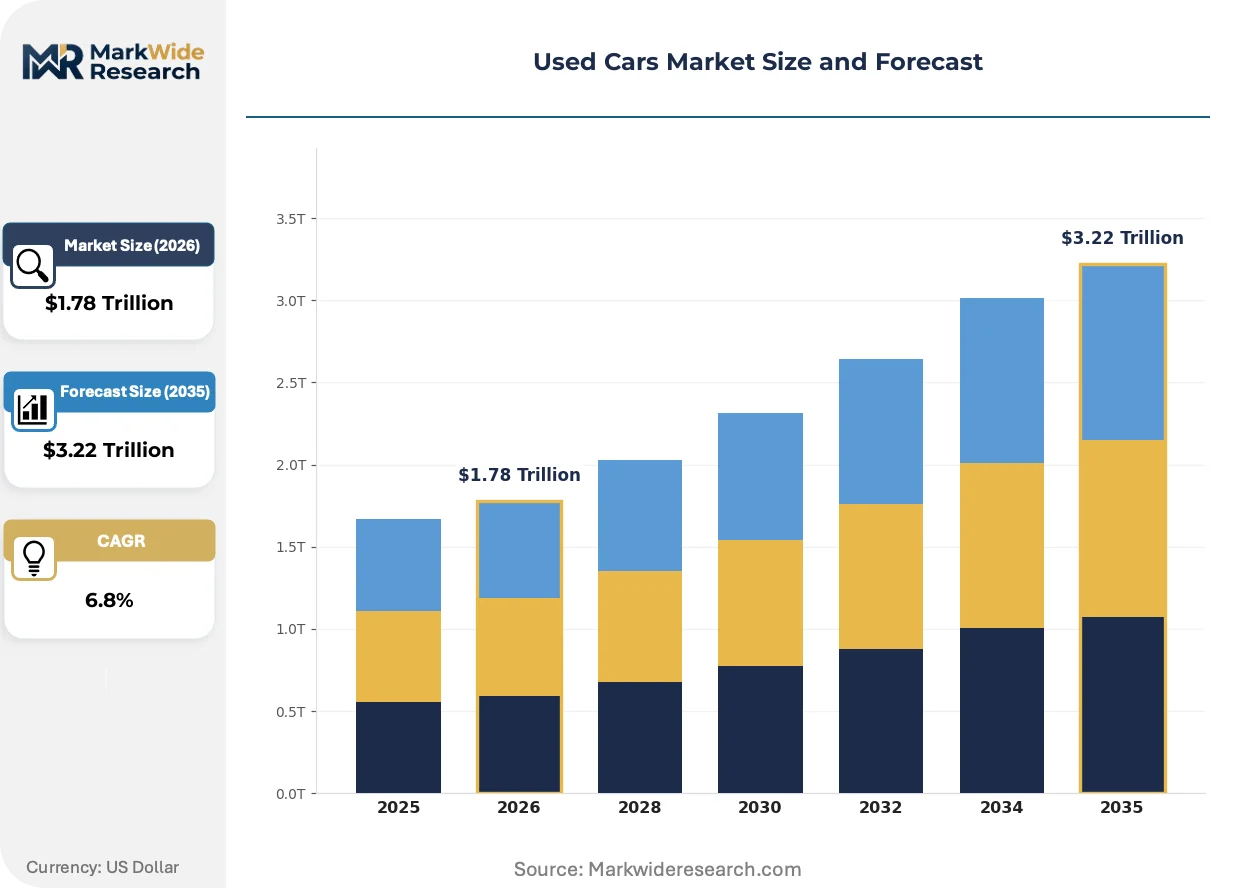
Market Dynamics
Digital title verification platforms are compressing transaction timelines across wholesale channels, while battery health certification protocols reshape lender collateral policies for electric vehicle inventory.
Growth Catalysts
- EU Green Deal decoupling:Diesel residual value collapse accelerates fleet turnover toward gasoline and hybrid units across European wholesale markets.
- Blockchain provenance tracking:Cross-border transaction friction drops as immutable ownership records replace paper-based title transfers.
- Southeast Asia ride-hailing procurement:Fleet operators in Indonesia, Thailand, and Vietnam expand certified pre-owned absorption to manage total cost of ownership pressures.
Market Restraints
- Battery degradation verification gaps:Absence of standardized state-of-health testing limits electric vehicle liquidity and lender confidence.
- Supply concentration in North American SUVs:Utility body style dominance creates inventory mismatch when sedan demand resurfaces.
- NHTSA recall compliance costs:Interstate resale eligibility requires expensive pre-listing safety campaign verification.
Strategic Opportunities
- Indonesia first-time buyer penetration:Underbanked consumer segments create white space for alternative financing and subscription ownership models.
- GDPR-compliant automated valuation:Algorithmic pricing engines that satisfy EU data handling rules capture margin from manual appraisal.
- Manufacturer-backed certification convergence:Extended warranty and inspection protocol standardization unlocks premium pricing across independent dealers.
Industry Challenges
- Diagnostic technician scarcity:Powertrain health assessment expertise lags behind connected vehicle data complexity.
- Cross-border logistics reconfiguration:Title transfer standardization across jurisdictions demands platform-level integration investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Cars Market |
| Market Size in 2026 | $1.78 Trillion |
| Market Size in 2035 | $3.22 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Condition: Certified Pre-Owned, Like New, Good Condition, Fair Condition Engine Type: Gasoline, Diesel, Hybrid, Electric Transmission: Automatic, Manual, CVT, Dual-Clutch Body Style: Sedan, SUV, Hatchback, Coupe |
| Companies Covered | Vroom, Group 1 Automotive, CarMax, Sonic Automotive, Lithia Motors, AutoNation, Shift Technologies, Asbury Automotive Group, Carvana, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Cars Market Emerging Trajectories
Artificial intelligence valuation engines and connected vehicle telemetry are compressing information asymmetry between buyers and sellers, fundamentally altering how trust is manufactured in secondary automotive transactions.
Blockchain-based provenance tracking is rewriting title verification workflows by creating immutable ownership chains that slash fraud exposure. Digital marketplaces in Germany and the Netherlands adopt these protocols fastest, reducing due diligence from days to hours. Wholesale auction houses now face margin compression as direct peer-to-peer transfers bypass traditional intermediaries.
The EU AI Act imposes algorithmic transparency requirements on automated pricing engines deployed across European digital marketplaces. Lenders must audit valuation models for discriminatory bias before integrating them into loan origination workflows. Certified pre-owned segments absorb compliance costs fastest, passing premiums to risk-averse buyers.
Subscription and flexible ownership models displace traditional installment financing among urban millennials in Vietnam and Thailand. Fleet operators and ride-hailing platforms now source directly from off-lease channels, bypassing dealer intermediaries entirely. This procurement pattern shift concentrates volume with platforms capable of direct OEM relationships and captive reconditioning infrastructure.
Used Cars Market Segmentation
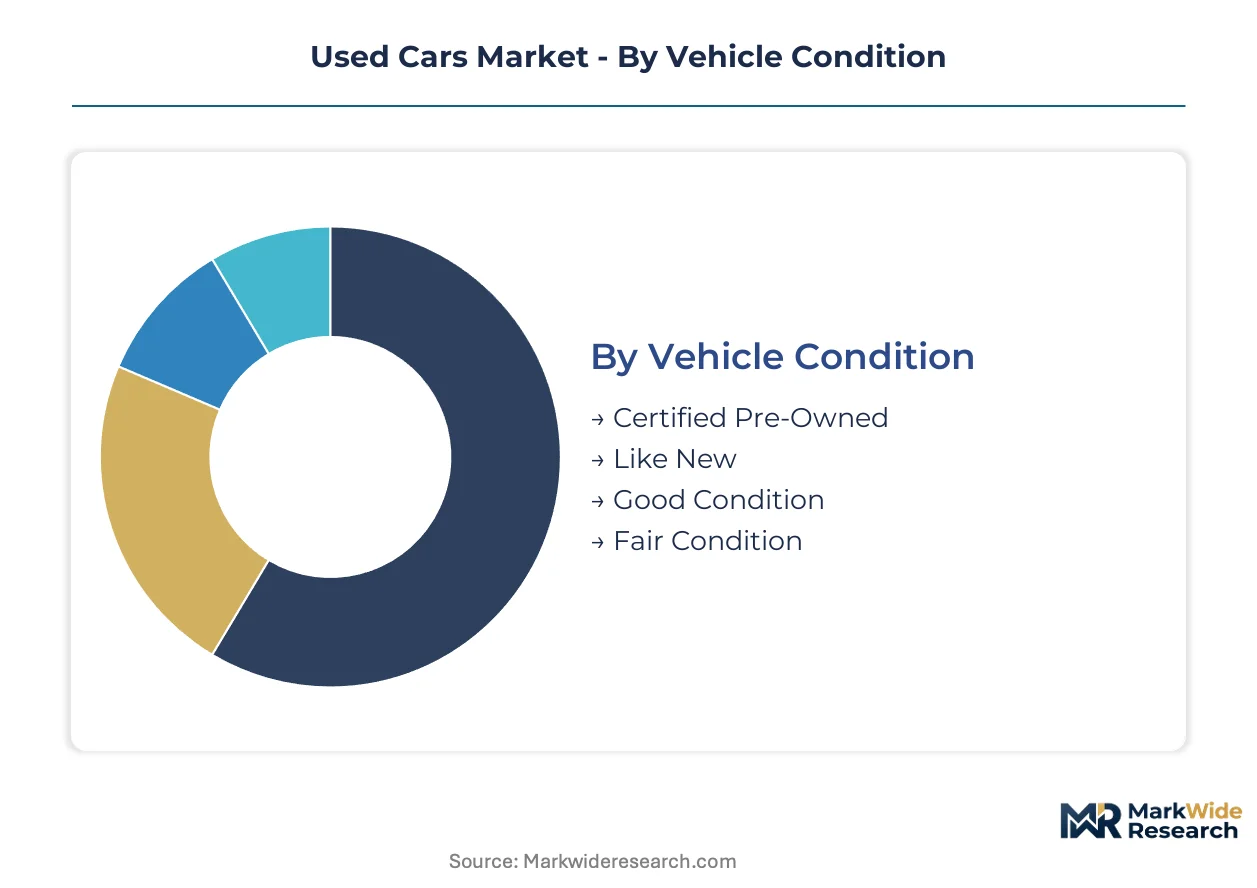
Segmentation in the used cars market determines liquidity velocity, financing eligibility, and residual value capture. Buyers, lenders, and fleet operators each weight condition grades, powertrain risk profiles, and body style utility differently when committing capital.
Vehicle Condition:
Standardization intensity varies sharply across this category, from manufacturer-controlled inspection protocols to unregulated private-party grading.
- Certified Pre-Owned:Factory-backed multi-point inspections and extended warranty coverage reduce buyer risk perception. Fleet operators in Indonesia and Thailand absorb these units fastest to minimize downtime liability under total cost of ownership pressures. Lenders extend preferential advance rates against CPO collateral due to documented maintenance histories.
- Like New:Low-mileage off-lease inventory with minimal wear, typically under 24 months from initial registration. Digital marketplaces in Germany and the Netherlands price these units algorithmically using connected vehicle telemetry rather than manual appraisal.
- Good Condition:Moderate wear acceptable to first-time buyers in Vietnam seeking basic transportation without premium certification costs.
- Fair Condition:Higher-mileage units requiring immediate maintenance, often cash transactions outside formal financing channels.
Leading the category by volume: Good Condition. Growing fastest: Certified Pre-Owned.
Engine Type:
Powertrain selection concentrates risk exposure across battery health uncertainty, emissions compliance costs, and fuel price volatility.
- Gasoline:Dominant transaction volume with established diagnostic protocols and dense reconditioning technician networks. EPA emissions testing requirements filter interstate resale eligibility in the United States.
- Diesel:EU Green Deal decoupling has collapsed residual values across European wholesale channels as fleet operators accelerate turnover toward gasoline and hybrid alternatives.
- Hybrid:Dual-powertrain complexity demands specialized battery and combustion system diagnostics, limiting reconditioning capacity to centralized facilities.
- Electric:Absence of standardized state-of-health testing constrains liquidity and lender confidence, though BIS fuel efficiency labeling in India is beginning to structure import eligibility.
Gasoline commands absolute transaction share. Hybrid is climbing the fastest as battery verification protocols mature.
Transmission:
Mechanical complexity and regional driving preference shape procurement patterns across fleet, retail, and export channels.
- Automatic:Dominates North American secondary markets where stop-and-go traffic patterns favor convenience over fuel efficiency optimization.
- Manual:Concentrated in European enthusiast segments and emerging markets where lower acquisition cost outweighs drivability trade-offs.
- CVT:Fuel efficiency advantages attract Southeast Asian ride-hailing procurement, though belt durability concerns limit warranty extension feasibility.
- Dual-Clutch:Performance-oriented applications with higher reconditioning costs due to mechatronic unit complexity.
Automatic transmission holds the volume lead. CVT is gaining share fastest in high-utilization fleet applications.
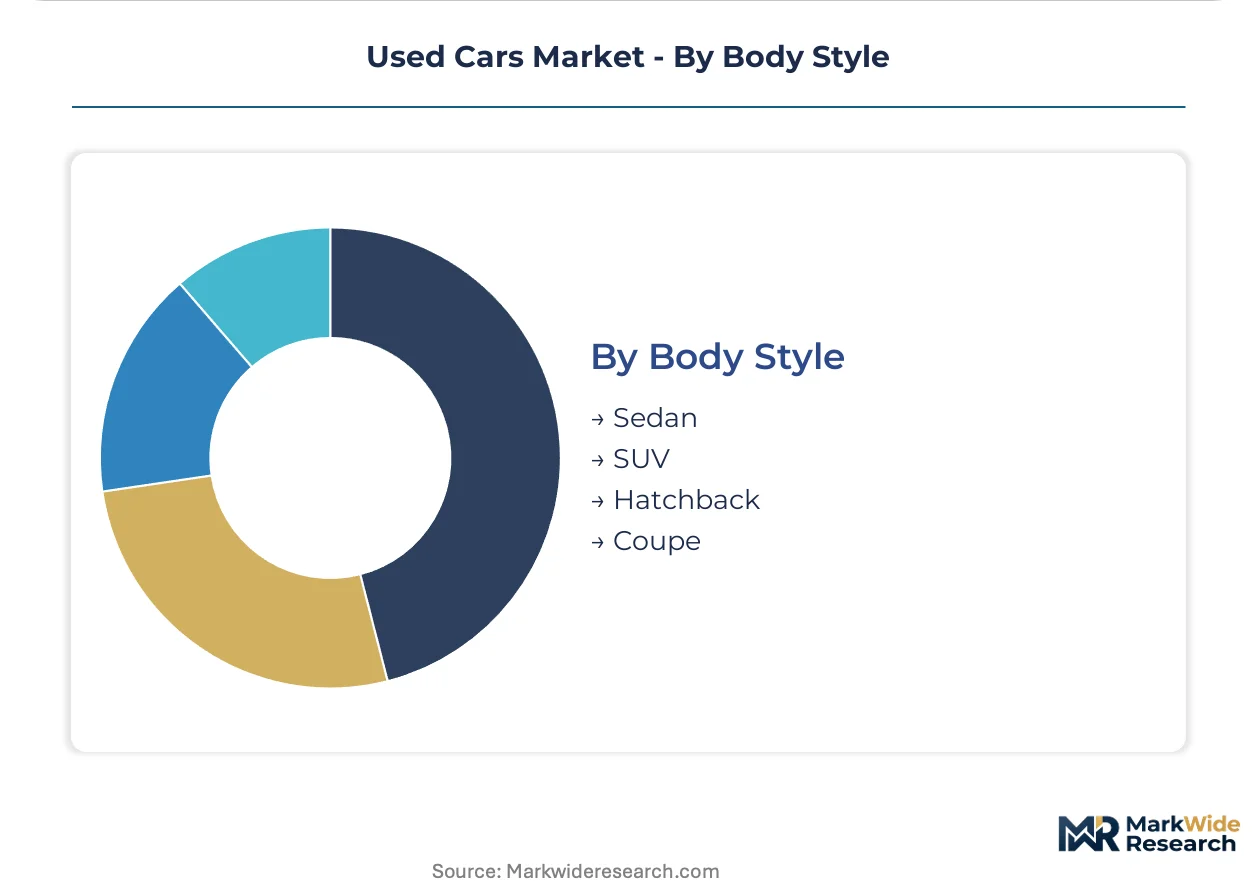
Body Style:
Utility preferences persist across income tiers in North American markets while urban density drives divergence elsewhere.
- SUV:Elevated seating position and cargo flexibility command pricing premiums. Inventory concentration in this segment creates mismatch risk when sedan demand resurfaces.
- Sedan:Declining share in wholesale channels as fleet operators and ride-hailing platforms prioritize passenger capacity and ground clearance.
- Hatchback:Urban parking efficiency drives absorption in Vietnamese and Thai metropolitan markets with limited residential garage penetration.
- Coupe:Niche volume with higher depreciation curves, typically transacting through specialized retail rather than wholesale auction.
SUV body styles lead by transaction count. Hatchback is expanding most quickly in dense Southeast Asian urban corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Used vehicle production concentrates in North American and European wholesale channels, while consumption gravity shifts toward Southeast Asian first-time buyer markets and ride-hailing fleet operators. The United States generates the largest certified pre-owned inventory volume. Indonesia, Thailand, and Vietnam absorb expanding supply as digital platforms compress cross-border transaction friction.
United States
CarMax and Carvana anchor digital retail density in Texas and Florida metros, where suburban sprawl sustains SUV demand across income tiers. NHTSA recall compliance mandates filter interstate resale eligibility through pre-listing safety campaign verification. Atlanta and Phoenix cluster reconditioning infrastructure that feeds nationwide last-mile delivery networks.
Germany
EU Green Deal decoupling has collapsed diesel residual values, accelerating fleet turnover toward gasoline and hybrid units in Bavaria and North Rhine-Westphalia. The EU AI Act imposes algorithmic transparency requirements on automated pricing engines deployed across Berlin and Hamburg digital marketplaces. KBA registration data feeds blockchain-based provenance tracking that compresses title verification timelines.
China
MIIT-connected vehicle telemetry enables algorithmic pricing in Shanghai and Shenzhen secondary markets, reducing manual appraisal dependency. GB standards for battery health certification are structuring electric vehicle liquidity as state-of-health testing protocols mature. Yangtze River Delta clusters dominate cross-provincial wholesale auction volume.
Indonesia
First-time buyer penetration in Jakarta and Surabaya creates white space for alternative financing models as underbanked consumers seek basic transportation. BIS fuel efficiency labeling filters import eligibility for pre-owned inventory from regional trading partners. Ride-hailing platforms source directly from off-lease channels, bypassing traditional dealer intermediaries.
Thailand
Fleet operators in Bangkok and Chiang Mai expand certified pre-owned absorption to manage total cost of ownership pressures under ride-hailing utilization demands. The country's national automotive regulator enforces roadworthiness mandates that standardize reconditioning protocols. Subscription ownership models displace traditional installment financing among urban millennials.
Used Cars Market Vendor Landscape
The competitive structure tilts toward centralized reconditioning specialists with captive logistics networks. Scale advantages concentrate with platforms controlling last-mile delivery density, while smaller dealers face margin compression from direct peer-to-peer transfer growth. Three archetypes dominate: vertically integrated retailers with in-house reconditioning, algorithmic pricing platforms with logistics control, and regional dealer groups with fixed-price digital retailing. M&A activity targets reconditioning capacity and geographic footprint expansion.
Within the centralized infrastructure tier, CarMax exemplifies scale-driven reconditioning integration, while Carvana occupies a position defined by logistics density and direct-to-consumer delivery. AutoNation anchors regional footprint consolidation through fixed-price digital retailing that reduces negotiation friction. These three represent the dominant competitive positioning vectors: reconditioning control, logistics optimization, and regional retail density.
| Leading Market Players |
|---|
| Vroom |
| Group 1 Automotive |
| CarMax |
| Sonic Automotive |
| Lithia Motors |
| AutoNation |
| Shift Technologies |
| Asbury Automotive Group |
| Carvana |
| Others |
Supply Flow & Price Mechanics
Diagnostic technician scarcity in Southeast Asian reconditioning hubs widens labor-cost differentials between centralized CPO facilities and independent dealer networks, compressing margin spreads at the economy tier while premium certification commands widening premiums.
Pricing Analysis
Margin tightening in certified pre-owned segments reflects manufacturer-backed warranty absorption costs and extended inspection protocol investments. Three-tier pricing structure across CPO, like-new, and good-condition grades separates collateral-eligible inventory from cash-market transactions. Cost-down pressure on fair-condition units accelerates because first-time buyers in Vietnam and Indonesia prioritize acquisition price over after-sales coverage. Fleet operators exhibit lowest price sensitivity due to total cost of ownership optimization, while underbanked urban millennials demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with battery health certification protocol providers concentrated in China, Germany, and South Korea. Used vehicle inventory draws from off-lease channels, rental fleet rotations, and trade-in aggregations as primary feedstock. Tariff exposure on cross-border title transfer standardization creates regulatory friction across ASEAN wholesale corridors. Distribution runs through digital marketplace platforms with captive logistics networks, bypassing traditional auction intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Used vehicle supply remains constrained by diagnostic technician scarcity, propping residual values across certified segments as reconditioning throughput hits workforce ceilings.
For Market Incumbents: Deploy captive reconditioning infrastructure to defend margin capture against direct peer-to-peer transfer growth. Consolidate regional footprint through fixed-price digital retailing that reduces negotiation friction. Absorb EU AI Act compliance costs fastest to capture algorithmic pricing premiums before smaller platforms achieve audit readiness. For New Entrants and Emerging Players: Underbanked first-time buyers in Indonesian secondary cities represent the most penetrable white-space segment. Alternative financing models and subscription ownership structures bypass traditional credit scoring barriers. Go-to-market through ride-hailing fleet procurement channels bypasses dealer intermediary costs entirely. For Investors and Strategic Acquirers: Re-rating potential sits with centralized reconditioning specialists given battery health certification protocol standardization. Five-to-ten-year viability hinges on electric vehicle liquidity unlocking as state-of-health testing matures. Watch for BIS fuel efficiency labeling adoption across India as inflection indicator for regional import eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Title Verification Deployment | Immutable ownership records slash fraud exposure and compress due diligence timelines across German and Dutch digital marketplaces. |
| Certified Pre-Owned Program Expansion | Factory-backed inspection protocols reduce buyer risk perception and unlock preferential lender advance rates. |
| Battery Health Certification Investment | Standardized state-of-health testing protocols address electric vehicle liquidity constraints and reshape collateral policies. |
| Fixed-Price Digital Retailing Rollout | Negotiation friction reduction captures margin from price-sensitive first-time buyers in Southeast Asian urban corridors. |
| Cross-Border Logistics Network Buildout | Last-mile delivery density controls cost erosion that compresses profitability for smaller peer-to-peer platforms. |
Methodological Framework
Document review covered vehicle registration databases, customs trade records, and OEM off-lease disclosures, complemented by interviews with fleet procurement managers, reconditioning facility operators, digital marketplace executives, and captive finance underwriters. Secondary validation drew from NHTSA recall filings, EU KBA registration statistics, and ASEAN automotive association production data. Bottom-up transaction volume modeling triangulated against top-down macroeconomic absorption forecasts.
Historical registration trends cross-referenced against panel input from wholesale auction houses and ride-hailing platform fleet directors. Segmentation dimensions spanned vehicle condition grade, powertrain architecture, body style utility, and regional regulatory cluster across the projection horizon. CAGRs derived from regression analysis against GDP elasticity coefficients and vehicle ownership penetration saturation curves. Battery degradation curves and residual value depreciation schedules served as automotive-specific forecast inputs.
Revisions become necessary when battery health certification protocol standardization accelerates or EU Green Deal decoupling intensifies diesel residual collapse beyond modeled trajectories. Deviation in Southeast Asian ride-hailing fleet procurement rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Used Cars in Russia Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
Canada Used Car Market
Used Vehicles
Italy Used Car Market
Used Vehicles
Qatar Used Car Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Used Semi Truck Market
Used Vehicles
United Arab Emirates Used Car Market