
 Regulatory Reporting Solutions Market | 2026-2036
Regulatory Reporting Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
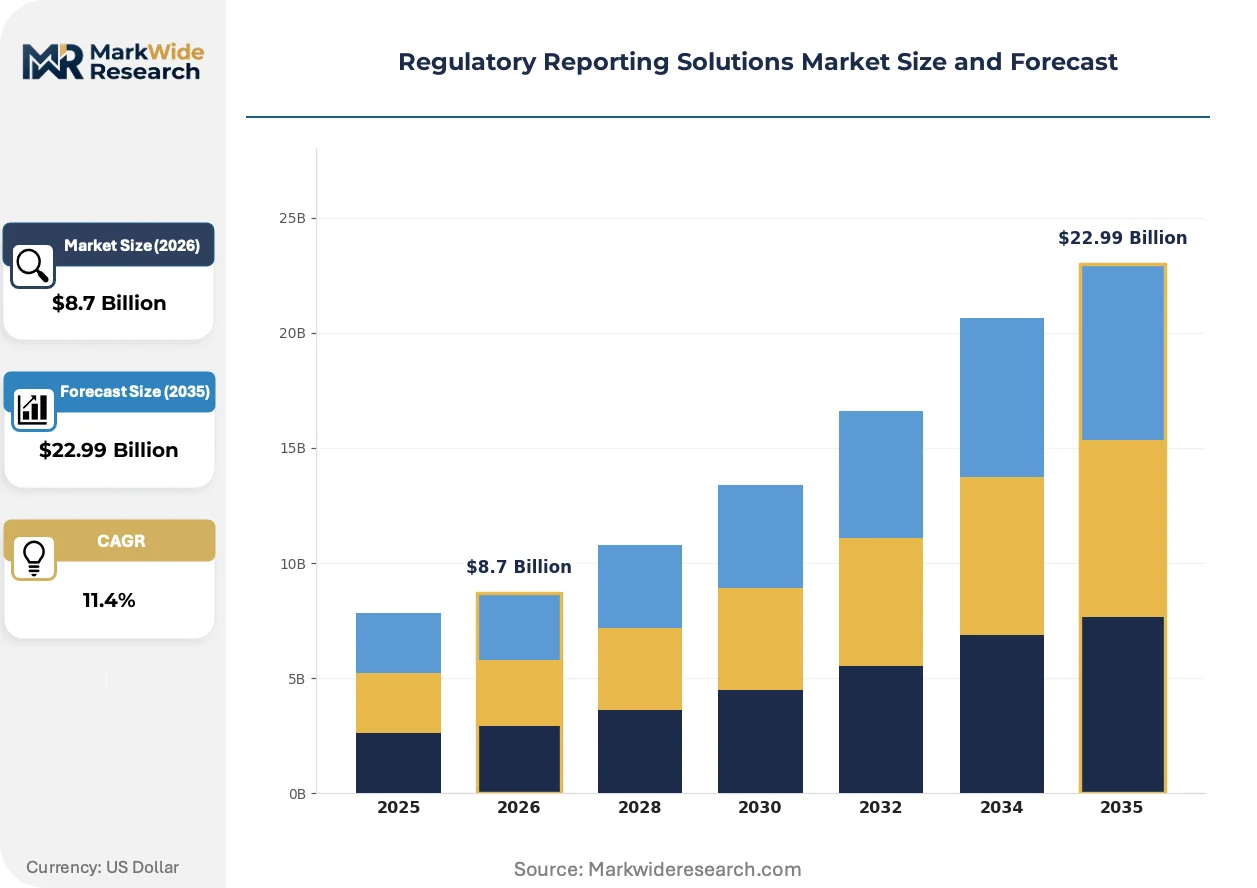
Regulatory Reporting Solutions Market Outlook
Subscription-based managed services is pivoting vendor economics toward recurring revenue models in regulatory reporting. Accenture plc leverages its consulting depth to anchor multi-year compliance transformation contracts across tier-one banks. Bloomberg LP sustains real-time data integration advantages that differentiate its terminal-linked reporting suites. Wolters Kluwer N.V. specializes in tax and accounting rule libraries that dominate European compliance workflows.
Regulatory reporting solutions encompass software platforms and services that automate the collection, validation, formatting, and submission of structured data to government agencies and standard-setting bodies, typically operating through XBRL taxonomy engines, API-connected data warehouses, and audit-trail architectures designed to satisfy granular lineage requirements. Cloud-based and SaaS deployments are capturing the fastest expansion as financial institutions retire legacy on-premises infrastructure, while hybrid configurations retain strong positioning among corporations navigating jurisdictional data-residency constraints. Compliance area segmentation shows securities regulations commanding the deepest incumbent spend, though environmental reporting is emerging as a high-velocity adjacent demand pool tied to sustainability disclosure mandates.
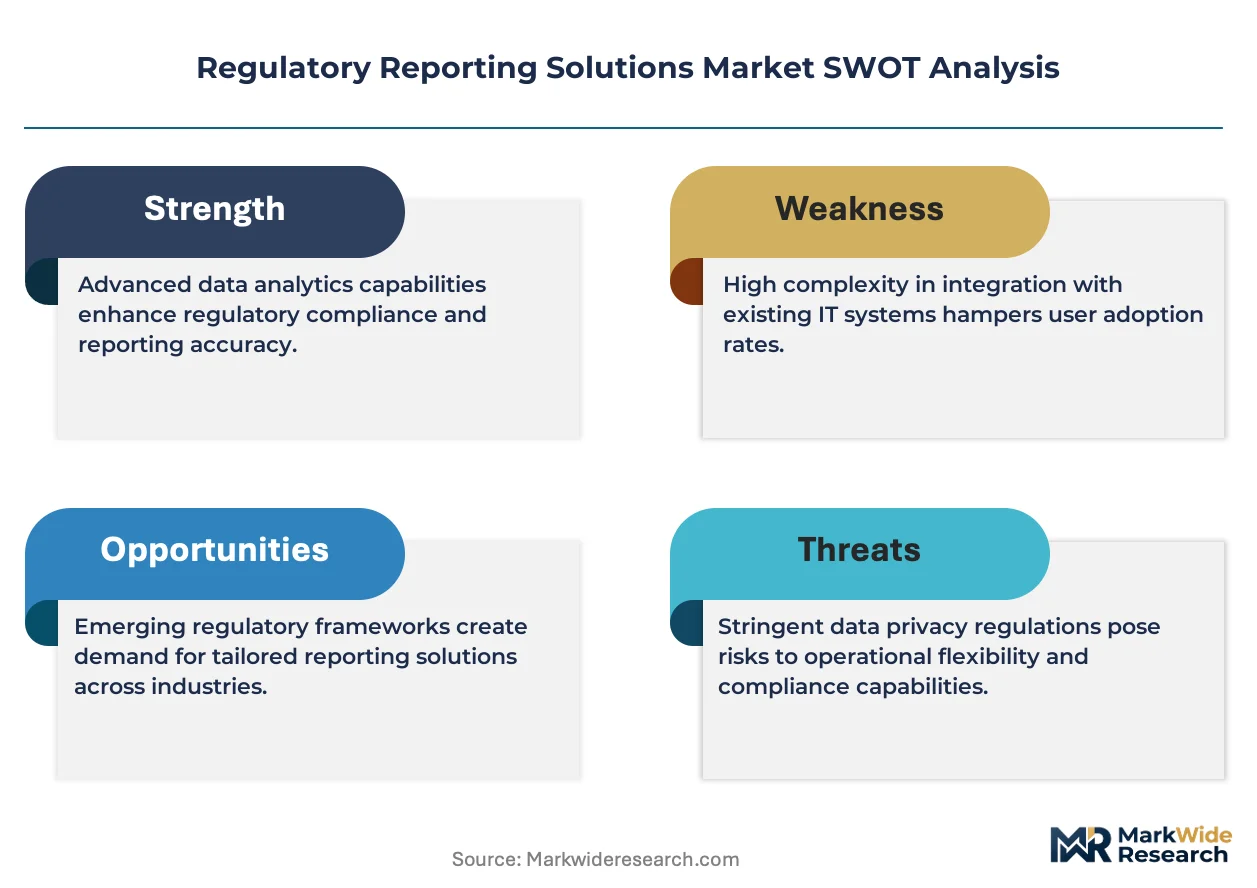
The SEC, EBA, and ECB collectively shape product roadmaps through iterative rulemaking on data granularity, submission timelines, and machine-readability standards that force platform refreshes at each implementation phase. Firms must map their current architecture against pending taxonomy updates to avoid last-mile integration failures. Stakeholders should monitor how AI-assisted validation tools reshape service delivery economics before committing to long-term vendor contracts.
Market Dynamics
Machine-readability mandates from the SEC and EBA are forcing financial institutions to retire legacy spreadsheet-based reporting workflows and adopt API-native validation architectures that embed compliance logic directly into data pipelines.
Growth Catalysts
- CSRD Mandate Rollout:European corporates must disclose sustainability metrics under granular taxonomy requirements, creating immediate demand for environmental reporting modules that integrate with existing financial platforms.
- Cloud Migration Acceleration:Tier-one banks are consolidating fragmented on-premises systems into unified SaaS deployments to reduce maintenance overhead and enable real-time regulatory updates.
- Singapore's Fintech Hub Status:The Monetary Authority of Singapore's progressive sandbox framework attracts regtech vendors establishing Asia-Pacific delivery centers, concentrating regional implementation expertise.
Market Restraints
- Data Residency Fragmentation:Jurisdictional constraints in Germany, China, and Russia prevent pure-cloud architectures, forcing expensive hybrid infrastructure that duplicates compliance logic across environments.
- XBRL Taxonomy Volatility:Annual updates to EBA and SEC filing specifications require continuous platform reconfiguration, locking vendors into perpetual engineering cycles that compress margins.
- Specialized Talent Scarcity:The intersection of regulatory expertise and data engineering skills concentrates in London, New York, and Singapore, inflating implementation costs for projects elsewhere.
Strategic Opportunities
- Insurance Sector Penetration:Solvency II reporting requirements across EU member states remain underserved by dedicated platforms, presenting white space for purpose-built capital adequacy solutions.
- AI-Assisted Validation Convergence:Natural language processing engines combined with graph-based lineage tracking enable anomaly detection in narrative disclosures, opening premium service tiers.
- India's Digital Public Infrastructure:The RBI's Account Aggregator framework and forthcoming corporate disclosure digitization create entry points for vendors adapting to India's unique identifier systems.
Industry Challenges
- Legacy System Entrenchment:Core banking platforms at established institutions embed decades of customized reporting logic, making API extraction and cloud migration prohibitively complex for mid-tier budgets.
- Certification Timeline Compression:Vendors must achieve SOC 2 Type II and ISO 27001 attestations simultaneously across multiple jurisdictions to satisfy procurement requirements, stretching compliance teams thin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regulatory Reporting Solutions Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premises, Hybrid, SaaS End User: Financial Institutions, Corporations, Public Sector, Compliance Agencies Deployment Model: Managed Services, Professional Services, Self-Service, Direct Access Compliance Area: Tax Reporting, Securities Regulations, Environmental, Health & Safety |
| Companies Covered | Accenture plc, International Business Machines Corporation, Deloitte Touche Tohmatsu Limited, PricewaterhouseCoopers International Limited, Ernst & Young Global Limited, AxiomSL Holdings Inc., Bloomberg LP, Broadridge Financial Solutions Inc., Wolters Kluwer N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regulatory Reporting Solutions Market Strategic Shifts
Regulatory technology vendors are embedding predictive compliance capabilities that anticipate rule changes before formal implementation, shifting competitive advantage from reactive adaptation to proactive architecture design.
Continuous monitoring platforms are expanding into securities lending and repo markets, where real-time position reporting to the SEC and FCA replaces batch-based submissions. Prime brokers and custody banks are adopting these systems fastest, compressing the traditional quarterly reporting cycle into intraday dashboards that flag threshold breaches before settlement.
The EU's Digital Operational Resilience Act (DORA) mandates granular incident reporting timelines for financial entities, forcing vendors to reengineer audit-trail architectures. ICT service providers must now demonstrate end-to-end observability of third-party dependencies, with the ECB's supervisory expectations driving demand for integrated risk and compliance consoles.
Asset managers are unbundling compliance service procurement from bundled technology suites, selecting best-of-breed validation engines and data providers separately. This fragmentation is most visible in Luxembourg and Dublin fund domiciles, where specialized ESG data vendors now win standalone contracts previously captured by incumbent platform providers.
Regulatory Reporting Solutions Market Segmentation
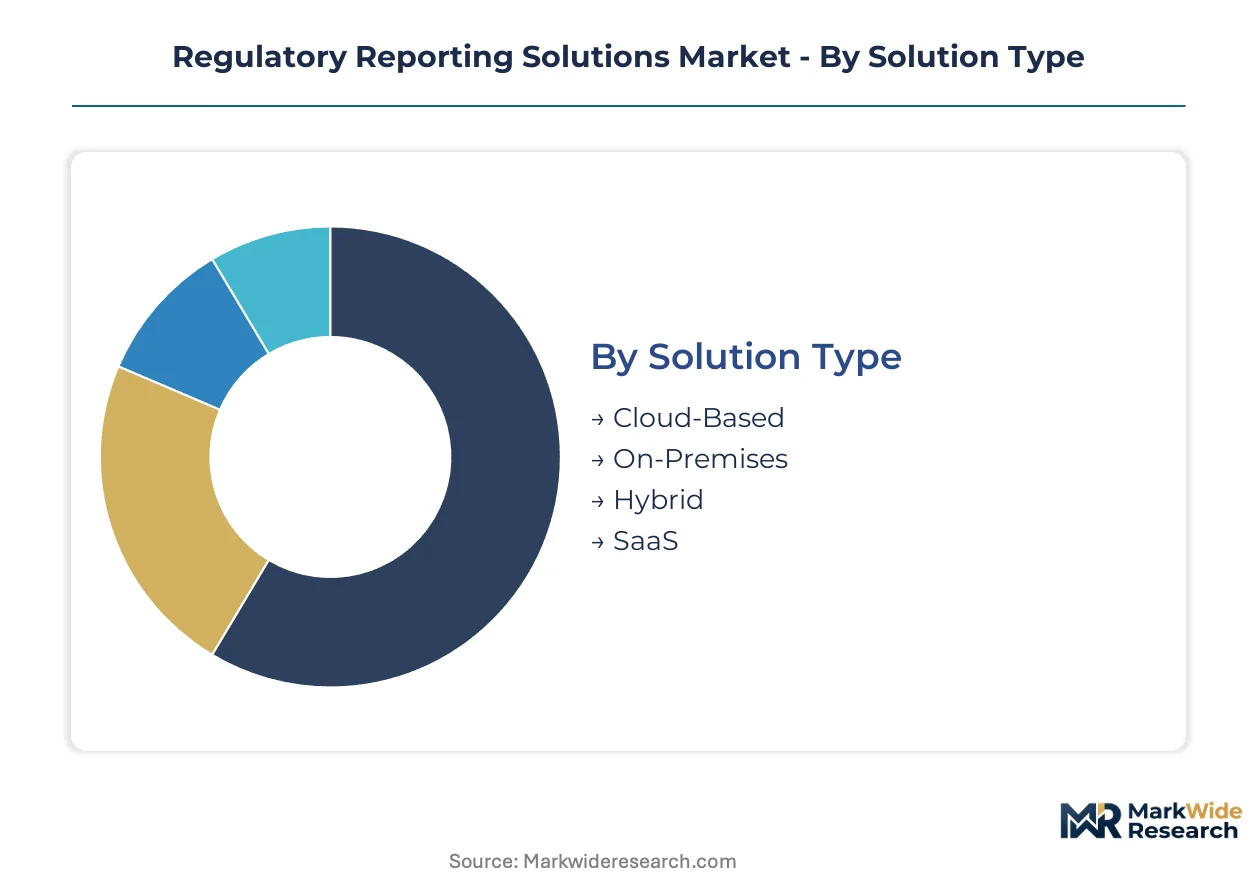
Platform refresh cycles dominate procurement decisions as financial institutions retire legacy architectures ahead of SEC and EBA machine-readability deadlines. Segmentation reveals distinct upgrade patterns across deployment modes, end-user sophistication, and compliance domain complexity.
Solution Type:
Migration economics drive replacement sequencing, with total cost of ownership calculations favoring cloud-native architectures for new installations while hybrid configurations preserve existing investments.
- Cloud-Based:Multi-tenant architectures with auto-scaling compute clusters handle peak filing volumes without capital expenditure spikes. Demand concentrates among mid-tier asset managers in Singapore and Luxembourg seeking SOC 2 attestation without dedicated infrastructure teams.
- On-Premises:Dedicated hardware installations with localized XBRL taxonomy engines maintain air-gapped environments for classified data. German universal banks and Russian state-owned institutions mandate these configurations under jurisdictional data residency statutes.
- Hybrid:Split architectures process sensitive client data on-premises while pushing aggregated analytics to cloud dashboards. This model dominates tier-one banks navigating cross-border regulatory arbitrage between UK and EU supervisory regimes.
- SaaS:Browser-accessible platforms with subscription metering eliminate version control overhead for quarterly taxonomy updates. Regional banks in the United States and Australia adopt these fastest for cost predictability.
Cloud-Based sits at the top of the volume ranking, with SaaS climbing the fastest.
End User:
Procurement sophistication varies sharply by organizational type, with regulatory sophistication dictating service tier selection and integration depth.
- Financial Institutions:Investment banks, commercial lenders, and insurers with dedicated compliance functions demand API-native validation engines embedding directly into trading systems. Their procurement favors multi-year transformation contracts with Accenture and Bloomberg for end-to-end coverage.
- Corporations:Non-financial entities facing CSRD sustainability disclosure mandates for the first time seek modular environmental reporting modules. German automotive suppliers and French luxury goods houses drive near-term demand for ESG taxonomy integration.
- Public Sector:Government pension funds and sovereign wealth vehicles require audit-trail architectures satisfying public procurement transparency rules. Singapore's GIC and Norway's NBIM exemplify this segment's emphasis on lineage documentation.
- Compliance Agencies:Regulatory bodies themselves purchase vendor platforms to validate incoming submissions, with the SEC and ECB contracting specialized firms for taxonomy conformance testing.
Financial Institutions anchor absolute spending, with Corporations expanding most quickly.
Deployment Model:
Service delivery economics reshape vendor margins as recurring revenue models displace perpetual license arrangements.
- Managed Services:Full outsourcing of data collection, validation, and submission to vendor-operated centers. Tier-one banks in London and New York favor this for Solvency II and Basel III complexity.
- Professional Services:Project-based implementation support for taxonomy mapping and legacy system extraction. This model peaks during regulatory transition windows.
- Self-Service:Client-operated platforms with vendor-provided training and documentation. Mid-market insurers in Germany and the Netherlands select this for cost control.
- Direct Access:Terminal-integrated reporting suites with real-time data feeds. Bloomberg LP dominates this segment through existing terminal subscriptions.
Managed Services commands the largest revenue pool, with Self-Service gaining share fastest among cost-conscious buyers.
Compliance Area:
Regulatory intensity and penalty severity determine platform investment priority across domains.
- Tax Reporting:Granular transaction-level disclosure requirements for transfer pricing and country-by-country reporting. Wolters Kluwer's rule libraries dominate European workflows.
- Securities Regulations:Position reporting, transaction reporting, and market abuse surveillance with real-time thresholds. The SEC's Consolidated Audit Trail and FCA's MiFID II implementation drive deepest incumbent spend.
- Environmental:CSRD-mandated sustainability metrics with XBRL taxonomy alignment. This domain shows steepest expansion trajectory as first-time reporters enter the market.
- Health & Safety:Occupational incident reporting and workplace compliance documentation. Manufacturing conglomerates in Japan and Germany maintain steady demand.
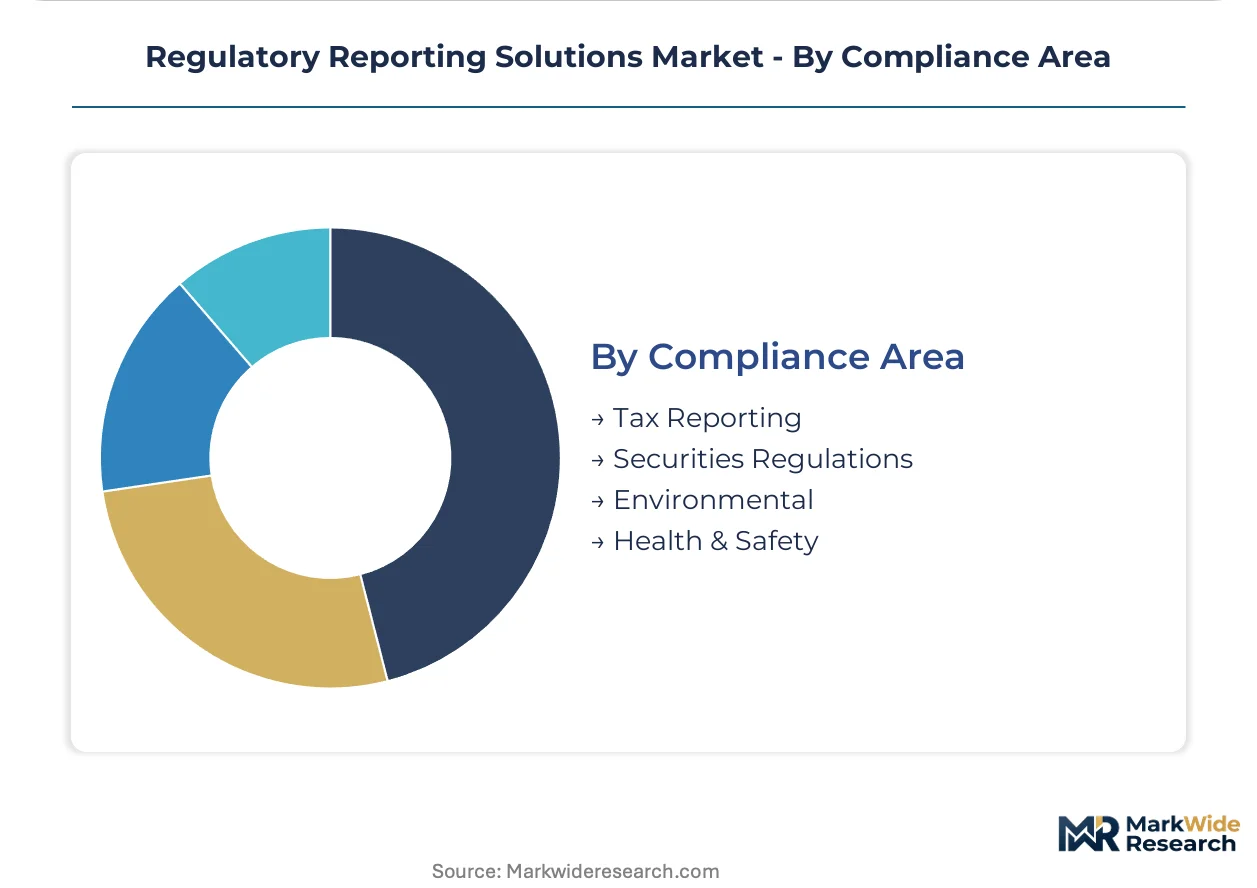
Securities Regulations sits at the top of the volume ranking, with Environmental climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance arbitrage is reshaping vendor deployment strategies as financial institutions migrate reporting operations toward jurisdictions with streamlined regulatory frameworks and established fintech infrastructure. Singapore and Luxembourg attract disproportionate platform investment due to sandbox licensing and fund domicile concentration. Germany and the United States retain premium pricing power through supervisory stringency that justifies sophisticated validation architectures.
United States
Investment banks and asset managers drive platform refresh cycles ahead of SEC machine-readability deadlines. The Consolidated Audit Trail implementation forces real-time transaction reporting infrastructure upgrades. New York's financial district concentrates vendor implementation teams serving tier-one institutions.
Germany
Universal banks mandate hybrid cloud configurations under data residency statutes while automotive suppliers confront first-time CSRD sustainability disclosures. BaFin's granular supervisory expectations sustain premium pricing for validation engines. Frankfurt's regtech cluster anchors European delivery centers for global vendors.
Singapore
The Monetary Authority of Singapore's sandbox framework attracts Asia-Pacific headquarters for compliance platform providers. Fund administrators in the city-state adopt SaaS deployments fastest for cost predictability. Marina Bay's fintech district concentrates implementation expertise serving regional asset managers.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks sustains demand for jurisdiction-specific reporting modules. The FCA's MiFID II implementation drives continuous monitoring platform adoption. London's Square Mile retains talent density for complex Solvency II and Basel III transformations.
India
The RBI's Account Aggregator framework creates entry points for vendors adapting to unique identifier systems. Corporate disclosure digitization mandates expand addressable market beyond financial institutions. Mumbai's BFSI corridor attracts implementation partnerships with domestic IT services firms.
Regulatory Reporting Solutions Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consulting-anchored platforms capturing multi-year transformation contracts while data-terminal incumbents defend integrated reporting suites. Market structure tilts toward consolidated tier-one positions in securities regulation modules, with fragmentation persisting in environmental reporting niches. Three archetypes dominate: consulting-led system integrators, data-feed-integrated terminal providers, and specialized tax-rule library vendors. Competitive moves concentrate on API-native architecture development and managed service outsourcing arrangements.
Within the consulting-led tier, Accenture plc and Deloitte Touche Tohmatsu Limited exemplify multi-year compliance transformation anchors. Bloomberg LP occupies a distinct position linking terminal subscriptions to real-time reporting infrastructure. Wolters Kluwer N.V. represents the specialized-rule-library archetype dominating European tax and accounting workflows.
| Leading Market Players |
|---|
| Accenture plc |
| International Business Machines Corporation |
| Deloitte Touche Tohmatsu Limited |
| PricewaterhouseCoopers International Limited |
| Ernst & Young Global Limited |
| AxiomSL Holdings Inc. |
| Bloomberg LP |
| Broadridge Financial Solutions Inc. |
| Wolters Kluwer N.V. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists now dominate the vendor landscape, concentrating platform ownership under fewer balance sheets and enforcing pricing discipline through standardized managed-service bundles. This ownership pattern tightens supply-side coordination while pushing subscription economics toward longer contract tenures that lock in recurring revenue streams.
Pricing Analysis
Capacity additions in Singapore and Luxembourg are reshaping price floors for cloud-native deployments as new data centers reduce regional hosting premiums. Three-tier pricing structure across premium, standard, and economy levels prevails, with differentiation driven by SOC 2 Type II certification status and API integration depth. Cost compression in the self-service tier is intensifying because mid-tier banks demand predictable quarterly spend. Regional banks in Australia exhibit highest price sensitivity; tier-one institutions in New York and London show least.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in pure-software markets, though hybrid deployments create hardware refresh cycles for on-premises taxonomy engines that vendors now manage as reverse-logistics services. Engineering talent concentrates in the United States, the United Kingdom, and Singapore, with cloud infrastructure drawing from Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Single-source vulnerability sits with XBRL taxonomy update pipelines controlled by EBA and SEC release schedules. Distribution runs through direct enterprise sales teams and systems-integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where each machine-readability mandate from the SEC or EBA forces platform refreshes that expand annual contract values. The CSRD rollout across European corporates represents the most significant demand accelerator currently visible.
For Market Incumbents: Lock in multi-year transformation contracts before taxonomy volatility peaks, embedding automatic update clauses that capture EBA and SEC specification changes. Anchor consulting depth against emerging API-native challengers by acquiring specialized ESG data vendors in Luxembourg and Dublin fund domiciles. Certification investment in ISO 27001 and SOC 2 Type II across multiple jurisdictions preserves procurement eligibility.
For New Entrants and Emerging Players: CSRD in Germany opens a window for modular environmental reporting modules that integrate with existing financial platforms without displacing incumbent core systems. Target first-time corporate reporters in automotive supply chains and luxury goods houses seeking standalone ESG taxonomy solutions. Go-to-market through the RBI's Account Aggregator framework partnerships in India leverages unique identifier system adaptation as differentiation.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized tax-rule library vendors with European compliance workflow dominance but limited Asia-Pacific presence. Long-term viability hinges on recurring revenue share exceeding perpetual license dependency. Acquisition target archetype: regional SaaS providers with managed-service attach rates below 40 percent. Monitor AI-assisted validation tool adoption curves as inflection indicator for service delivery economics disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Architecture Development | EBA machine-readability deadlines force retirement of spreadsheet-based workflows at tier-one banks. |
| Managed Service Outsourcing Arrangements | Singapore's MAS sandbox framework attracts regional delivery centers for Asia-Pacific expansion. |
| AI-Assisted Validation Convergence | NLP engines with graph-based lineage tracking enable premium anomaly detection in narrative disclosures. |
| ESG Data Vendor Acquisition | Luxembourg and Dublin fund domiciles fragment compliance procurement away from bundled suites. |
| Hybrid Cloud Configuration Engineering | German data residency statutes mandate split architectures processing sensitive client data on-premises. |
Study Parameters
Coverage spans the United States, Germany, Singapore, the United Kingdom, and India, with primary inputs from each market informing segment-specific demand assumptions. The study combines structured interviews with compliance officers at tier-one banks, regulatory affairs leads at asset managers, platform engineers at regtech vendors, and procurement directors at insurance groups with secondary validation from SEC filings, EBA technical standards, CSRD implementation guidance, and XBRL taxonomy release documentation. Bottom-up deployment counts and top-down regulatory mandate sizing were triangulated to anchor volume estimates.
Rate-of-change decomposition separates baseline replacement demand from incremental CSRD-driven expansion across the projection horizon. Segmentation dimensions modeled include deployment mode, end-user sophistication, compliance domain complexity, and regional regulatory cluster intensity. CAGRs were derived from installation base evolution and average revenue per account trajectories, with taxonomy update frequency and cloud migration velocity as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt XBRL specification changes or sovereign data-localization mandates. Practitioners should monitor EBA and SEC rulemaking calendars, AI validation tool adoption curves, and Singapore MAS licensing announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
United States Sales Tax Compliance Software Market
Regulatory Compliance Technology
General Data Protection Regulation (GDPR) Market
Regulatory Compliance Technology
Regulatory Change Management Software Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market
Regulatory Compliance Technology
Management System Certification Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
US Anti Money Laundering Solution Market
Regulatory Compliance Technology
Cross-Border Customs and Trade Compliance Orchestration Platforms Market
Regulatory Compliance Technology
Regtech Software Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
Compliance and Traceability Solutions Market
Regulatory Compliance Technology
Global Regulatory Technology (Regtech) Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
Nordic Regulatory Affairs Market