
 Service Fulfillment Market | 2026-2036
Service Fulfillment Market Size, Share, and Industry Trends Forecast 2026-2036
Service Fulfillment Market Intelligence
The capital-intensity divergence between legacy on-premise deployers and cloud-native platform builders is redrawing competitive boundaries in service fulfillment. Cisco Systems leverages its embedded network infrastructure presence to sustain hardware-software bundling advantages across telecommunications deployments. Ericsson anchors its position through deep 3GPP standardization involvement and carrier-grade reliability credentials in mobile network provisioning. Accenture PLC differentiates via consulting-led transformation engagements that integrate order management with enterprise ERP modernization.
Service fulfillment encompasses the technical systems and operational workflows that activate, configure, and sustain commercial services from order capture through delivery confirmation, typically orchestrating inventory databases, workforce scheduling engines, and real-time status APIs across distributed architectures. Its primary commercial purpose is to compress order-to-activation intervals while eliminating manual handoffs that introduce errors and delay revenue recognition. Cloud-based platforms now lead technology adoption as enterprises abandon capital-heavy on-premise stacks for subscription scalability, while AI-powered automation represents the fastest-expanding capability layer as natural language processing and predictive routing reduce exception handling costs. Order management retains the largest margin pool due to its position at the transaction origin point where pricing authority concentrates.
The Federal Communications Commission shapes North American market access through network reliability and data security requirements that elevate platform resilience standards, while the EU AI Act imposes algorithmic transparency obligations on automated decision systems used in customer support and logistics planning workflows. India's Telecom Regulatory Authority and BIS certification mandates are tightening data localization rules that influence cloud architecture decisions for multinational deployments. Stakeholders must monitor how divergent regulatory timelines for AI governance create compliance fragmentation that favors modular platform architectures over monolithic stacks.
Market Dynamics
Telecommunications operators are dismantling monolithic fulfillment stacks in favor of API-first microservices architectures that decouple order management from network inventory systems, compressing provisioning cycles from days to minutes.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises face algorithmic transparency requirements for automated customer support workflows, forcing platform upgrades that expand addressable market for compliant vendors.
- 5G standalone network rollouts:Mobile operators require real-time service orchestration capabilities that legacy provisioning systems cannot deliver, creating replacement demand across Germany, South Korea, and the United States.
- Intent-based networking:Self-configuring network policies reduce manual provisioning touchpoints, enabling telecoms to scale service velocity without linear headcount expansion.
Market Restraints
- Specialized engineering talent scarcity:Cloud-native fulfillment architecture skills concentrate in Silicon Valley, Tel Aviv, and Bangalore clusters, inflating implementation costs for operators elsewhere.
- Legacy system technical debt:Decades-old inventory databases lack real-time API exposure, forcing expensive middleware layers that erode cloud migration ROI.
- Data localization compliance fragmentation:India's TRAI mandates and China's cybersecurity law impose conflicting sovereignty requirements on multinational platform deployments.
Strategic Opportunities
- Edge computing service orchestration:Distributed cloud infrastructure requires localized fulfillment nodes, opening greenfield deployments in secondary metropolitan markets.
- Converged billing-fulfillment platforms:Integration of usage metering with service activation creates stickier vendor relationships and expands per-account revenue capture.
- Private 5G network provisioning:Manufacturing and logistics campuses in Germany and Japan seek turnkey fulfillment solutions for captive wireless deployments.
Industry Challenges
- Multi-vendor integration complexity:Heterogeneous network equipment from disparate suppliers demands custom adapter development that prolongs deployment timelines.
- API standardization gaps:Absence of unified TM Forum Open APIs across all network layers forces bilateral integration agreements that constrain scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Fulfillment Market |
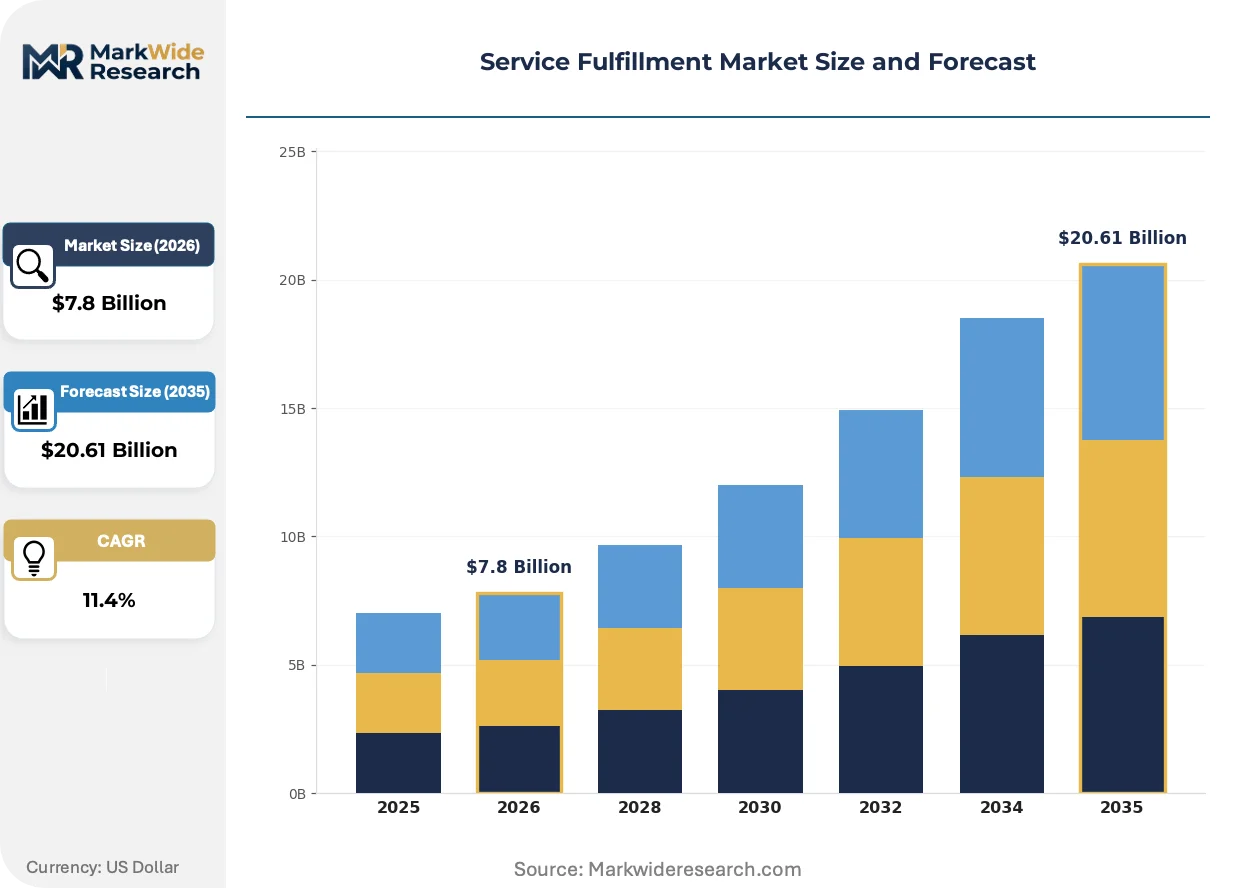
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Order Management, Customer Support, Inventory Coordination, Logistics Planning, Payment Processing End User: E-Commerce Merchants, Telecommunications Firms, Financial Institutions, Hospitality Chains, Educational Organizations Distribution Channel: Online Portals, Direct Sales, Third-Party Marketplaces, Franchise Networks, Mobile Applications Technology: Cloud-Based Platforms, AI-Powered Automation, Blockchain Integration, Robotic Process Automation, API Connectivity |
| Companies Covered | Comarch SA, Accenture PLC, Cisco Systems, Infosys Limited, TATA Communications, Oracle, Ericsson, IBM, Alcatel-Lucent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Fulfillment Market Strategic Shifts & Innovations
Service fulfillment architectures are pivoting from transaction processing engines toward predictive orchestration platforms that anticipate demand patterns and pre-stage network resources before order capture.
Cloud-native containerization is supplanting virtual machine-based deployment models in telecommunications fulfillment stacks. Tier-1 mobile operators in South Korea and Germany are migrating production workloads to Kubernetes-orchestrated microservices, shrinking infrastructure provisioning from weeks to hours. This architectural shift is supplanting traditional vendor lock-in with modular best-of-breed component sourcing.
The EU AI Act's algorithmic transparency requirements are reshaping automated decision systems in customer support and logistics planning workflows. European operators must now maintain explainable audit trails for AI-driven service routing decisions, elevating platform documentation and testing burdens. German carriers are responding by embedding compliance-by-design into fulfillment roadmaps ahead of enforcement timelines.
Enterprise buyers are consolidating vendor relationships around platforms that unify order management with real-time inventory visibility. Manufacturing and logistics verticals in the United States increasingly reject siloed fulfillment tools in favor of integrated suites that expose network status via embedded analytics dashboards. This preference shift favors vendors with embedded ERP connectors over pure-play fulfillment specialists.
Service Fulfillment Market Segmentation
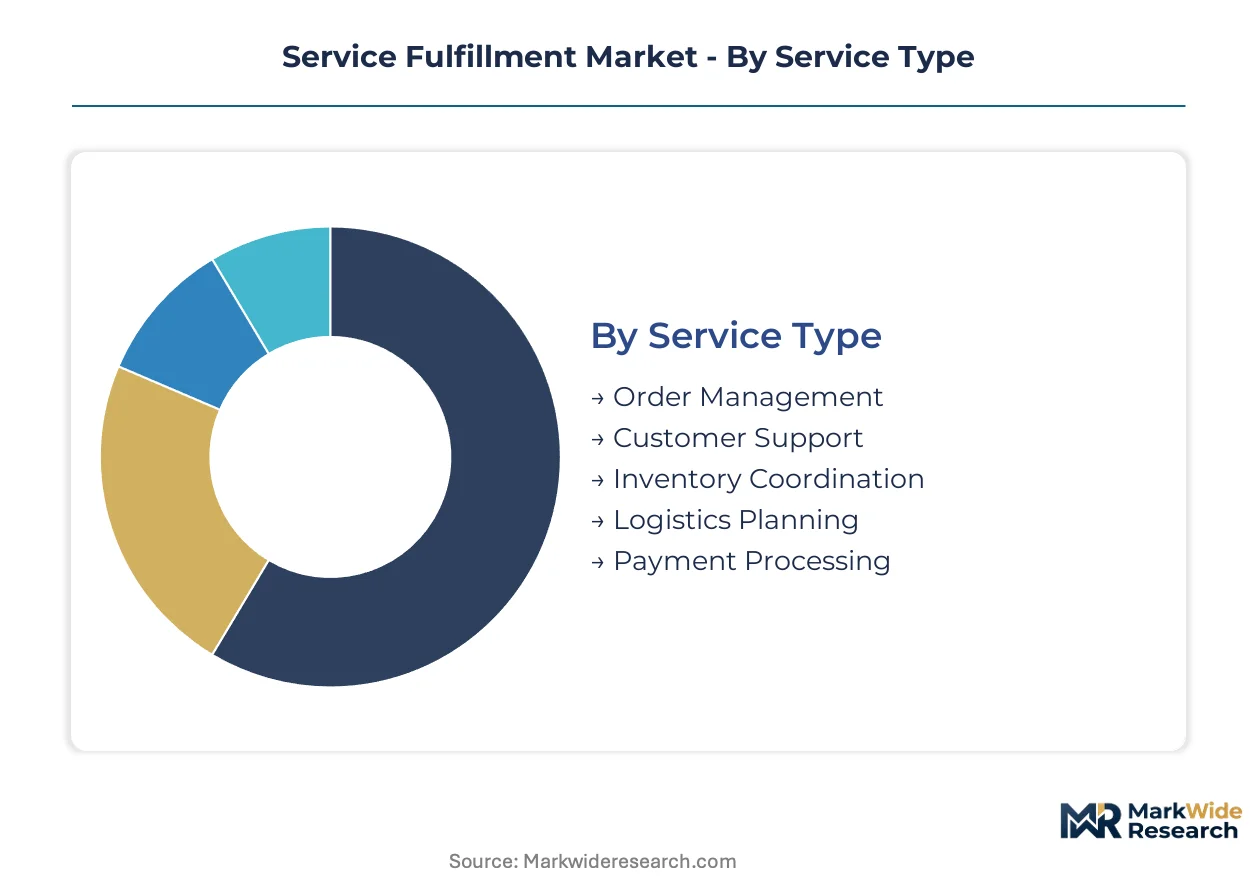
Service fulfillment platforms serve heterogeneous operational requirements across order velocity, network complexity, and compliance intensity. Segment differentiation determines vendor selection criteria, implementation timelines, and pricing architecture. Procurement teams evaluate segments through the lens of integration burden and revenue impact per transaction.
Service Type:
Order Management flows through direct sales and online portals to enterprise buyers, while Customer Support concentrates in mobile application channels for consumer-facing deployments. Inventory Coordination and Logistics Planning move through franchise networks in telecommunications and hospitality verticals.
- Order Management:Core transaction orchestration layer managing quote-to-cash workflows, pricing authority, and contract validation. Demand concentrates among telecommunications firms in Germany and the United States where 5G service bundles require real-time provisioning. The EU AI Act's algorithmic transparency mandates are forcing platform upgrades for automated decision trails.
- Customer Support:AI-driven inquiry resolution and exception handling workflows with embedded natural language processing. E-commerce merchants in South Korea and hospitality chains in Japan are expanding deployment to compress response latency. GDPR compliance requirements elevate data retention architecture costs.
- Inventory Coordination:Real-time network asset tracking across multi-vendor equipment databases.
- Logistics Planning:Workforce dispatch and field service scheduling with predictive routing.
- Payment Processing:Revenue recognition automation and billing reconciliation engines.
Order Management dominates installed base. Customer Support is where expansion concentrates.
End User:
Cost tier stratification separates telecommunications firms and financial institutions at premium implementation spend from educational organizations at constrained budget tiers. Hospitality chains and e-commerce merchants occupy mid-tier procurement bands with hybrid cloud requirements.
- Telecommunications Firms:Carrier-grade reliability requirements with sub-second provisioning latency for 5G standalone networks. German and South Korean operators are dismantling legacy stacks for API-first microservices. FCC network resilience standards and EU AI Act compliance drive platform refresh cycles.
- Financial Institutions:Real-time payment orchestration with embedded fraud detection and regulatory audit trails. Demand concentrates in the United States where the SEC and state banking regulators impose data lineage requirements. RBI data localization mandates shape Indian deployment architecture.
- E-Commerce Merchants:High-velocity order processing with seasonal capacity scaling.
- Hospitality Chains:Distributed property management with centralized guest service orchestration.
- Educational Organizations:Cost-constrained implementations favoring subscription SaaS over capital deployment.
Telecommunications Firms anchor premium pricing tiers. Financial Institutions are climbing the fastest in platform investment intensity.
Distribution Channel:
Volume concentration varies sharply by buyer maturity—direct sales capture complex enterprise transformations while mobile applications serve transactional self-service procurement. Online portals and third-party marketplaces fragment vendor control over pricing and implementation support.
- Direct Sales:Consultative engagement model for multi-year transformation contracts with embedded professional services. Telecommunications firms in the United States and financial institutions in Germany favor this channel for solution customization. Accenture PLC and systems integrators dominate this pathway.
- Online Portals:Self-service procurement with standardized configuration templates and instant provisioning. E-commerce merchants and educational organizations in India and South Korea are shifting volume here. TRAI and BIS certification requirements complicate multinational platform delivery.
- Third-Party Marketplaces:Aggregated vendor comparison with compressed sales cycles.
- Franchise Networks:Localized support infrastructure for hospitality and logistics verticals.
- Mobile Applications:Field technician and customer-facing interfaces for real-time status visibility.
Direct Sales dominates contract value. Online Portals are gaining share fastest in mid-market penetration.
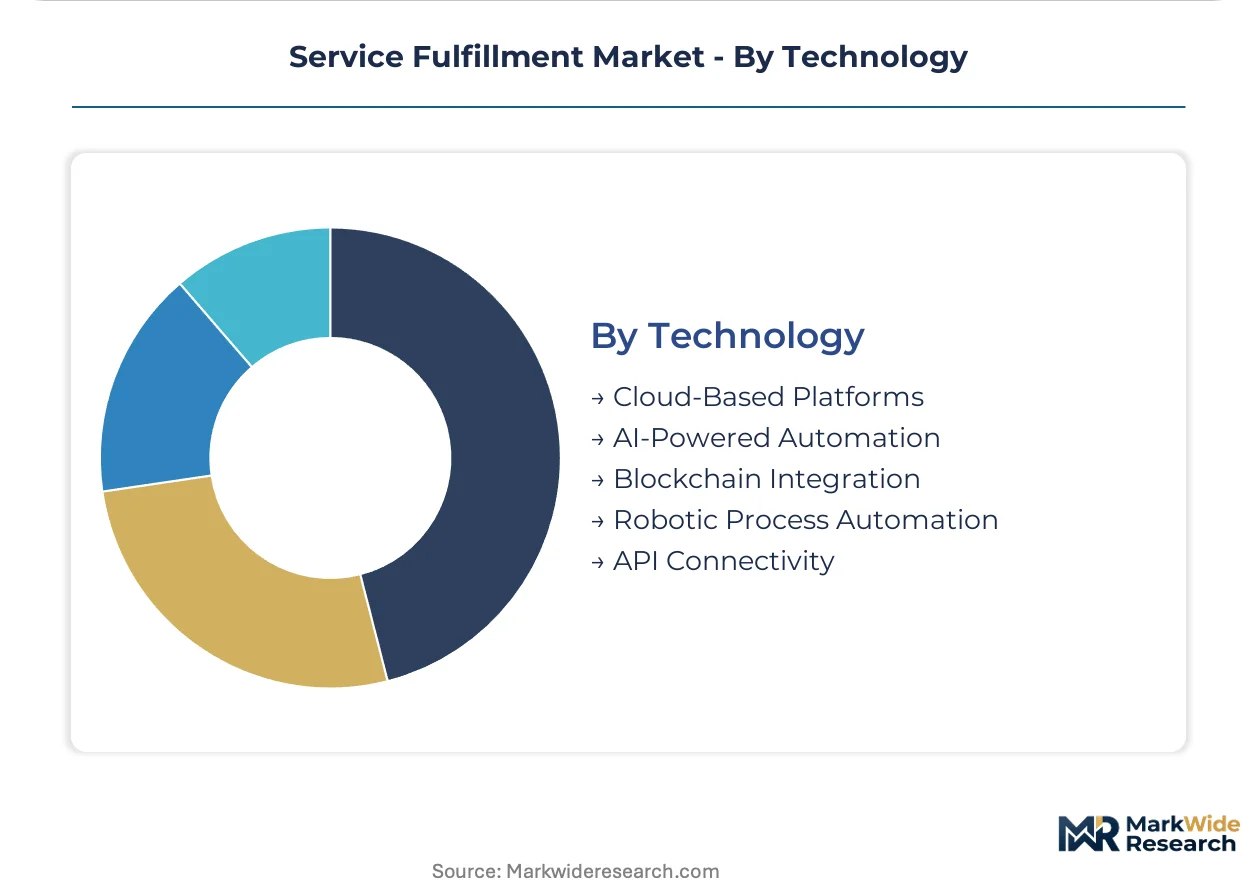
Technology:
Application maturity separates cloud-native architectures with containerized deployment from legacy automation layers requiring middleware translation. AI-powered automation and API connectivity represent adjacent capability investments rather than standalone procurement categories.
- Cloud-Based Platforms:Kubernetes-orchestrated microservices with elastic scaling and subscription economics. Tier-1 operators in South Korea and Germany are migrating production workloads here. GDPR and EU AI Act compliance requirements favor SaaS vendors with embedded regulatory tooling.
- AI-Powered Automation:Predictive demand forecasting and natural language processing for exception reduction. Financial institutions in the United States and telecommunications firms in Japan are prioritizing this layer for headcount containment. Explainable AI audit trails are becoming procurement prerequisites.
- Blockchain Integration:Distributed ledger for supply chain provenance and contract immutability.
- Robotic Process Automation:Legacy system screen scraping and workflow automation bridging technical debt.
- API Connectivity:TM Forum Open API compliance for multi-vendor interoperability.
Cloud-Based Platforms dominate new deployment value. AI-Powered Automation is where capability expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where enterprise digital transformation budgets command premium platform tiers, while Indian operators negotiate aggressive SaaS terms that compress vendor margins across Asia-Pacific deployments.
United States
Enterprise 5G rollouts and real-time inventory coordination drive platform investments. The FCC imposes network reliability and data security standards that elevate resilience requirements. Silicon Valley engineering clusters concentrate cloud-native architecture talent, inflating implementation costs for operators elsewhere.
Germany
5G standalone network provisioning and industrial automation integration create replacement demand for legacy systems. The EU AI Act mandates algorithmic transparency for automated customer support workflows, forcing compliance-by-design roadmaps. Munich and Frankfurt host carrier-grade platform development centers serving European telecommunications operators.
India
Cost-constrained educational organizations and mid-market e-commerce merchants favor subscription SaaS procurement over capital deployment. TRAI data localization mandates and BIS certification requirements complicate multinational platform delivery. Bangalore engineering clusters supply cloud-native fulfillment architecture skills, though talent scarcity inflates implementation timelines.
South Korea
Tier-1 mobile operators dismantle monolithic stacks for Kubernetes-orchestrated microservices, shrinking infrastructure provisioning cycles. The country's national telecommunications regulator shapes market access through network performance standards. Seoul Capital Area concentrates production workload migrations driving containerization adoption.
Japan
Manufacturing and logistics campuses seek turnkey private 5G network provisioning solutions. METI industrial policy supports captive wireless deployment standards. Osaka-Kansai industrial corridors anchor hospitality chain demand for distributed property management with centralized guest service orchestration.
Service Fulfillment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where consulting-led integrators command transformation premiums while infrastructure specialists defend hardware-software bundling positions. The vendor base spans three strategic archetypes: embedded network infrastructure providers, carrier-grade reliability specialists, and consulting-led transformation integrators. Dominant competitive moves include strategic partnerships bridging technical debt gaps and portfolio diversification into converged billing-fulfillment platforms.
Within the consulting-led transformation tier, Accenture PLC exemplifies the ERP modernization integration archetype. Cisco Systems and Ericsson occupy positions as embedded infrastructure specialists, with the former leveraging network presence and the latter anchoring carrier-grade mobile provisioning credentials. These three represent the strategic positioning spectrum from advisory services through hardware-software bundling to standardization-driven reliability.
| Leading Market Players |
|---|
| Comarch SA |
| Accenture PLC |
| Cisco Systems |
| Infosys Limited |
| TATA Communications |
| Oracle |
| Ericsson |
| IBM |
| Alcatel-Lucent |
| Others |
Cost & Logistics Intelligence
Forty-five-day provisioning cycles for legacy on-premise fulfillment stacks concentrate pricing power with cloud-native vendors in Bangalore and Tel Aviv, while SaaS subscription models compress margins for hardware-dependent incumbents. The EU AI Act's compliance documentation requirements add cost layers that widen spreads between certified and non-certified platform tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise deployments from standardized SaaS tiers. Subscription-based pricing dominates, with differentiation driven by certification grade (EU AI Act compliance tier) and vertical integration depth (embedded ERP connectors vs. standalone modules). Cost compression in the mid-market stems from Indian e-commerce merchants negotiating aggressive SaaS terms. Educational organizations exhibit highest price sensitivity; telecommunications firms in Germany and the United States show lowest sensitivity due to carrier-grade reliability requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate cloud-native component sourcing, though strategic stockpiling persists for specialized engineering talent in Silicon Valley and Bangalore. Supply concentrates in the United States (hyperscaler infrastructure), Germany (carrier-grade platform development), and India (cost-optimized SaaS delivery). Critical dependencies include Kubernetes orchestration tools, GPU clusters for AI training, and TM Forum Open API compliance modules. Single-source vulnerability runs through NVIDIA GPU supply for AI-powered automation layers. Distribution runs through direct sales for enterprise transformations and online portals for mid-market self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
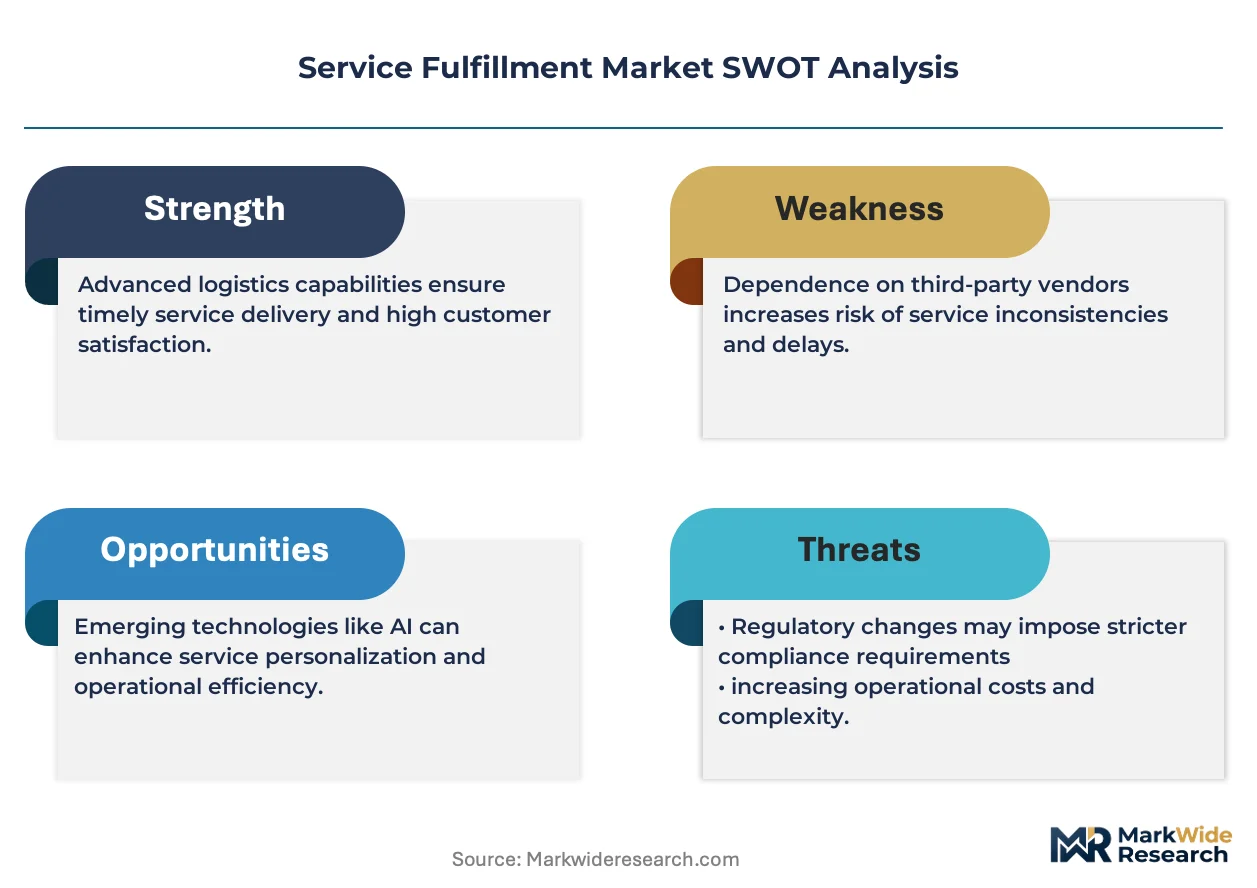
Service fulfillment is reshaping as a high-growth disruption. The EU AI Act's algorithmic transparency mandates force platform upgrades that expand addressable market for compliant vendors.
For Market Incumbents: Shield installed base relationships by embedding compliance-by-design roadmaps ahead of EU AI Act enforcement timelines. Deepen upstream control over AI training infrastructure to offset GPU supply concentration risk. Accenture PLC's consulting-led transformation model demonstrates how professional services bundling defends margin position against pure-play SaaS erosion. For New Entrants and Emerging Players: Lead with edge computing service orchestration in secondary German and Japanese metropolitan markets where incumbent coverage gaps persist. Target private 5G network provisioning for manufacturing campuses seeking turnkey fulfillment solutions. A channel partnership strategy with systems integrators accelerates enterprise credibility without direct sales infrastructure investment. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because API-first microservices architectures favor modular best-of-breed component sourcing over monolithic stacks. Acquisition targets should exhibit TM Forum Open API compliance and embedded EU AI Act documentation tooling. Watch for 5G standalone network rollout acceleration as the inflection signal that triggers replacement demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies order management with ERP systems, creating stickier vendor relationships in telecommunications verticals. |
| Strategic Partnership | Bridges legacy technical debt gaps through middleware alliances with incumbent infrastructure providers. |
| Acquisition of Specialist Firm | Adds EU AI Act compliance tooling and explainable AI audit trail capabilities to platform roadmaps. |
| Geographic Expansion | Establishes localized fulfillment nodes for edge computing orchestration in secondary metropolitan markets. |
| Product Launch | Introduces converged billing-fulfillment platforms that integrate usage metering with service activation workflows. |
Research Approach
A standing panel of telecommunications CTOs, cloud platform engineers, ERP integration specialists, and regulatory compliance officers provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from SEC filings, TM Forum standardization documents, EU regulatory databases, and hyperscaler capex disclosures. Bottom-up deployment sizing and top-down market aggregation underwent continuous triangulation.
Consistency checks validated outputs against external benchmarks across the analysis window. The analytical framework modeled segmentation dimensions including service type, end-user vertical, deployment model, integration complexity, and regional regulatory cluster. CAGRs derived from slope-log regression of annualized deployment trajectories. Industry-specific inputs incorporated 5G standalone network rollout schedules and EU AI Act implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained cloud migration momentum and stable regulatory enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding telecommunications capital expenditure patterns and AI governance harmonization progress. Revision becomes warranted when GPU supply constraints or data localization mandate fragmentation cross thresholds that materially alter platform architecture economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Event Apps Market
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Change Management Software Market
Digital Solutions
Shipping Software Market
Digital Solutions
Neuromarketing Solutions Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
Cloud Electronic Design Automation Market