
 Cheque Scanner Market | 2026-2036
Cheque Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Cheque Scanner Market Analysis
Multi-feed detection and ultraviolet authentication capability is collapsing into baseline specifications across mid-tier and premium cheque scanner tiers. Canon, Inc. leverages its optical imaging heritage to sustain leadership in high-resolution capture modules. PANINI specializes in compact branch-counter units that dominate European retail banking networks. DIGITAL CHECK CORP anchors the North American market through deep integration with core banking software ecosystems.
A cheque scanner is a document imaging device equipped with magnetic ink character recognition (MICR) read heads, dual-sided cameras typically capturing 200-300 dots per inch, and transport mechanisms designed to process 50-200 documents per minute for automated clearing and fraud prevention. High-speed models lead volume shipments to large banking institutions processing centralized remittances, while compact units represent the fastest-growing configuration as community banks downsize physical footprints. Image processing technology captures the dominant share of value-add software revenue, though scanning software integration determines customer retention and upgrade cycles across installed bases.
The Federal Reserve's Check 21 Act framework and ANSI X9 standards govern image quality requirements for substitute checks in the United States, while the European Central Bank's SEPA instruments directive shapes cross-border cheque truncation protocols. ISO 19005 compliance for archival PDF/A formats increasingly filters into procurement specifications for government agency deployments. Stakeholders must weigh branch digitization timelines against residual cheque volume trajectories when allocating R&D between hardware refinement and cloud-native capture platforms.
Market Dynamics
Branch footprint reduction across North American retail banking is compressing demand toward compact, multi-function capture devices while legacy high-speed remittance systems face extended replacement cycles.
Growth Catalysts
- Check 21 Act truncation mandates:US Federal Reserve requirements for image-based clearing sustain hardware refresh demand as banks modernize back-office infrastructure.
- Community bank consolidation:Merged institutions standardize on unified capture platforms, creating replacement waves across acquired branch networks.
- Ultraviolet authentication modules:Fraud prevention upgrades drive premium-tier scanner adoption among institutions handling high-value commercial deposits.
Market Restraints
- Optical sensor supply concentration:Japanese and German precision imaging component suppliers create procurement bottlenecks during semiconductor allocation cycles.
- Residual cheque volume decline:ACH and real-time payment adoption in the United States erodes transaction throughput justification for dedicated hardware.
- MICR ink standardization gaps:Inconsistent magnetic signal strength across cheque stock sources degrades read reliability and increases manual exception handling.
Strategic Opportunities
- Cloud-native capture platforms:Hybrid architectures that offload image processing to hosted environments reduce on-premise hardware footprints while preserving compliance.
- Credit union branch automation:Member-owned institutions lag commercial banks in scanner refresh cycles, presenting untapped replacement demand.
- ISO 19005-4 archival compliance:PDF/A-4 standard adoption for long-term document retention creates upgrade pull for government agency deployments.
Industry Challenges
- Embedded systems engineering talent:Firmware development for transport mechanisms and image pipelines faces competition from broader IoT and automotive sectors.
- Core banking integration complexity:Scanner APIs must synchronize with legacy mainframe architectures that resist rapid modification without operational risk.
- ANSI X9.100-181 certification timelines:Extended laboratory validation for image quality metrics delays product launches and compresses revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheque Scanner Market |
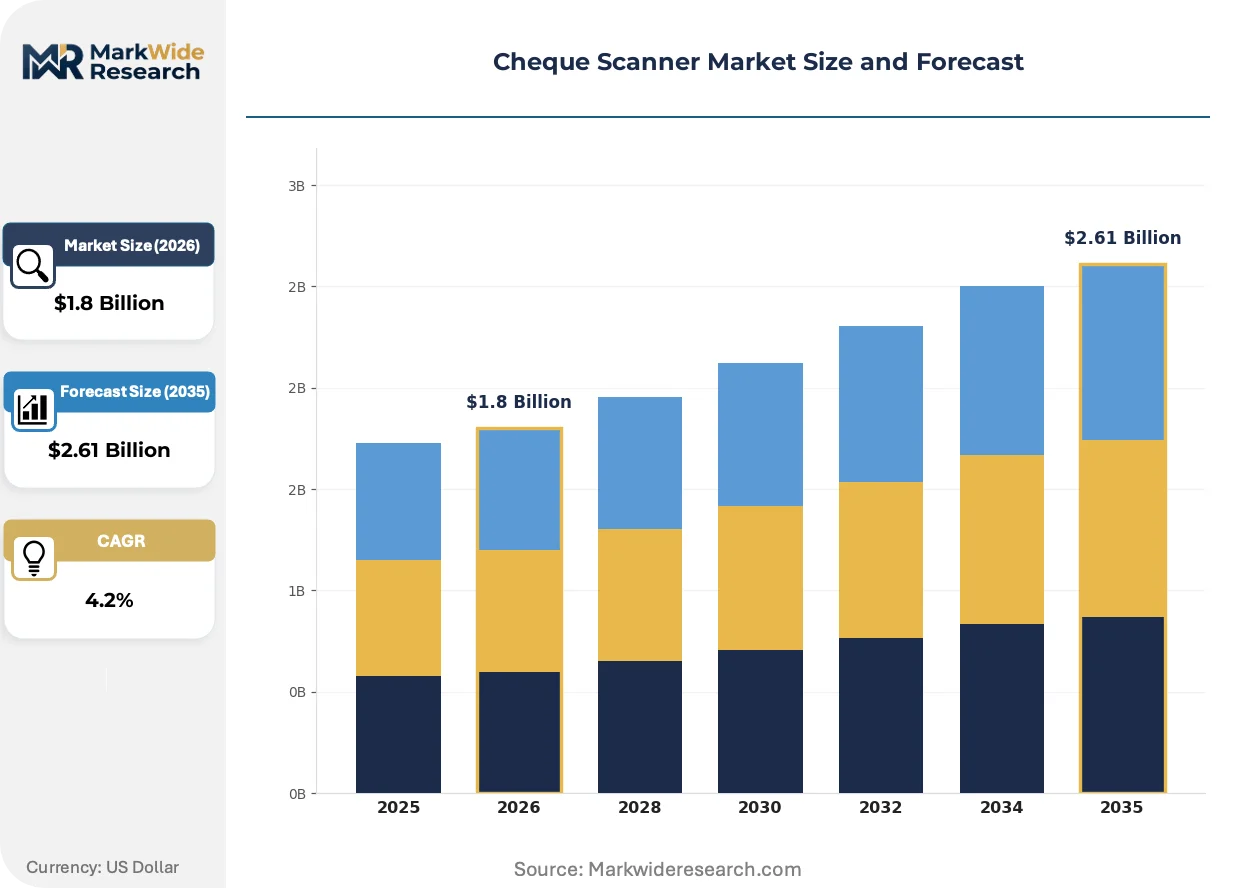
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Compact, High-Speed, Portable Technology: Magnetic Ink Character Recognition, Image Processing, OCR, Scanning Software End User: Banking Institutions, Retailers, Insurance Companies, Government Agencies Application: Check Processing, Fraud Detection, Record Keeping, Data Entry |
| Companies Covered | DIGITAL CHECK CORP, Canon, Inc., Benchmark Technology Group, ACOM Solutions, Inc., MagTek, Inc., ScanSource, Epson America, Inc., Troy Group, Inc., PANINI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheque Scanner Market Emerging Trajectories
Intelligent capture architectures are decoupling hardware from software value, enabling subscription-based service models that reshape vendor-customer relationships across installed bases.
Edge-based image processing is fragmenting the traditional scanner value proposition. On-device GPUs now execute fraud detection algorithms previously requiring server-side computation. Mid-tier banks in the United States pilot these configurations to reduce network latency during peak deposit windows. The technology is fragmenting procurement decisions between standalone hardware and software-defined capture stacks.
SEPA instrument harmonization across European Union member states is standardizing cross-border cheque truncation protocols. This regulatory convergence reduces country-specific hardware certification burdens for manufacturers serving multiple jurisdictions. German and French retail networks accelerate scanner refresh cycles to align with the European Central Bank's unified clearing timelines.
Managed service contracts for capture infrastructure are displacing capital purchase models among regional banking chains. Third-party operators assume hardware maintenance and software update responsibilities under per-transaction pricing. This shift concentrates most visibly among credit unions in the United States seeking to outsource non-core operational technology.
Cheque Scanner Market Segmentation
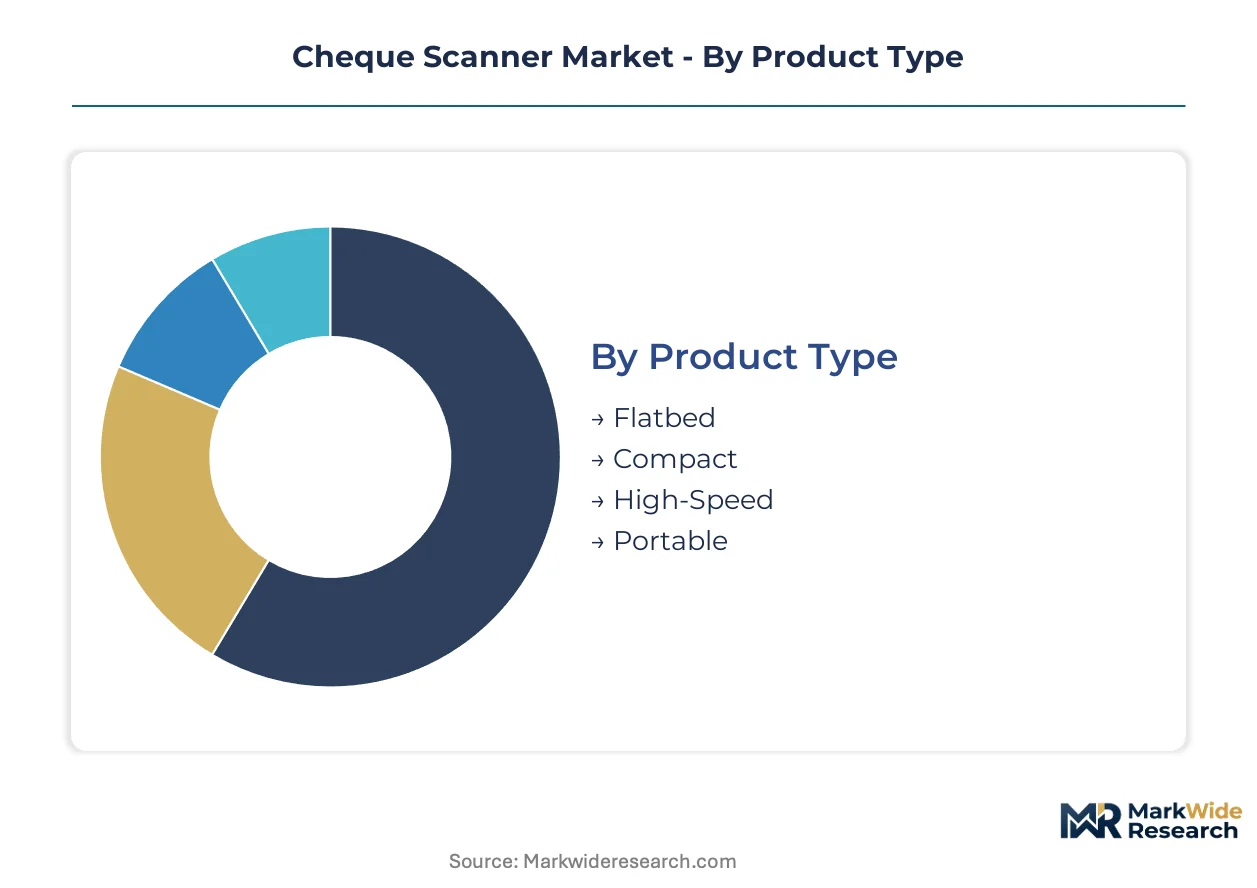
Cheque scanner procurement decisions diverge sharply by operational scale and compliance burden. Product configurations, underlying capture technologies, and end-user workflows each create distinct specification requirements that vendors must address separately.
Product Type:
Domestic demand concentrates in high-speed and compact variants for centralized banking operations, while portable units find stronger traction in field-service and export markets serving emerging banking networks.
- Flatbed:Stationary capture platforms employing flat glass platen designs for intermittent low-volume processing. Demand localizes to small government offices and insurance back-rooms in the United States where cheque volumes remain below fifty documents daily.
- Compact:Branch-counter units with 50-100 document-per-minute throughput and integrated MICR readers. United States community banks drive replacement cycles as they consolidate acquired branch networks and standardize on unified capture infrastructure.
- High-Speed:Transport mechanisms processing 150-200 documents per minute with double-sided imaging and ultraviolet authentication modules. Large banking institutions in the United States anchor procurement for centralized remittance operations.
- Portable:Battery-powered units weighing under two kilograms with wireless connectivity for mobile deposit capture. Credit union field representatives and commercial banking relationship managers in rural United States markets generate emerging demand.
High-speed scanners hold the largest share; momentum sits with compact configurations as branch footprints shrink.
Technology:
Cost tier stratification separates legacy magnetic recognition from premium image processing stacks, with software integration determining customer retention across installed bases.
- Magnetic Ink Character Recognition:Legacy read heads detecting magnetic signal patterns in MICR ink for routing and account identification. Banking institutions in the United States maintain this as baseline requirement despite declining cheque volumes, though inconsistent ink standardization across cheque stock sources degrades read reliability.
- Image Processing:On-device GPU architectures executing edge-based fraud detection and image quality enhancement. Mid-tier United States banks pilot these configurations to reduce network latency during peak deposit windows.
- OCR:Optical character recognition engines extracting handwritten and printed text fields for automated data entry. Retailers in the United States deploy OCR-capable units for consumer cheque acceptance at point-of-sale terminals.
- Scanning Software:Cloud-native capture platforms with subscription pricing and API integration into core banking systems. Regional banking chains in the United States shift toward managed service contracts displacing capital purchase models.
Image processing commands premium pricing; scanning software is climbing the fastest as vendor-customer relationships reshape around subscription economics.
End User:
Application maturity varies sharply, with banking institutions driving hardware refresh cycles while government agencies lag in ISO 19005 archival compliance adoption.
- Banking Institutions:Commercial banks, credit unions, and savings associations processing retail and commercial deposits. United States regional banks modernize branch infrastructure under Federal Reserve Check 21 Act truncation mandates.
- Retailers:Big-box stores, grocery chains, and specialty merchants accepting consumer cheques at point-of-sale. United States retail networks prioritize compact units with rapid authentication to minimize checkout friction.
- Insurance Companies:Carriers processing premium payments and claim disbursements through cheque instruments. United States property and casualty insurers maintain dedicated capture operations for commercial policyholder transactions.
- Government Agencies:Federal, state, and municipal entities handling tax payments, permits, and vendor disbursements. United States agencies face procurement specifications filtering in ISO 19005-4 PDF/A archival compliance requirements.
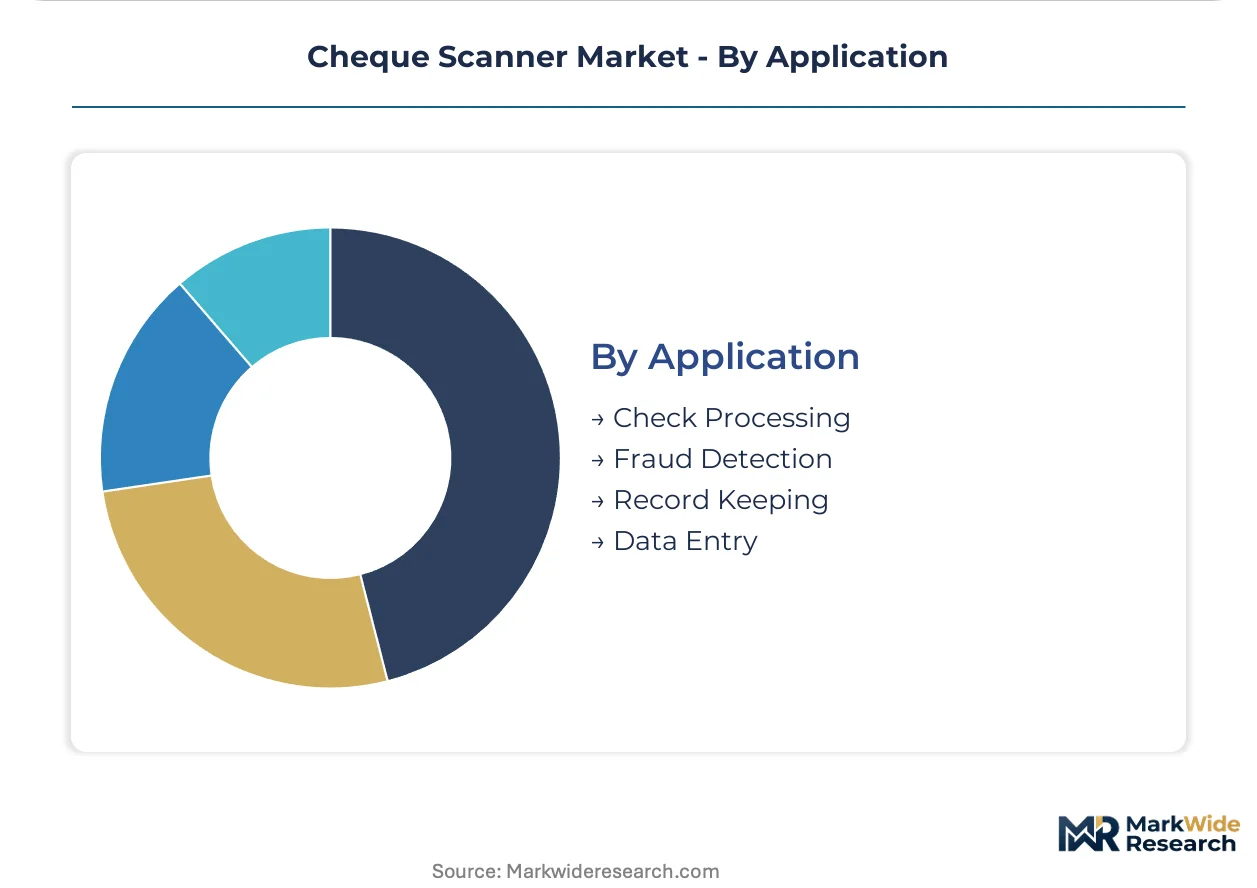
Banking institutions hold the largest share; momentum sits with government agencies as archival compliance mandates accelerate replacement timelines.
Application:
Volume concentration centers on check processing for clearing operations, while fraud detection applications command premium pricing through ultraviolet authentication module integration.
- Check Processing:Core clearing operations capturing images for substitute check creation and electronic exchange. United States banking institutions sustain hardware refresh demand as they modernize back-office infrastructure under ANSI X9 standards.
- Fraud Detection:Ultraviolet and infrared authentication verifying cheque stock integrity and signature validity. United States institutions handling high-value commercial deposits drive premium-tier scanner adoption for this application.
- Record Keeping:Long-term archival imaging meeting audit and regulatory retention requirements. United States government agencies specify PDF/A-4 compliance for document retention creating upgrade pull.
- Data Entry:Automated extraction of payee, amount, and memo fields for straight-through processing. United States retailers deploy this capability to reduce manual keying at point-of-sale cheque acceptance points.
Check processing holds the largest share; fraud detection is expanding most quickly as authentication module integration becomes baseline in premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component sourcing for precision imaging modules concentrates in Japanese and German manufacturing clusters, creating procurement dependencies that ripple through North American and European assembly operations. Banking infrastructure modernization drives hardware refresh cycles across distinct regulatory environments.
United States
Community bank consolidation and Federal Reserve Check 21 Act mandates sustain replacement demand for compact branch-counter units. ANSI X9.100-181 image quality certification shapes product launch timelines. Chicago and Dallas metropolitan banking clusters standardize on unified capture platforms across merged branch networks.
Germany
SEPA instrument harmonization accelerates scanner refresh cycles in retail banking networks. The European Central Bank's unified clearing timelines compress procurement decision windows. Frankfurt's financial services corridor drives specification requirements for cross-border cheque truncation compatibility.
Japan
Precision optical sensor manufacturing anchors upstream supply capacity for global scanner assembly. METI industrial standards influence imaging component export specifications. Nagoya's precision engineering cluster supplies transport mechanism subsystems to North American integrators.
United Kingdom
Post-Brexit regulatory divergence creates parallel certification requirements for cheque imaging systems. The Bank of England's settlement system standards shape enterprise procurement specifications. London's fintech corridor pilots cloud-native capture platforms for hybrid branch architectures.
Canada
Credit union branch automation lags commercial banking modernization, presenting replacement demand concentration. Payments Canada image clearing rules govern hardware compliance requirements. Toronto's financial district anchors procurement decision-making for regional banking chains.
Cheque Scanner Market Vendor Landscape
Concentration sits with diversified imaging equipment manufacturers and specialized banking technology providers. The vendor base stratifies across three tiers: optical imaging heritage companies, core banking integration specialists, and compact hardware fabricators. Strategic moves cluster around cloud-native platform development and managed service contract expansion.
Within the optical imaging tier, Canon, Inc. exemplifies heritage-driven positioning in high-resolution capture modules. DIGITAL CHECK CORP anchors North American market presence through deep software ecosystem relationships. PANINI occupies a specialist position in compact European branch-counter configurations.
| Leading Market Players |
|---|
| DIGITAL CHECK CORP |
| Canon, Inc. |
| Benchmark Technology Group |
| ACOM Solutions, Inc. |
| MagTek, Inc. |
| ScanSource |
| Epson America, Inc. |
| Troy Group, Inc. |
| PANINI |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with Japanese and German precision imaging suppliers lock in both optical sensor access and unit cost visibility for North American scanner integrators facing volatile semiconductor allocation cycles. These contracts insulate assembly operations from spot-market volatility while embedding ANSI X9.100-181 certification costs into baseline procurement specifications.
Pricing Analysis
Federal Reserve Check 21 Act truncation mandates dictate the pricing tier structure across the scanner market, separating premium ultraviolet-authentication configurations from standard MICR-only units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in economy-tier flatbed models is intensifying because credit unions and small government offices prioritize capital expenditure minimization over feature depth. Community banks exhibit highest price sensitivity due to constrained technology budgets, while large banking institutions processing centralized remittances demonstrate lowest sensitivity to per-unit premiums.
Supply Chain Analysis
Inventory cycles for precision optical sensors currently stretch 18-24 weeks, constraining North American assembly throughput during peak banking refresh seasons. Manufacturing gravity centers on Japan for CMOS imaging arrays, Germany for precision transport mechanisms, and the United States for final integration and software loading. Raw material dependencies include rare-earth elements for MICR read heads, specialized glass substrates for camera modules, and precision-machined aluminum for transport chassis. Single-source vulnerability concentrates in Japanese optical component suppliers, creating procurement bottlenecks during geopolitical trade disruptions. Distribution runs through authorized banking technology resellers with direct core banking software integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
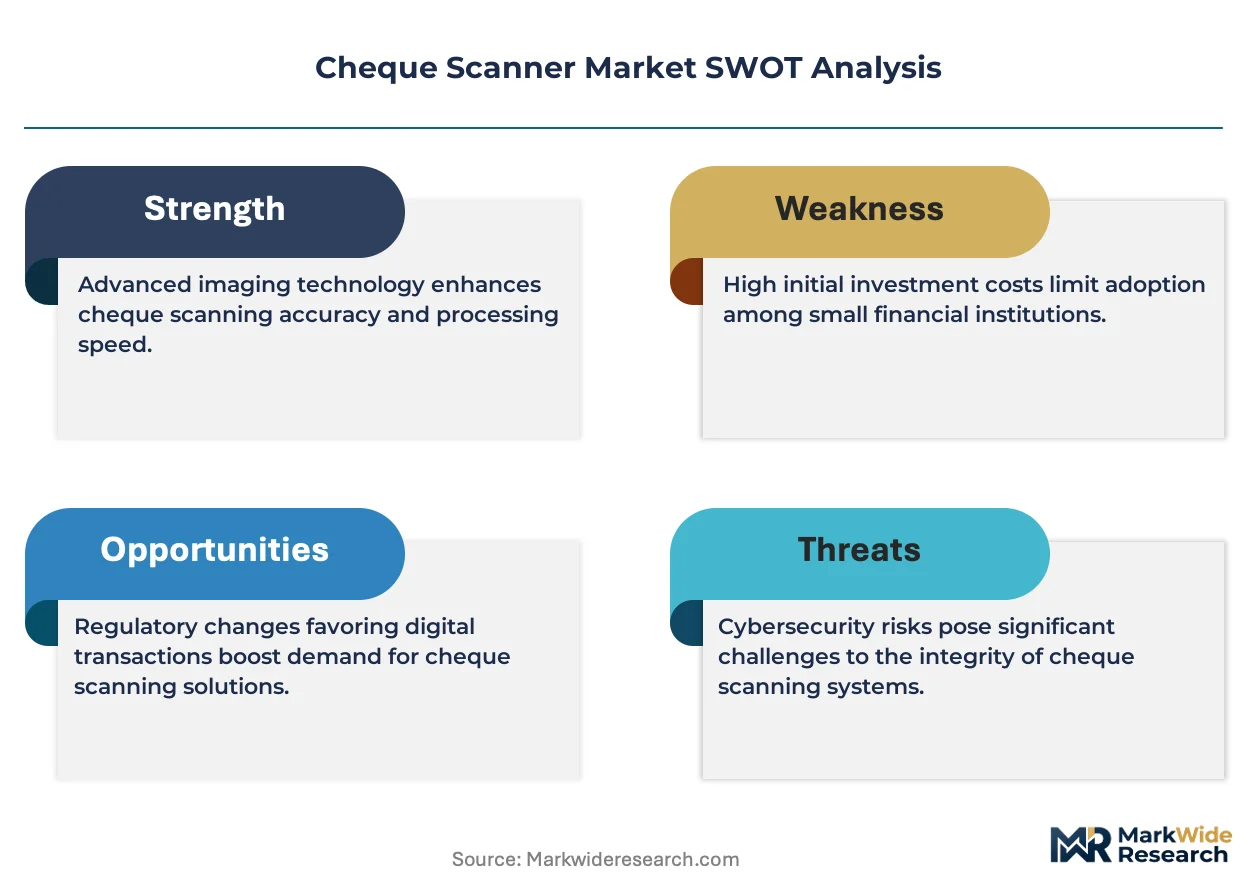
The cheque scanner market functions as a defensive moat sustained by regulatory entrenchment: Federal Reserve truncation mandates and ANSI X9 certification requirements create structural barriers that protect incumbents with established compliance track records and installed base relationships.
For Market Incumbents: Fortify market position through backward integration into optical sensor supply chains, reducing exposure to Japanese and German component allocation volatility. Deepen software ecosystem lock-in by accelerating API development for cloud-native capture platforms, countering emerging fintech entrants offering software-defined alternatives. Prioritize ANSI X9.100-181 certification investment velocity to compress product launch timelines and capture replacement waves from community bank consolidation. For New Entrants and Emerging Players: Differentiate on edge-based image processing architectures that reduce network latency for mid-tier United States banks during peak deposit windows. Target credit union branch automation as the most penetrable segment, where managed service contract appetite outpaces capital purchase capability. Pursue white-label partnerships with established core banking software providers to bypass direct certification burden and accelerate market access. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive optical component supply and established Federal Reserve compliance relationships. Long-term viability hinges on the 5-10 year residual cheque volume trajectory in United States commercial banking. Monitor ACH adoption velocity and real-time payment penetration as the critical signal for hardware demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Capture Platform Development | Hybrid architectures reduce on-premise footprints while preserving Federal Reserve compliance requirements. |
| Managed Service Contract Expansion | Per-transaction pricing models displace capital purchases among credit union branch networks. |
| Edge-Based Image Processing Integration | On-device GPU execution fragments procurement between standalone hardware and software-defined stacks. |
| ISO 19005-4 Archival Compliance Certification | PDF/A-4 standard adoption creates upgrade pull for government agency deployments. |
| Optical Component Supply Integration | Backward integration into Japanese and German sensor manufacturing reduces allocation cycle exposure. |
Methodological Framework
A spread of perspectives from banking technology procurement officers, core banking integration specialists, branch operations managers, and precision imaging component suppliers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through Federal Reserve regulatory filings, ANSI X9 standards documentation, Payments Canada image clearing rule sets, and European Central Bank SEPA instrument harmonization protocols. Bottom-up shipment data from scanner manufacturers triangulated against top-down banking branch modernization expenditure patterns.
Segmentation dimensions modeled include product configuration tier, capture technology stack, end-user institutional type, and application workflow across the analysis window. CAGRs were derived from regression analysis of historical replacement cycles projected against cheque volume trajectories and regulatory mandate timelines. Forecast inputs incorporated Federal Reserve Check 21 Act enforcement patterns, community bank consolidation velocity, and cloud-native platform adoption curves.
Material uncertainties — residual cheque volume decline acceleration, semiconductor allocation cycle volatility, and real-time payment substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision as regulatory frameworks evolve. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Supplier Contract Management Market
Digital Solutions
Electronic Records Management Solutions Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Green IT Services Market
Digital Solutions
Global Connected Workplace Market
Digital Solutions
Europe Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Global Data Virtualization Market
Digital Solutions
Ediscovery Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Global Product Lifecycle Management Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Data Monetization Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Clientless Remote Support Software Market