
 Knife Set Market | 2026-2036
Knife Set Market Size, Share, and Industry Trends Forecast 2026-2036
Knife Set Market Insights
Skilled blade artisans in Solingen, Seki, and Thiers is unwinding a generational bottleneck that had constrained high-end output. Wüsthof leverages its forged-in-Germany heritage to anchor European premium distribution. Zwilling competes through dual-brand architecture spanning mass and artisan tiers. Victorinox dominates commercial kitchen procurement with NSF-certified lines and institutional pricing discipline.
A knife set comprises multiple blades engineered to distinct edge geometries, hardness ratings, and handle ergonomics for segmented food preparation tasks; VG-10 stainless steel at 60-61 HRC exemplifies the metallurgical threshold separating professional from consumer grades. Chef's Knives and Santoku Knives lead value contribution due to universal indispensability across use cases, while Damascus Steel commands outsized margin pools despite fractional volume share. Six-Piece and Eight-Piece Sets capture the bulk of household demand, though Ten-Piece Sets are accelerating as gifting and registry channels professionalize.
EU REACH restrictions on nickel leaching and FDA food-contact surface standards under 21 CFR 175.300 shape alloy selection and finishing protocols for export-bound manufacturers. Japan's METI oversees JIS standards for blade hardness disclosure, creating compliance friction for unverified claims. Stakeholders must monitor how carbon-neutral forging requirements in the EU Green Deal cascade through supplier qualification criteria.
Market Dynamics
Professional culinary school enrollment surges across North America and Europe are compressing commercial-grade replacement cycles, while EU REACH nickel restrictions and FDA food-contact standards are forcing alloy requalification across export supply chains.
Growth Catalysts
- Professional Culinary Education:Expanded enrollment at Le Cordon Bleu and Culinary Institute of America campuses is accelerating institutional procurement of forged blade sets for training kitchens.
- REACH Compliance Arbitrage:German manufacturers with pre-certified low-nickel stainless supply chains are capturing displaced orders from non-compliant Asian exporters facing EU border rejection.
- Damascus Aesthetic Premiumization:Layered steel patterning techniques developed in Seki are migrating into mid-tier consumer sets through automated cladding processes.
Market Restraints
- Cobalt and Vanadium Price Volatility:Alloy additive costs for VG-10 and SG2 powder metallurgy steels fluctuate with aerospace and battery sector demand, squeezing margin on premium lines.
- Solingen Artisan Bottleneck:Master forger apprenticeship programs graduate fewer than forty certified bladesmiths annually, capping authentic hand-forged output regardless of price elasticity.
- Stamped Blade Substitution:Precision-rolled stainless from Chinese cold mills achieves 90% of forged hardness at 40% of labor cost, pressuring Western mid-market positioning.
Strategic Opportunities
- Carbon-Neutral Forging Mandates:EU Green Deal supplier qualification criteria will favor early adopters of hydrogen-fired heat treatment and renewable-powered grinding operations.
- Direct-to-Registry Channels:Wedding and housewarming gift platforms are professionalizing ten-piece set curation, bypassing traditional retail markup structures.
- Modular Magnetic Storage Systems:Wall-mounted blade blocks with integrated edge guards are creating attachment-rate opportunities in kitchen renovation and Airbnb outfitting verticals.
Industry Challenges
- Hardness Verification Disputes:Japan's METI JIS enforcement actions against unsubstantiated Rockwell claims are triggering costly third-party testing and label redesign cycles.
- Cross-Border Certification Lag:NSF commercial kitchen approval timelines stretch eight to fourteen months, delaying Victorinox and Wüsthof institutional launches in North American foodservice.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knife Set Market |
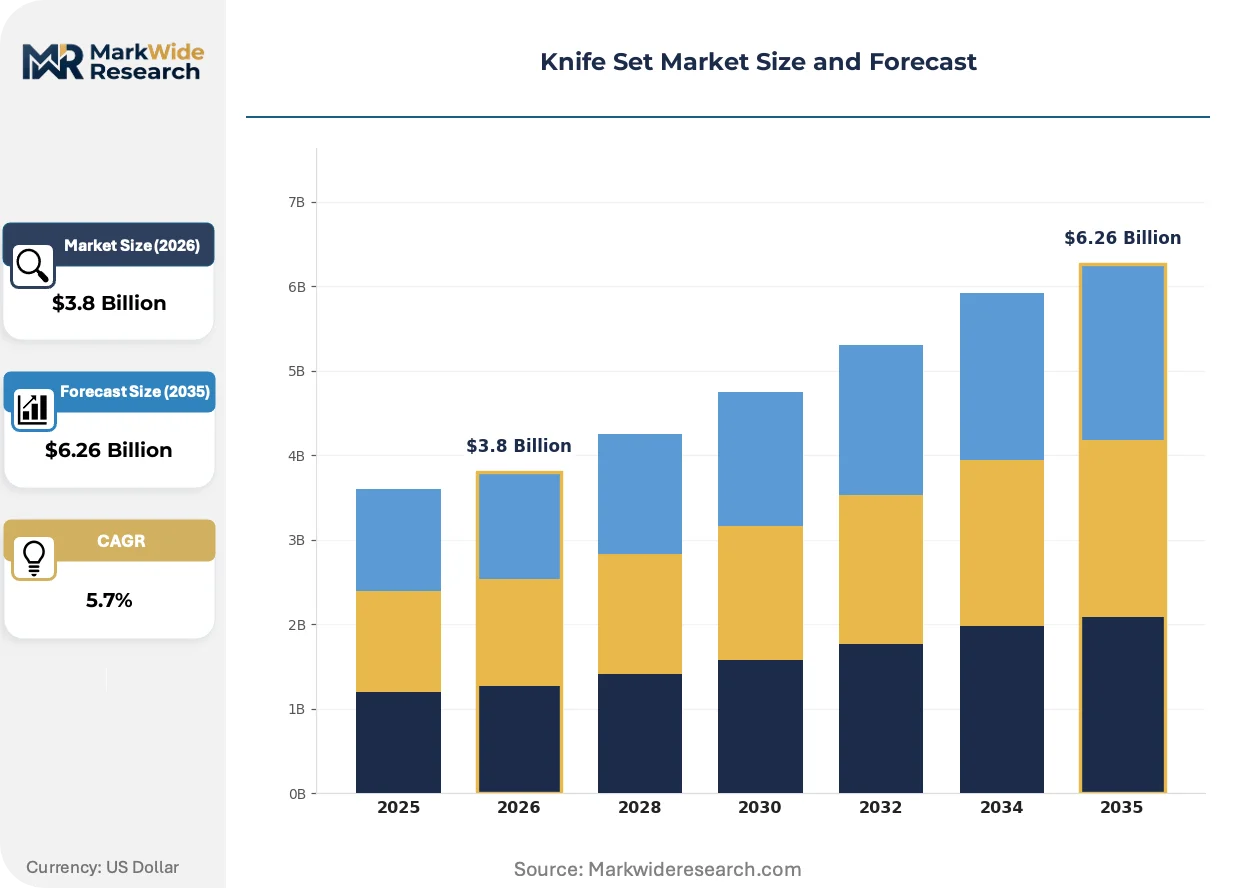
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chef's Knives, Paring Knives, Santoku Knives, Utility Knives Material: Stainless Steel, Carbon Steel, Ceramic, Damascus Steel Size: Four-Piece Sets, Six-Piece Sets, Eight-Piece Sets, Ten-Piece Sets Use Case: Home Cooking, Professional Culinary, Outdoor Use, Food Preparation |
| Companies Covered | Global, Miyabi, Wüsthof, Tojiro, Henckels, Zwilling, Victorinox, Kikuichi, Shun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knife Set Market Trends and Innovations
Powder metallurgy advances and regulatory disclosure mandates are converging to compress the performance gap between artisan and precision-manufactured blades while reshaping how buyers verify quality claims.
SG2 and R2 micro-carbide powder steels are achieving 63-64 HRC with superior chipping resistance over traditional high-carbon alloys. Commercial kitchens in Japan and Nordic countries are adopting these blades for high-volume fish and vegetable prep. The technology is miniaturizing production scale requirements, enabling boutique forges in Thiers and Seki to compete with Solingen's industrial volume on performance metrics rather than heritage alone.
EU REACH Annex XVII nickel leaching thresholds are tightening from 0.5 to 0.2 micrograms per square centimeter for prolonged skin contact. German and French exporters are reformulating 18/10 stainless to 18/0 or titanium-stabilized variants, adding 12-15% to material costs. North American medical and childcare foodservice buyers are now demanding REACH-equivalent documentation, extending EU regulatory gravity beyond its borders.
Registry and gifting platforms are consolidating buyer decision-making into curated ten-piece and twelve-piece configurations. Traditional cutlery retailers in Germany and the United States are losing bridal market share to direct-to-consumer brands with virtual try-on and engraving personalization. This channel rotation is most pronounced in urban coastal markets where apartment kitchen storage constraints favor magnetic or in-drawer solutions over block-based sets.
Knife Set Market Segmentation
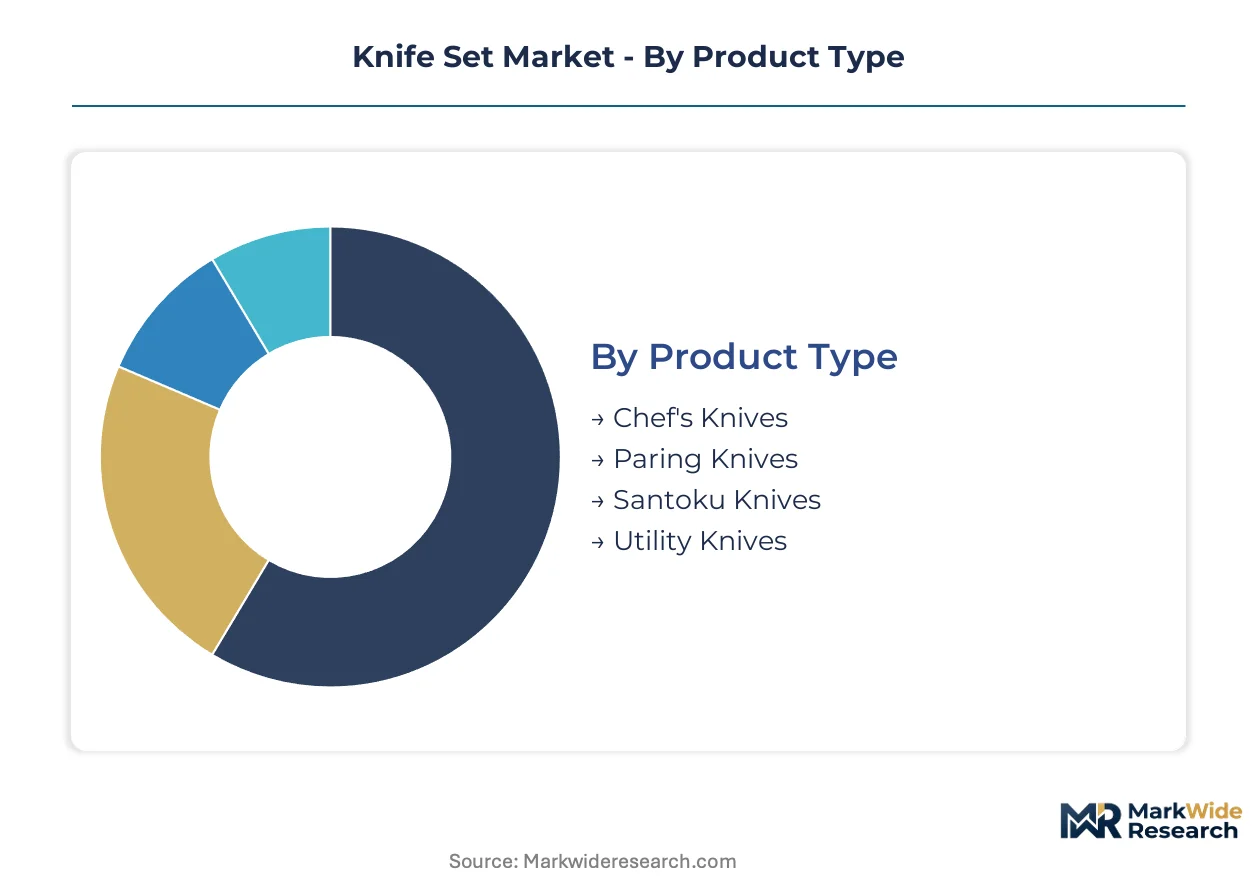
Knife set manufacturers configure product portfolios across four intersecting dimensions where blade geometry, metallurgical grade, set configuration, and end-use certification determine margin capture. Each segmentation axis carries distinct pricing power and supply chain complexity.
Product Type:
Margin pools concentrate in the two blade categories that anchor every functional set configuration.
- Chef's Knives:The 8-10 inch curved belly blade at 58-62 HRC hardness anchors professional and consumer sets alike. Demand clusters in North American culinary school procurement and German premium retail where forged bolster construction commands price premiums over stamped alternatives.
- Santoku Knives:The sheep's foot profile with granton edge dimples dominates Japanese export volumes and Western home kitchens seeking vegetable-centric prep tools. Seki-forged variants with VG-10 cores are displacing European competitors in coastal US markets.
- Paring Knives:3-4 inch spear-point blades for precision tasks.
- Utility Knives:Mid-length serrated or straight edges filling gap coverage in larger sets.
Chef's Knives hold installed capacity across Solingen and Seki forging clusters. Santoku Knives is rotating up the share rankings in North American bridal registry channels.
Material:
Alloy selection dictates regulatory compliance burden and end-use eligibility more than any other segmentation axis.
- Damascus Steel:Layered pattern-welded construction achieving 60-62 HRC through VG-10 or SG2 core cladding commands outsized margin despite low volume share. Automated cladding lines in Seki and Thiers are compressing production costs for mid-tier accessibility.
- Stainless Steel:18/10 and 18/0 chromium-nickel alloys dominate institutional procurement requiring NSF certification and REACH nickel compliance. German mills in Solingen supply low-leaching formulations that satisfy both EU and FDA food-contact surface standards.
- Carbon Steel:High-carbon alloys at 60-65 HRC requiring active maintenance.
- Ceramic:Zirconium dioxide blades for specialized slicing applications.
Stainless Steel holds installed capacity across commercial kitchen certification pathways. Damascus Steel is climbing the fastest in direct-to-consumer premium channels.
Size:
Set configuration determines channel placement and gift-occasion targeting.
- Six-Piece Sets:Chef, paring, utility, bread, kitchen shears, and block configuration captures maximum household penetration. German and US mass retailers stock this configuration as the default upgrade from open-stock purchases.
- Ten-Piece Sets:Expanded configurations incorporating santoku, boning, and sharpening steel are accelerating as wedding registry platforms professionalize curation. Magnetic storage integration is driving attachment sales in urban apartment markets.
- Four-Piece Sets:Entry-level starter configurations.
- Eight-Piece Sets:Mid-market bridge configuration.
Six-Piece Sets hold installed capacity across traditional retail block-based merchandising. Ten-Piece Sets is gaining share fastest in direct-to-registry digital channels.
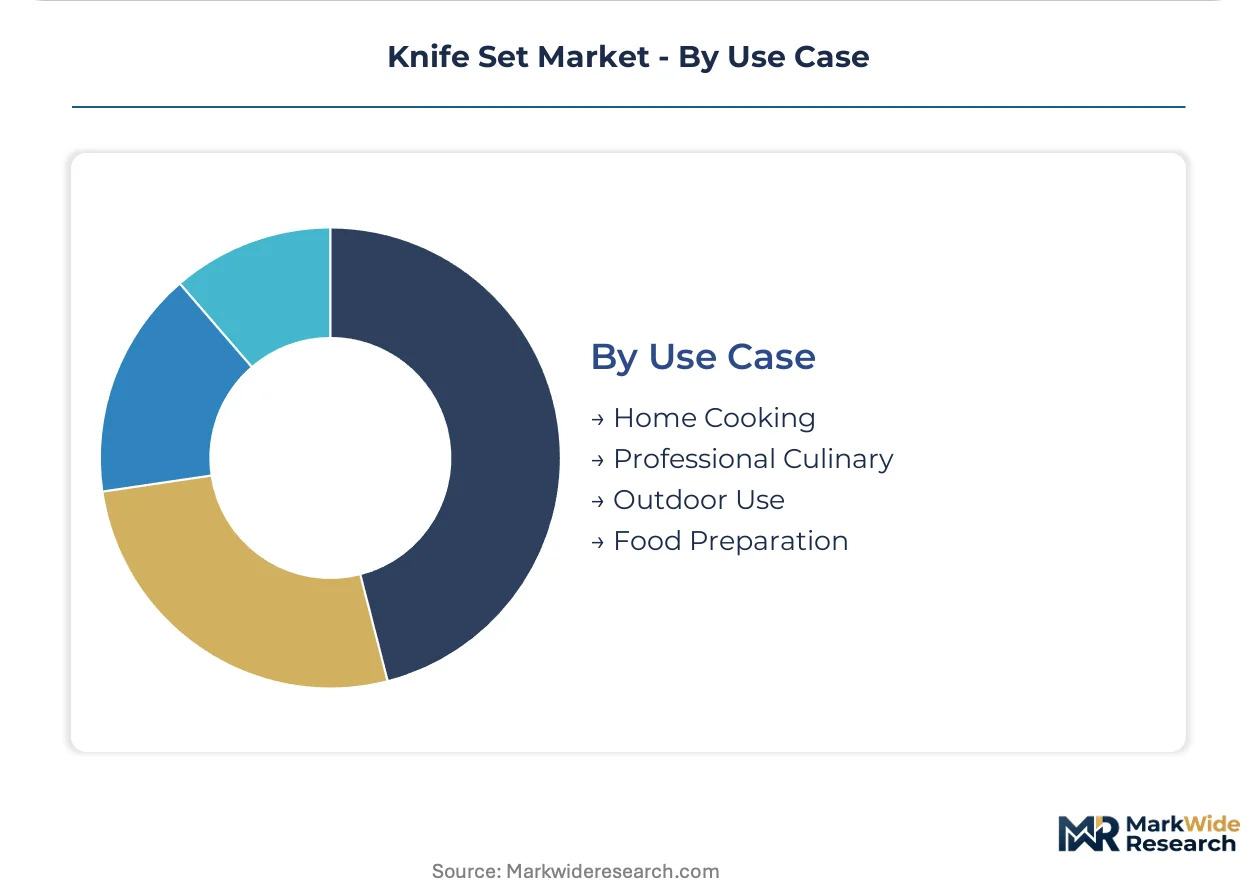
Use Case:
End-use certification requirements create divergent supply chain qualification pathways.
- Professional Culinary:NSF-certified forged blades with documented Rockwell hardness and ergonomic handle certification dominate Le Cordon Bleu and Culinary Institute of America training kitchen procurement. Replacement cycles compress as enrollment expands across North American and European campuses.
- Home Cooking:Aesthetic-forward sets with Damascus cladding and magnetic storage integration concentrate in direct-to-consumer channels bypassing traditional cutlery retail markup structures.
- Outdoor Use:Camping and hunting-adjacent blade sets.
- Food Preparation:Light commercial and catering applications.
Professional Culinary holds installed capacity across institutional certification networks. Home Cooking is rotating up the share rankings as gifting platforms consolidate buyer decision-making.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH Annex XVII nickel restrictions are reshaping alloy sourcing across export supply chains. German mills with pre-certified low-leaching formulations capture displaced orders from non-compliant competitors. Culinary school procurement and gifting platform consolidation are compressing replacement cycles in mature markets while opening premium-tier penetration in emerging consumption centers.
United States
Le Cordon Bleu and Culinary Institute of America campuses are accelerating institutional procurement of forged blade sets for training kitchens. FDA food-contact surface standards under 21 CFR 175.300 mandate documented alloy composition for commercial kitchen eligibility. California and New York Metro markets concentrate direct-to-consumer brand penetration where magnetic storage solutions address apartment kitchen constraints.
Germany
Solingen's blade-making heritage anchors premium export volumes through certified master forger apprenticeship programs. EU REACH compliance on nickel content in stainless alloys tightens material specifications for export-bound manufacturers. North Rhine-Westphalia's forging clusters supply low-leaching 18/0 formulations that satisfy both EU and North American regulatory documentation requirements.
Japan
Seki-forged variants with VG-10 cores are displacing European competitors in coastal US bridal registry channels. METI oversees JIS standards for blade hardness disclosure, creating compliance friction for unverified Rockwell claims. Gifu Prefecture's automated cladding lines are compressing production costs for mid-tier Damascus accessibility.
France
Thiers blade artisans are unwinding generational bottlenecks that had constrained high-end output through miniaturized powder metallurgy adoption. EU Green Deal carbon-neutral forging requirements cascade through supplier qualification criteria for export access. Auvergne-Rhône-Alpes cutlery clusters are migrating layered steel patterning techniques into automated production for premium consumer sets.
China
Precision-rolled stainless from Chinese cold mills achieves hardness parity with forged alternatives at substantially reduced labor cost. GB standards for food-contact materials shape domestic market entry requirements for alloy selection. Yangtze River Delta manufacturing bases supply stamped blade alternatives pressuring Western mid-market positioning through cost-efficient volume production.
Knife Set Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the knife set market. Heritage forgers with Solingen or Seki provenance command premium positioning through metallurgical certification and artisan scarcity. Precision manufacturers leverage automated cladding and powder metallurgy to compress performance gaps at scale. Strategic moves concentrate on direct-to-registry channel bypass and carbon-neutral forging pre-certification ahead of EU Green Deal enforcement.
Within the heritage-forger tier, Wüsthof and Zwilling occupy positions defined by geographic provenance and multi-brand architecture spanning mass and artisan tiers. Victorinox represents the institutional procurement archetype through NSF-certified lines and commercial kitchen pricing discipline. These three anchors illustrate how competitive positioning separates premium heritage claims from scale-driven certification compliance.
| Leading Market Players |
|---|
| Global |
| Miyabi |
| Wüsthof |
| Tojiro |
| Henckels |
| Zwilling |
| Victorinox |
| Kikuichi |
| Shun |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts between Solingen forging clusters and German stainless mills lock in low-nickel alloy access while anchoring price visibility for export-bound manufacturers facing REACH compliance deadlines. These arrangements insulate premium-tier producers from spot volatility in cobalt and vanadium additive markets while constraining margin flexibility for mid-tier competitors sourcing through Asian traders.
Pricing Analysis
German-forged sets command 40-60% premiums over Seki equivalents in North American bridal channels, while Chinese stamped alternatives undercut both by half on landed cost. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and hardness verification documentation. Cost compression in mid-tier lines is intensifying because precision-rolled Chinese stainless achieves hardness parity at reduced labor input. Institutional buyers at culinary schools exhibit lowest price sensitivity due to NSF certification requirements, while Airbnb outfitters and gift registrants drive volume at economy tiers.
Supply Chain Analysis
Inventory cycles for VG-10 and SG2 powder steel inputs now stretch 16-20 weeks as aerospace and battery sector demand competes for limited Japanese and Austrian mill capacity. Finished blade supply concentrates in Germany, Japan, and China, with Solingen and Seki anchoring premium forged output and Yangtze River Delta mills dominating stamped volume. Raw material sourcing draws from Swedish ore deposits, Austrian powder metallurgy specialists, and Chinese cold-rolling facilities. Single-source vulnerability in Gifu Prefecture's automated cladding lines threatens mid-tier Damascus supply continuity. Distribution runs through direct-to-registry platforms, traditional cutlery retail, and institutional procurement channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-neutral forging mandates under the EU Green Deal are disrupting established supplier qualification pathways, compressing the window for pre-certification advantage before enforcement hardens.
For Market Incumbents: Consolidate master forger apprenticeship pipelines in Solingen and Seki to defend authentic hand-forged scarcity against automated cladding encroachment. Secure backward integration into low-nickel stainless supply chains ahead of REACH Annex XVII threshold tightening. Pre-certify hydrogen-fired heat treatment capacity to capture EU Green Deal supplier qualification preference. For New Entrants and Emerging Players: Magnetic storage system integration represents a service-layer gap where heritage incumbents under-serve urban apartment dwellers constrained by block-based merchandising. Target direct-to-registry channels with ten-piece configurations featuring engraved personalization and virtual try-on. Pursue carbon-neutral forging partnerships with Thiers boutiques to bypass Solingen artisan bottlenecks. For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors early-compliant forging assets with pre-certified low-leaching alloy supply chains. Long-term viability centers on carbon-neutral production capacity and direct-to-consumer channel control rather than traditional retail footprint. Monitor EU Green Deal enforcement timelines as the signal to watch for supplier qualification arbitrage windows closing.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Neutral Forging Pre-Certification | Hydrogen-fired heat treatment investment secures EU Green Deal supplier qualification ahead of enforcement. |
| Direct-to-Registry Channel Expansion | Bridal platform partnerships bypass traditional retail markup structures in coastal urban markets. |
| Low-Nickel Alloy Backward Integration | Captive 18/0 stainless supply insulates against REACH Annex XVII border rejection risk. |
| Automated Damascus Cladding Scale-Up | Seki-derived pattern-welding automation compresses production costs for mid-tier accessibility. |
| Magnetic Storage System Attachment | Wall-mounted blade blocks with integrated edge guards capture kitchen renovation vertical spend. |
Research Methodology
Operator-level perspectives from master forgers, culinary school procurement directors, cutlery retail buyers, and registry platform curators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC filings of listed manufacturers, METI JIS standard documentation, and ECHA REACH compliance registries. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Sensitivity analysis tested volume and value projections across the analysis window against alloy price volatility scenarios and regulatory enforcement timing variations. Segmentation dimensions modeled include blade geometry category, metallurgical grade tier, set configuration size, end-use certification pathway, and regional production hub. CAGRs derived from installed capacity trajectories, replacement cycle compression rates, and channel shift velocity. Forecast inputs incorporated culinary school enrollment trends and gifting platform transaction data.
Underlying assumptions cover REACH compliance timeline adherence, powder metallurgy capacity expansion schedules, and carbon-neutral forging technology maturation, with deviation risk concentrated in regulatory enforcement acceleration and raw material supply disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Barbeque Grill Market
Household Items
Air Humidifier Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
Toilet Paper Market
Household Items
Lunch Box Market
Household Items
US Digital Showers Market
Household Items
Insulated Drinkware Market
Household Items
Compressed Tablet Towel Market
Household Items
Electric Brooms Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
Dryer Sheets Market
Household Items
Basin, Bowl, and Cup Market
Household Items
China Cookware Market
Household Items
Electric Clothes Drying Hanger Market
Household Items
Middle East and Africa Air Purifier Market
Household Items
Asia-Pacific Hand Dryer Market