
 US Digital Showers Market | 2026-2036
US Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
US Digital Showers Market Insights
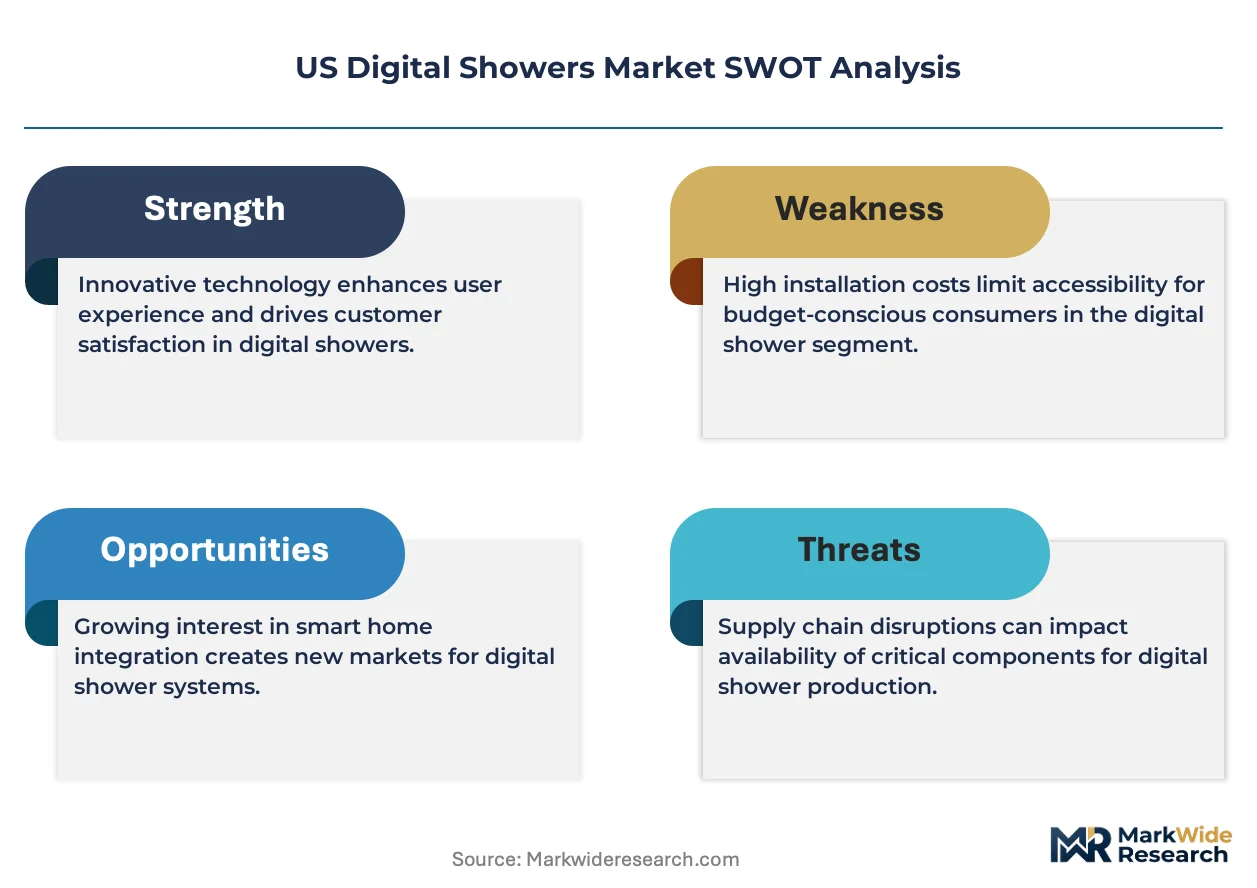
EPA WaterSense certification is bifurcating the US Digital Showers Market into qualified and non-qualified product tiers. Kohler Co. leverages its in-house valve manufacturing to control component quality from foundry to final assembly. Moen Incorporated anchors its position through exclusive big-box retail partnerships that limit competitor shelf access. Delta Faucet specializes in contractor-grade digital systems that dominate new construction specifications across the Southeast.
US digital showers integrate thermostatic mixing valves, Wi-Fi or Bluetooth connectivity, and touchscreen or voice-activated interfaces to deliver precise temperature and flow control for residential and commercial bathing applications. Smart showerheads and digital control panels capture the majority of current revenue as consumers prioritize visible technology upgrades over hidden infrastructure. The hospitality segment within end users is expanding fastest as boutique hotels deploy wireless sensors and temperature controllers to differentiate guest experiences and reduce water liability.
EPA WaterSense standards, DOE energy efficiency regulations, and state-level plumbing codes in California and Texas shape product design thresholds and installation compliance costs. The Federal Communications Commission oversees wireless sensor radio certifications that gate market entry for connected shower systems. Stakeholders must monitor evolving state water restrictions and building electrification mandates that will determine which digital shower architectures qualify for new construction permits.
Market Dynamics
EPA WaterSense certification is bifurcating the US Digital Showers Market into qualified and non-qualified product tiers, forcing manufacturers to redesign valve architectures and recertify entire product lines or surrender access to federally incentivized procurement channels.
Growth Catalysts
- Building electrification mandates:California and New York codes now require electric-ready rough-in during new construction, embedding digital valve infrastructure before walls close.
- Hospitality guest experience differentiation:Boutique hotels in Miami and Austin deploy wireless temperature presets and usage analytics to reduce water liability and drive review scores.
- Wi-Fi mesh penetration:Residential builders in Sun Belt states now spec connected bathroom packages as standard, normalizing app-controlled shower systems in entry-level housing.
Market Restraints
- Brass alloy cost volatility:Foundry-grade copper-zinc ingots fluctuate with commodity markets, compressing margin on thermostatic valve cores.
- Licensed plumber dependency:Digital shower installation requires EPA WaterSense-certified technicians, creating bottleneck capacity in rural Texas and Arizona markets.
- Smart speaker substitution:Voice-activated shower interfaces compete with Alexa and Google Home routines that replicate temperature control without dedicated hardware.
Strategic Opportunities
- Water-stressed municipalities:Las Vegas and Phoenix offer rebate programs for EPA WaterSense fixtures, creating pull-through demand for qualified digital systems.
- Retrofit channel expansion:Big-box retailers now stock contractor-grade digital panels for bathroom renovation projects, bypassing new construction cycles.
- Bluetooth Low Energy convergence:Integration with Matter protocol enables cross-device automation, positioning digital showers as nodes in whole-home water management.
Industry Challenges
- FCC Part 15 certification timelines:Radio frequency testing for wireless sensor modules delays product launches by four to six months.
- Legacy plumbing interoperability:Digital valves must interface with galvanized pipe in older housing stock, requiring adapter SKUs that complicate inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Digital Showers Market |
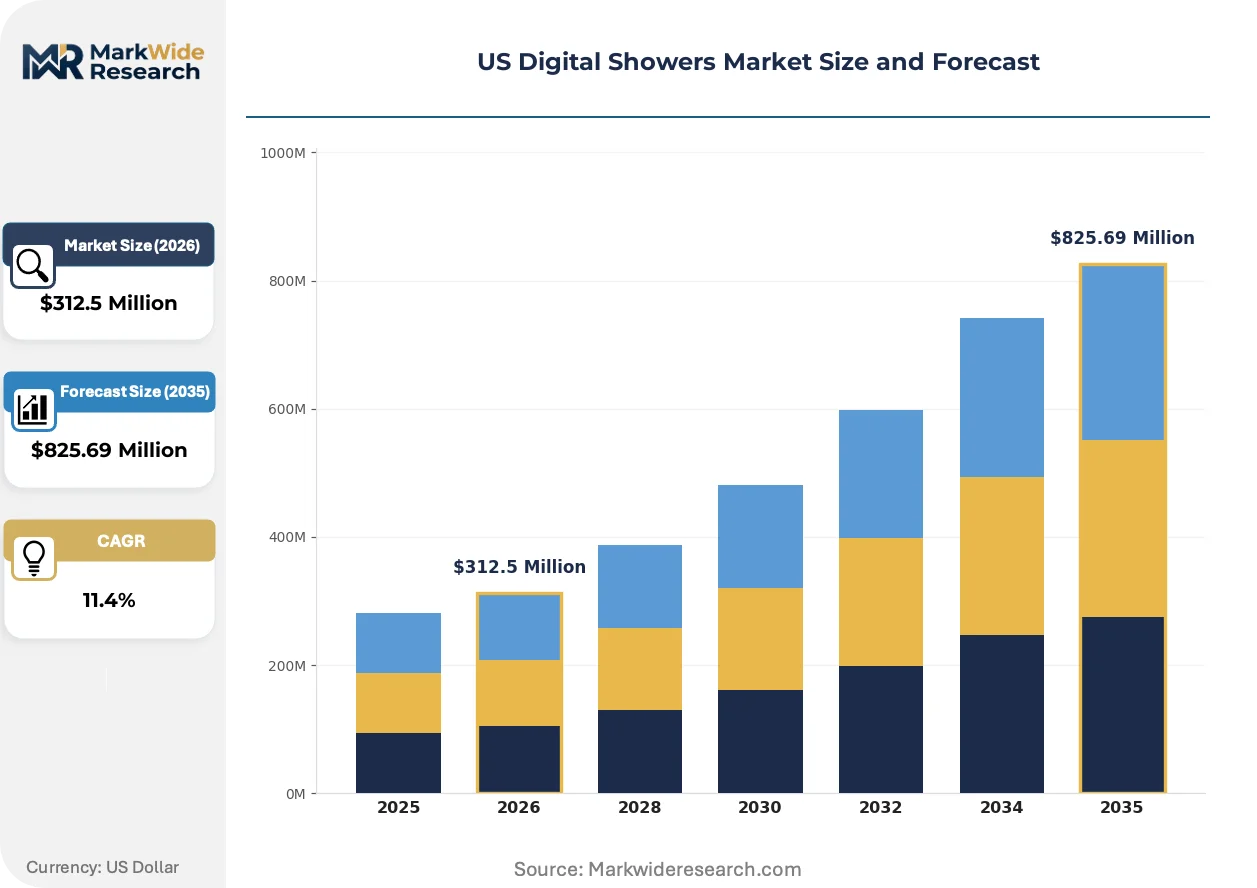
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Showerheads, Digital Control Panels, Wireless Sensors, Temperature Controllers Installation Type: Retrofit, New Construction, Modular, Integrated Systems End User: Residential, Commercial, Hospitality, Spa Facilities Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Kohler Co., Moen Incorporated, LIXIL Corporation, TOTO LTD, Roca Sanitario SA, Aqualisa, Delta Faucet, American Standard, ThermaSol, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Digital Showers Market Trends and Innovations
Connectivity architectures are splintering the US Digital Showers Market into proprietary ecosystem camps, with manufacturers betting on incompatible wireless protocols that lock installers and homeowners into single-brand bathroom suites.
Voice-activated control modules are fragmenting competitive positioning across price tiers. These hands-free interfaces enable temperature adjustment mid-shower without wet touchscreen contact. Hospitality operators in Nashville and Charleston are specifying voice-first panels for accessibility compliance and guest convenience. The technology is fragmenting procurement decisions, forcing architects to choose between Alexa-native, Google-native, and proprietary voice stacks before specifying rough-in.
DOE energy efficiency regulations now mandate maximum standby power draw for connected fixtures, compelling firmware redesigns that extend battery life on wireless sensors. Manufacturers must submit updated test data to certification bodies or risk delisting from federal procurement schedules. The commercial specification segment is responding fastest, with institutional buyers in Texas and Florida requiring compliant documentation at bid stage.
Direct-to-contractor digital ordering is compressing traditional distribution layers. Builders in Atlanta and Charlotte now configure shower systems through manufacturer portals that bypass regional plumbing wholesalers. This channel shift concentrates purchasing power with national production homebuilders while squeezing margin for independent distributors serving custom residential markets.
US Digital Showers Market Segmentation
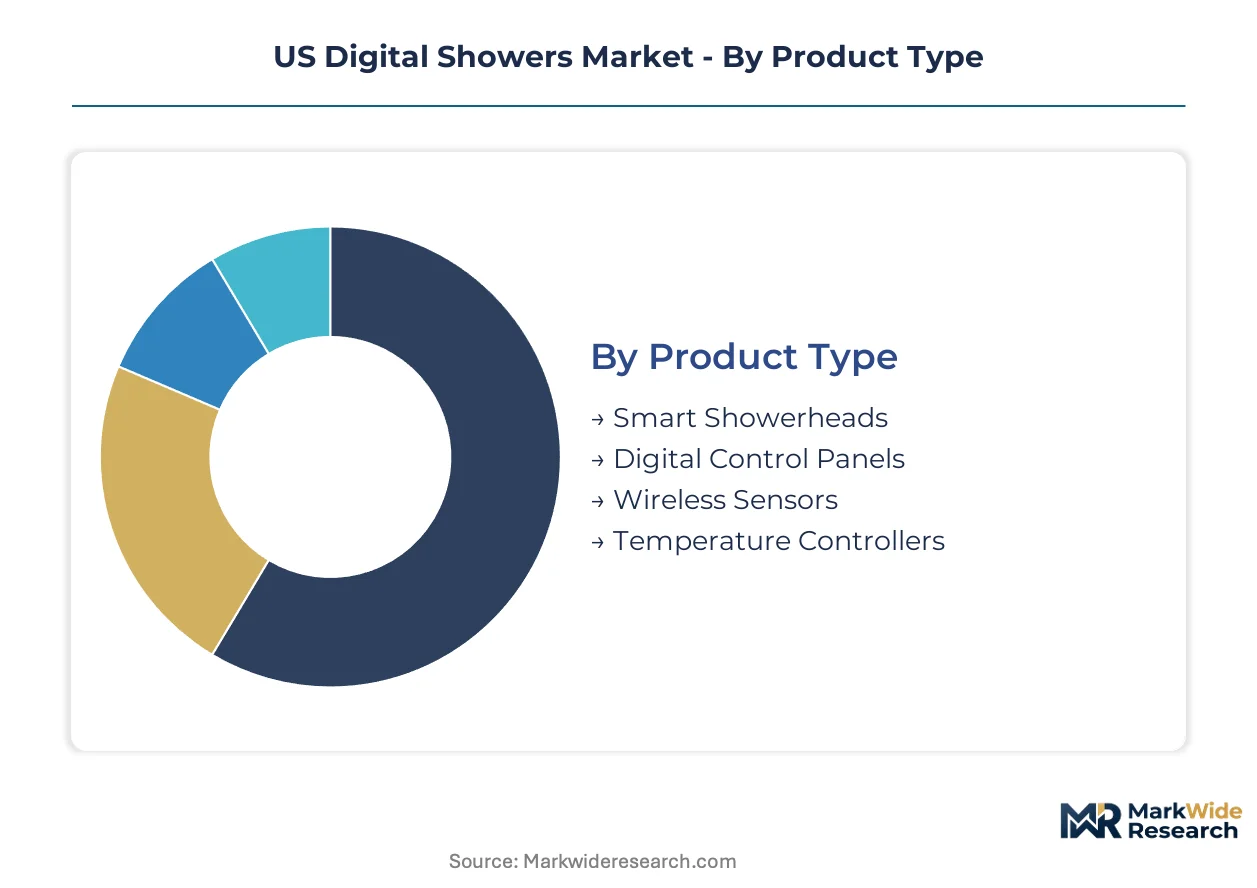
Digital shower segmentation reveals where technology investments concentrate and where legacy hardware retains defensive moats. Substitute threats from smart home ecosystems reshape which product categories warrant premium positioning versus commodity defense.
Product Type:
Smart speaker ecosystems and voice assistants exert substitution pressure unevenly across hardware categories, with visible interface products facing greater displacement risk than embedded infrastructure.
- Smart Showerheads:These Wi-Fi or Bluetooth-enabled fixtures embed thermostatic mixing and flow regulation directly into the showerhead housing. Demand clusters in Sun Belt states where new construction integrates connected bathroom packages as standard features.
- Digital Control Panels:Wall-mounted touchscreen or voice-activated interfaces govern temperature, flow duration, and preset profiles through centralized valve architectures. Hospitality operators in Miami and Austin specify these for guest experience differentiation and water liability reduction.
- Wireless Sensors:Battery-powered modules detect occupancy, temperature, and flow rates for automated activation and usage analytics.
- Temperature Controllers:In-line thermostatic valves maintain precise output temperatures regardless of inlet pressure fluctuations.
Smart Showerheads anchor the volume base while Digital Control Panels gain share at the steepest rate.
Installation Type:
Cost tier stratification separates specification-grade integrated systems from accessible retrofit solutions, with margin structures diverging sharply across installation complexity levels.
- New Construction:Electric-ready rough-in mandates in California and New York embed digital valve infrastructure during framing, locking in specifications before walls close. This segment captures the steepest expansion trajectory as building codes accelerate connected bathroom adoption.
- Retrofit:Contractor-grade digital panels stocked at big-box retailers enable bathroom renovation projects without full plumbing replacement. Demand concentrates in water-stressed municipalities where Las Vegas and Phoenix rebate programs pull through EPA WaterSense-qualified systems.
- Modular:Component-based systems allow incremental upgrades from basic thermostatic to fully connected configurations.
- Integrated Systems:Factory-configured shower suites bundle valves, controls, and fixtures under single-brand ecosystems.
New Construction commands premium pricing while Retrofit expands addressable market reach most aggressively.
End User:
Application maturity varies dramatically, with commercial specifications responding fastest to regulatory compliance pressures while residential adoption normalizes through builder channel incentives.
- Hospitality:Boutique hotels in Nashville and Charleston deploy wireless temperature presets and usage analytics to drive review scores and reduce water liability exposure. This segment climbs the fastest as institutional buyers in Texas and Florida require compliant documentation at bid stage.
- Residential:Homeowners in California and Florida upgrade bathrooms with app-controlled temperature systems, prioritizing visible technology over hidden infrastructure. Volume concentrates in Sun Belt states where Wi-Fi mesh penetration normalizes connected bathroom packages.
- Commercial:Institutional facilities specify DOE-compliant fixtures with mandated standby power limits.
- Spa Facilities:Wellness centers deploy precision temperature control for hydrotherapy and contrast bathing protocols.
Residential anchors installed base volume while Hospitality expands most quickly through experience-driven procurement.
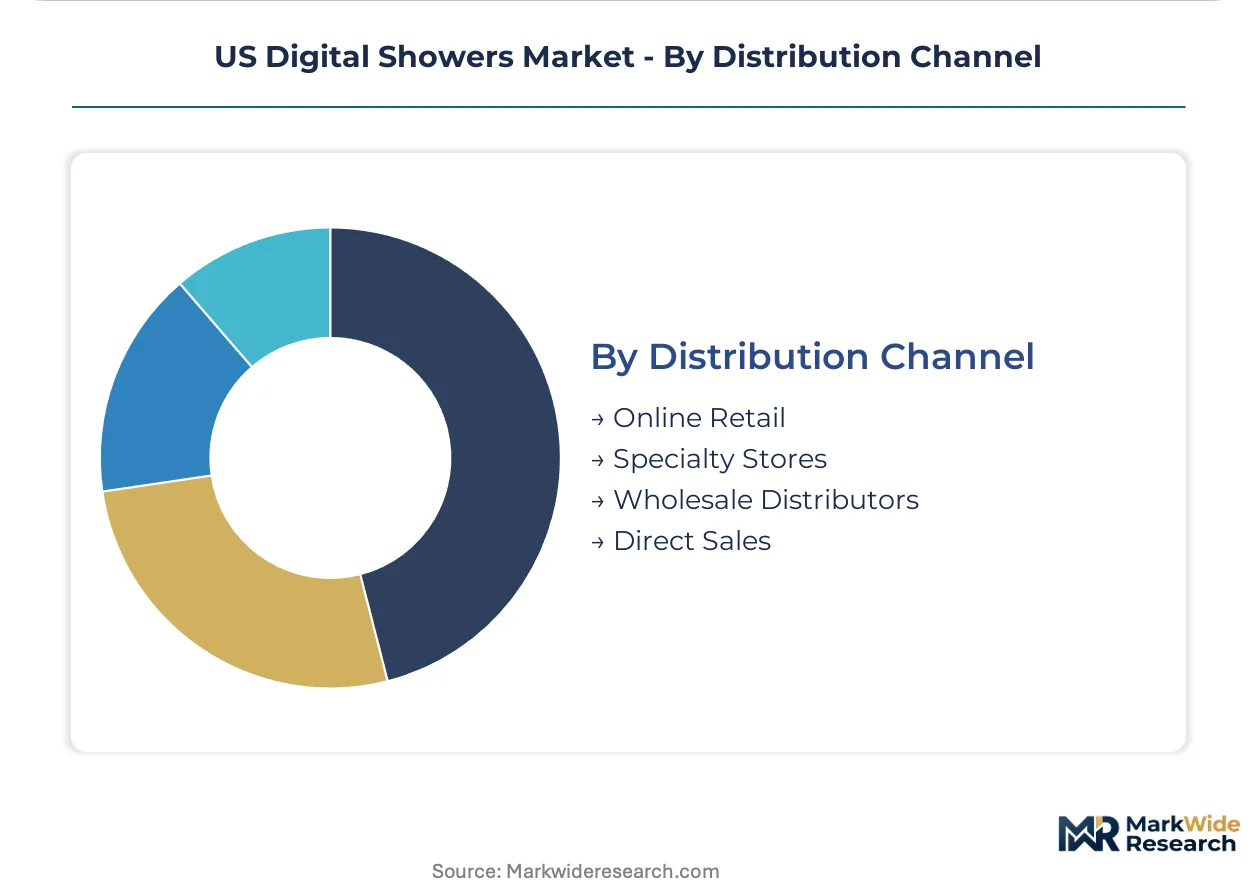
Distribution Channel:
Customer type concentration shapes channel power, with national production homebuilders compressing traditional wholesale layers through direct manufacturer relationships.
- Direct Sales:Manufacturer portals enable builders in Atlanta and Charlotte to configure shower systems without regional plumbing wholesalers. This channel concentrates purchasing power with national production homebuilders while squeezing independent distributor margins.
- Online Retail:E-commerce platforms capture consumer-driven replacement demand and research-intensive specification journeys. Growth accelerates where EPA WaterSense rebate programs drive self-directed procurement.
- Specialty Stores:Showroom-based retailers serve custom residential markets with high-touch consultation and design integration.
- Wholesale Distributors:Regional plumbing supply houses retain relevance in rural Texas and Arizona markets where licensed plumber dependency creates service-layer stickiness.
Wholesale Distributors retain infrastructure dominance while Direct Sales gains share fastest through builder channel consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA WaterSense rebate programs and building electrification mandates are redrawing geographic demand patterns across the United States. State-level plumbing codes and water stress severity now determine where digital shower adoption accelerates fastest.
California
Building electrification mandates in California now require electric-ready rough-in during new construction, embedding digital valve infrastructure before walls close. Title 24 energy codes and CALGreen standards compel builders to spec connected bathroom packages as baseline features. Los Angeles and San Francisco metro areas concentrate demand as homeowners upgrade bathrooms with app-controlled temperature systems.
Texas
Texas anchors volume expansion through Sun Belt construction growth and hospitality investment in Dallas-Fort Worth and Austin. Municipal water restrictions in Houston and San Antonio create pull-through demand for EPA WaterSense-qualified fixtures. Licensed plumber dependency creates installation bottlenecks in rural markets, compressing retrofit penetration outside major metros.
Florida
Florida's humidity-driven replacement cycles and coastal new construction normalize digital shower specifications in Miami and Orlando. The state's plumbing code adopts federal WaterSense standards without augmentation, streamlining compliance for manufacturers. Boutique hotels in Miami Beach deploy wireless temperature presets to differentiate guest experiences and reduce water liability exposure.
New York
New York's building electrification mandates mirror California's electric-ready rough-in requirements, embedding digital infrastructure during framing in New York City and downstate counties. NYSERDA incentive programs accelerate commercial specification of DOE-compliant fixtures with mandated standby power limits. Upstate markets lag due to older housing stock and galvanized pipe retrofit complexity.
Arizona
Arizona's water-stressed municipalities offer the most aggressive rebate programs for EPA WaterSense fixtures, creating pull-through demand in Phoenix and Tucson. Municipal water departments in Scottsdale and Tempe bundle digital shower incentives with broader conservation campaigns. New construction in suburban Maricopa County integrates connected bathroom packages as standard features.
US Digital Showers Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and distribution channels. The market structure concentrates around three to five dominant players with captive manufacturing and exclusive retail relationships, while mid-tier specialists compete on retrofit accessibility and voice protocol integration. Strategic archetypes include in-house valve manufacturers controlling quality from foundry to assembly, big-box exclusive partners limiting competitor shelf access, and contractor-grade specialists dominating new construction specifications. Competitive moves center on direct-to-contractor digital ordering portals and exclusive voice assistant partnerships that lock homeowners into single-brand bathroom suites.
Among the dominant tier, Kohler Co., Moen Incorporated, and Delta Faucet occupy positions that exemplify distinct competitive archetypes. Kohler Co. represents the vertically integrated manufacturer with captive valve production. Moen Incorporated sits within the retail-exclusive partnership model. Delta Faucet anchors the contractor-grade specification channel. These three companies collectively illustrate how certification control, distribution access, and construction channel penetration segment competitive positioning in the US market.
| Leading Market Players |
|---|
| Kohler Co. |
| Moen Incorporated |
| LIXIL Corporation |
| TOTO LTD |
| Roca Sanitario SA |
| Aqualisa |
| Delta Faucet |
| American Standard |
| ThermaSol |
| Others |
Pricing and Supply Chain Analysis
EPA WaterSense certification gates both supply qualification and price differentiation simultaneously, bifurcating the US Digital Showers Market into qualified and non-qualified tiers that command distinct procurement channels and margin structures. Manufacturers must recertify entire product lines or surrender access to federally incentivized markets, embedding compliance costs into pricing architecture before valves reach rough-in.
Pricing Analysis
Certification level (EPA WaterSense-qualified versus non-qualified) creates the primary spread between specification-grade and accessible retrofit tiers. Three-tier pricing structure across premium, standard, and economy levels reflects valve architecture complexity, voice protocol integration, and after-sales service bundling. Cost compression in contractor-grade segments is intensifying because brass alloy volatility squeezes thermostatic core margins. Residential builders in Sun Belt states exhibit highest price sensitivity, while hospitality operators in Miami and Austin prioritize guest experience differentiation over unit economics.
Supply Chain Analysis
Inventory lead times for FCC Part 15-certified wireless modules extend product launches by four to six months, compressing planning horizons for seasonal construction cycles. Foundry-grade brass ingot supply concentrates in domestic Midwest operations and select Mexican maquiladora facilities, drawing from copper-zinc commodity markets tethered to construction demand swings. Single-source vulnerability sits with proprietary valve cartridge architectures that lock installers into single-brand ecosystems. Distribution runs through direct-to-contractor portals that bypass regional plumbing wholesalers in Atlanta and Charlotte, while rural Texas and Arizona markets retain wholesale distributor infrastructure due to licensed plumber dependency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in retrofit channels where water-stressed municipalities create rebate-driven niches, and voice protocol divergence prevents ecosystem consolidation. Building electrification mandates and hospitality guest experience differentiation generate parallel demand vectors that resist single-vendor capture.
For Market Incumbents: Shield specification-grade positioning by deepening captive valve manufacturing and exclusive big-box retail partnerships that limit competitor shelf access. Counter smart speaker substitution threats through proprietary voice stack development that locks homeowners into single-brand bathroom suites. Prioritize EPA WaterSense recertification investment to maintain access to federally incentivized procurement channels.
For New Entrants and Emerging Players: EPA WaterSense fast-track certification enables retrofit channel penetration in Las Vegas and Phoenix where municipal rebate programs pull through qualified systems. Target contractor-grade digital panels stocked at big-box retailers for bathroom renovation projects, bypassing new construction specification barriers. Pursue Bluetooth Low Energy Matter protocol integration as a cross-device automation wedge against proprietary ecosystem camps.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across in-house valve manufacturing as foundry-grade brass volatility demands captive supply control. Long-term viability favors vertically integrated manufacturers with backward integration into thermostatic core production and direct-to-contractor digital ordering infrastructure. Monitor FCC Part 15 certification timeline compression as an inflection indicator for wireless-enabled product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EPA WaterSense Certification Fast-Track | Unlocks access to Las Vegas and Phoenix municipal rebate programs driving qualified system adoption. |
| Direct-to-Contractor Portal Development | Concentrates purchasing power with national production homebuilders in Atlanta and Charlotte markets. |
| Proprietary Voice Stack Integration | Creates ecosystem lock-in against Alexa and Google Home routine substitution in hospitality specifications. |
| Brass Foundry Backward Integration | Insulates margin from copper-zinc commodity volatility compressing thermostatic valve core profitability. |
| Matter Protocol Certification | Positions digital showers as nodes in whole-home water management systems for cross-device automation. |
Research Methodology
A standing panel of plumbing contractor operations managers, big-box retail category buyers, hospitality facilities directors, EPA WaterSense certification specialists, and residential production homebuilder procurement leads provided ongoing calibration across primary fieldwork. Secondary validation drew from DOE energy efficiency filings, FCC Part 15 equipment authorization databases, state plumbing code repositories in California and Texas, and municipal water department rebate program disclosures. Bottom-up unit shipment modeling triangulated against top-down construction permit flow analysis.
Consistency checks validated volume and value outputs against external benchmarks including new construction housing starts, bathroom renovation spending indices, and hospitality capital expenditure surveys across the projection horizon. Segmentation dimensions modeled encompassed product type, installation complexity, end-user application, and distribution channel structure alongside voice protocol ecosystem affiliation as an industry-specific dimension. CAGRs derived from regression analysis of historical replacement cycle compression and regulatory mandate acceleration, with inputs including Wi-Fi mesh household penetration curves and building electrification code adoption timelines.
Decision-makers should treat outputs as directional under assumptions of sustained brass alloy cost volatility and stable FCC certification timelines; material deviation in commodity markets or regulatory enforcement intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Germany Digital Showers Market
Household Items
Hangers Market
Household Items
Umbrella Market
Household Items
Portable Air Humidifier and Dehumidifier Market
Household Items
Disposable Napkins Market
Household Items
Air Freshener Market
Household Items
Smart Air Purifier Market
Household Items
Drain Cleaners Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Residential Water Purifier Market
Household Items
Compressed Tablet Towel Market
Household Items
Qatar Gas Hobs Market
Household Items
Air Care Market
Household Items
Electric Tealight Candles Market
Household Items
Ultrasonic Diffusers Market
Household Items
North America Car Air Freshener Market