
 Global on-Premise-Laundry (OPL) Market | 2026-2036
Global on-Premise-Laundry (OPL) Market Size, Share, and Industry Trends Forecast 2026-2036
Global on-Premise-Laundry (OPL) Market Outlook
The EU Ecodesign Directive is expanding efficiency requirements for commercial laundry equipment across Europe, compelling manufacturers to redesign thermal systems and water loops. Alliance Laundry Systems leverages its vertically integrated manufacturing footprint to meet these standards at scale. Electrolux Professional anchors its competitive position through R&D intensity in heat-pump dryer technology. Huebsch specializes in durable wash systems engineered for high-cycle hospital and hotel environments.
On-premise laundry denotes commercial-grade textile cleaning operations conducted within the same facility that generates soiled linens, utilizing industrial washing machines with drum capacities from 20 to 450 pounds, extractors reaching 400 G-force, and dryers with programmable moisture sensing to process thousands of pounds daily. Washing machines dominate product-type revenue due to replacement cycles in aging North American and European installed bases, while water recycling technology represents the fastest-growing segment as drought-prone regions mandate consumption limits. Hotels and hospitals constitute the deepest end-user margin pools because these sectors prioritize uptime guarantees and multi-year service contracts over upfront equipment cost.
The EPA Energy Star program in the United States and China's GB standards for commercial appliance efficiency create dual compliance tracks that shape product development roadmaps and factory certification requirements. REACH chemical restrictions in Europe further constrain detergent formulation choices, pushing equipment makers to engineer compatibility with enzyme-based and low-temperature chemistries. Stakeholders must monitor how fragmented national water-usage regulations evolve and whether efficiency mandates consolidate into transnational standards that reshape competitive access.
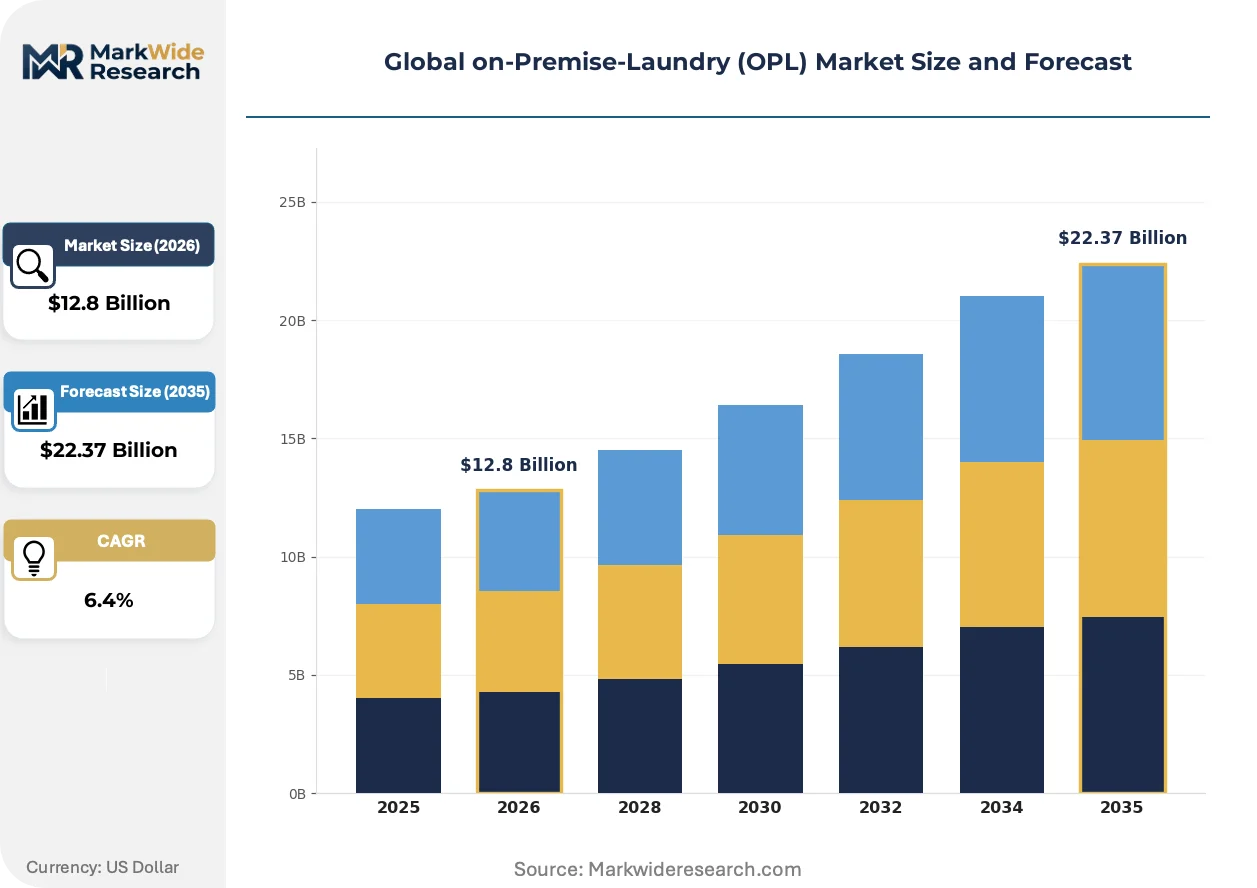
Market Dynamics
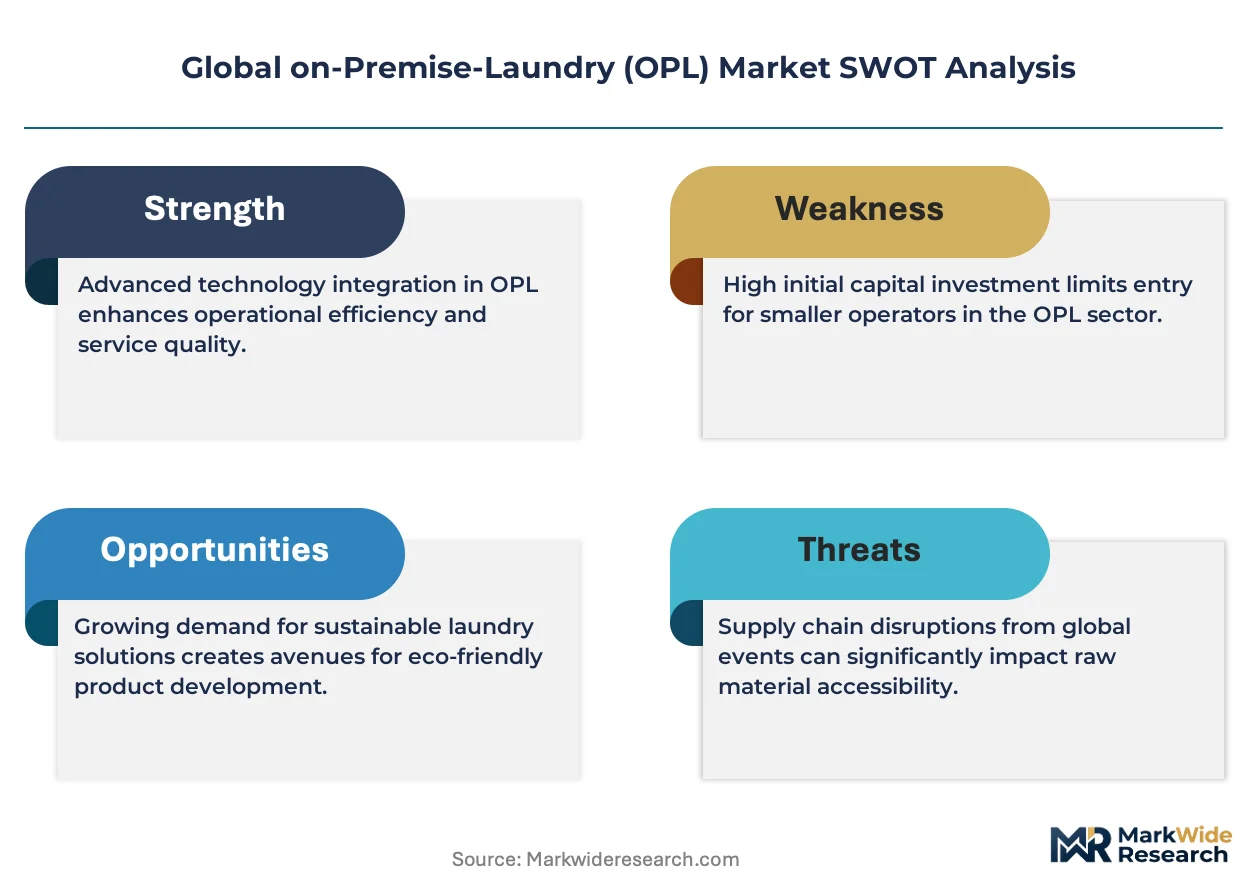
The EU Ecodesign Directive is compressing replacement cycles across Europe's installed base of aging commercial washers and dryers, forcing capital deployment toward heat-pump thermal systems and closed-loop water architectures that meet tightening efficiency thresholds.
Growth Catalysts
- EPA Energy Star compliance mandates:US federal procurement rules now require certified equipment for federally funded hospital renovations, redirecting capital toward programmable moisture-sensing dryers and high-G-force extractors.
- Hotel vertical consolidation:Global hospitality chains are standardizing in-house laundry specifications across property portfolios to reduce per-pound processing costs and eliminate third-party linen service dependency.
- Heat-pump dryer diffusion:Advances in refrigerant-based thermal recovery are cutting natural gas consumption by half in large-capacity hospital installations, accelerating retrofit demand in Germany and China.
Market Restraints
- Stainless steel input volatility:Drum and chassis fabrication depends on nickel-alloy sheet pricing, with mill delivery timelines extending to 16 weeks during commodity squeeze periods.
- REACH detergent formulation constraints:European chemical restrictions limit surfactant chemistry compatibility, forcing equipment redesigns to accommodate low-temperature enzyme washing protocols.
- Skilled technician scarcity:Installation and maintenance of 400 G-force extractors and heat-pump systems requires refrigeration and electrical certifications that outpace vocational training pipeline output.
Strategic Opportunities
- India hospital infrastructure buildout:Government health insurance expansion is funding 150-bed-plus facilities with captive laundry capacity, creating first-mover positioning for OPL equipment suppliers.
- Water recycling technology convergence:Integration of membrane filtration with ozone disinfection enables zero-liquid-discharge operations in drought-prone US Southwest municipalities facing consumption caps.
- China GB standard alignment:National efficiency labeling revisions are disqualifying legacy thermal dryer designs, opening replacement windows for heat-pump and gas-fired hybrid systems.
Industry Challenges
- Legacy building electrical infrastructure:Pre-1990 hospital and hotel facilities lack 480V three-phase service capacity for modern high-G-force extractors, requiring costly electrical room upgrades.
- Cross-border certification fragmentation:Separate UL, CE, and CCC approval tracks for the same equipment platform extend product launch timelines and inflate testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global on-Premise-Laundry (OPL) Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Ironers, Finishing Equipment End User: Hotels, Hospitals, Restaurants, Gyms Technology: Steam, Electric, Hybrid, Water Recycling Size: Small, Medium, Large, Industrial |
| Companies Covered | Alliance Laundry Systems, Electrolux Professional, Speed Queen, UniMac Laundry Equipment, Dexter Laundry, Ecolab, Huebsch, Laundrylux, Continental Girbau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global on-Premise-Laundry (OPL) Market Strategic Shifts
Electrification of thermal systems is displacing fossil-fuel dependency across commercial laundry operations, with regulatory pressure and operating cost arithmetic converging to accelerate capital reallocation toward heat-pump and induction-based drying architectures.
Heat-pump dryer technology is electrifying the thermal energy input for large-capacity commercial drying, replacing natural gas combustion with refrigerant-cycle heat recovery. Hospital systems in Germany and the Netherlands are specifying these systems for new construction, with procurement committees prioritizing Scope 1 emissions reduction targets over first-cost metrics. This shift is compressing demand for conventional gas-fired dryer platforms and rewiring supplier R&D roadmaps toward compressor and heat-exchanger optimization.
REACH chemical restrictions are forcing equipment-water-chemistry co-design across European manufacturing. The ECHA framework limits phosphonate-based surfactants and high-alkaline builders, compelling washer programmers to develop low-temperature enzyme cycles that maintain soil removal at 105°F rather than 160°F. OEM engineering teams are responding with extended tumble algorithms and precision chemical dosing pumps that compensate for reduced thermal energy input.
Service contract unbundling is fragmenting the traditional equipment-plus-maintenance bundle in North American hospital procurement. Materials management directors are separating capital acquisition from multi-year uptime guarantees, pitting specialized service contractors against manufacturer-captive service arms. This pattern is most pronounced in Texas and Florida health systems, where third-party technical labor pools compete aggressively on response-time SLAs.
Global on-Premise-Laundry (OPL) Market Segmentation
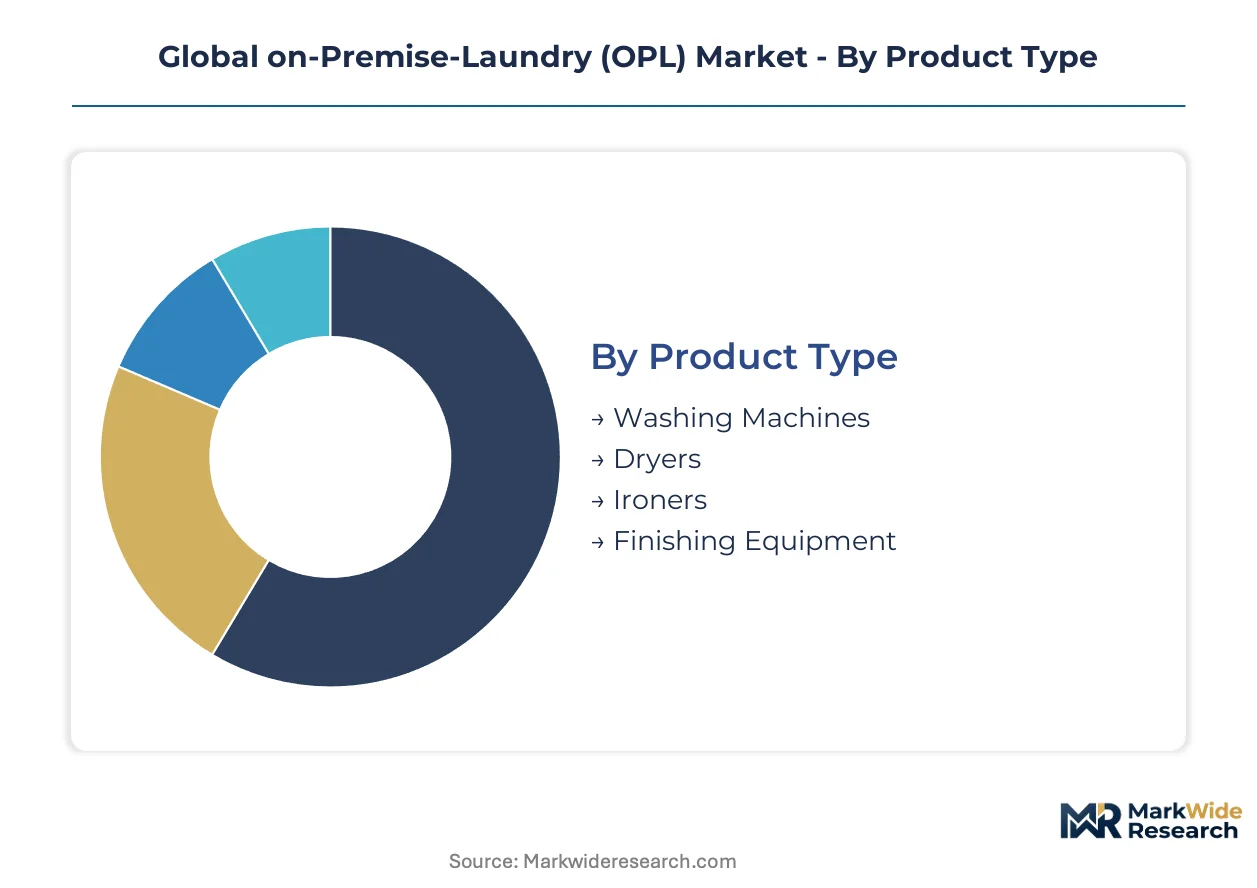
Segmentation in the on-premise laundry market reveals how capital deployment, regulatory compliance, and operational scale create distinct procurement patterns across equipment categories and user types.
Product Type:
Washing machines and dryers command the highest upfront capital outlays due to drum fabrication costs and thermal system complexity, while finishing equipment requires lower initial investment but higher integration engineering.
- Washing Machines:Industrial-grade units with 20 to 450-pound drum capacities and programmable extractors reaching 400 G-force dominate replacement demand in aging North American and European installed bases. Hotels in the United States prioritize these systems for uptime guarantees and multi-year service contracts.
- Dryers:Programmable moisture-sensing units with heat-pump or gas-fired thermal architectures are displacing conventional designs under EPA Energy Star and EU Ecodesign Directive pressure. German hospital procurement committees specify heat-pump configurations for Scope 1 emissions targets.
- Ironers:Heated roll and chest ironers handle flatwork finishing with steam or electric thermal input. These systems see concentrated demand in European hotel properties with high-volume linen throughput requirements.
- Finishing Equipment:Folding, pressing, and garment finishing systems complete the textile processing line. Chinese manufacturing clusters produce cost-optimized units for mid-scale hospital installations.
Washing machines absorb the bulk of installed capacity; water recycling technology is expanding most quickly.
End User:
Capital allocation intensity varies sharply across user categories, with hospitals and hotels deploying multi-million-dollar captive facilities while restaurants and gyms operate smaller-scale configurations.
- Hotels:Global hospitality chains standardize in-house laundry specifications across property portfolios to eliminate third-party linen service dependency. These operators prioritize programmable extractors and moisture-sensing dryers for per-pound cost control.
- Hospitals:Infection control protocols and 24/7 uptime requirements drive specification of ozone-compatible washers and heat-pump dryers. India's government health insurance expansion is funding 150-bed-plus facilities with captive laundry capacity.
- Restaurants:Table linen and uniform processing demands compact under-counter or small-footprint systems. These operators in drought-prone US Southwest municipalities face water consumption caps that constrain equipment selection.
- Gyms:Towel service operations utilize medium-capacity washers with rapid cycle times. Chinese fitness chains are adopting GB standard-compliant electric dryers as national efficiency labeling disqualifies legacy thermal designs.
Hospitals command the deepest margin pools for multi-year service contracts; hotels are standardizing specifications fastest across property portfolios.
Technology:
Thermal energy source selection determines both operating cost structure and regulatory compliance trajectory, with electrification mandates reshaping R&D roadmaps.
- Steam:Boiler-dependent thermal systems remain prevalent in legacy hospital infrastructure but face displacement where 480V three-phase electrical upgrades prove cost-prohibitive. German facilities with existing steam distribution maintain this architecture for flatwork ironers.
- Electric:Resistance-heating and induction-based dryers serve installations without natural gas infrastructure. These systems dominate in Chinese urban hospitals where pipeline constraints limit fossil fuel access.
- Hybrid:Gas-electric dual-fuel configurations provide operational flexibility for facilities with volatile utility pricing. Texas health systems specify these units to hedge against natural gas price spikes.
- Water Recycling:Membrane filtration and ozone disinfection integration enables zero-liquid-discharge operations. Drought-prone municipalities in the United States are mandating these systems for new commercial laundry permits.
Steam retains the largest legacy installed base; water recycling technology is gaining share fastest under regulatory pressure.
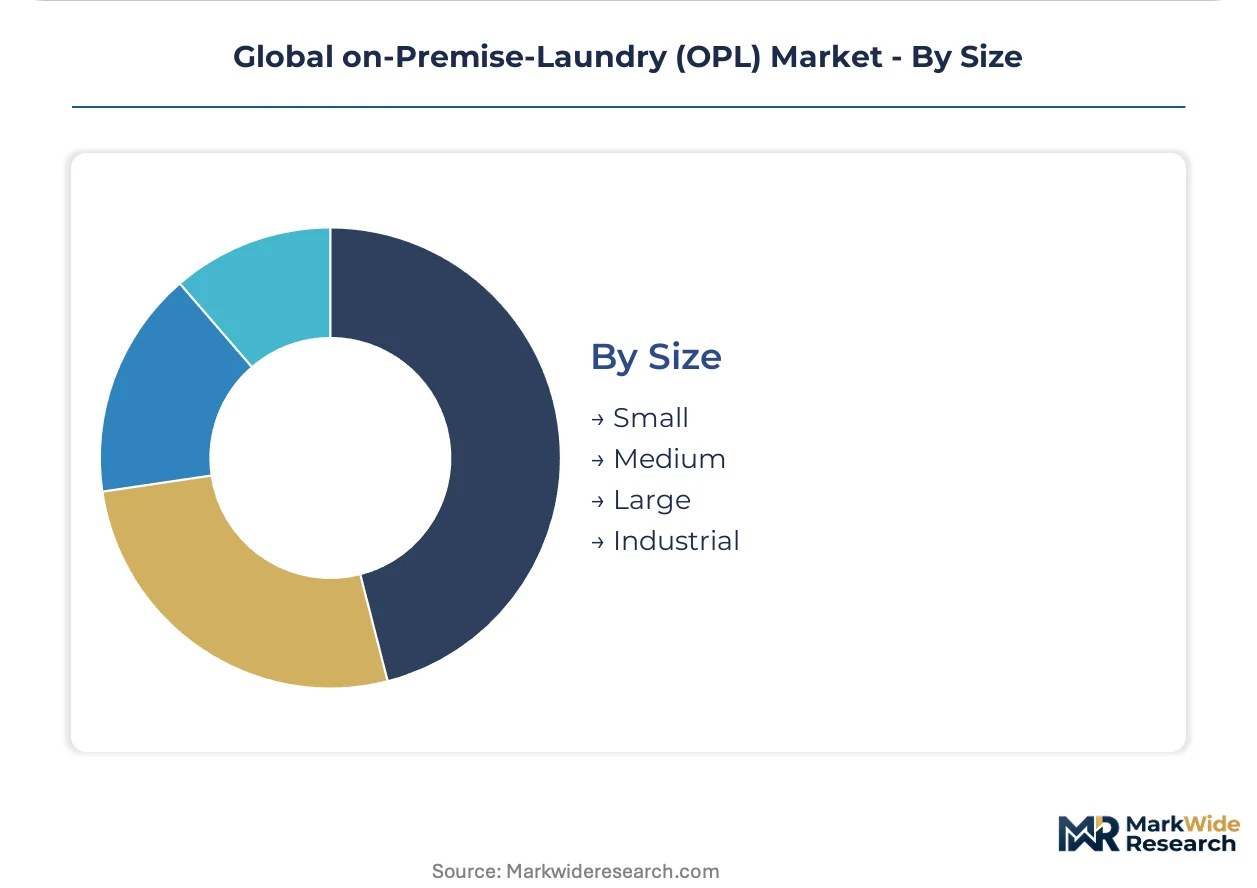
Size:
Equipment scale correlates directly with facility throughput requirements and building infrastructure constraints, creating distinct specification bands.
- Small:Under-50-pound capacity units serve boutique hotels and independent restaurants with limited linen volumes. These systems dominate replacement cycles in pre-1990 European buildings with restricted floor loading.
- Medium:50 to 200-pound drum configurations balance throughput with space constraints. Gyms and mid-scale hospital wards in China specify these units for towel and uniform processing.
- Large:200 to 450-pound washers and matching dryers process thousands of pounds daily. United States hotel chains deploy these systems in centralized laundry facilities serving multiple properties.
- Industrial:Continuous-batch and tunnel washing systems handle extreme throughput for major hospital networks. German university medical centers specify these configurations for centralized sterile supply integration.
Large-capacity equipment anchors revenue concentration; industrial-scale systems are penetrating fastest among consolidated hospital networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American OPL equipment manufacturing, with industrial laundries across the Great Lakes corridor driving replacement demand for high-G-force extractors and heat-pump dryers.
United States
Federally funded hospital renovations now mandate EPA Energy Star certified equipment, redirecting capital toward programmable moisture-sensing systems. The EPA procurement rules compress replacement cycles in aging infrastructure. Texas health systems deploy hybrid gas-electric dryers to hedge utility volatility, while Southwest municipalities enforce water recycling mandates for new commercial permits.
Germany
Hospital procurement committees prioritize Scope 1 emissions reduction through heat-pump dryer specifications for new construction. The EU Ecodesign Directive tightens efficiency thresholds for thermal systems and water loops. University medical centers in Baden-Württemberg specify continuous-batch tunnel washers for centralized sterile supply integration.
China
Government health insurance expansion funds 150-bed-plus facilities with captive laundry capacity, creating first-mover positioning for equipment suppliers. GB standards for commercial appliance efficiency disqualify legacy thermal dryer designs. Urban hospitals in the Yangtze River Delta specify electric dryers as pipeline constraints limit natural gas access.
India
Public hospital infrastructure buildout accelerates demand for industrial-grade washers with ozone disinfection compatibility. The country's national health insurance expansion channels capital toward infection control protocols. Maharashtra's government medical colleges deploy medium-capacity systems for ward linen processing.
Netherlands
Dutch hospital systems specify heat-pump configurations to meet national carbon reduction targets. REACH chemical restrictions constrain surfactant compatibility, forcing equipment redesigns for low-temperature enzyme cycles. Amsterdam medical centers integrate membrane filtration for zero-liquid-discharge operations.
Global on-Premise-Laundry (OPL) Market Competitive Environment
The competitive structure tilts toward vertically integrated manufacturers with captive component supply. Three tiers define the landscape: multinational equipment platforms with full product portfolios, regional specialists concentrating on specific capacity bands, and service-integrated operators bundling maintenance contracts. Consolidation pressure intensifies as efficiency mandates raise R&D thresholds. Strategic moves center on heat-pump technology licensing and backward integration into compressor manufacturing.
Within the multinational tier, Alliance Laundry Systems and Electrolux Professional exemplify scale-driven platform operators with integrated manufacturing footprints. Huebsch occupies a position among durability-focused specialists engineered for high-cycle hospital and hotel environments. These anchors represent divergent competitive vectors: full-line coverage versus application-specific engineering depth.
| Leading Market Players |
|---|
| Alliance Laundry Systems |
| Electrolux Professional |
| Speed Queen |
| UniMac Laundry Equipment |
| Dexter Laundry |
| Ecolab |
| Huebsch |
| Laundrylux |
| Continental Girbau |
| Others |
Value Chain & Pricing Dynamics
Performance-tier divergence between heat-pump thermal systems and conventional gas-fired platforms manifests in both capital expenditure bands and component sourcing geography. Premium configurations command price premiums tied to energy efficiency certification tiers while drawing compressor and heat-exchanger supply from specialized manufacturing clusters.
Pricing Analysis
Throughput-guarantee contracting anchors value-based pricing for hospital and hotel procurement committees. Three-tier pricing structure across premium, standard, and economy levels separates EPA Energy Star-certified heat-pump systems from baseline electric units and refurbished legacy installations. Cost compression in the standard tier is intensifying because stainless steel mill delivery timelines extend during commodity squeeze periods. Budget-constrained independent restaurants exhibit highest price sensitivity; consolidated US hospital networks prioritize uptime SLAs over first-cost metrics.
Supply Chain Analysis
Single-source vulnerability sits with nickel-alloy stainless steel sheet suppliers concentrated in Germany, China, and South Korea. Drum fabrication and chassis welding draw from these metallurgical inputs, while refrigeration compressors for heat-pump architectures rest on Japanese and German component specialists. Tariff exposure runs through cross-border steel trade flows. Distribution runs through manufacturer-direct sales for large hospital installations and specialized equipment distributors serving mid-scale hospitality properties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The on-premise laundry market occupies a technology-transition phase as heat-pump thermal architectures displace fossil-fuel combustion systems across European and North American installed bases.
For Market Incumbents: Anticipate margin compression from REACH-compliant detergent formulation constraints by engineering low-temperature enzyme cycle compatibility into next-generation washer programmers. Backward integration into compressor manufacturing secures supply continuity for heat-pump dryer platforms as demand concentrates in Germany and the Netherlands.
For New Entrants and Emerging Players: Capture first-mover positioning in India's government-funded hospital infrastructure buildout by specifying ozone-compatible washers for 150-bed-plus facilities. Service-contract unbundling in Texas and Florida health systems creates entry pathways for specialized technical labor pools competing on response-time SLAs.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated manufacturers given EU Ecodesign Directive efficiency thresholds that raise R&D barriers for component assemblers. Long-term viability favors platform operators with captive heat-pump technology licensing. The signal to watch is consolidation momentum among regional specialists lacking scale to meet transnational certification requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Licensing | Electrolux Professional and Alliance Laundry Systems monetize refrigerant-cycle IP across OEM partnerships. |
| Backward Integration into Compressor Manufacturing | Captive supply of heat-pump thermal components insulates margin from Japanese and German supplier bottlenecks. |
| Water Recycling System Integration | Membrane filtration with ozone disinfection meets Southwest US municipal consumption caps for new permits. |
| India Hospital Infrastructure Partnership | Government health insurance expansion channels capital toward infection-control-specified captive laundry capacity. |
| Service Contract Unbundling Response | Third-party technical labor pools compete against manufacturer-captive service arms on Texas and Florida SLAs. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with maintenance directors at hospital systems, procurement leads at hospitality chains, plant engineers at equipment manufacturing facilities, and aftermarket service heads validated demand patterns. EPA Energy Star certification databases, EU Ecodesign Directive compliance registries, China GB standards documentation, and stainless steel trade flow statistics provided secondary triangulation. Bottom-up equipment shipment analysis and top-down macroeconomic factor modeling converged on segment-level outputs.
Granularity-level modeling deployed product-type, end-user sector, thermal technology architecture, and equipment capacity band dimensions across the projection horizon. CAGRs derived from replacement cycle analysis in aging North American and European installed bases, regulatory mandate timelines, and hospital construction pipeline tracking. Heat-pump technology diffusion curves and water recycling mandate adoption rates informed scenario-weighted projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Ecodesign Directive enforcement stringency and stainless steel commodity volatility. Deviation in REACH chemical restriction scope or China GB standard revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Toilet Rim Blocks Market
Household Items
Stick Vacuum Cleaner Market
Household Items
Massage Pillow Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Disposable Napkins Market
Household Items
Fine Mist Sprayer Market
Household Items
Smart Air Purifier Market
Household Items
Sanitary Napkin Receptacles Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Dosage Spoon Market
Household Items
Smart Faucets Market
Household Items
Thermos Drinkware Market
Household Items
Drinkware Accessories Market
Household Items
Bladeless Neck Fan Market
Household Items
Washing Machine Cleaner Market
Household Items
Coffin and Cremation Urn Market